
 Hammer Unions Market | 2026-2036
Hammer Unions Market Size, Share, and Industry Trends Forecast 2026-2036
Hammer Unions Market Analytics
API 6A wellhead equipment specifications is expanding the engineering cost threshold for hammer union suppliers seeking upstream certification. NOV anchors its position through captive forging capacity and deep integration with offshore drilling contractors. FMC Technologies leverages decades of subsea system integration to sustain premium positioning in high-pressure applications. Kemper Valve and Fittings specializes in domestic U.S. manufacturing scale, competing aggressively on lead times for standard-pressure inventory.
Hammer unions are threaded or slip-on pressure-sealing connectors engineered from forged alloy steel with working pressure ratings spanning 1,000 to 20,000 psi, designed for rapid make-and-break operations in flowing media lines. Their primary commercial purpose centers on maintaining structural integrity of temporary flowline assemblies during drilling, completion, and production phases where conventional flanged connections prove impractical. High-pressure hammer unions command disproportionate margin pools relative to standard variants due to metallurgical complexity and narrower qualified supplier bases. Carbon steel dominates unit volume across the oil and gas industry end user segment, though sour-service applications are shifting specification mix toward alloy steel grades resistant to sulfide stress cracking.
API, ASTM A105/A182 material standards, and OSHA Process Safety Management requirements collectively govern hammer union design validation, material traceability, and field-use documentation in the United States. These frameworks elevate compliance costs for new entrants while creating sustained aftermarket demand for inspection, recertification, and replacement of in-service unions approaching fatigue life limits. Stakeholders must monitor evolving methane emission detection protocols and their downstream implications for connection integrity standards in fugitive-monitoring regimes.
Market Dynamics
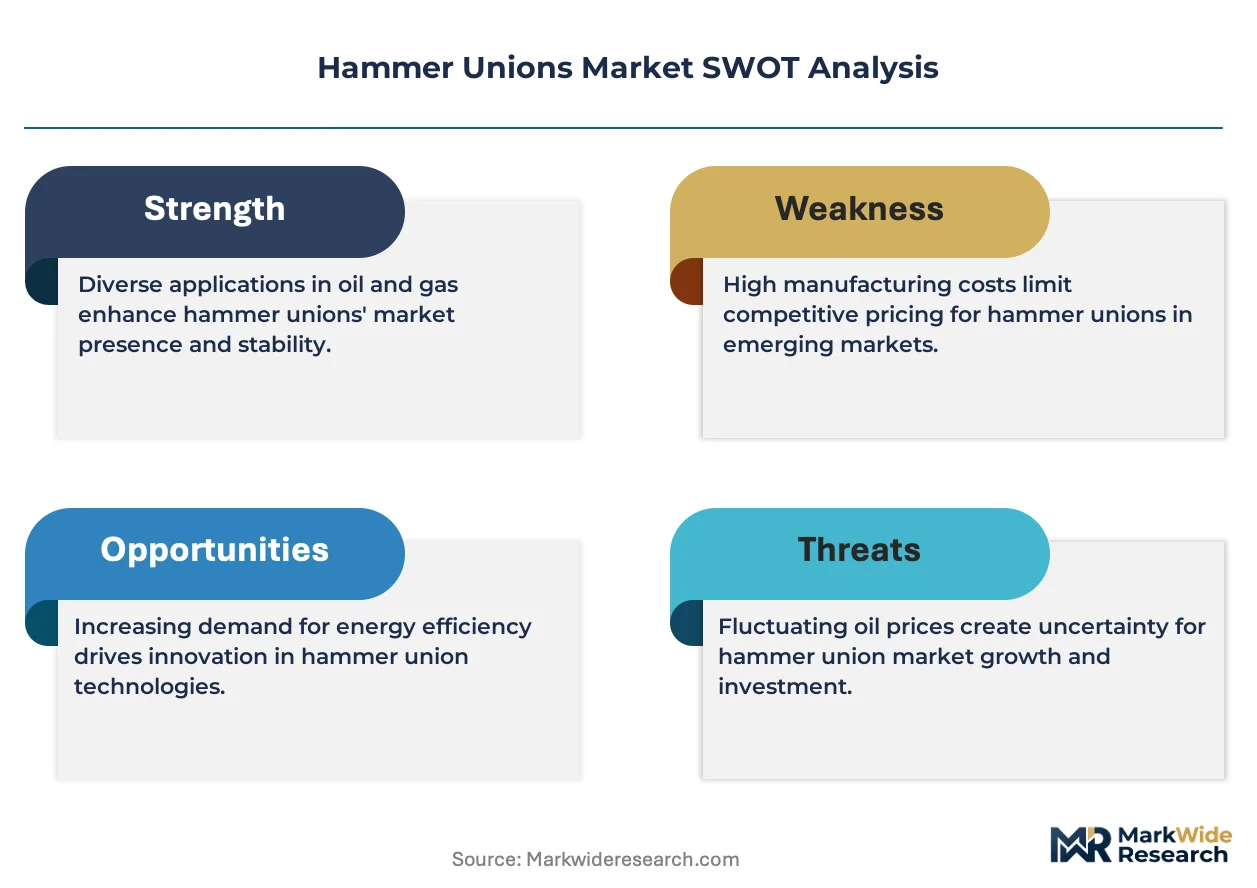
API 6A specification revisions are forcing hammer union suppliers to absorb elevated metallurgical testing costs while offshore contractors in the Gulf of Mexico accelerate sour-service alloy procurement. This regulatory compression is simultaneously narrowing qualified supplier pools and concentrating procurement authority among integrated drilling contractors.
Growth Catalysts
- OSHA Process Safety Management mandates:Field documentation requirements for pressure equipment traceability are sustaining aftermarket inspection and recertification demand across U.S. shale basins.
- Hydrogen sulfide compatibility specifications:Sour-service alloy grades resistant to sulfide stress cracking are capturing specification share in Permian Basin wellhead assemblies.
- Offshore Gulf of Mexico project pipeline:Deepwater drilling contractors are expanding high-pressure rated union procurement to meet wellhead integrity mandates.
Market Restraints
- Alloy steel input cost volatility:Nickel and chromium price swings compress margin predictability for sour-service grade production.
- Captive forging capacity concentration:North American integrated suppliers control critical heat-treatment infrastructure, limiting independent competitor scale.
- Flanged connection substitution in permanent installations:Fixed production facilities increasingly specify API 6A flanges over temporary hammer union assemblies.
Strategic Opportunities
- Methane emission detection protocol alignment:Fugitive-monitoring regime expansion creates connection integrity specification opportunities for leak-resistant union designs.
- Digital twin integration with pressure equipment:Sensor-embedded hammer unions enabling real-time fatigue monitoring are attracting integrated operator interest.
- Middle Eastern concession expansion:National oil companies are revising procurement frameworks to qualify additional sour-service alloy suppliers.
Industry Challenges
- API 6A certification timeline compression:Third-party validation queues extend supplier qualification cycles beyond operator procurement windows.
- Weld procedure specification harmonization:Inconsistent field repair standards across drilling contractors complicate aftermarket service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hammer Unions Market |
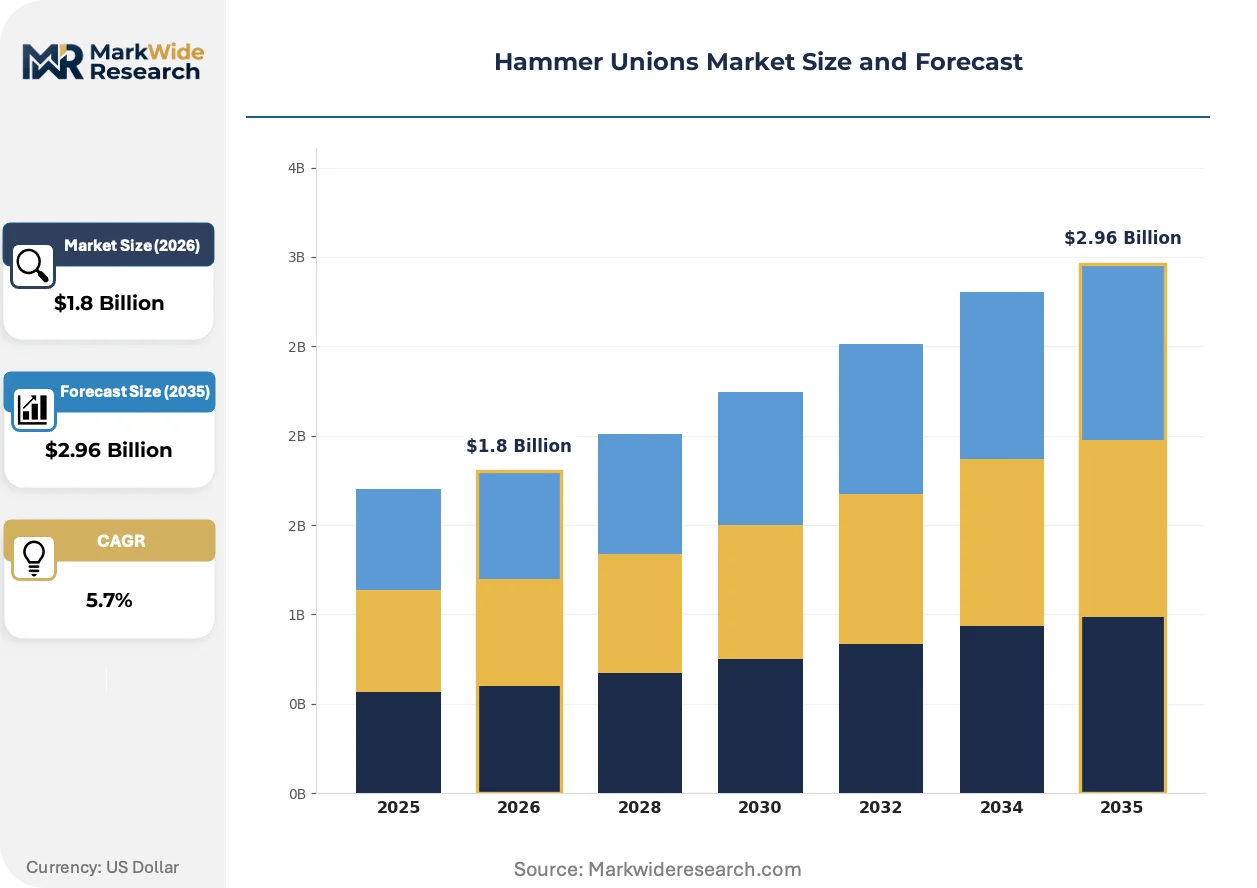
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hammer Unions, Pancake Hammer Unions, Wing Nut Hammer Unions, High Pressure Hammer Unions End User: Oil & Gas Industry, Construction, Manufacturing, Chemical Processing Size: 1 inch, 2 inch, 3 inch, 4 inch Material: Carbon Steel, Stainless Steel, Alloy Steel, Others |
| Companies Covered | PRV Industries, FMC Technologies, NOV (National Oilwell Varco), Align Manufacturing, Anvil International, ASC Engineered Solutions, Kemper Valve and Fittings, Trupply, American Completion Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hammer Unions Market Evolving Landscape
Material science advances and regulatory telemetry requirements are converging to redefine hammer union performance benchmarks. Suppliers must now engineer for simultaneous pressure integrity, corrosion resistance, and digital traceability.
Corrosion-resistant alloy overlays applied through laser cladding are electrifying hammer union sealing surface durability. Offshore contractors in the Gulf of Mexico are specifying clad interfaces for subsea flowline assemblies. This metallurgical shift is compressing replacement cycle frequency and elevating premium-grade margin capture.
EPA methane emission detection protocols are mandating connection integrity documentation for fugitive monitoring compliance. Equipment suppliers must now certify leak-tight performance across thermal cycling regimes. High-pressure applications in shale plays are experiencing the most acute documentation burden.
Integrated drilling contractors are consolidating procurement authority through master service agreements with qualified union suppliers. Independent distributors are losing specification influence as operators centralize vendor qualification. This concentration is most visible in Permian Basin drilling programs where contractor-led procurement dominates.
Hammer Unions Market Segmentation
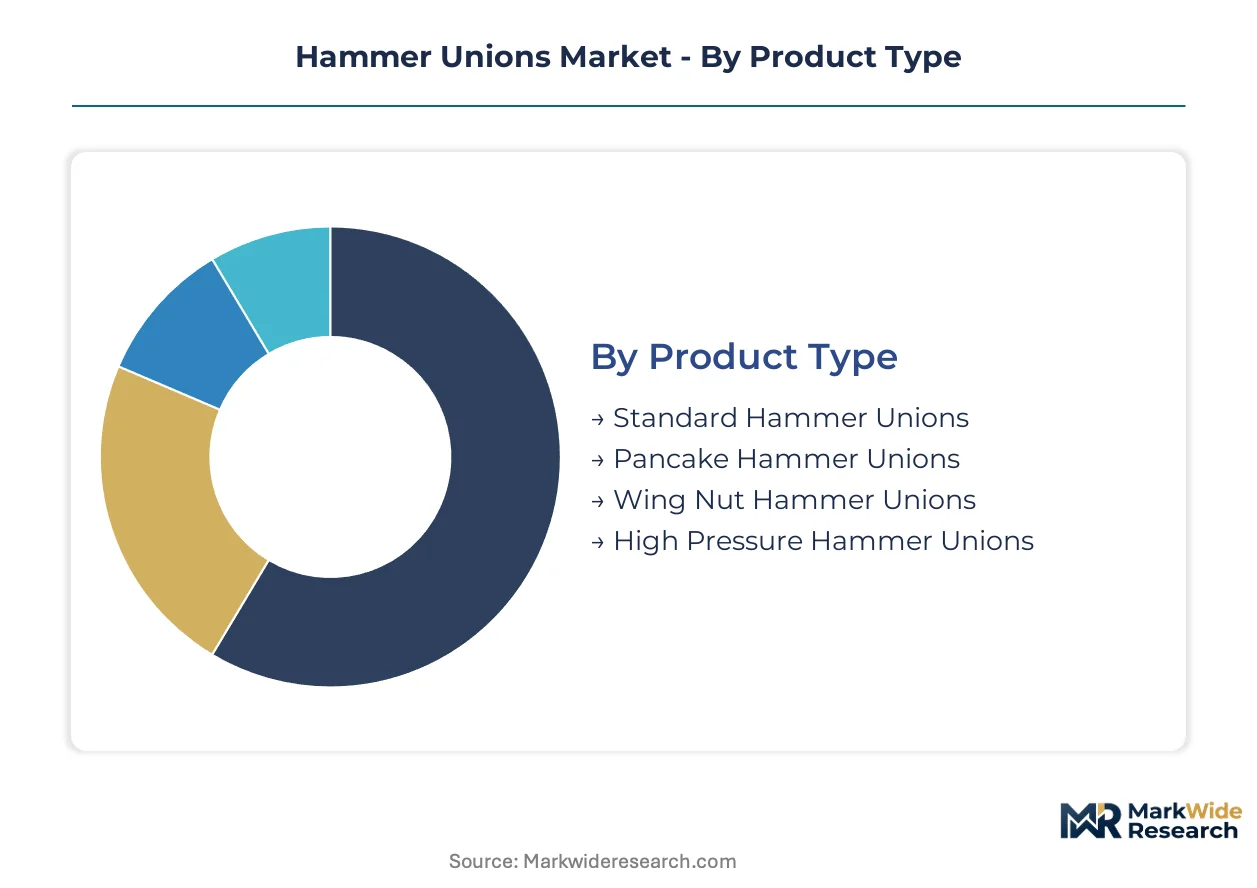
Hammer union specification diversity reflects divergent pressure regimes and corrosion environments across upstream oilfield operations. Procurement patterns fragment sharply between temporary flowline assemblies and permanent production infrastructure, with material selection and pressure rating serving as the primary commercial sorting mechanisms.
Product Type:
Supply concentration clusters around forged alloy variants capable of meeting API 6A certification thresholds, while standard-pressure inventory competes on lead-time velocity.
- High Pressure Hammer Unions:Engineered from heat-treated alloy steel with working pressure ratings from 10,000 to 20,000 psi. Demand concentrates in Gulf of Mexico deepwater drilling contractors facing wellhead integrity mandates from BSEE. API 6A certification requirements narrow qualified supplier pools and sustain premium margin capture.
- Standard Hammer Unions:Carbon steel construction rated 1,000 to 6,000 psi dominates unit volume across Permian Basin workover rig operations. Procurement prioritizes inventory availability and rapid field replacement over metallurgical sophistication.
- Pancake Hammer Unions:Compact profile design optimized for space-constrained manifold assemblies. Offshore platform contractors specify these for subsea flowline terminations where vertical clearance is restricted.
- Wing Nut Hammer Unions:Threaded or slip-on variants featuring external lugs for hammer-driven make-and-break operations. Construction sector demand favors these for temporary water and air service lines.
High Pressure Hammer Unions absorb the bulk of installed capacity; Pancake Hammer Unions are expanding most quickly in offshore applications.
End User:
Customer concentration tilts toward integrated drilling contractors consolidating procurement authority through master service agreements.
- Oil & Gas Industry:Upstream operators in U.S. shale basins and Middle Eastern concessions drive specification intensity. Sour-service alloy procurement accelerates in Permian Basin wellhead assemblies where hydrogen sulfide compatibility is non-negotiable.
- Chemical Processing:Refinery turnaround contractors specify corrosion-resistant hammer unions for temporary process line bypasses. Material traceability documentation under OSHA Process Safety Management sustains aftermarket inspection demand.
- Construction:Infrastructure dewatering and hydrostatic testing applications favor standard-pressure carbon steel inventory. Procurement emphasizes unit cost minimization over pressure rating headroom.
- Manufacturing:Industrial fluid power systems and test bench applications represent fragmented, price-sensitive demand with limited specification leverage.
Oil & Gas Industry commands the dominant share of procurement volume; Chemical Processing is gaining specification influence through safety compliance mandates.
Size:
Dimensional specification correlates directly with flowline throughput requirements and pressure drop tolerances in multi-well pad configurations.
- 2 inch:Standard workhorse dimension for drilling mud circulation and completion fluid transfer. Permian Basin rig contractors specify this size across 60% of temporary flowline assemblies.
- 3 inch:Production manifold and test separator connections favor this intermediate dimension. Gulf of Mexico platform retrofits are expanding 3-inch sour-service procurement.
- 4 inch:Large-bore applications in high-rate gas wells and centralized processing facilities. Limited supplier base for high-pressure 4-inch forgings creates procurement bottlenecks.
- 1 inch:Instrumentation and chemical injection lines specify this compact dimension. Downhole monitoring tool deployment drives niche demand.
2 inch dominates active inventory counts; 3 inch is climbing fastest in offshore project specifications.
Material:
Metallurgical specification divergence reflects the tension between unit cost minimization and corrosion resistance requirements in sour-service environments.
- Alloy Steel:Nickel-chromium-molybdenum grades resistant to sulfide stress cracking per NACE MR0175. Offshore contractors in the Gulf of Mexico mandate these for subsea flowline integrity.
- Carbon Steel:ASTM A105 forgings dominate standard-pressure drilling applications where corrosion exposure is minimal. Input cost volatility from scrap steel markets compresses margin predictability.
- Stainless Steel:316L and duplex grades specified for chemical processing and coastal offshore environments. Premium pricing limits penetration outside corrosion-critical applications.
- Others:Titanium and Inconel overlays for extreme sour-service and high-temperature geothermal applications. Laser cladding technology is expanding overlay durability.
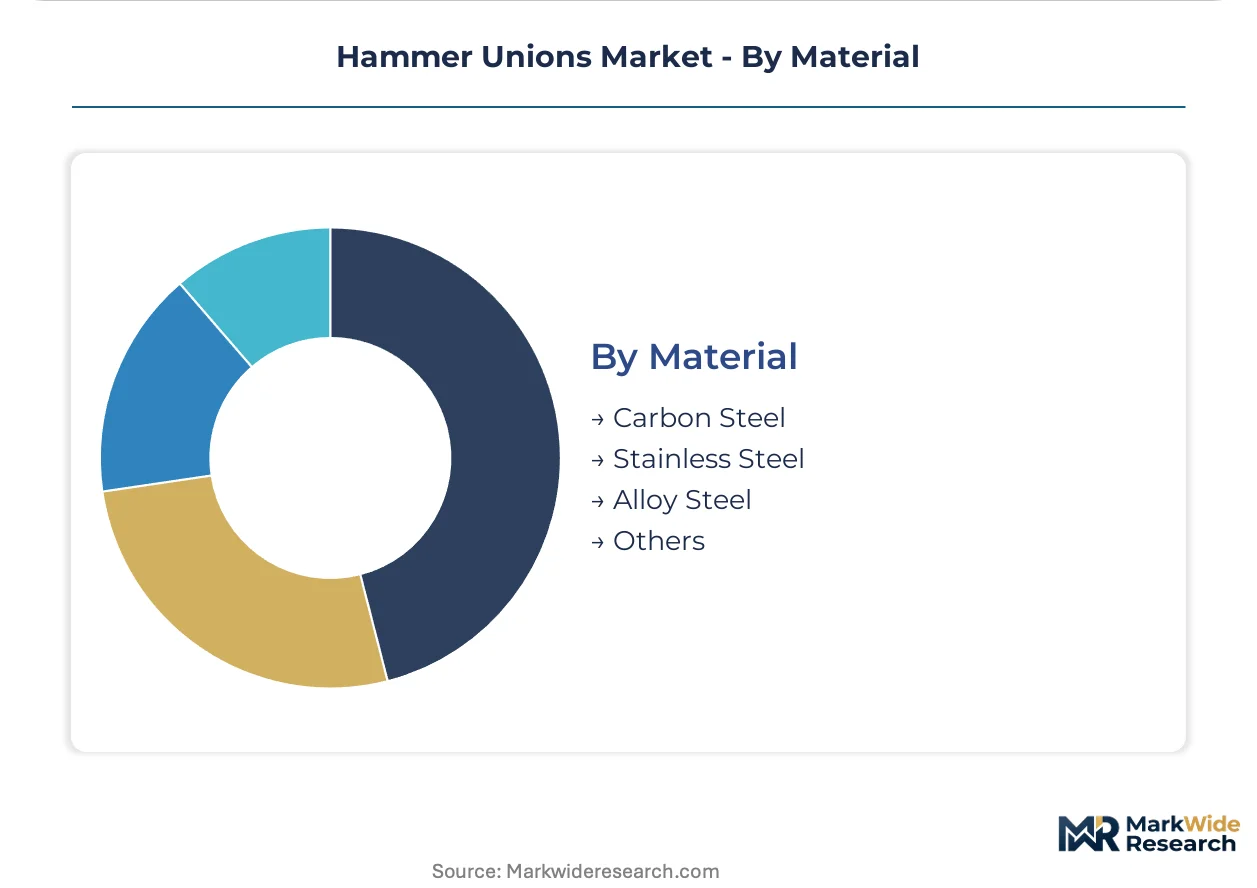
Carbon Steel maintains the largest installed base; Alloy Steel is gaining share fastest in wellhead integrity specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream operators in the United States and Middle Eastern concessions concentrate procurement authority for high-pressure rated unions, while offshore contractors in the Gulf of Mexico and North Sea drive sour-service alloy specifications.
United States
Permian Basin drilling contractors specify sour-service hammer unions for wellhead assemblies where hydrogen sulfide compatibility is mandatory. OSHA Process Safety Management mandates sustain aftermarket inspection demand across Texas and New Mexico shale plays. Houston anchors the supplier ecosystem, with integrated forging capacity concentrated along the Gulf Coast petrochemical corridor.
Saudi Arabia
National oil companies are revising procurement frameworks to qualify additional sour-service alloy suppliers for concession expansion programs. The country's national petroleum regulator enforces wellhead integrity standards that elevate API 6A certification requirements. Eastern Province production clusters around Dhahran and Jubail Industrial City concentrate demand for high-pressure flowline connectors.
United Arab Emirates
Offshore field development in the Upper Zakum and Lower Zakum concessions drives specification intensity for subsea-rated hammer unions. MOHAP oversight of industrial equipment safety elevates material traceability documentation burdens. Abu Dhabi anchors procurement authority, with fabrication yards in Jebel Ali supplying regional drilling contractors.
Norway
North Sea platform operators mandate corrosion-resistant alloy grades for subsea flowline terminations exposed to North Atlantic conditions. The country's national petroleum regulator enforces strict wellhead equipment validation protocols. Stavanger and Bergen harbor clusters concentrate engineering procurement for deepwater drilling contractors.
Brazil
Pre-salt basin development drives demand for high-pressure rated unions in ultra-deepwater drilling campaigns. ANVISA and national petroleum regulator requirements govern pressure equipment certification for offshore installations. Rio de Janeiro anchors the supplier ecosystem, with fabrication yards in Niterói serving Petrobras-led procurement.
Hammer Unions Market Competitive Landscape
North American producers anchor the premium-tier supply base; European and Middle Eastern specialists hold regional qualification advantages. The vendor structure concentrates around integrated forging capacity owners, independent distributors, and subsea system integrators. Three archetypes dominate: captive-forging integrated suppliers, sour-service alloy specialists, and standard-pressure inventory competitors. Competitive moves center on API 6A certification timeline acceleration and master service agreement consolidation with drilling contractors.
Among U.S.-based integrated suppliers, NOV and FMC Technologies exemplify the captive-forging archetype, while Kemper Valve and Fittings occupies a position within the domestic manufacturing scale tier. These three entities represent distinct competitive vectors: offshore system integration, subsea high-pressure applications, and rapid lead-time standard inventory respectively. Their positioning reflects the market's segmentation between premium-grade sour-service procurement and velocity-driven carbon steel replacement cycles.
| Leading Market Players |
|---|
| PRV Industries |
| FMC Technologies |
| NOV (National Oilwell Varco) |
| Align Manufacturing |
| Anvil International |
| ASC Engineered Solutions |
| Kemper Valve and Fittings |
| Trupply |
| American Completion Tools |
| Others |
Value Network & Pricing Analysis
API 6A certification tiers bifurcate the market into premium alloy suppliers commanding captive forging premiums and carbon steel competitors racing on inventory velocity. This divergence manifests in procurement patterns where Gulf of Mexico contractors absorb metallurgical testing costs for sour-service grades while Permian Basin workover rigs minimize unit expenditure on standard-pressure replacements.
Pricing Analysis
Volume-margin splits separate the market into three distinct tiers: premium alloy grades capturing disproportionate returns through narrow qualified supplier pools, mid-pressure carbon steel variants competing on lead-time arbitrage, and commodity inventory facing relentless cost compression. Price differentiation rests on API 6A certification status and captive heat-treatment infrastructure ownership. Margins are tightening in standard-pressure segments due to scrap steel input volatility and distributor consolidation. Chemical processing contractors exhibit highest price sensitivity for temporary bypass applications; offshore drilling contractors show lowest sensitivity given wellhead integrity mandate compliance costs.
Supply Chain Analysis
Dual-sourcing requirements from integrated drilling contractors mandate qualified supplier redundancy across heat-treatment and forging stages. Manufacturing concentrates in the United States, Saudi Arabia, and Norway where API 6A validation infrastructure anchors production. Raw material flows draw from nickel-chromium-molybdenum alloy suppliers, ASTM A105 carbon steel forgers, and laser cladding service providers. Single-source vulnerability concentrates in high-pressure 4-inch forging capacity where qualified mill rolls are scarce. Distribution runs through master service agreements with drilling contractors, bypassing independent distributor networks in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hammer unions market is becoming a vertical-integration race where control over heat-treatment infrastructure and API certification timelines determines competitive survival. Players are pursuing backward integration into captive forging capacity to escape raw material volatility and qualification bottlenecks.
For Market Incumbents: Lock in drilling contractor relationships through accelerated API 6A certification timelines and exclusive master service agreements. Defend against flanged connection substitution in permanent installations by embedding digital fatigue monitoring into high-pressure product lines. Prioritize captive forging capacity additions along the Gulf Coast petrochemical corridor to secure alloy steel input stability. For New Entrants and Emerging Players: Capture specification share in Middle Eastern concession expansion programs where national oil companies are actively qualifying additional sour-service alloy suppliers. Target chemical processing turnaround contractors facing OSHA Process Safety Management documentation burdens with inspection and recertification service bundles. Lead with laser cladding overlay capabilities as a differentiated metallurgical offering. For Investors and Strategic Acquirers: Re-rating potential sits with sour-service alloy specialists given hydrogen sulfide compatibility mandate expansion across Permian Basin and Gulf of Mexico drilling programs. Long-term viability favors entities with integrated forging capacity and established BSEE wellhead equipment validation protocols. Monitor API 6A third-party validation queue lengths as the critical inflection signal for supplier qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Acceleration | Shortens supplier qualification cycles to match drilling contractor procurement windows. |
| Captive Forging Capacity Expansion | Secures heat-treatment infrastructure control against nickel-chromium input volatility. |
| Digital Twin Integration | Sensor-embedded unions attract integrated operator interest for real-time fatigue monitoring. |
| Laser Cladding Overlay Adoption | Corrosion-resistant sealing surfaces elevate premium-grade margin capture in subsea applications. |
| Middle Eastern Supplier Qualification | National oil company concession expansion creates specification entry points for alloy specialists. |
Research Methodology
Trade databases, API certification registries, and BSEE wellhead equipment filings formed the secondary backbone for market sizing and supplier mapping. Primary interviews with procurement directors at integrated drilling contractors, metallurgical engineers at forging facilities, and aftermarket service managers at chemical processing facilities validated demand patterns and qualification timelines. Bottom-up unit demand estimates across pressure rating tiers and material grades triangulated against top-down procurement spend analysis from upstream operator capital budgets.
Bottom-up modeling aggregated individual product line volumes by pressure rating, material specification, and end-use application across the projection horizon. Segmentation dimensions included product type, end-user industry, dimensional size, and metallurgical grade. CAGR derivation incorporated historical replacement cycle frequencies, regulatory mandate implementation schedules, and alloy steel price elasticity assumptions. Forecast inputs weighted Permian Basin drilling activity trajectories and Gulf of Mexico deepwater project pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to API specification revision timing and methane emission detection protocol enforcement intensity. Assumptions reflect current regulatory frameworks and contractor procurement consolidation trends. Deviation in nickel-chromium alloy price volatility or BSEE wellhead integrity mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Global Riveting Equipment Market
Construction Equipment
Piling Machine Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Pressure Vessel Market