
 Global Riveting Equipment Market | 2026-2036
Global Riveting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Riveting Equipment Market Intelligence
The supply of skilled manual riveters trained in traditional solid riveting techniques is collapsing, creating an urgent need for automated and robotic systems. Atlas Copco AB leverages its industrial automation expertise to offer integrated robotic riveting cells. Stanley Engineered Fastening specializes in high-volume blind riveting systems for automotive and industrial markets. Cherry Aerospace dominates the high-specification segment for aerospace-grade fasteners and tooling.
Riveting equipment comprises mechanical, pneumatic, or hydraulic tools designed to install and deform a rivet, creating a permanent mechanical fastener. Its primary function is to join materials, such as metal sheets or composite panels, in applications where welding is impractical or undesirable. Self-piercing riveting technology is advancing rapidly, driven by its use in joining dissimilar materials in automotive body-in-white applications. While pneumatic riveters remain the workhorse for many workshops, battery-operated riveters are gaining share due to their portability and ease of use in field maintenance.
Occupational safety regulations, such as those from the US Occupational Safety and Health Administration (OSHA), mandate ergonomic designs and noise reduction features. Conformance with CE marking in Europe and adherence to ISO 9001 quality management standards are critical for market access and product reliability. Equipment manufacturers must therefore balance investments in automation and connectivity with the need to meet increasingly stringent global safety and quality certifications.
Market Dynamics
The rapid decline in the supply of skilled manual riveters is forcing an industry-wide pivot toward automated and robotic riveting systems. This structural shift fundamentally alters capital investment priorities and factory floor configurations, particularly in high-volume manufacturing sectors.
Growth Catalysts
- Aerospace Lightweighting:The expanding use of composite materials and advanced aluminum alloys in aircraft fuselages and wing structures requires specialized riveting techniques that can join these materials without compromising structural integrity.
- EV Manufacturing in China:Automotive production for electric vehicles in hubs like Shanghai and Shenzhen drives demand for self-piercing riveting to join dissimilar materials in battery enclosures and body-in-white structures.
- Ergonomic Regulations:Mandates from bodies like the US Occupational Safety and Health Administration (OSHA) concerning repetitive stress injuries and noise exposure accelerate the replacement of traditional pneumatic tools with quieter, ergonomic battery-powered and automated systems.
Market Restraints
- High Capital Expenditure:The significant upfront cost of integrated robotic riveting cells and automated systems presents a substantial investment barrier for small and medium-sized enterprises (SMEs) and contract manufacturers.
- Technical Process Limitations:Certain brittle materials, such as specific ceramic-matrix composites or thermoset plastics, are prone to cracking during the riveting process, limiting the technology's applicability compared to adhesive bonding.
- Substitution from Welding:Advances in friction stir welding and laser welding technologies provide a viable alternative for joining aluminum and other non-ferrous metals in automotive and rail applications, creating direct competition.
Strategic Opportunities
- Portable Repair Solutions:The market for high-performance, battery-operated riveting tools for on-site maintenance and field repair in the construction, commercial vehicle, and renewable energy sectors remains significantly underpenetrated.
- Process Monitoring and Data Analytics:Integrating sensors into riveting heads to capture data on clamp force, rivet insertion speed, and final formation provides a new service revenue stream based on quality assurance and predictive maintenance.
- Miniaturization for Electronics:The assembly of consumer electronics and server racks creates an opportunity for precision micro-riveting systems designed for fastening small components within compact and heat-sensitive environments.
Industry Challenges
- Automation Integration Complexity:Manufacturers face considerable difficulty and expense in integrating new robotic riveting cells with legacy factory control software and manufacturing execution systems (MES), causing production delays.
- Technician Skill Gap:A critical shortage exists for technicians who possess the dual skills required to program, troubleshoot, and maintain the complex mechanical, electronic, and software components of modern automated riveting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Riveting Equipment Market |
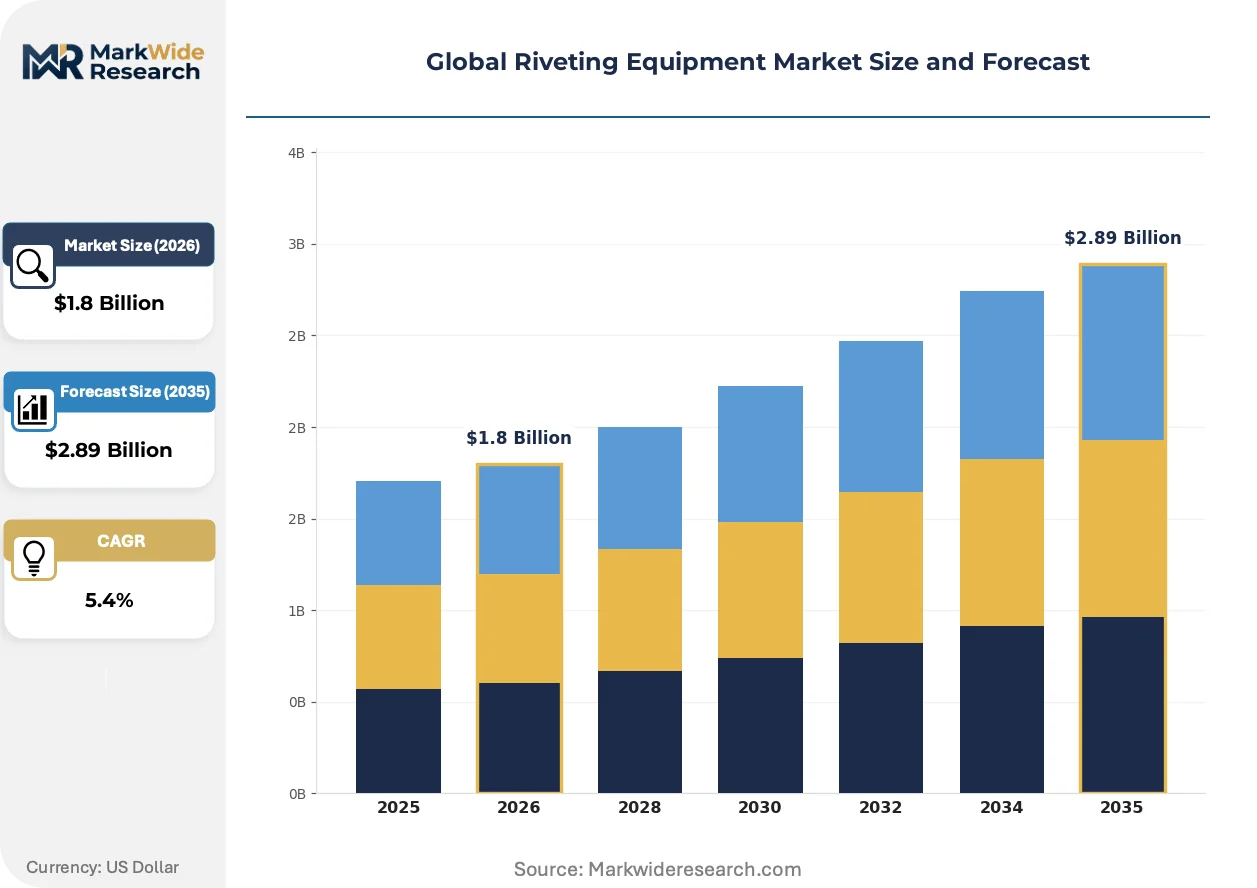
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Riveters, Pneumatic Riveters, Hand Riveters, Electric Riveters, Battery-Operated Riveters Technology: Blind Riveting, Solid Riveting, Semi-Tubular Riveting, Self-Piercing Riveting, Threaded Riveting Application: Aerospace Assembly, Shipbuilding, Appliance Manufacturing, Metal Fabrication, Structural Engineering End User: OEM Manufacturers, Maintenance Workshops, Tier-1 Suppliers, Contract Assemblers, Aftermarket Service Providers |
| Companies Covered | Ingersoll Rand, Cherry Aerospace, Stanley Engineered Fastening, GESIPA Blindniettechnik GmbH, Brown Aviation Tool Company, Atlas Copco AB, Orbitform, Stanley Black & Decker, Arconic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Riveting Equipment Market Strategic Shifts & Innovations
The concept of riveting equipment is expanding beyond mechanical force application to include data generation and system integration. This evolution is driven by the dual pressures of manufacturing efficiency and stringent quality assurance demands in critical industries like aerospace and automotive.
Self-piercing riveting (SPR) provides a method for joining dissimilar materials without a pre-drilled hole. Automotive OEMs are the primary adopters, using SPR extensively in aluminum-intensive vehicle bodies to improve crash performance and reduce weight. This technology is fragmenting the traditional spot-welding market for certain body-in-white applications, creating a distinct supply chain for specialized dies and rivets.
European Union directives for CE marking, particularly those covering machinery safety and workplace noise emissions, impose strict design constraints. This forces equipment manufacturers to invest heavily in developing quieter hydraulic-pneumatic systems, integrated safety guards, and ergonomic tool bodies. The pneumatic hand tool segment is most affected, with manufacturers redesigning products to maintain market access in the EU.
Aversion to large, one-time capital outlays is changing equipment acquisition models. End-users in high-cost labor markets are moving from purchasing standalone tools to leasing fully-serviced, integrated robotic riveting work cells on a subscription or per-unit basis. This shift is most visible in the German automotive sector, where automation integrators are displacing traditional equipment distributors.
Global Riveting Equipment Market Segmentation
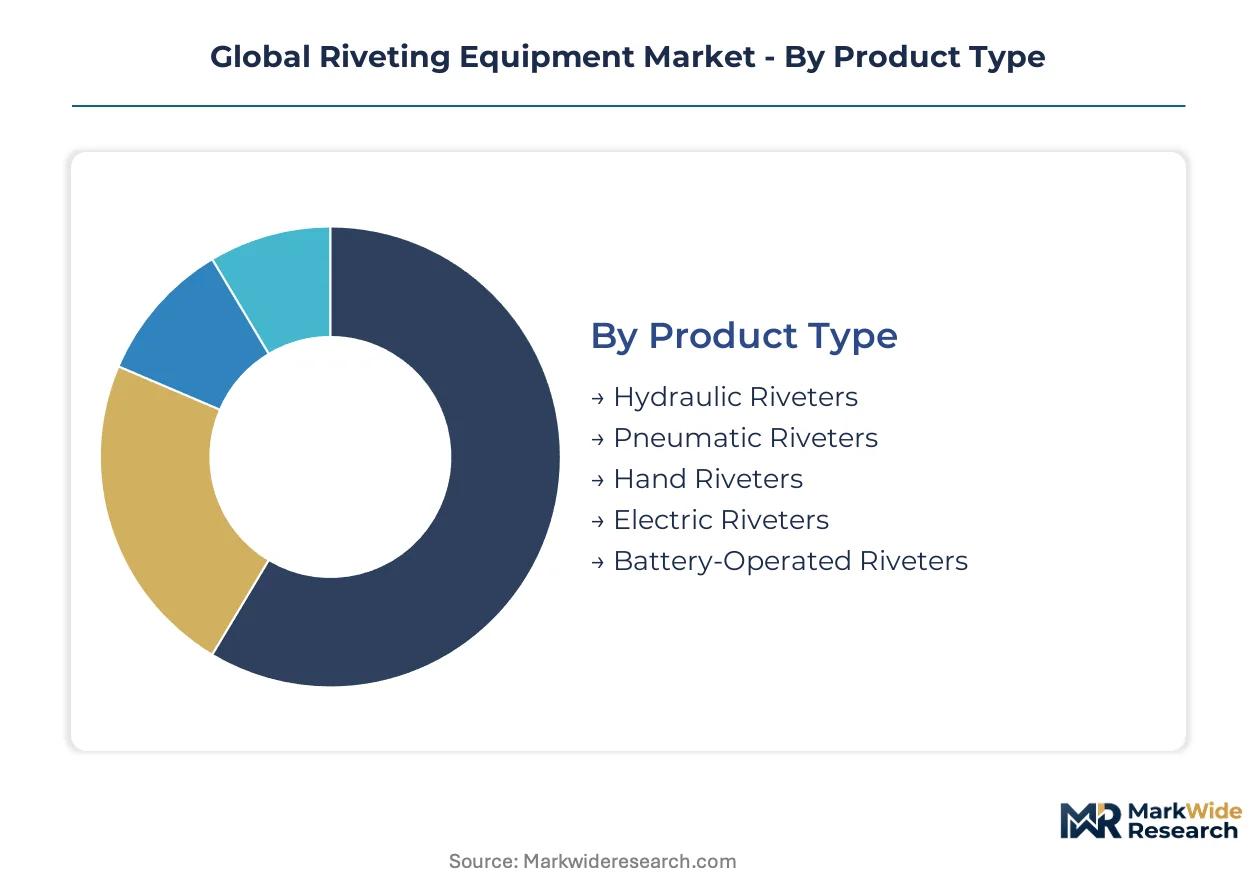
Understanding the market's segmentation reveals the diverse operational requirements and technological preferences across various industrial applications. This granular analysis helps identify specific demand pockets and the underlying drivers influencing equipment adoption within distinct user groups.
Product Type:
The geographic spread of riveting equipment demand often depends on regional industrial maturity and labor costs, influencing the balance between manual and automated tool adoption.
- Pneumatic Riveters:These tools utilize compressed air to drive the riveting process, offering high power-to-weight ratios and reliability for continuous industrial operation. Demand remains concentrated in established manufacturing hubs in Germany and Japan, where robust industrial infrastructure supports air tool deployment.
- Battery-Operated Riveters:Cordless tools powered by rechargeable batteries provide enhanced portability and flexibility for on-site work and remote applications, eliminating the need for air lines or power cords. Their adoption is gaining momentum in field maintenance across the US and construction projects in Australia, driven by convenience and ergonomic benefits.
- Hydraulic Riveters:Heavy-duty equipment generates high forces for large-diameter rivets, common in structural applications.
- Electric Riveters:These tools offer precise control and quiet operation, suitable for environments where noise reduction is critical.
- Hand Riveters:Manual tools are used for low-volume tasks and repair work, valued for their simplicity and cost-effectiveness.
Pneumatic Riveters command the established base. The steepest expansion runs through Battery-Operated Riveters.
Technology:
The technological sophistication of riveting equipment is primarily driven by the specific material joining challenges and performance requirements of different applications, rather than geographic factors.
- Self-Piercing Riveting:This advanced cold-forming process joins dissimilar materials, such as aluminum and steel, without pre-drilled holes, providing robust mechanical interlocks. Automotive OEMs in China and Europe extensively employ SPR for lightweight vehicle body-in-white structures, enhancing crash performance and reducing overall weight.
- Solid Riveting:A traditional method involving a solid rivet inserted into a pre-drilled hole and deformed on both ends, creating a permanent joint. This technique remains critical for high-integrity structural applications in aerospace assembly across North America and Europe, where long-term fatigue resistance is paramount.
- Blind Riveting:These rivets are installed from one side of the workpiece, making them ideal for enclosed structures and limited access applications.
- Semi-Tubular Riveting:This method uses a rivet with a partial hole at the tail end, requiring less force for installation than solid rivets.
- Threaded Riveting:These fasteners create a strong load-bearing thread in thin materials, suitable for subsequent attachment of components with screws.
Self-Piercing Riveting is driven by automotive lightweighting. Solid Riveting remains critical for aerospace structural integrity.
Application:
The application focus for riveting equipment is largely dictated by industry-specific material requirements and regulatory standards, which vary significantly across sectors.
- Aerospace Assembly:This segment demands high-precision, high-strength riveting solutions for joining advanced composite materials and aluminum alloys in aircraft fuselages and wing structures. Strict FAA and EASA regulations govern equipment specifications and process control for airworthiness in the US and European aerospace industries.
- Metal Fabrication:Riveting equipment is widely used in general metalworking for various industrial components, enclosures, and structural elements where welding is not feasible or desired. This broad application spans diverse manufacturing operations across India and Southeast Asia, driven by versatility and cost-effectiveness.
- Shipbuilding:Heavy-duty riveting systems are employed for joining large metal plates and structural components in marine vessel construction.
- Appliance Manufacturing:Precision riveting is used for assembling consumer appliances, focusing on speed and consistency for high-volume production.
- Structural Engineering:Riveting tools are crucial for connecting steel beams and other load-bearing structures in civil construction projects.
The primary demand originates from Aerospace Assembly, with Metal Fabrication showing consistent industrial usage.
End User:
End-user segmentation reflects varied purchasing behaviors and operational scales, from large-scale manufacturing to specialized repair services.
- OEM Manufacturers:These large-scale producers integrate riveting equipment directly into their assembly lines for high-volume production, particularly in the automotive and aerospace sectors. Their procurement patterns prioritize automation, integration with existing MES, and long-term service contracts, especially for EV manufacturing in China.
- Maintenance Workshops:These facilities require versatile and often portable riveting tools for repair, overhaul, and custom fabrication tasks across various industries. Demand in European maintenance workshops is shifting towards ergonomic battery-operated riveters, driven by occupational safety regulations.
- Tier-1 Suppliers:These companies provide components and sub-assemblies to OEMs, often operating high-volume, specialized riveting processes.
- Contract Assemblers:Firms offering assembly services to multiple clients utilize a range of riveting equipment to meet diverse project specifications.
- Aftermarket Service Providers:These entities focus on repair and replacement of components, requiring durable and adaptable riveting solutions for field use.
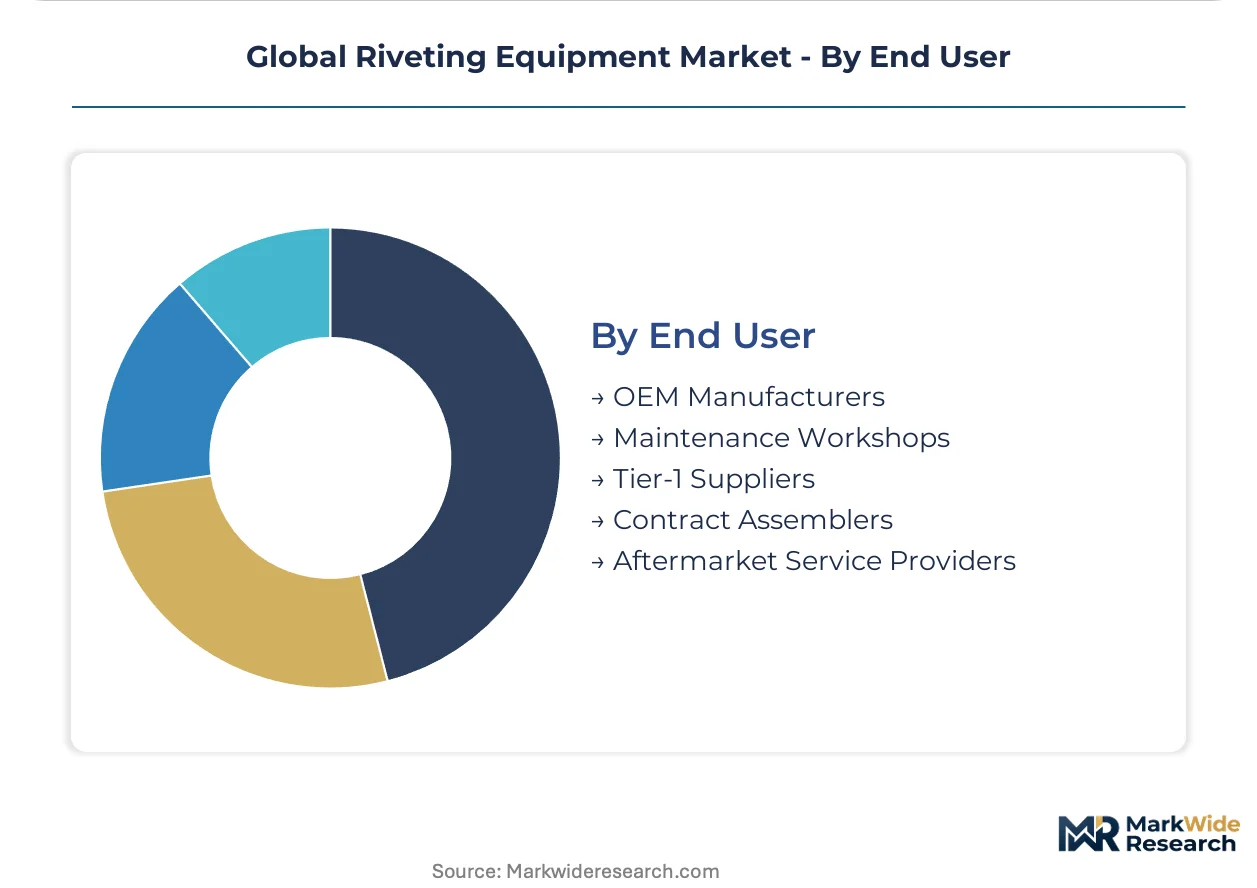
The market's volume is concentrated in OEM Manufacturers, while Maintenance Workshops represent a growing area for portable solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption mix for riveting equipment exhibits distinct regional preferences, driven by industrial maturity and labor cost dynamics. While China leads in automated self-piercing riveting for high-volume EV production, the United States prioritizes high-integrity solid riveting for aerospace and portable solutions for field maintenance.
China
Automotive production for electric vehicles drives substantial demand for self-piercing riveting technology. National GB standards for manufacturing quality influence equipment design and adoption in industrial settings. Advanced manufacturing hubs in Shanghai and Shenzhen concentrate demand for precision riveting systems in electronics and battery enclosures.
United States
Aerospace assembly remains a critical application, demanding high-strength solid riveting for structural integrity. OSHA mandates concerning repetitive stress injuries and noise exposure accelerate the shift towards ergonomic and automated systems. Key aerospace clusters in Seattle and Wichita integrate specialized robotic riveting cells into aircraft production lines.
Germany
Established manufacturing hubs in Germany continue to utilize pneumatic riveters, supported by robust industrial infrastructure. CE marking directives for machinery safety and workplace noise emissions necessitate quieter, safer equipment designs. The automotive sector in Bavaria and Baden-Württemberg increasingly leases fully-serviced robotic riveting work cells.
Japan
High-volume manufacturing sectors, particularly automotive and electronics, drive demand for efficient and precise riveting solutions. Adherence to JIS standards for industrial equipment quality ensures reliability and performance. Aichi Prefecture, a major automotive production hub, invests in automated riveting systems for vehicle assembly.
Australia
Field maintenance and construction projects increasingly adopt battery-operated riveters due to their portability and flexibility. Work health and safety regulations encourage the use of ergonomic tools to minimize operator fatigue. Major urban centers like Sydney and Melbourne see demand for versatile riveting equipment in infrastructure development and repair.
Global Riveting Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the riveting equipment market. These tiers include industrial automation specialists, high-volume fastening system providers, and high-specification aerospace tooling suppliers. Companies pursue strategic partnerships and technology licensing to expand their market reach and product portfolios.
On the premium-tier vector, Atlas Copco AB exemplifies expertise in integrated robotic riveting cells, leveraging its industrial automation background. Stanley Engineered Fastening occupies a position as a high-volume blind riveting systems provider for diverse industrial applications. Cherry Aerospace anchors the high-specification segment, focusing on aerospace-grade fasteners and specialized tooling for critical assembly.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Cherry Aerospace |
| Stanley Engineered Fastening |
| GESIPA Blindniettechnik GmbH |
| Brown Aviation Tool Company |
| Atlas Copco AB |
| Orbitform |
| Stanley Black & Decker |
| Arconic |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing scale for aerospace and automotive assembly directly shapes supply concentration, influencing price floors for integrated riveting solutions. This scale allows leading manufacturers to invest heavily in automation, driving down per-unit production costs and creating barriers for smaller competitors.
Pricing Analysis
Contract-based long-term offtake agreements dominate pricing for integrated robotic riveting cells, reflecting significant capital investment and ongoing service requirements. Price differentiation stems from the level of automation and specialized certifications, particularly for aerospace-grade equipment, and the inclusion of data analytics features. Pricing pressure stems from the increasing availability of modular automated solutions, particularly for mid-tier manufacturers. OEM manufacturers exhibit the least price sensitivity due to stringent quality and integration demands, while maintenance workshops are highly sensitive to initial tool costs and ergonomic benefits.
Supply Chain Analysis
China and Germany anchor the supply of advanced riveting equipment, leveraging robust manufacturing infrastructure and R&D capabilities. The supply chain draws from specialized alloys for high-strength rivets and precision electronic components for automated systems. A structural risk involves single-source vulnerabilities for critical automation software and sensor technologies. Distribution runs through direct sales channels for major OEMs and a network of specialized industrial distributors for smaller workshops and contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The riveting equipment market is undergoing a platform-economics inflection, driven by the integration of data analytics and connectivity into robotic systems for quality assurance and predictive maintenance.
For Market Incumbents: Secure long-term service contracts for automated riveting cells, bundling predictive maintenance and software upgrades to create recurring revenue streams. This defends against emerging entrants offering lower-cost, modular solutions. Invest in R&D for AI-driven process optimization, enhancing efficiency and reducing operational costs for high-volume automotive lines. Control key component supply chains for specialized fasteners to mitigate geopolitical risks.
For New Entrants and Emerging Players: Anchor in underpenetrated regional markets like Southeast Asia for metal fabrication, offering ergonomic battery-operated tools with strong local support. Target the growing demand for portable repair solutions in construction and renewable energy sectors. Develop subscription models for smaller, flexible robotic riveting work cells, lowering the significant capital expenditure barrier for SMEs. Focus on niche applications requiring micro-riveting for electronics assembly.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrators offering subscription-based robotic cells, providing stable cash flows. Identify acquisition targets specializing in process monitoring software or advanced sensor technology for riveting heads. A key signal to watch is the adoption rate of data-enabled riveting heads in general industrial applications, indicating broader market acceptance beyond aerospace. Focus on companies with strong intellectual property in self-piercing riveting for lightweight materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-driven process monitoring | Enhances quality control and reduces rework for aerospace component manufacturers. |
| Expand battery-operated tool portfolio | Addresses demand for portable, ergonomic solutions in field maintenance and construction. |
| Develop modular robotic riveting cells | Lowers capital expenditure barriers for small and medium-sized enterprises. |
| Form strategic partnerships with integrators | Accelerates market penetration for automated systems in high-volume production. |
| Obtain advanced material compatibility certifications | Unlocks new applications in lightweight composite and dissimilar material assembly. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, patent databases, national manufacturing statistics, and company annual reports. This involved in-depth interviews with aerospace engineers, automotive production managers, maintenance workshop owners, and equipment integrators. The analysis utilized both bottom-up and top-down triangulation to ensure data consistency and accuracy across all segments.
The forecast framework modeled segmentation dimensions including product type, technology, application, end-user, and regional adoption patterns across the analysis window. Compound Annual Growth Rates were derived from historical trends, projected technological adoption rates, and macroeconomic indicators. Key industry-specific forecast inputs included electric vehicle production forecasts and commercial aerospace build rates.
Decision-makers should treat outputs as directional under assumptions of stable raw material costs and consistent regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect assumptions concerning continued investment in automation and the evolution of alternative joining technologies. Recalibration cycles align with material shifts in global economic conditions or manufacturing policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
India Crane Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Australia Concrete Pump Market