
 Self-Driving Dumpers Machine Market | 2026-2036
Self-Driving Dumpers Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Driving Dumpers Machine Market Analysis
Contractor demand is rotating toward mining companies as the dominant buyer archetype for self-driving dumpers. Caterpillar Inc. leverages its autonomous haulage heritage to sustain technology leadership in large-scale deployments. Komatsu Ltd. anchors its position through integrated fleet management platforms that span multiple mine sites. Volvo Construction Equipment differentiates via articulated chassis expertise adapted for narrower quarry environments.
Self-driving dumpers are autonomous or teleoperated earthmoving vehicles engineered for material transport without continuous human operator presence, typically integrating LiDAR arrays, GNSS positioning, and onboard compute platforms processing terrain data at sub-second intervals for collision avoidance and route optimization. Articulated dump trucks lead unit shipments due to maneuverability advantages in confined construction and quarry settings, while rigid dump trucks concentrate value generation through ultra-class mining configurations exceeding 400-ton payload capacity. Autonomous navigation technology captures the fastest expansion trajectory as original equipment manufacturers embed machine-learning path planners that reduce fuel consumption and tire wear across haul cycles.
The US Mine Safety and Health Administration enforces collision-avoidance mandates that directly shape sensor redundancy requirements and emergency-stop system architectures for autonomous haulage. The EU Machinery Directive and CE marking framework govern functional safety certifications, creating compliance thresholds that filter non-integrated subsystem suppliers from European market access. China's MIIT publishes GB standards for intelligent connected vehicles that extend to mining-sector autonomous equipment, establishing domestic technical baselines for sensor fusion and V2X communication protocols. Stakeholders must monitor how divergent regional certification timelines affect platform development roadmaps and aftermarket service localization strategies.
Market Dynamics
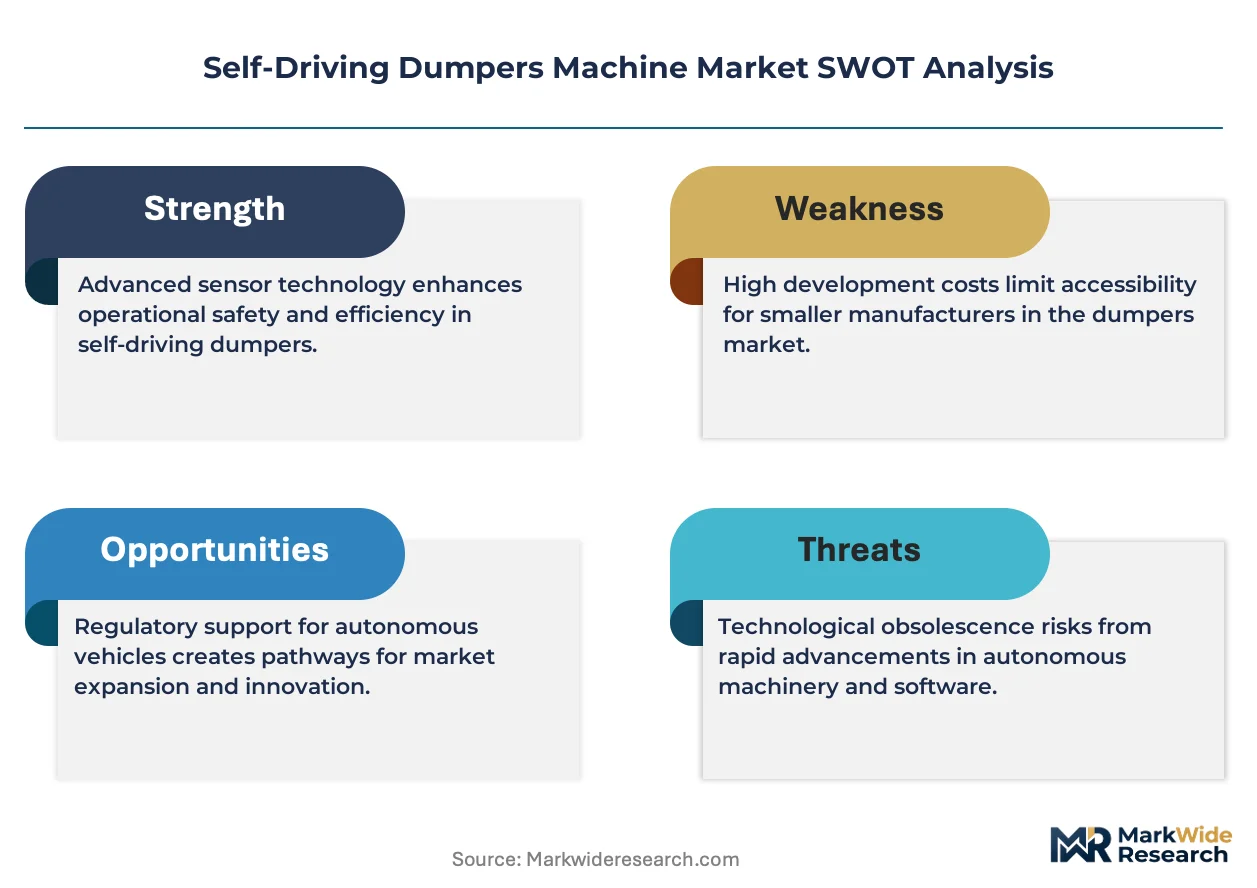
Mining sector labor shortages are compressing operator availability below sustainable thresholds, forcing fleet operators toward autonomous haulage architectures that eliminate continuous cab occupancy. This structural pressure is reshaping procurement timelines and technology roadmaps across earthmoving equipment.
Growth Catalysts
- Australia's Pilbara corridor:Rio Tinto and BHP have validated decade-long autonomous haulage deployments, generating operational data that reduces adoption risk for follower mining companies.
- EU AI Act safety frameworks:Standardized certification pathways for autonomous earthmoving equipment are reducing regulatory uncertainty for OEMs targeting European quarry markets.
- LiDAR-GNSS sensor fusion:Sub-second terrain processing capabilities are enabling collision-avoidance performance that meets MSHA emergency-stop mandates without human oversight.
Market Restraints
- High-grade LiDAR supply concentration:Sensor manufacturing capacity clusters in East Asian contract manufacturers, creating single-source vulnerability for OEM qualification timelines.
- Steel and rare-earth input volatility:Articulated chassis production faces margin compression from fluctuating alloy prices and permanent magnet supply constraints.
- Functional safety certification friction:CE marking under the EU Machinery Directive requires redundant subsystem validation that extends product development cycles by 18-24 months.
Strategic Opportunities
- India's surface mining expansion:Coal India and captive mining blocks are modernizing truck fleets under PLI scheme incentives for domestic manufacturing of autonomous components.
- 5G-V2X convergence:Ultra-reliable low-latency communication is enabling teleoperation fallback modes that reduce the sensor payload required for full autonomy.
- Quarry-to-construction diversification:Articulated dump truck OEMs are adapting autonomous navigation stacks for urban infrastructure projects with narrower haul corridors.
Industry Challenges
- Autonomous systems integration talent:Mining operators face acute shortages of embedded software engineers capable of calibrating machine-learning path planners to site-specific geologies.
- Legacy fleet interoperability:Mixed autonomous-manual haulage operations require communication protocol bridges that increase integration complexity and downtime risk.
- ISO 17757 compliance timelines:Autonomous machine safety standards demand extensive field validation that delays commercial deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Driving Dumpers Machine Market |
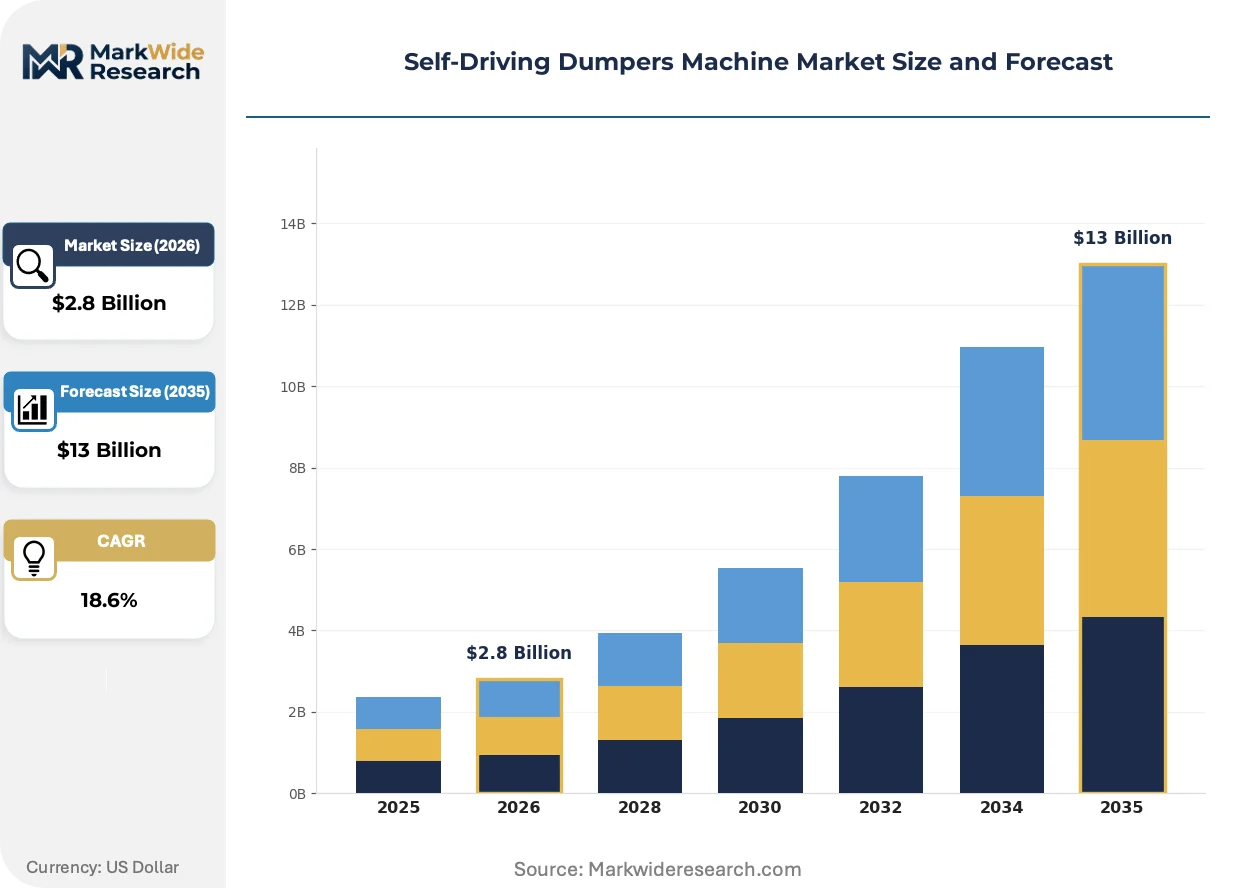
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Dump Trucks, Rigid Dump Trucks, Mini Dumpers, Others Technology: Autonomous Navigation, Obstacle Detection, Remote Control, Telemetry Systems Industry Vertical: Construction, Mining, Agriculture, Waste Management End User: Contractors, Mining Companies, Agricultural Producers, Municipalities |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, XCMG Group, Hitachi Construction Machinery Co., Ltd., Liebherr Group, SANY Group, Deere & Company, CNH Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Driving Dumpers Machine Market Emerging Trajectories
Autonomous earthmoving is undergoing a platform consolidation phase where modular perception stacks are displacing vertically integrated sensor suites. Equipment manufacturers are rearchitecting control systems around open software frameworks that accelerate third-party algorithm integration.
Perception hardware is fragmenting as solid-state LiDAR arrays and 4D imaging radar converge into redundant sensor configurations. Tier-1 suppliers are shipping pre-validated environmental sensing modules that reduce OEM development overhead. Mining fleet operators are adopting these modular platforms to decouple hardware refresh cycles from autonomy software updates.
The EU AI Act's risk-classification framework is mandating formal verification of autonomous decision pathways in earthmoving equipment. CE marking authorities are requiring documented safety case architectures that trace sensor inputs to emergency-stop actuation. European quarry operators are prioritizing OEMs with established conformity assessment partnerships to compress certification timelines.
Contract structures are rotating from equipment ownership toward availability-based performance agreements. Mining companies are unbundling autonomous fleet management from capital procurement, shifting operational risk to OEM service arms. Australia's iron ore producers are piloting tonne-kilometer pricing models that align vendor incentives with haulage efficiency outcomes.
Self-Driving Dumpers Machine Market Segmentation
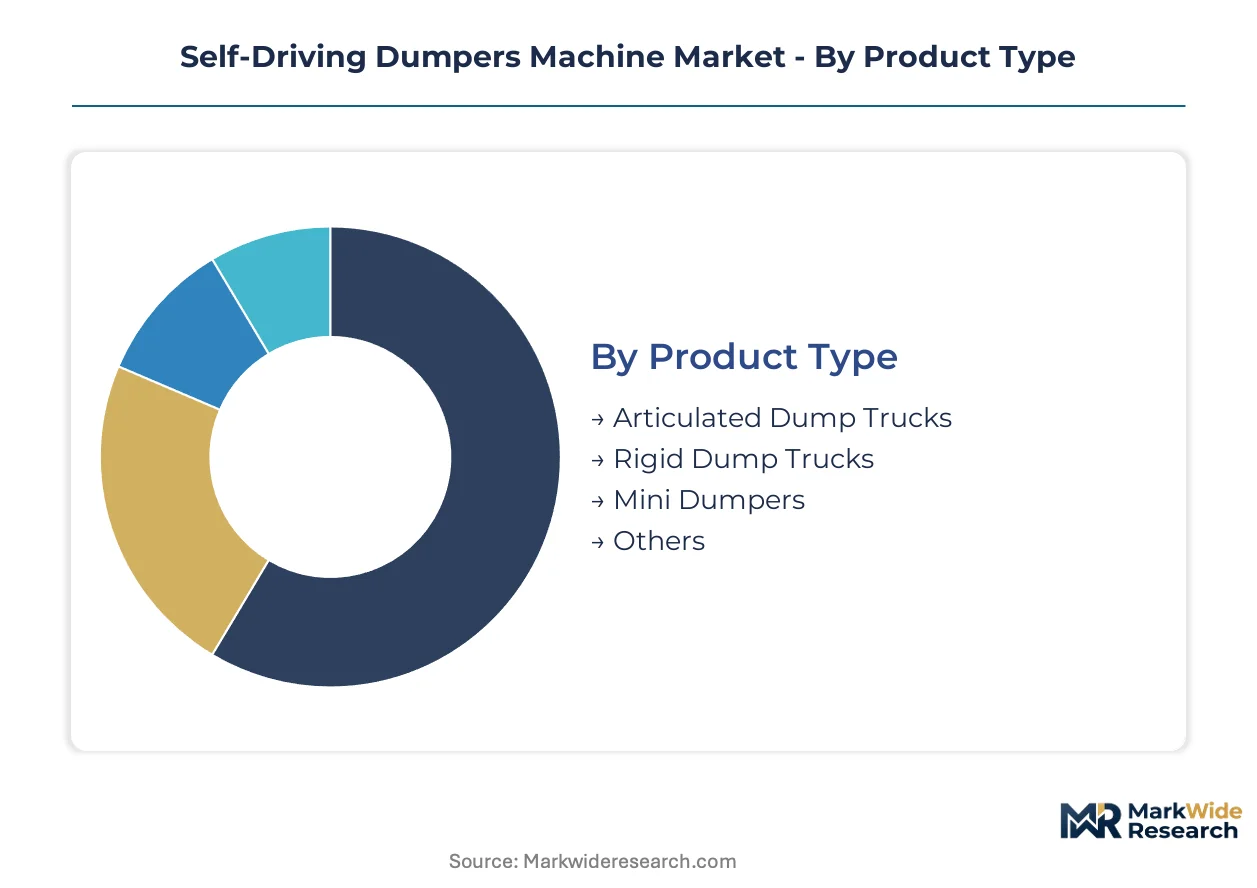
Segmentation in self-driving dumpers reveals how technology maturity, payload scale, and operational environment dictate procurement patterns. Mining operators prioritize ultra-class rigid configurations, while quarry contractors favor maneuverable articulated chassis. Understanding these segment boundaries clarifies why sensor payload requirements and autonomy software licensing vary dramatically across buyer archetypes.
Product Type:
Channel mix varies sharply: mining fleet operators source rigid dump trucks through direct OEM procurement with embedded service contracts, while articulated units flow through dealer networks serving construction contractors.
- Articulated Dump Trucks:Hinged chassis designs enable tight turning radii in confined quarry haul corridors. Demand concentrates in European aggregate operations and North American infrastructure projects where maneuverability outweighs payload maximization. Site managers prioritize these units for multi-directional dumping flexibility in space-constrained environments.
- Rigid Dump Trucks:Fixed-frame ultra-class configurations exceed 400-ton payload capacity with reinforced suspension for high-cycle mining operations. Australia's Pilbara iron ore producers specify these units exclusively for autonomous haulage fleets, driving sensor integration standardization across the category.
- Mini Dumpers:Compact electric-powered units serve urban construction and landscaping contractors requiring pedestrian-zone operation clearance.
- Others:Specialized underground mining carriers and amphibious transport variants address niche extraction environments.
By volume, Articulated Dump Trucks lead. By growth pace, Rigid Dump Trucks are climbing the fastest as autonomous retrofit programs accelerate in surface mining.
Technology:
Cost tier stratification separates premium autonomous navigation stacks from standardized telemetry modules, with obstacle detection occupying the mid-tier positioning for safety-critical retrofit applications.
- Autonomous Navigation:Machine-learning path planners process LiDAR-GNSS fusion data for collision-free haul routing without continuous operator oversight. Mining companies in Australia's Pilbara corridor deploy these systems at scale, validating sub-second terrain processing for 24/7 operations.
- Obstacle Detection:Radar and camera arrays provide emergency-stop capabilities that satisfy MSHA mandates for mixed autonomous-manual fleet environments. Quarry operators specify these systems as minimum viable autonomy for labor-constrained sites not ready for full navigation deployment.
- Remote Control:Teleoperation fallback modes leverage 5G-V2X connectivity for human intervention in complex loading scenarios.
- Telemetry Systems:Fleet management platforms transmit equipment health and location data to centralized dispatch centers.
By installed base, Telemetry Systems dominates. By expansion trajectory, Autonomous Navigation is gaining share fastest as OEMs bundle path-planning software with new equipment sales.
Industry Vertical:
Application intensity determines sensor redundancy requirements, with mining demanding full autonomous navigation and construction settling for obstacle detection with teleoperation backup.
- Construction:Earthmoving contractors deploy self-driving dumpers for repetitive material transport between excavation and processing sites. Urban infrastructure projects in Germany and Japan specify compact articulated units with CE-marked autonomous navigation for tunneling and roadbuilding applications.
- Mining:Surface and underground extraction operations eliminate continuous cab occupancy through autonomous haulage architectures. Rio Tinto and BHP in Australia's Pilbara region have validated decade-long deployments, generating operational datasets that reduce adoption risk for follower operators.
- Agriculture:Large-scale grain and sugarcane producers pilot autonomous transport for field-to-silo logistics.
- Waste Management:Landfill operators test teleoperated dumpers for hazardous material handling in contaminated zones.
By equipment value, Mining leads. By adoption velocity, Construction is expanding most quickly as quarry-to-infrastructure diversification accelerates.
End User:
Customer type shapes contract structure: mining companies negotiate availability-based performance agreements, while contractors favor equipment ownership with software subscription tiers.
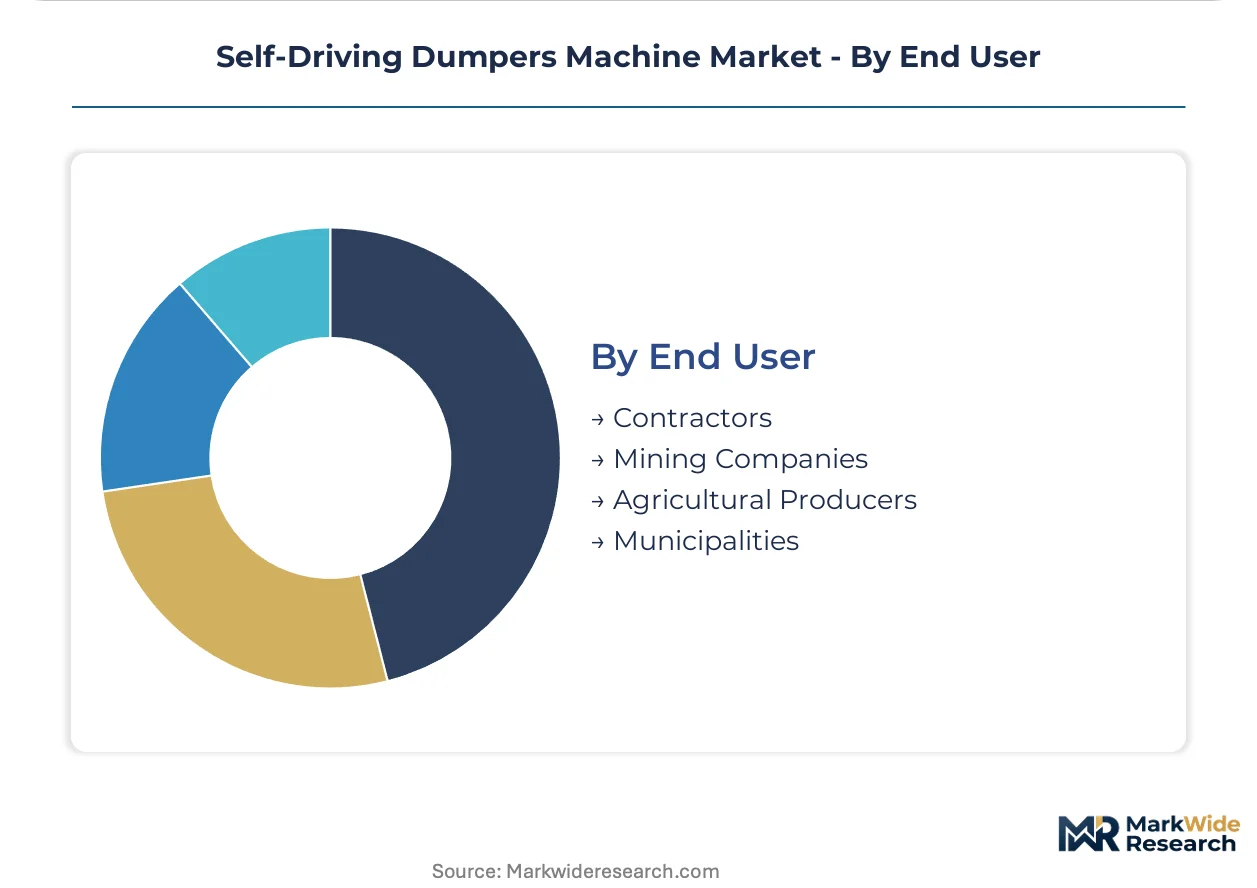
- Mining Companies:Integrated fleet operators specify autonomous haulage systems as capital projects with decade-long operational horizons. BHP and Vale negotiate tonne-kilometer pricing models that align OEM service incentives with haulage efficiency outcomes across Brazilian and Australian operations.
- Contractors:Construction and earthmoving firms procure articulated dump trucks through dealer finance arrangements with modular autonomy upgrades. European quarry contractors prioritize CE-marked platforms to compress Machinery Directive certification timelines.
- Agricultural Producers:Cooperative farming operations evaluate autonomous mini dumpers for seasonal harvest logistics.
- Municipalities:Public works departments pilot teleoperated units for snow removal and road maintenance applications.
By fleet size, Mining Companies lead. By procurement activity growth, Contractors are ahead as labor shortages force fleet modernization across earthmoving segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy-haul rail network underwrites Australia's dominance in autonomous earthmoving validation, while China's Belt and Road port infrastructure accelerates mining equipment deployment across resource corridors.
Australia
Rio Tinto and BHP operate the world's largest autonomous haulage fleets in Western Australia's Pilbara region, generating decade-long operational datasets that reduce adoption risk for follower operators. The country's Work Health and Safety Act mandates collision-avoidance system certification for autonomous mobile plant. Perth serves as the engineering hub where OEMs co-locate autonomy software development teams with mining operator headquarters.
China
Coal India and domestic surface mining operators drive fleet modernization demand under MIIT GB standards for intelligent connected vehicles extending to mining-sector equipment. The country's dual carbon goals accelerate electric autonomous dumper deployment in Inner Mongolia coal basins. Xuzhou anchors manufacturing concentration where state-owned construction equipment groups integrate autonomous navigation stacks with domestic LiDAR supply chains.
United States
Copper and aggregates producers in Arizona and Nevada deploy autonomous haulage to offset MSHA-documented operator shortages in surface mining operations. The Mine Safety and Health Administration enforces collision-avoidance mandates shaping sensor redundancy requirements for emergency-stop architectures. Tucson clusters autonomous mining technology development where Caterpillar maintains its proving grounds for ultra-class rigid dump truck validation.
Germany
Quarry operators in the North Rhine-Westphalia limestone belt specify CE-marked articulated dump trucks with autonomous navigation for tunneling and roadbuilding applications. The EU Machinery Directive and EU AI Act impose functional safety certification thresholds that filter non-integrated subsystem suppliers from market access. Munich hosts conformity assessment partnerships where OEMs compress Machinery Directive validation timelines through pre-certified modular perception platforms.
India
Coal India and captive mining blocks modernize truck fleets under PLI scheme incentives for domestic manufacturing of autonomous components. The country's Bureau of Indian Standards develops technical baselines for intelligent mining equipment safety verification. Jharkhand's coal belt concentrates pilot deployments where state-owned miners test teleoperation fallback modes in mixed autonomous-manual haulage environments.
Self-Driving Dumpers Machine Market Vendor Landscape
Concentration sits with diversified construction equipment conglomerates possessing integrated autonomy software stacks and decade-long mining operator relationships. The vendor base spans three tiers: ultra-class rigid dump truck specialists serving Pilbara-scale deployments, articulated chassis fabricators targeting European quarry markets, and emerging Chinese state-owned groups leveraging domestic sensor supply chains. Strategic moves center on availability-based performance contracting that shifts operational risk from mining companies to OEM service arms, plus modular perception platform partnerships that decouple hardware refresh cycles from software update roadmaps.
Within the diversified conglomerate tier, Caterpillar Inc. and Komatsu Ltd. exemplify archetypes anchored by autonomous haulage heritage and integrated fleet management platforms respectively. Volvo Construction Equipment occupies a position representing articulated chassis expertise adapted for narrower quarry environments. XCMG Group and SANY Group sit within the state-owned Chinese manufacturer archetype, leveraging domestic GB standards alignment and Belt and Road corridor access. Hitachi Construction Machinery Co., Ltd. and Liebherr Group represent mid-tier specialists where regional mining relationships and CE marking conformity partnerships differentiate positioning in European and Asian quarry markets.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| XCMG Group |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr Group |
| SANY Group |
| Deere & Company |
| CNH Industrial |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR substitution for mechanical scanning arrays is redrawing procurement geography toward East Asian contract manufacturers while compressing sensor cost curves for OEM autonomy stacks. This input transition simultaneously concentrates supply leverage in Shenzhen and Seoul fabrication hubs and erodes pricing premiums previously attached to Western-sourced perception hardware.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with mining fleet operators commanding 15-25% unit cost reductions at 50+ vehicle deployment scales against quarry contractor single-digit purchases. Price differentiation rests on CE marking certification grade and embedded service contract duration, with EU AI Act-compliant platforms capturing premium positioning. Pricing pressure intensifies in the articulated chassis segment as Chinese state-owned manufacturers undercut European OEMs on comparable payload specifications. Mining companies exhibit lowest price sensitivity due to availability-based contracting that shifts operational risk to vendor service arms, while independent construction contractors face acute margin compression that amplifies procurement negotiation leverage.
Supply Chain Analysis
Strait of Malacca transit congestion threatens just-in-time delivery schedules for rare-earth magnet shipments feeding permanent-motor production for electric dumper powertrains. Component sourcing concentrates in China, South Korea, and Germany, with LiDAR sensor fabrication anchored in Shenzhen contract manufacturers, precision gearing in Stuttgart industrial clusters, and battery cell production in Gwangju chemical parks. Raw material dependencies span neodymium-dysprosium magnet alloys, high-grade steel plate for rigid chassis stamping, and silicon carbide wafers for traction inverters. Single-source vulnerability pervades solid-state LiDAR emitter supply where qualification timelines lock OEMs into 18-month supplier commitments. Distribution runs through direct OEM procurement channels for mining fleet operators and authorized dealer networks serving fragmented construction contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as mining fleet operators consolidate procurement decisions across multi-site haulage operations, compressing vendor count from six OEM relationships to two preferred platform partners per major iron ore producer.
For Market Incumbents: Compound autonomous haulage heritage advantages by embedding machine-learning path planners into decade-long service contracts that raise switching costs for Pilbara-scale operators. Defensive consolidation demands backward integration into LiDAR sensor qualification pipelines to circumvent East Asian contract manufacturer bottlenecks, while CE marking pre-certification investments filter emerging Chinese competitors from European quarry access. Threat substitution from teleoperation-as-a-service platforms requires counter-positioning through 5G-V2X latency guarantees that full autonomy stacks uniquely deliver. For New Entrants and Emerging Players: CE marking fast-track partnerships with Munich conformity assessment bodies unlock white-space penetration in German limestone quarry corridors where incumbent lead times extend 24 months. India's PLI scheme incentives for domestic autonomous component manufacturing present the most penetrable geography, with Coal India fleet modernization tenders specifying local content thresholds that disadvantage established import-dependent vendors. Go-to-market execution should anchor on teleoperation fallback mode pilots that reduce upfront sensor payload requirements and accelerate site acceptance protocols. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated autonomy software stacks over modular hardware suppliers. Long-term viability across the projection horizon rests on OEMs possessing both decade-long mining operator relationships and embedded fleet management platform installed bases. Acquisition target archetypes include articulated chassis specialists with CE marking conformity partnerships and proven narrow-corridor navigation algorithms. Signal to watch: tonne-kilometer pricing contract penetration rates in Australian iron ore operations as inflection indicator for availability-based business model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Availability-Based Performance Contracting | Tonne-kilometer pricing aligns OEM incentives with BHP haulage efficiency outcomes across Pilbara operations. |
| Modular Perception Platform Partnerships | Pre-validated LiDAR-GNSS modules decouple hardware refresh cycles from autonomy software update roadmaps. |
| CE Marking Conformity Investment | EU AI Act safety case architectures filter non-integrated subsystem suppliers from European quarry market access. |
| 5G-V2X Teleoperation Integration | Ultra-reliable low-latency connectivity enables fallback modes that reduce full-autonomy sensor payload requirements. |
| Backward Integration into LiDAR Supply | Captive emitter qualification pipelines circumvent East Asian contract manufacturer single-source vulnerability. |
Methodological Framework
Desk research of OEM technical documentation, MSHA incident databases, and EU Machinery Directive conformity assessment records preceded structured interviews with mining fleet operations directors, autonomous systems integration engineers, quarry site managers, and construction equipment procurement leads. Primary fieldwork combined telephone consultations and on-site observation at Western Australian Pilbara haulage corridors with secondary validation against SEC 10-K equipment segment disclosures, customs trade data for autonomous vehicle component flows, and industry association production statistics. Bottom-up unit shipment estimates triangulated against top-down fleet modernization capex allocations reported by major mining operators.
Variance decomposition across product type, technology tier, industry vertical, and end-user category shaped the analytical framework, with segment-level growth trajectories modeled throughout the forecast period. CAGRs derived from logistic adoption curve fitting calibrated against decade-long autonomous haulage deployment histories in Australian iron ore operations. Industry-specific forecast inputs incorporated labor shortage severity indices by mining jurisdiction, LiDAR sensor cost curve projections, and EU AI Act implementation timeline assumptions for conformity assessment capacity constraints.
Decision-makers should treat outputs as directional under sustained mining sector labor shortage assumptions and stable East Asian sensor supply availability; material deviation in either would warrant model refresh. Forecasts reflect base-case autonomous navigation adoption velocity without regulatory acceleration or technology disruption scenarios. Practitioners should keep alternative scenarios live as EU Machinery Directive certification timeline delays and rare-earth magnet supply restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Water Sprinkler Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Foundry Sand Cleaning Machine Market