
 Water Sprinkler Market | 2026-2036
Water Sprinkler Market Size, Share, and Industry Trends Forecast 2026-2036
Water Sprinkler Market Analytics
Commercial landscaping contractors is rotating toward precision irrigation systems as municipal water budgets tighten across drought-prone states. Rain Bird Corporation leverages its dominance in smart controller technology to capture specification-driven projects. Hunter Industries anchors the golf course segment with specialized gear-drive rotors engineered for uniform distribution. Jain Irrigation Systems competes through backward integration into drip-line manufacturing and polymer compounding.
A water sprinkler is a pressurized distribution device engineered to discharge water through nozzles at controlled flow rates, typically operating between 30 and 50 psi for residential units and up to 100 psi for agricultural systems, designed to simulate rainfall patterns across targeted zones for vegetation maintenance or crop production. Rotary sprinklers lead commercial and agricultural installations due to their throw radius adaptability and wind resistance, while smart control systems represent the fastest-expanding margin pool as connectivity modules and soil-moisture sensors command premium pricing over timer-based alternatives. Fixed spray heads occupy mature residential retrofit channels where price sensitivity limits technology upgrade rates.
EPA WaterSense and the EU Ecodesign Directive shape product certification requirements, forcing manufacturers to document flow efficiency and seasonal performance metrics before market entry. California's Model Water Efficient Landscape Ordinance and Australia's WELS rating scheme extend this compliance burden into sub-national procurement specifications. Stakeholders must monitor evolving groundwater withdrawal permits and tiered water pricing structures that directly alter return-on-investment calculations for automated system upgrades.
Market Dynamics
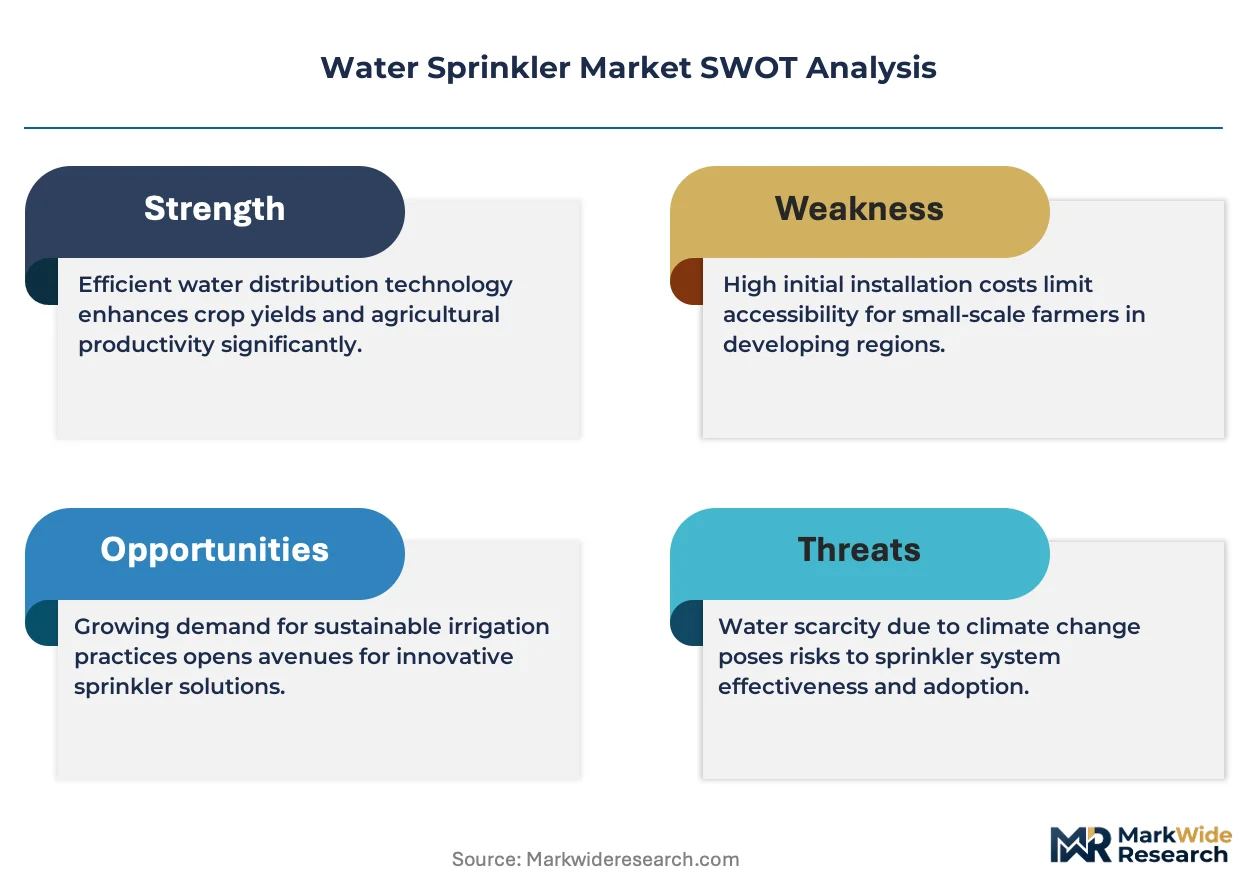
EPA WaterSense flow-rate standards are compressing specification windows for outdoor equipment manufacturers while California's municipal conservation programs accelerate replacement cycles. This regulatory tightening intersects with smart controller adoption curves to reshape competitive positioning.
Growth Catalysts
- Smart controller penetration:Soil-moisture sensors and connectivity modules command premium pricing over timer-based systems in commercial landscaping procurement.
- California Model Water Efficient Landscape Ordinance:Municipal water budgets in drought-prone states mandate precision irrigation retrofits for public spaces and agricultural corridors.
- Agricultural water stress:Groundwater withdrawal permits in the Central Valley tier pricing structures that favor automated system upgrades for crop production efficiency.
Market Restraints
- Polymer input volatility:Drip-line manufacturing depends on polyethylene resin pricing subject to petrochemical supply fluctuations.
- Specification lock-in:Gear-drive rotor installations in golf course maintenance create multi-year replacement cycles resistant to technology migration.
- Residential price sensitivity:Fixed spray head retrofits in mature housing stock face budget constraints that limit smart system adoption rates.
Strategic Opportunities
- EU Ecodesign Directive expansion:Flow efficiency documentation requirements create certification barriers that favor established manufacturers with testing infrastructure.
- Commercial IoT convergence:Building management system integration allows irrigation networks to synchronize with HVAC and lighting controls for unified facility optimization.
- Australia WELS rating scheme:Sub-national procurement specifications in water-stressed regions open specification-driven project channels for certified equipment.
Industry Challenges
- Field technician training gaps:Smart system diagnostics require fluency in wireless protocol troubleshooting and sensor calibration beyond traditional irrigation skill sets.
- Legacy timer integration:Hybrid installations combining new controllers with existing valve networks create commissioning complexity and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Sprinkler Market |
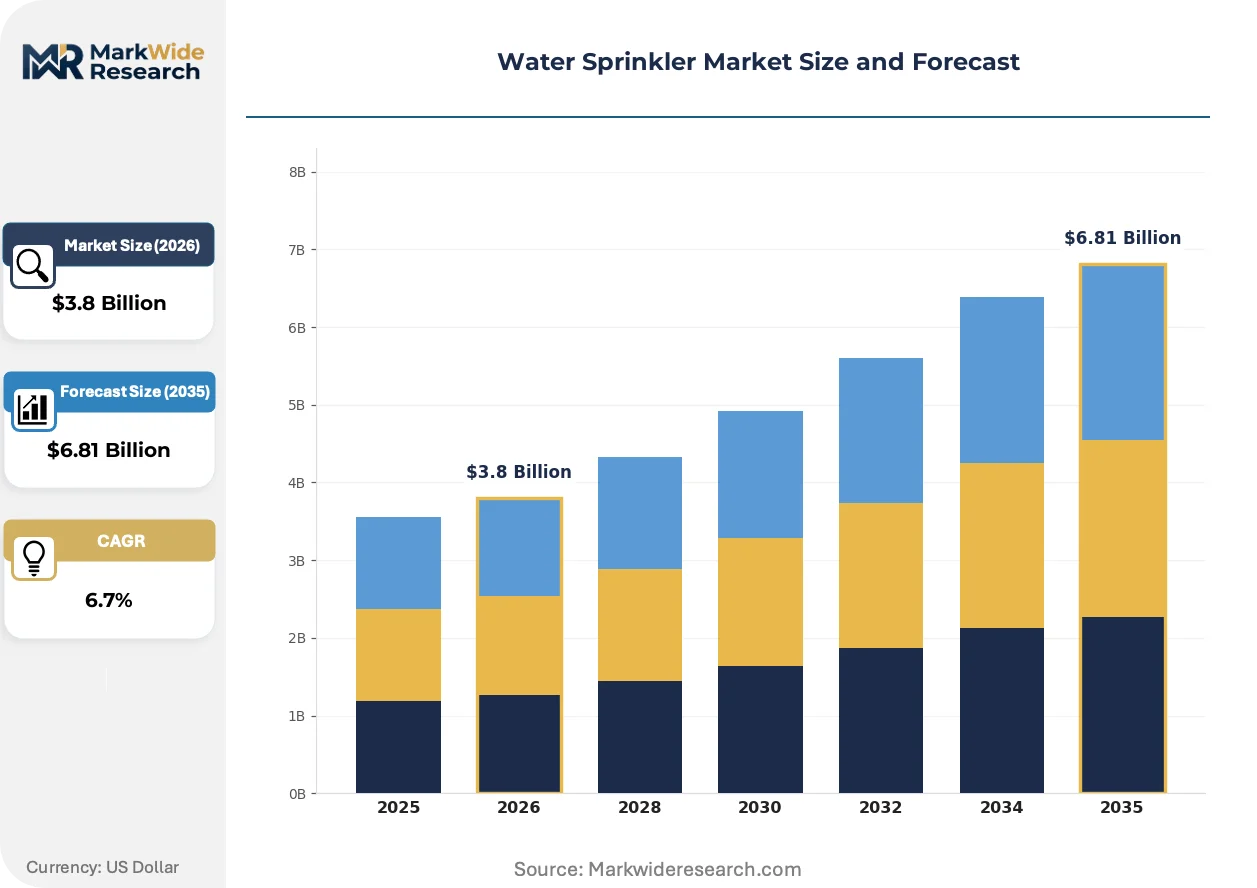
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Fixed, Oscillating, Soaker Application: Agricultural Irrigation, Residential Lawns, Golf Courses, Parks Installation Type: In-ground, Above-ground, Portable, Temporary Control Method: Manual, Electric, Timer-based, Smart Systems |
| Companies Covered | Rain Bird Corporation, The Toro Company, Hunter Industries, Lindsay Corporation, Netafim, Valmont Industries, Jain Irrigation Systems, Nelson Irrigation, T-L Irrigation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Sprinkler Market Evolving Landscape
Connectivity modules and sensor networks are transforming irrigation from scheduled watering to responsive resource management. Equipment specification increasingly hinges on data integration capabilities rather than mechanical performance alone.
Soil-moisture sensing technology with cloud-based analytics is displacing timer-based scheduling in commercial and agricultural installations. Large-scale landscaping contractors and farming cooperatives are adopting these systems at accelerated rates to comply with municipal water budgets and groundwater permits. This shift is displacing mechanical timer inventory from distributor shelves and compressing margins on non-connected controller alternatives.
EPA WaterSense certification requirements are tightening flow-rate documentation standards for outdoor equipment sold in the United States. Manufacturers must now submit seasonal performance metrics and third-party testing data before market entry authorization. Agricultural system suppliers serving California's Central Valley face the steepest compliance burden as Model Water Efficient Landscape Ordinance enforcement intensifies.
Commercial buyers are consolidating vendor relationships around full-system providers capable of supplying controllers, valves, and sensor networks under unified specification. Single-source procurement is replacing component-level purchasing in municipal water conservation programs and golf course maintenance contracts. This concentration is most visible in California and Texas where drought-response funding streams favor turnkey installation contracts over equipment-only sales.
Water Sprinkler Market Segmentation
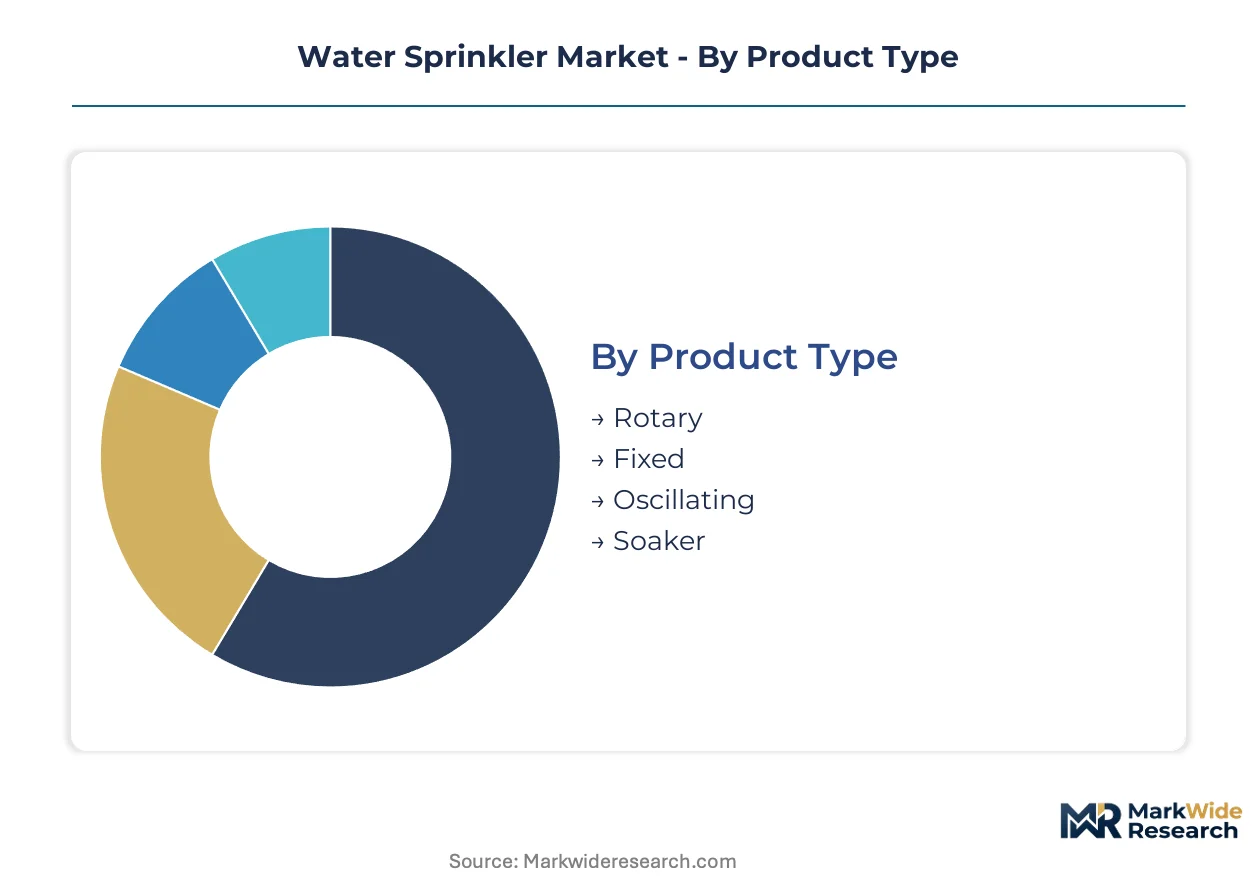
Product architecture in the water sprinkler market determines specification pathways and margin capture. Segmentation reveals where smart technology premiums concentrate versus where price competition dominates replacement cycles.
Product Type:
Margin pools sit heaviest in rotary and smart-enabled categories where engineering complexity sustains pricing power against commodity alternatives.
- Rotary:Gear-drive rotors deliver adjustable throw radii from 15 to 100 feet with wind-resistant stream diffusion. Demand clusters in California Central Valley agricultural corridors and Texas municipal parks where uniform distribution reduces water waste under tiered pricing structures.
- Fixed:Pop-up spray heads operate at 30 psi with fixed-pattern nozzles for residential lawn coverage. Specification concentrates in mature suburban retrofit channels across Florida and Arizona where price sensitivity limits technology migration.
- Oscillating:Rectangular-pattern sprinklers with tube-and-nozzle bars serve temporary residential applications.
- Soaker:Porous hose systems discharge water directly at soil level for garden bed and shrub zone irrigation.
The dominant share belongs to Rotary, while Smart Systems integration is pushing Fixed spray heads toward connected retrofit upgrades fastest.
Application:
Volume flows differentiate sharply between production agriculture and amenity landscaping, with regulatory pressure reshaping procurement priorities.
- Agricultural Irrigation:Center-pivot and lateral-move systems serve row-crop production across California's Central Valley and Texas High Plains. Groundwater withdrawal permits and tiered water pricing favor automated precision upgrades that reduce per-acre consumption.
- Residential Lawns:Post-construction installation and retrofit replacement dominate suburban markets in Phoenix, Las Vegas, and Orlando where HOA landscaping mandates sustain maintenance spending.
- Golf Courses:Specialized gear-drive rotors with uniform distribution patterns maintain playing surfaces under intense scrutiny.
- Parks:Municipal procurement through water conservation programs specifies EPA WaterSense-certified equipment.
Agricultural Irrigation commands the largest installed base, though Golf Courses are adopting precision soil-moisture systems most aggressively.
Installation Type:
Capital intensity and labor specialization separate permanent infrastructure from seasonal deployment models.
- In-ground:PVC riser and valve systems buried 8-12 inches deliver permanent coverage for commercial and high-end residential properties. Specification concentrates in new California commercial developments subject to Model Water Efficient Landscape Ordinance compliance.
- Above-ground:Hose-connected units on sled bases or tripods serve rental properties and seasonal users.
- Portable:Lightweight wheeled systems relocate across fields for temporary crop irrigation.
- Temporary:Quick-connect solutions deploy for construction site dust suppression and event landscaping.
In-ground systems retain the dominant share, while Portable units are gaining traction fastest in rental agriculture and construction adjacencies.
Control Method:
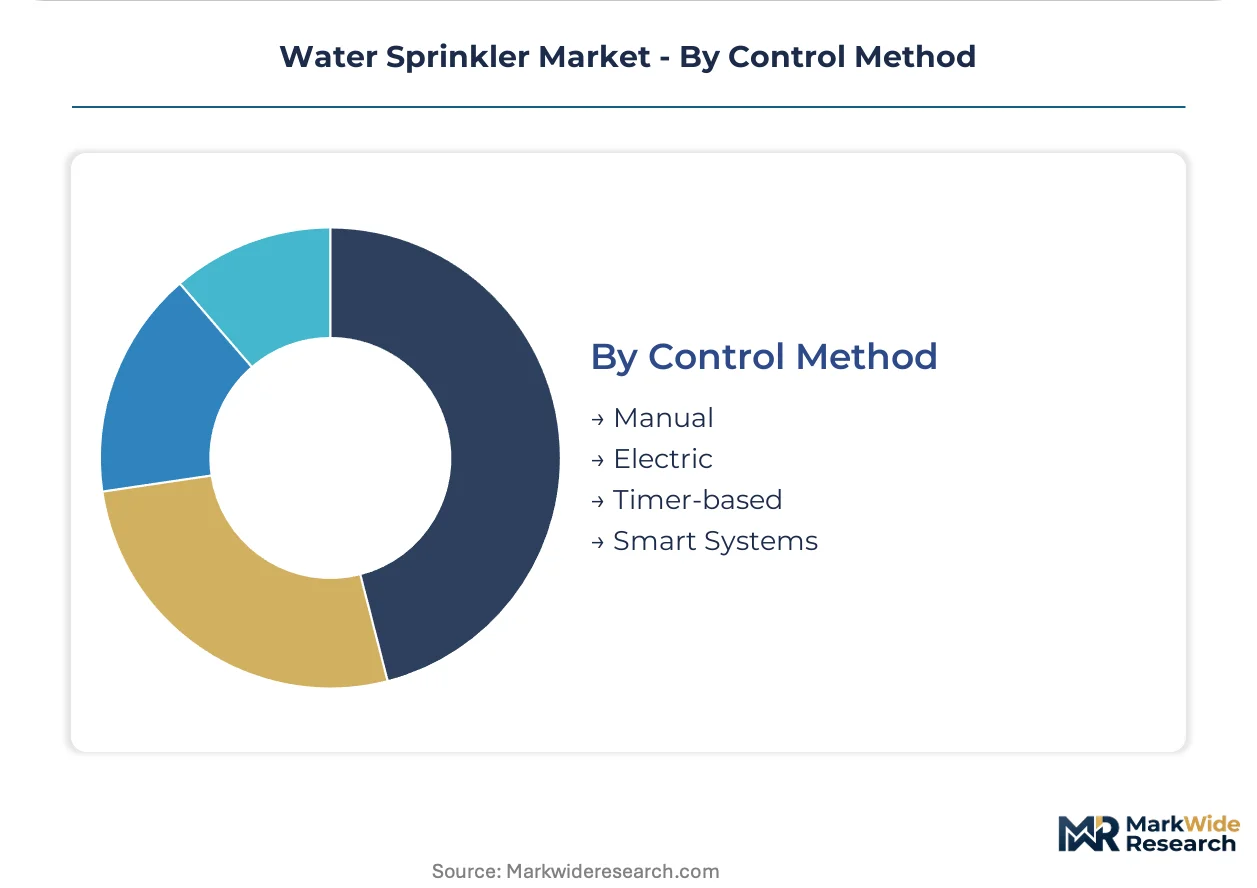
Technology tiering separates premium connectivity from mechanical scheduling, with regulatory certification creating specification gates.
- Smart Systems:Wi-Fi-enabled controllers integrate soil-moisture sensors and weather data APIs for responsive scheduling. Demand concentrates in California municipal water conservation programs and commercial landscaping contracts where EPA WaterSense certification qualifies for rebate funding.
- Timer-based:Electromechanical and digital timers execute fixed schedules without environmental feedback.
- Electric:Basic solenoid valve activation through simple switches.
- Manual:Hand-operated valves for isolated zone control in small-scale applications.
Timer-based controllers still dominate unit volume, though Smart Systems are climbing the fastest as connectivity modules displace mechanical inventory from distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States, Germany, and China where precision irrigation engineering and polymer processing infrastructure overlap. Distribution networks radiate from these hubs into water-stressed agricultural corridors and municipal conservation programs.
United States
EPA WaterSense certification mandates tighten flow-rate documentation for outdoor equipment entering the market. California's Model Water Efficient Landscape Ordinance enforces precision irrigation retrofits in public spaces. The Central Valley agricultural corridor drives demand for center-pivot and lateral-move systems under tiered groundwater pricing.
Germany
Commercial landscaping contractors specify smart-controlled systems for municipal parks and corporate campuses. The EU Ecodesign Directive requires seasonal performance metrics and third-party testing data before market authorization. Bavaria's precision agriculture clusters adopt soil-moisture sensing technology for row-crop production efficiency.
China
MIIT standards for agricultural mechanization accelerate automated irrigation deployment across the North China Plain. NMPA-equivalent agricultural equipment certification focuses on water efficiency in drought-prone provinces. The Yangtze River Delta concentrates manufacturing of polymer components for drip-line systems.
Australia
The WELS rating scheme creates procurement gates for water-efficient equipment in municipal and agricultural channels. State-level groundwater withdrawal permits in the Murray-Darling Basin favor precision system upgrades. Queensland's sugar cane and cotton belts represent concentrated demand for large-scale lateral-move installations.
India
PLI scheme incentives for agricultural machinery support domestic manufacturing of micro-irrigation components. BIS certification requirements for polymer-based irrigation equipment tighten quality standards for market entry. Maharashtra's sugar belt and Gujarat's cotton regions drive adoption of drip and sprinkler systems under state water conservation mandates.
Water Sprinkler Market Competitive Landscape
Concentration sits with diversified irrigation equipment conglomerates that span residential, commercial, and agricultural segments. The vendor base separates into three strategic tiers: full-system providers capable of unified specification, component specialists focused on polymer manufacturing, and regional assemblers serving price-sensitive retrofit channels. Competitive moves center on backward integration into drip-line manufacturing and certification-driven specification capture in municipal procurement programs.
Among North American full-system providers, Rain Bird Corporation and The Toro Company represent the premium-tier archetype with integrated controller and valve portfolios. Lindsay Corporation exemplifies the agricultural-scale specialist position with center-pivot manufacturing concentration. Jain Irrigation Systems anchors the backward-integrated archetype through captive polymer compounding and drip-line production capabilities.
| Leading Market Players |
|---|
| Rain Bird Corporation |
| The Toro Company |
| Hunter Industries |
| Lindsay Corporation |
| Netafim |
| Valmont Industries |
| Jain Irrigation Systems |
| Nelson Irrigation |
| T-L Irrigation |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for polyethylene resin lock in supply access and price visibility for drip-line manufacturers serving California's Central Valley agricultural corridor, insulating procurement teams from petrochemical spot-market volatility while compressing margin flexibility for non-integrated competitors.
Pricing Analysis
EPA WaterSense dictates the pricing tier structure across the United States, separating certified smart controllers from non-compliant timer-based alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and connectivity integration, with premium tiers commanding substantial markups for soil-moisture sensing modules. Cost compression in economy fixed-spray segments is intensifying because residential retrofit channels face budget constraints that resist technology migration. Municipal procurement programs exhibit the least price sensitivity, while mature suburban homeowners in Florida and Arizona represent the most price-constrained segment.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Los Angeles trade lane periodically disrupt inbound logistics costs for polymer compounding equipment and specialized nozzle assemblies. Manufacturing gravity centers on the United States, Germany, and China where precision molding infrastructure and controller electronics ecosystems overlap. Raw material dependencies draw from polyethylene resin, brass alloys for gear-drive components, and semiconductor chips for connectivity modules. Single-source vulnerability concentrates in advanced soil-moisture sensor arrays sourced from limited Asian suppliers. Distribution runs through irrigation distributors and commercial landscaping contractor networks into municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring revenue from cloud-based analytics subscriptions and sensor calibration contracts expands faster than hardware unit sales, rewarding vendors that bundle connectivity with ongoing field support.
For Market Incumbents: Compound specification capture in municipal water conservation programs by deepening backward integration into polymer compounding and sensor manufacturing. Anchor defensive positioning through EPA WaterSense certification maintenance and exclusive distribution agreements with California commercial landscaping contractors. Prioritize field technician training infrastructure to offset smart-system diagnostic complexity that threatens warranty exposure.
For New Entrants and Emerging Players: Remote sensor calibration services represent a service-layer gap where incumbents under-serve agricultural cooperatives lacking in-house wireless protocol expertise. Target portable irrigation equipment for rental agriculture and construction dust suppression adjacencies where specification barriers remain lowest. Pursue direct-to-farmer digital sales channels bypassing traditional distributor relationships in water-stressed Indian states.
For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated manufacturers with captive polymer supply and established certification infrastructure across multiple regulatory regimes. Long-term viability hinges on exposure to municipal procurement cycles rather than residential retrofit volatility. Monitor tiered groundwater pricing policy announcements in California and Texas as the critical inflection signal for precision upgrade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin pressure from petrochemical volatility in drip-line manufacturing. |
| EPA WaterSense Certification Investment | Unlocks municipal rebate funding streams and specification-driven procurement in drought-prone states. |
| Cloud-Based Analytics Platform Launch | Transforms hardware vendors into recurring-revenue service providers with soil-moisture data subscriptions. |
| Field Technician Training Infrastructure | Addresses diagnostic skill gaps in wireless protocol troubleshooting that threaten smart-system warranty costs. |
| Geographic Expansion into Australian WELS Channels | Accesses sub-national procurement specifications in the Murray-Darling Basin groundwater management zones. |
Research Methodology
Initial hypotheses were tested against primary input from commercial landscaping contractors, agricultural irrigation managers, municipal water conservation officers, and polymer supply procurement leads, then refined through secondary validation against EPA WaterSense certification databases, California Department of Water Resources conservation program filings, and customs records for irrigation equipment imports. Bottom-up unit economics from distributor channel checks were triangulated against top-down market sizing from regulatory mandate coverage expansion.
Variance decomposition across product type, application, control method, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling against tiered water pricing trajectories and municipal budget allocation patterns. Forecast inputs incorporated smart controller adoption curves, drip-line replacement cycles in California agriculture, and golf course maintenance contract renewal timing.
Forecasts assume regulatory continuity in EPA WaterSense and EU Ecodesign Directive regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mill Pulverizer Market
Construction Equipment
Amphibious Excavator Market
Construction Equipment
Shield Machines Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Road Roller Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Mini Excavators Market
Construction Equipment
North America and Europe Snow Blowers Market