
 Global Seam Welding Machine Market | 2026-2036
Global Seam Welding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seam Welding Machine Market Intelligence
Demand from heavy equipment producers for robust, high-integrity welds is consolidating the market around specialized, high-power machinery. This shift benefits established suppliers capable of delivering durable systems for thick materials. Miller Weldmaster leverages its expertise in automated solutions for industrial fabrics and heavy-duty applications. ESAB, a major industrial player, competes on the breadth of its welding and cutting portfolio across multiple end-user segments.
A seam welding machine creates a continuous, leak-proof weld by passing a workpiece between two rotating electrode wheels. This process forms a series of overlapping spot welds, or nuggets, to produce a fluid-tight or gas-tight seam. While traditional resistance seam welders remain dominant in applications like cylindrical tank fabrication, laser seam welders are gaining share. The precision of fiber laser technology is particularly valued in high-specification automotive component assembly.
Machine safety and operator protection standards heavily influence equipment design and market access. Compliance with regulations such as OSHA guidelines in the United States and the CE marking directive in Europe is mandatory. In China, adherence to GB standards for industrial machinery is essential for all manufacturers. Ultimately, vendor selection will hinge on balancing the total cost of ownership against the need for automation and compliance with evolving safety protocols.
Market Dynamics
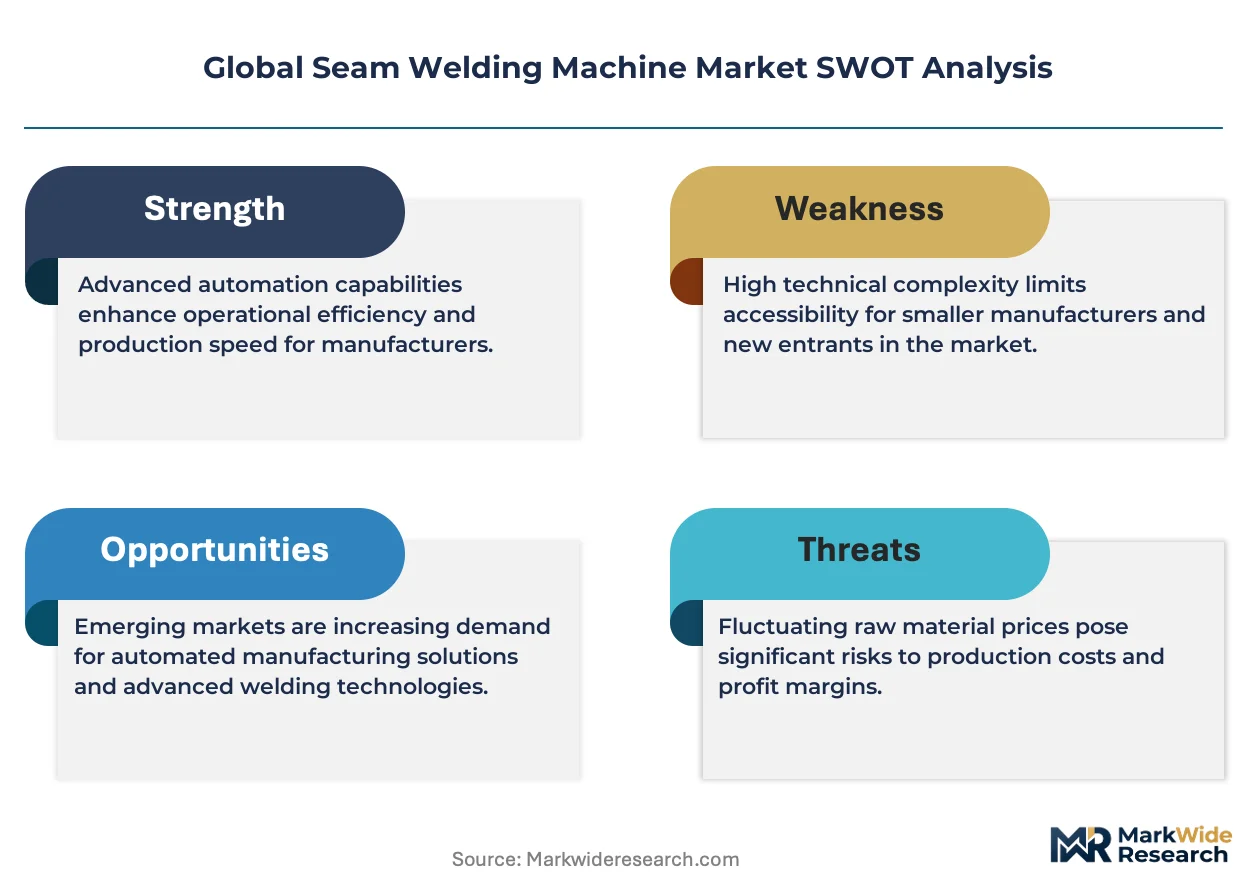
The central tension in the seam welding machine market is the technological and economic trade-off between established resistance welding and advanced fiber laser systems. This dynamic forces buyers to balance the lower cost of traditional equipment against the superior speed, precision, and material versatility offered by lasers.
Growth Catalysts
- Automotive Lightweighting:Demand for high-strength, lightweight steel and aluminum components in vehicle bodies and battery enclosures drives the adoption of advanced, high-speed seam welding processes to ensure structural integrity and reduce mass.
- HVAC Sector Expansion:Growth in commercial and residential construction, particularly in Asia, increases the need for leak-proof seam welds in the production of ductwork, heat exchangers, and water heaters.
- Government Manufacturing Incentives:Policies like China's support for advanced manufacturing and India's PLI scheme encourage capital investment in modern fabrication equipment, including automated seam welders, to boost domestic production capabilities.
Market Restraints
- High Capital Investment:The significant upfront cost of automated and laser-based seam welding systems, compared to manual or semi-automated alternatives, presents a substantial barrier for small and medium-sized fabrication shops.
- Material Compatibility Limits:Traditional resistance seam welding faces technical difficulties with certain materials, including some aluminum alloys and coated steels, which can lead to inconsistent weld quality and electrode wear.
- Alternative Joining Technologies:The availability of competing methods like adhesive bonding, clinching, and riveting for non-critical structural applications presents a substitution threat in sectors like appliance manufacturing and light-gauge metal fabrication.
Strategic Opportunities
- Electric Vehicle Battery Manufacturing:The production of EV battery packs requires precise, hermetically sealed enclosures, creating a significant opportunity for laser seam welding systems capable of joining aluminum and copper alloys with high reliability.
- Medical Device Fabrication:The need for sterile, leak-proof seams in surgical instruments, pacemakers, and other implantable devices opens a niche market for high-precision, low-heat-input laser seam welders.
- Integration with Industry 4.0:Incorporating IoT sensors, machine vision, and AI-driven software for real-time quality monitoring and predictive maintenance offers a path for vendors to create higher-value, data-enabled welding platforms.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of technicians qualified to program, operate, and maintain complex, computer-controlled laser and automated resistance welding machinery constrains productivity and limits technology adoption.
- Regulatory Compliance Complexity:Adherence to a diverse and stringent set of international safety standards, including CE marking in Europe, OSHA guidelines in the US, and GB standards in China, increases design costs and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seam Welding Machine Market |
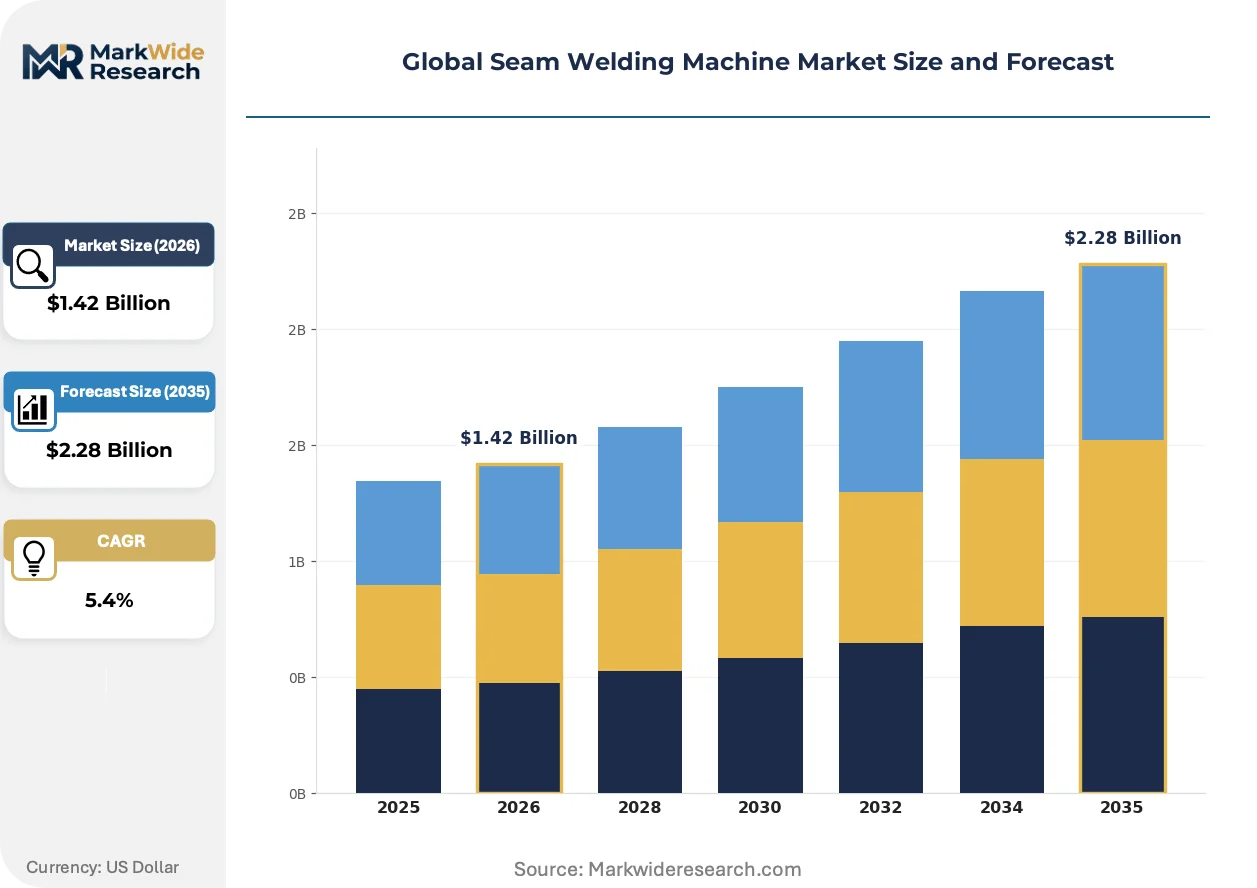
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Seam Welders, Laser Seam Welders, Ultrasonic Seam Welders, Resistance Seam Welders, Plasma Seam Welders Technology: CO2 Laser, Fiber Laser, Radio Frequency, Spot Welding, Flash Butt Welding, Induction Heating Application: Pressure Vessels, HVAC Manufacturing, Metal Roofing, Cylindrical Tanks, Pipe Fabrication, Automotive Component Assembly End User: Manufacturing Plants, Fabrication Workshops, Heavy Equipment Producers, Electronics Assemblers, Aerospace Assemblers |
| Companies Covered | Branson Ultrasonics, Miller Weldmaster, Leister Technologies, Spiro International, Franzan, ESAB, Lincoln Electric, Koike Aronson, Dahching Electric Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seam Welding Machine Market Strategic Shifts & Innovations
Automation and data integration are fundamentally changing the seam welding process. The market is shifting from standalone machines to fully integrated systems that incorporate robotics, advanced sensors, and software for real-time process control and quality assurance, redefining productivity expectations for fabricators.
Fiber laser technology provides a highly concentrated energy source capable of producing deep, narrow welds at high speeds with minimal thermal distortion. Automotive and medical device manufacturers are adopting these systems for joining thin-gauge and dissimilar materials. The precision of this process is absorbing applications that previously required slower, more specialized TIG or plasma welding techniques.
Stricter machine safety regulations globally, including Europe's Machinery Directive and OSHA standards in the United States, are mandating more sophisticated safety features. This forces equipment manufacturers to integrate light curtains, interlocked access doors, and advanced fume extraction systems as standard features. The pressure vessel and fuel tank manufacturing segments are most affected, as compliance adds cost and complexity to equipment certification.
Consolidated purchasing from large OEMs represents a significant shift in procurement patterns, particularly within the aerospace and heavy equipment industries. These buyers increasingly seek global partners who can supply standardized, automated welding solutions across multiple international production sites. This trend is most prominent in North America and Europe, where manufacturers aim to ensure process consistency and simplify their global supply chains.
Global Seam Welding Machine Market Segmentation
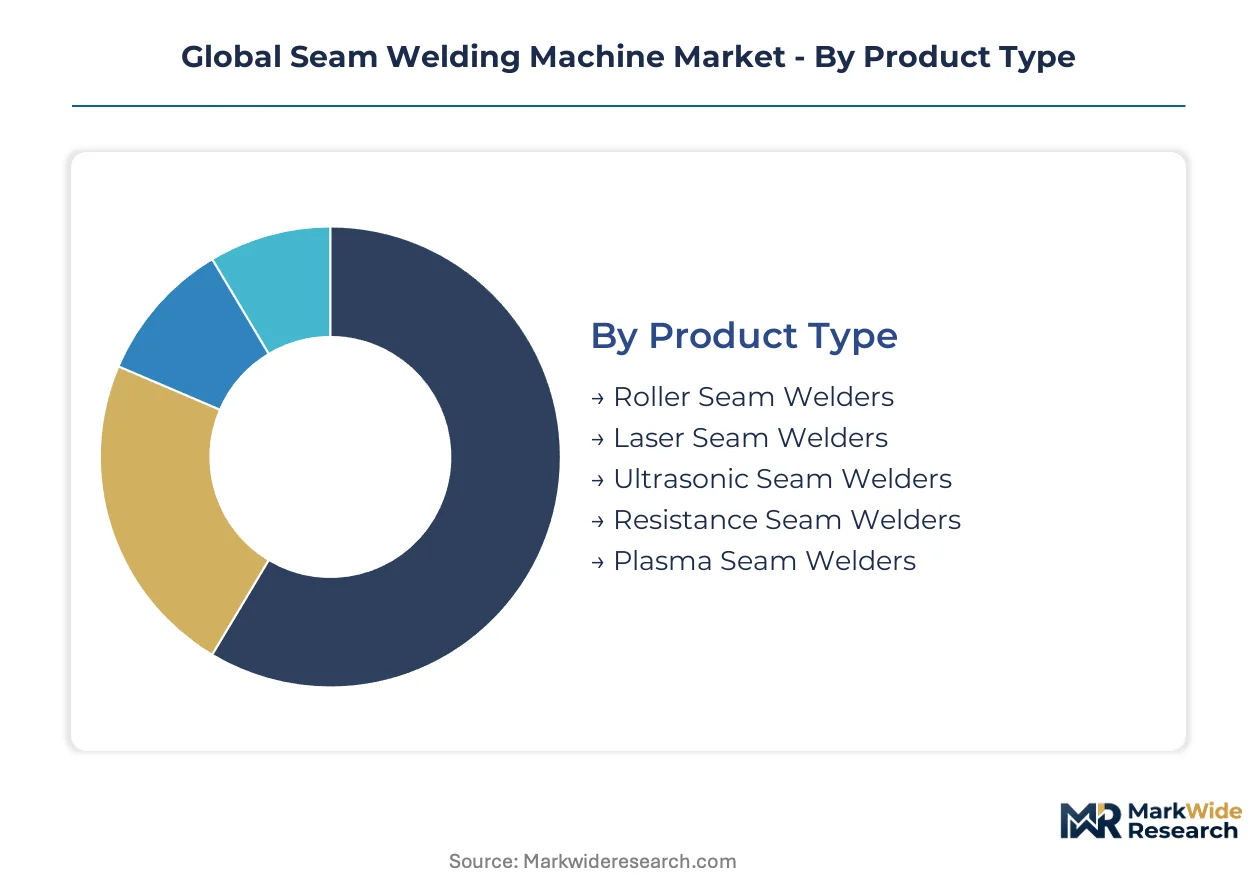
The seam welding machine market segments across diverse parameters, reflecting the specialized requirements of various industrial applications and technological advancements. Understanding these distinctions helps vendors align product development and market strategies with specific customer needs and operational demands.
Product Type:
Product type segmentation differentiates machines based on their primary welding mechanism, ranging from standalone units to those integrated into larger automated lines.
- Resistance Seam Welders:These machines create continuous, leak-proof welds by passing a workpiece between two rotating electrode wheels, forming overlapping spot welds. Demand remains strong in cylindrical tank fabrication and ductwork production due to their reliability and cost-effectiveness.
- Laser Seam Welders:Utilizing highly concentrated light energy, these systems produce precise, narrow welds with minimal heat input, suitable for delicate or heat-sensitive materials. Automotive component assembly and medical device fabrication in Germany value their speed and accuracy.
- Roller Seam Welders:A specific type of resistance welder, these machines employ roller electrodes to create a continuous seam, often used for manufacturing drums, cans, and fuel tanks. These systems are prevalent in industrial packaging sectors across China.
- Ultrasonic Seam Welders:These welders use high-frequency vibrations to join thermoplastic materials or thin metals without melting, ideal for applications requiring hermetic seals. Electronics assemblers in South Korea utilize this technology for battery pack sealing.
- Plasma Seam Welders:Employing a concentrated plasma arc, these machines offer deep penetration and high welding speeds for thicker materials, often used in heavy fabrication. Shipyards and large structural steel manufacturers in Japan employ plasma welding for robust joints.
Volume placements concentrate in Resistance Seam Welders; the faster expansion belongs to Laser Seam Welders.
Technology:
Technology segmentation outlines the underlying energy sources and methods employed, influencing both initial investment and operational efficiency across different cost tiers.
- Fiber Laser:This technology delivers a highly focused beam with excellent beam quality, enabling high-speed, precise welding of thin-gauge and dissimilar materials with minimal distortion. Automotive lightweighting initiatives in the United States drive demand for fiber laser systems.
- Spot Welding:A foundational resistance welding technique, spot welding creates localized welds at specific points, often used in conjunction with seam welding for structural integrity. This technology sees extensive use in appliance manufacturing and general fabrication workshops.
- CO2 Laser:A traditional laser welding technology, CO2 lasers are versatile for various materials and thicknesses, offering good weld quality and penetration. Heavy equipment producers in India use CO2 lasers for robust component joining.
- Radio Frequency:This method uses electromagnetic energy to heat and fuse plastic materials, predominantly for creating hermetic seals in flexible packaging and medical devices. Manufacturers in Switzerland leverage RF welding for sterile product enclosures.
- Flash Butt Welding:This resistance welding process joins components end-to-end by applying high current and pressure, generating a flash of molten metal at the joint. Railway track construction and pipe manufacturing utilize flash butt welding for strong, continuous connections.
- Induction Heating:Employing electromagnetic induction to generate heat, this technology is used for pre-heating, post-heating, or brazing in certain seam welding applications, particularly for pipe and tube production. Steel mills in Germany integrate induction heating for consistent weld quality.
Fiber Laser technology commands a growing share in high-precision applications, while Spot Welding remains fundamental across diverse fabrication processes.
Application:
Application segmentation highlights the specific end-uses for seam welding machines, where demand varies significantly by volume and weld criticality.
- HVAC Manufacturing:This sector requires leak-proof seams for ductwork, heat exchangers, and water heaters, driving demand for efficient and reliable seam welding solutions. Growth in commercial and residential construction in China fuels the need for HVAC welding equipment.
- Automotive Component Assembly:The production of lightweight steel and aluminum components, along with battery enclosures, necessitates advanced, high-speed seam welding for structural integrity and mass reduction. European automotive OEMs increasingly adopt laser seam welding for these critical assemblies.
- Pressure Vessels:Fabricating pressure vessels demands high-integrity, continuous welds that can withstand internal pressure, making robust seam welding critical for safety and performance. Industrial boiler manufacturers in South Korea rely on specialized seam welders.
- Metal Roofing:Seam welding ensures watertight and durable connections for metal roofing panels, particularly in commercial and industrial buildings. Construction projects in the United States utilize seam welding for long-lasting roof installations.
- Cylindrical Tanks:The production of various cylindrical tanks, from storage containers to fuel tanks, relies heavily on seam welding for fluid-tight seals. Manufacturers in Brazil frequently employ resistance seam welders for these products.
- Pipe Fabrication:Continuous seam welding is essential for producing pipes and tubes of various diameters and materials, ensuring structural integrity and leak prevention. Infrastructure development in India drives demand for pipe fabrication welding.
HVAC Manufacturing represents an established application segment, with Automotive Component Assembly demonstrating significant emerging demand.
End User:
End user segmentation categorizes demand by the type and scale of the purchasing entity, from large-scale industrial operations to specialized workshops.
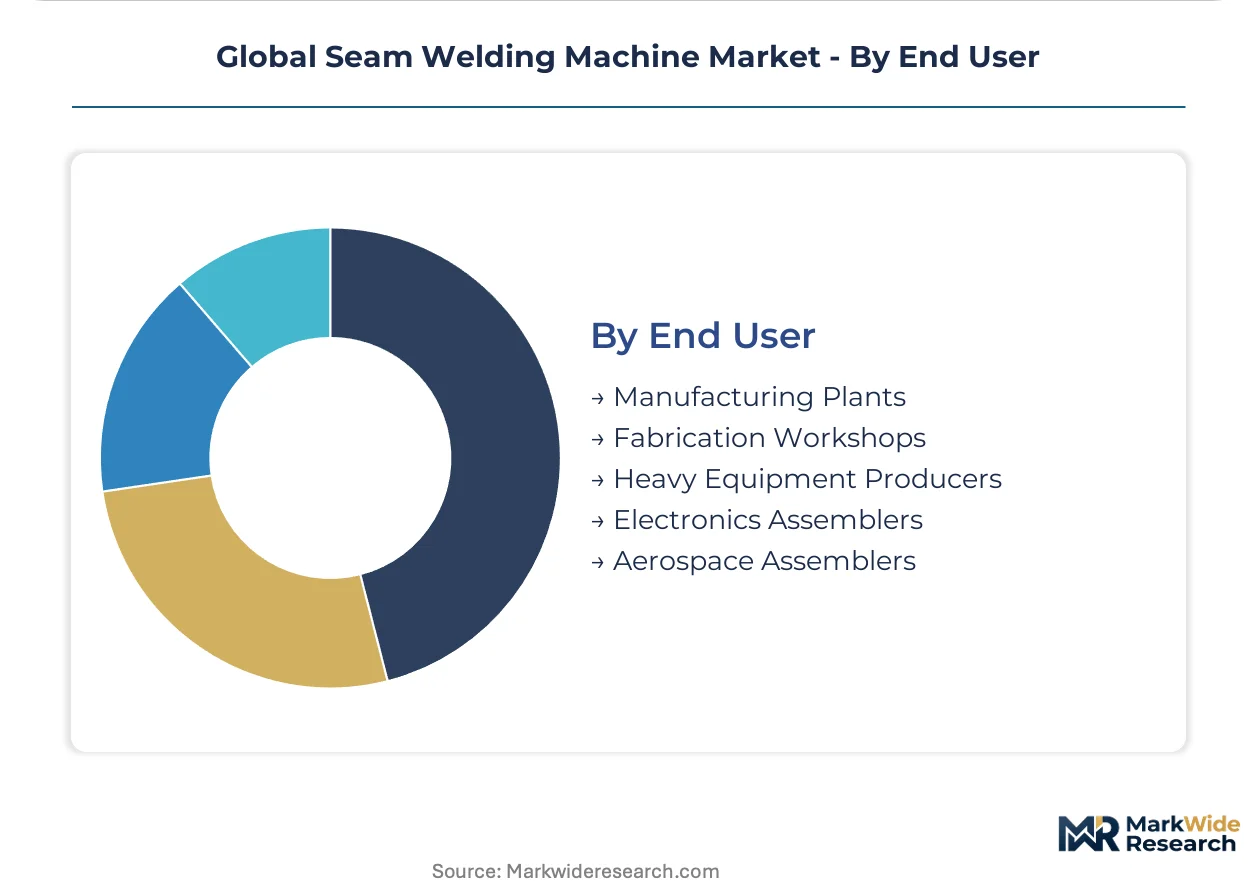
- Heavy Equipment Producers:These manufacturers require robust, high-power seam welding machines for joining thick materials used in construction machinery, agricultural equipment, and mining vehicles. Companies in Japan prioritize durable systems for their demanding production lines.
- Manufacturing Plants:Large-scale manufacturing facilities across various industries, including general fabrication and consumer goods, utilize seam welding for continuous production lines. These plants in Germany often seek automated and integrated welding solutions.
- Fabrication Workshops:Smaller, specialized workshops perform custom metalwork and repairs, requiring versatile and often more compact seam welding equipment. These workshops across Europe value adaptable machines for diverse projects.
- Electronics Assemblers:This segment requires high-precision, low-heat-input seam welding for delicate components, battery packs, and hermetic sealing of electronic devices. Electronics manufacturers in Taiwan increasingly adopt laser seam welding.
- Aerospace Assemblers:Aerospace manufacturing demands extremely high-quality, defect-free welds for critical aircraft components, often involving specialized materials like titanium and high-strength alloys. Companies in France invest in advanced laser welding for stringent aerospace standards.
Heavy Equipment Producers drive investment in high-power systems, while Electronics Assemblers prioritize precision and automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global seam welding machine market exhibits a clear divide between production hubs and consumption centers. Demand for advanced welding solutions is concentrating in specialized industrial zones, while manufacturing capabilities are evolving globally. This dynamic shapes investment patterns and technology adoption across key economies.
China
Extensive fabrication workshops in China drive demand for resistance seam welders in industrial packaging and HVAC manufacturing. Adherence to GB standards for industrial machinery is essential for market access. Specialized industrial zones like the Yangtze River Delta actively support advanced manufacturing equipment deployment.
United States
Automotive lightweighting initiatives in the United States fuel demand for high-speed fiber laser systems for battery enclosures. OSHA guidelines mandate stringent safety features for welding equipment in manufacturing plants. The automotive cluster around Detroit continues to integrate automated seam welding for vehicle body production.
Germany
Manufacturing plants in Germany require automated and integrated welding solutions for automotive component assembly and heavy equipment production. CE marking directives ensure compliance for all machinery entering the European market. Industrial regions such as Bavaria are adopting advanced laser seam welding for precision applications.
Japan
Shipyards and heavy equipment producers in Japan prioritize durable, high-power seam welding machines for robust structural joints. JIS standards govern the quality and performance of industrial welding equipment. The Kansai region, with its strong industrial base, sees continuous investment in plasma seam welding technology.
India
Infrastructure development in India drives demand for pipe fabrication welding and heavy equipment component joining. The PLI scheme encourages capital investment in modern fabrication equipment to boost domestic production. Manufacturing hubs like Maharashtra are rapidly integrating automated seam welders into their production lines.
Global Seam Welding Machine Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized manufacturers cater to niche applications requiring precision or specific material handling capabilities. The market exhibits a tiered structure, with a few global players offering comprehensive portfolios and numerous regional specialists. Strategic archetypes include diversified industrial conglomerates providing end-to-end solutions and focused automation providers specializing in integrated systems. Companies are actively pursuing portfolio diversification and geographic expansion to capture emerging opportunities in new industrial sectors.
Within the diverse competitive landscape, Miller Weldmaster exemplifies expertise in automated solutions for industrial fabrics and heavy-duty applications, representing the specialized automation archetype. ESAB, a major industrial player, occupies a position across multiple end-user segments with its broad welding and cutting portfolio, anchoring the diversified conglomerate segment. Lincoln Electric also represents a significant presence, known for its extensive range of welding equipment and consumables for general fabrication. These firms collectively demonstrate the industry's focus on both specialized high-performance systems and comprehensive industrial offerings, reflecting the varied needs of global customers.
| Leading Market Players |
|---|
| Branson Ultrasonics |
| Miller Weldmaster |
| Leister Technologies |
| Spiro International |
| Franzan |
| ESAB |
| Lincoln Electric |
| Koike Aronson |
| Dahching Electric Industrial |
| Others |
Cost & Logistics Intelligence
A clear performance gap between traditional resistance welders and advanced fiber laser systems defines market pricing and shapes component sourcing strategies. This divergence impacts both the cost structure for manufacturers and the procurement decisions for end-users across industrial sectors.
Pricing Analysis
Premium pricing often reflects shorter lead times for specialized components, while standard equipment sees discounts for immediate availability. Per-unit transactional and contract-based long-term agreements dominate the market. Weld precision, compliance with CE marking or OSHA guidelines, and comprehensive after-sales support drive price differentiation. Pricing pressure for advanced laser systems stems from specialized component availability. Small and medium-sized fabrication shops exhibit high price sensitivity, unlike large automotive OEMs.
Supply Chain Analysis
Regional distribution centers facilitate timely delivery of standard resistance welding machines, while hub-and-spoke models support specialized laser system components. Manufacturing capabilities concentrate in China, Germany, and Japan for both machinery and critical sub-components. The industry relies heavily on laser diodes, precision optics, and specialized electrode materials. Single-source vulnerability for advanced fiber laser components poses a structural risk. Distribution runs through direct sales teams for high-value automated systems and local distributor networks for conventional equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment, where limited global manufacturing capacity for high-power laser diodes props up pricing for advanced systems.
For Market Incumbents: Acquire specialized software firms to integrate advanced AI for real-time weld quality monitoring and predictive maintenance. Standardize global product lines to counter regional competitors and simplify supply chains. Deepen vertical integration into critical component manufacturing, such as laser sources, to mitigate supply risks. Invest in R&D for advanced material compatibility, especially for EV battery enclosures.
For New Entrants and Emerging Players: Enter via niche applications requiring ultra-precision, such as medical device fabrication, leveraging specialized laser welding technology. Focus on emerging Asian markets for mid-range automated resistance welders where capital investment is lower. Offer comprehensive service and support bundles to differentiate from established players. Target fabrication workshops seeking cost-effective automation upgrades.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized automation providers given accelerating demand for precision welding in EV battery and medical device manufacturing. The market shows strong viability over the next 5-10 years, driven by industrial automation. Target firms with proprietary fiber laser technology or advanced vision systems. Watch for increased venture capital funding into welding software and AI integration companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing production of fiber laser sources addresses supply bottlenecks for automotive OEMs. |
| Technology Licensing | Licensing advanced material welding patents accelerates adoption in aerospace and medical device sectors. |
| Joint Venture | Partnering with robotics firms creates fully automated welding cells for manufacturing plants in Germany. |
| Green Manufacturing Transition | Developing energy-efficient welding processes aligns with sustainability goals for heavy equipment producers. |
| Platform Standardization | Standardizing control interfaces across machine types simplifies operation for fabrication workshops in China. |
Research Approach
GB standards, OSHA guidelines, and CE marking directives formed the secondary backbone, providing regulatory context for seam welding machine design and market access. This was augmented by primary interviews with plant managers, R&D directors, and procurement leads across key industrial sectors. Insights were triangulated using both bottom-up market sizing and top-down validation from published industry reports.
Historical trendline analysis established foundational growth trajectories for each market segment over the analysis window. The analytical framework segmented by Product Type, Technology, Application, End User, and regional adoption. Compound Annual Growth Rates were derived from historical data and projected market drivers like global construction spending. Electric vehicle production targets also served as a key forecast input.
Revisions become necessary when geopolitical trade tensions or rapid technological obsolescence materialize, impacting supply chains or demand. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Snow Removal Equipment Market
Construction Equipment
US Rental Equipment Market