
 Stud Welding Guns Market | 2026-2036
Stud Welding Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Stud Welding Guns Market Analytics
Automotive OEMs are reorganizing their body-in-white fastening specifications toward lighter mixed-material assemblies. Taylor Studwelding dominates European shipyard contracts through its drawn-arc systems. Nelson Stud Welding anchors North American infrastructure retrofit demand with portable capacitor-discharge equipment. HBS Bolzenschweiss-Systeme differentiates via in-house production of gun control electronics and custom feeder mechanisms.
A stud welding gun is a precision fastening tool that delivers controlled electrical energy to fuse a metal stud onto a base material without auxiliary filler metal, typically operating at currents between 800 A and 2,500 A depending on stud diameter and material thickness. The device serves primarily to create permanent load-bearing attachments in steel construction, automotive body assembly, and marine fabrication where drilled holes would compromise structural integrity. Handheld guns still occupy the largest installed base due to flexibility in field repair and retrofit work, though automatic guns represent the fastest-growing category as robotic integration spreads through automotive metal fabrication lines. Drawn-arc technology leads in heavy structural applications requiring deep penetration, while capacitor-discharge systems command premium positioning in thin-sheet automotive and aerospace specialty projects where heat-affected zone minimization protects material properties.
The EU Machinery Directive and CE marking requirements enforce operator safety interlocks and electromagnetic compatibility standards that shape gun control architecture and shielding design. China's GB standards and SAMR certification protocols govern import access and dictate local testing for electrical safety and weld consistency. Japan's METI energy-efficiency guidelines and JIS welding standards influence product development cycles for equipment sold into precision manufacturing segments. Stakeholders must monitor how evolving carbon-accounting rules under the EU Green Deal and China's dual carbon goals reshape material sourcing and energy-consumption specifications for welding equipment supply chains.
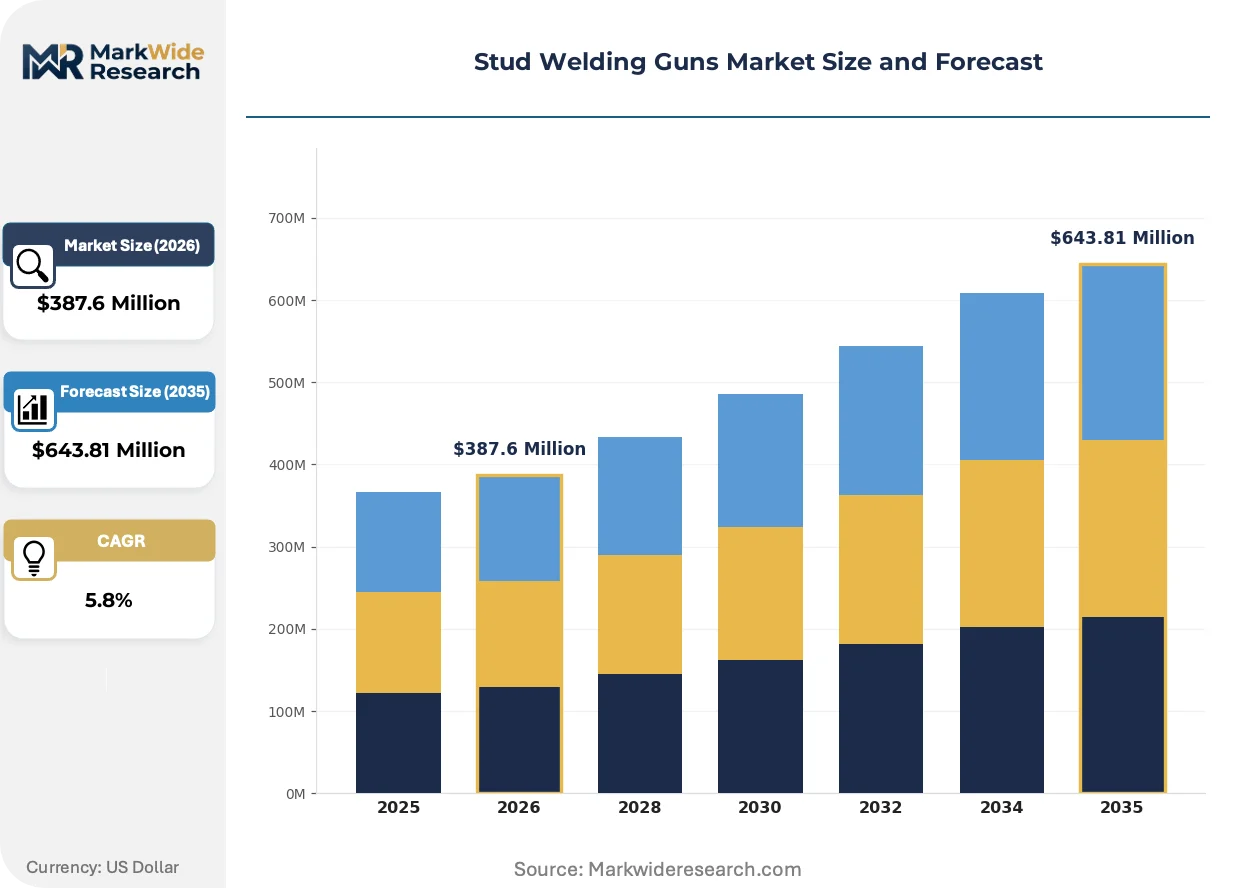
Market Dynamics
Automotive body-in-white automation is compressing cycle-time requirements for stud welding operations, forcing equipment suppliers to reconcile robotic integration demands with legacy manual-system installed bases across Tier-1 supplier networks.
Growth Catalysts
- EU Machinery Directive weld-quality mandates:CE marking requirements for certified traceability are pulling buyers toward capacitor-discharge and drawn-arc systems with integrated data-logging capabilities.
- Shipbuilding automation in East Asia:South Korean and Japanese yards are expanding automated stud welding lines for LNG carrier construction, creating concentrated demand for high-duty-cycle equipment.
- Lightweighting in mixed-material automotive assemblies:Aluminum-steel joining requirements in body-in-white structures are expanding specification scope for heat-controlled welding processes.
Market Restraints
- Copper and rare-earth magnet cost volatility:Gun coil assemblies and transformer cores face input price swings that compress margin predictability for equipment manufacturers.
- Specialized technician scarcity:The intersection of welding physics, programmable logic control, and robotic integration creates a narrow talent pool that constrains deployment velocity.
- Capacitor bank supply concentration:High-voltage capacitor manufacturing clusters in East Asia create single-source vulnerability for CD system producers.
Strategic Opportunities
- India's PLI scheme for automotive component manufacturing:Domestic production incentives are attracting body-in-white investment that requires localized stud welding equipment supply.
- Wind tower fabrication scaling:Onshore and offshore turbine foundation construction is opening new heavy-structural applications for drawn-arc systems.
- Retrofit digitization of installed manual bases:Sensor retrofit kits and connectivity modules can capture recurring revenue from existing fleet modernization without full replacement.
Industry Challenges
- Multi-standard certification timelines:Simultaneous CE, GB, and UL approval pathways for new gun models extend time-to-revenue by 8-14 months.
- Legacy control protocol fragmentation:Proprietary fieldbus systems from incumbent robot OEMs complicate seamless integration for third-party gun suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stud Welding Guns Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Guns, Automatic Guns, Stationary Guns, Accessories Technology: Capacitor Discharge, Drawn Arc, Large Diameter, MIG End User: Construction, Automotive, Shipbuilding, Aerospace Application: Metal Fabrication, Industrial Production, Repair Services, Specialty Projects |
| Companies Covered | Taylor Studwelding, Nelson Stud Welding, Stanley Engineered Fastening, HBS Bolzenschweiss-Systeme, Bolte GmbH, Köster & Co. GmbH, Heinz Soyer Bolzenschweisstechnik, Pro-Tek, Koeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stud Welding Guns Market Evolving Landscape
Control electronics miniaturization and real-time weld-monitoring sensor integration are redefining equipment architecture, creating divergence between premium connected systems and cost-optimized manual alternatives.
Modular gun architectures with swappable transformer and feeder subassemblies are fragmenting traditional equipment categories. Tier-1 automotive suppliers in Germany's Stuttgart-Wolfsburg corridor are piloting these configurations to reduce line-changeover downtime. The technology is fragmenting supplier tiering, enabling mid-scale fabricators to access performance tiers previously gated by capital intensity.
China's GB standards and SAMR certification protocols are tightening electrical safety and electromagnetic compatibility requirements for imported welding equipment. The industrial consequence is a bifurcation between products engineered for simultaneous multi-market approval and those optimized solely for domestic Chinese sale. Capacitor-discharge systems targeting thin-sheet automotive applications face the most intensive retesting burden.
Buyer preference is consolidating around equipment-as-service models with bundled maintenance and consumable replenishment. Tier-1 automotive procurement teams are displacing capital-purchase frameworks with per-weld or uptime-guarantee contracts. This shift is most visible in Germany and South Korea, where fleet-scale deployments justify vendor-managed inventory arrangements.
Stud Welding Guns Market Segmentation
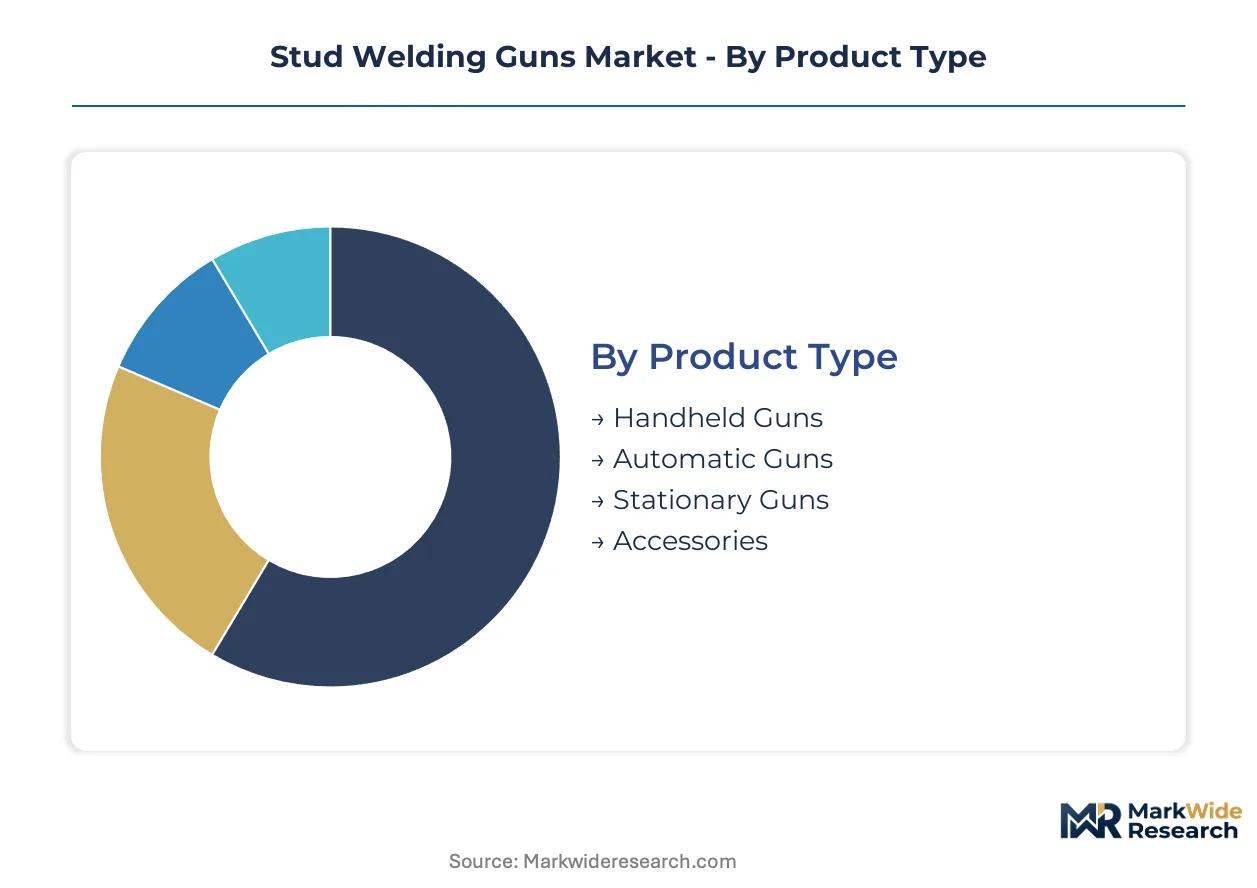
Segmentation reveals how stud welding gun demand fragments across equipment mobility, energy delivery methods, and end-use intensity. Channel strategy varies sharply between capital-intensive automatic systems and portable field-service units.
Product Type:
Channel mix splits between distributor networks for handheld units and direct OEM relationships for automated lines, with service contracts increasingly bundled across all tiers.
- Handheld Guns:Portable units with pistol-grip or inline configurations deliver 800-1,500 A output for field repair and retrofit work. Construction crews across Germany's industrial zones and Japan's shipyards maintain extensive fleets due to flexibility in confined structural access. Manual systems face margin compression from rising copper coil costs.
- Automatic Guns:Robotic integration-ready units with programmable force-feedback and real-time current modulation serve body-in-white lines. Stuttgart and Wolfsburg automotive supplier clusters are standardizing on these configurations to compress cycle times for aluminum-steel mixed assemblies.
- Stationary Guns:Fixed-position systems with heavy-duty transformer assemblies anchor high-volume production cells.
- Accessories:Feeder mechanisms, control cables, and consumable collet sets generate recurring aftermarket revenue.
Handheld guns dominate installed base. Automatic guns are where expansion concentrates.
Technology:
Cost tier stratification separates premium precision systems from standard structural equipment, with certification grade driving price multiples.
- Capacitor Discharge:Rapid energy discharge through pre-charged capacitor banks produces minimal heat-affected zones for thin-sheet applications. Aerospace specialty shops in France and automotive surface-sensitive operations in South Korea specify CD systems to protect material properties on aluminum panels. GB standards and SAMR protocols impose intensive retesting burdens on imported CD equipment.
- Drawn Arc:Controlled arc ignition with ceramic ferrule shielding penetrates thick plate and coated steels for structural loads. LNG carrier construction at South Korean and Japanese yards consumes high-duty-cycle drawn-arc lines for deck and bulkhead fastening.
- Large Diameter:Extended-stroke mechanisms handle studs above 16 mm for heavy civil infrastructure.
- MIG:Wire-feed hybrid systems bridge stud welding and conventional arc processes for specialized repair scenarios.
Drawn arc commands heavy-structural volume. Capacitor discharge captures premium positioning in precision segments.
End User:
Application intensity varies by sector, with automotive and shipbuilding requiring highest equipment utilization rates.
- Construction:Steel erection and facade installation demand portable equipment for field adaptation.
- Automotive:Body-in-white automation drives specification toward robotic integration and data-logging compliance.
- Shipbuilding:LNG carrier programs at Hyundai Heavy Industries and Mitsubishi Heavy Industries concentrate demand for automated lines.
- Aerospace:Thin-gauge aluminum and titanium joining restricts specification to heat-minimized CD systems with certified traceability.
Construction holds widest unit dispersion. Shipbuilding shows steepest expansion trajectory.
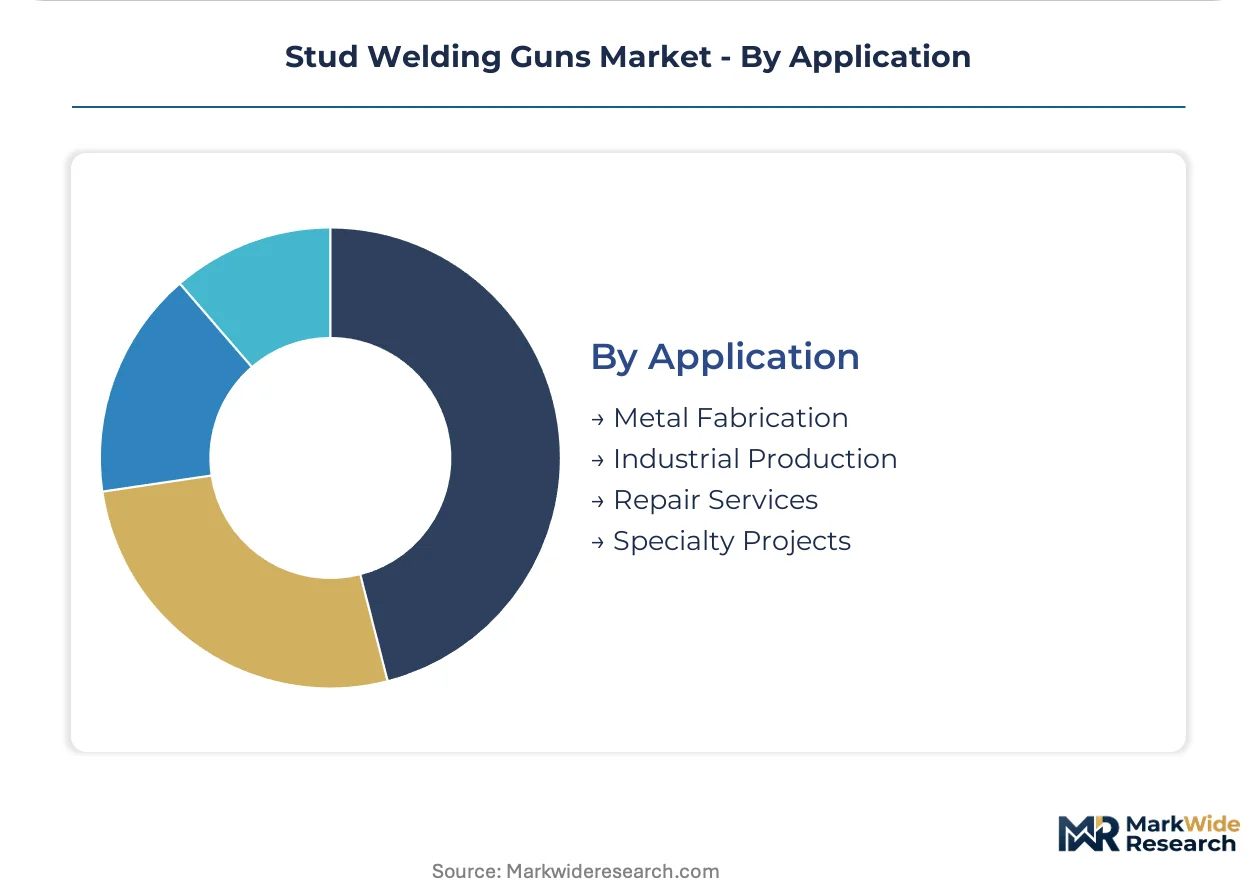
Application:
Customer type segmentation separates capital-purchase frameworks from equipment-as-service contracts, particularly in fleet-scale deployments.
- Metal Fabrication:Job shops and contract manufacturers balance flexibility requirements against throughput targets.
- Industrial Production:OEM captive shops prioritize uptime guarantees and vendor-managed inventory arrangements.
- Repair Services:Mobile maintenance contractors favor lightweight handheld units with rapid setup.
- Specialty Projects:Prototype and custom fabrication tolerates higher per-weld costs for precision control.
Industrial production leads contract value. Repair services represent broadest unit distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's steel handling infrastructure underwrites Europe's role in stud welding equipment distribution. LNG import terminals at Incheon and Yokohama anchor East Asian demand for heavy-structural fastening systems. Automotive export corridors from Bremerhaven and Charleston concentrate precision welding equipment flows.
Germany
Automotive body-in-white automation and shipyard modernization drive equipment procurement. CE marking requirements under the EU Machinery Directive enforce certified traceability for capacitor-discharge and drawn-arc systems. Stuttgart and Wolfsburg supplier clusters standardize on robotic integration-ready configurations for aluminum-steel mixed assemblies.
China
Domestic shipbuilding expansion and automotive lightweighting programs absorb high-duty-cycle equipment. GB standards and SAMR certification protocols govern import access and mandate local electrical safety testing. Shanghai and Guangzhou fabrication hubs concentrate demand for thin-sheet capacitor-discharge systems with electromagnetic compatibility compliance.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries LNG carrier programs consume automated stud welding lines. METI-aligned technical standards influence equipment specifications through cross-border supply relationships. Ulsan and Geoje shipyard complexes deploy high-cycle drawn-arc systems for deck and bulkhead fastening operations.
United States
Infrastructure retrofit and wind tower fabrication scale demand for portable and heavy-structural equipment. OSHA electrical safety regulations and NHTSA automotive standards shape gun control architecture and shielding design. Gulf Coast petrochemical construction and Great Lakes automotive corridors concentrate field-service and production-line deployments.
Japan
Precision manufacturing and shipbuilding automation sustain premium equipment demand. METI energy-efficiency guidelines and JIS welding standards influence product development cycles for domestic and export markets. Nagoya automotive supplier networks and Yokohama shipyards specify heat-minimized systems for thin-gauge material joining.
Stud Welding Guns Market Competitive Landscape
Concentration sits with European and East Asian specialists controlling drawn-arc and capacitor-discharge technology tiers. The vendor base separates into three strategic archetypes: integrated system houses with captive control electronics production, regional fabricators serving shipyard and construction end-users, and automation-focused suppliers targeting automotive robotic integration. Competitive moves center on modular gun architecture development and equipment-as-service contract structures displacing capital-purchase frameworks.
Among European specialists, Taylor Studwelding, HBS Bolzenschweiss-Systeme, and Nelson Stud Welding occupy positions spanning shipyard, automotive, and infrastructure retrofit segments. Taylor Studwelding exemplifies the shipyard-contract archetype through drawn-arc system deployment. HBS Bolzenschweiss-Systeme represents integrated production capabilities with in-house control electronics. Nelson Stud Welding anchors North American infrastructure positioning through portable equipment specialization. These three names illustrate how geographic origin and company structure suffixes map to distinct competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Taylor Studwelding |
| Nelson Stud Welding |
| Stanley Engineered Fastening |
| HBS Bolzenschweiss-Systeme |
| Bolte GmbH |
| Köster & Co. GmbH |
| Heinz Soyer Bolzenschweisstechnik |
| Pro-Tek |
| Koeco |
| Others |
Value Network & Pricing Analysis
Copper coil substitution toward aluminum-wound transformer cores is redrawing procurement geography from German automotive supplier belts toward Chinese winding facilities, compressing premium-tier pricing power while opening economy-tier volume channels.
Pricing Analysis
Volume-discount tiering structures separate three performance levels across the market. Certification grade under CE marking and GB standards drives price multiples between premium capacitor-discharge systems and standard drawn-arc configurations. Cost compression in handheld manual tiers intensifies as copper and rare-earth magnet input volatility squeezes margin predictability. Tier-1 automotive procurement teams exhibit lowest price sensitivity due to uptime-guarantee contract structures, while mobile repair contractors in construction segments demonstrate highest elasticity.
Supply Chain Analysis
China and South Korea anchor high-voltage capacitor bank manufacturing, with Taiwan contributing precision control electronics subassemblies. Gun coil assemblies draw from copper concentrate flows through Chilean and Indonesian smelters. Single-source vulnerability concentrates in East Asian capacitor production clusters. Distribution runs through authorized distributor networks for handheld units and direct OEM relationships for automated line integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as automotive lightweighting splits demand between precision CD systems for aluminum panels and heavy-duty drawn-arc lines for mixed-material chassis, creating distinct procurement silos.
For Market Incumbents: Fortify captive control electronics production against modular gun architecture disruption from mid-scale competitors. Deepen backward integration into transformer winding capacity in Germany and China to defend margin position against copper cost volatility. Prioritize CE-GB simultaneous certification pathways to compress time-to-revenue for new product launches. For New Entrants and Emerging Players: Equipment-as-service bundling gaps in India's PLI-driven automotive component corridors offer white-space entry. Target under-served wind tower fabricators in the US Gulf Coast with portable drawn-arc rental fleets. Pursue sensor retrofit kit development for installed manual bases as recurring revenue anchor. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with in-house gun control electronics and established SAMR certification pathways. Long-term viability over a multi-year horizon hinges on automation-readiness and service-contract attach rates. Monitor India's PLI scheme disbursement velocity as inflection indicator for regional equipment demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Gun Architecture Development | Reduces line-changeover downtime for Stuttgart-Wolfsburg automotive supplier clusters. |
| Backward Integration into Control Electronics | Protects margin stability against copper coil and capacitor input volatility. |
| Equipment-as-Service Contract Structuring | Captures recurring revenue from Germany and South Korea fleet-scale deployments. |
| Multi-Standard Certification Investment | Accelerates CE-GB-UL approval timelines for capacitor-discharge system launches. |
| Retrofit Digitization Kit Development | Monetizes installed manual base fleets without full replacement capital cycles. |
Research Methodology
The analysis maps handheld, automatic, and stationary gun configurations, each validated through maintenance directors at Tier-1 automotive suppliers, shipyard production engineers at Hyundai Heavy Industries and Mitsubishi Heavy Industries, and aftermarket service heads at European distributor networks. Primary interview insights triangulate against customs trade data for welding equipment flows, SEC filings from industrial automation conglomerates, SAMR certification registries, and IHS Markit automotive production databases. Bottom-up equipment unit estimates reconcile with top-down end-use industry consumption models.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span product mobility tier, energy delivery technology, end-use intensity, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and automation penetration curves. Forecast inputs incorporate shipbuilding orderbook data from Korean and Japanese yards and automotive body-in-white capital expenditure disclosures.
Forecasts assume regulatory continuity in CE marking regimes under the EU Machinery Directive and GB standards enforcement by SAMR; material policy shifts would require re-modeling. Specific risks that could revise projections include capacitor supply chain disruption, automotive platform standardization cancellations, and carbon-accounting rule changes under the EU Green Deal. Recalibration cycles align with material shifts in shipbuilding order flows and automotive lightweighting program commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America Drilling Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Cable Winches Market
Construction Equipment
Utility Locator Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Crane Rail Market
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Rotary Trommel Market