
 Ceramic Tile Printing Machine Market | 2026-2036
Ceramic Tile Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Tile Printing Machine Market Analysis
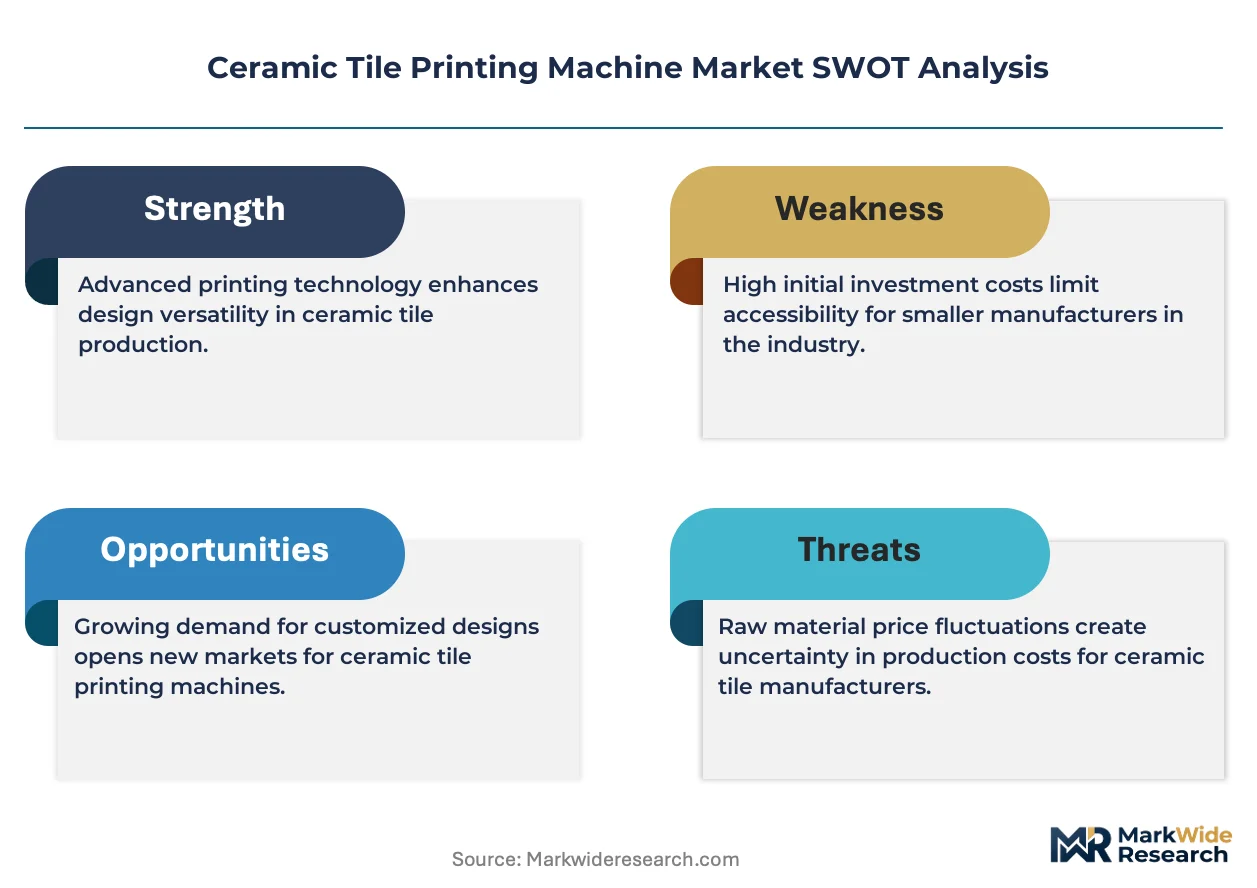
EU REACH pigment restrictions is realigning the cost-of-entry calculus for ceramic tile printing equipment suppliers entering European markets. EFI leverages its UV-curing platform specialization to navigate tighter chemical compliance without sacrificing throughput. Ferro Corporation anchors its position through captive ink formulation capabilities that reduce third-party pigment exposure. Roland DGA competes in the mid-tier decorator segment with compact digital systems engineered for shorter production runs.
A ceramic tile printing machine is industrial equipment that deposits ceramic inks or pigments onto bisque-fired or glazed tile surfaces using piezoelectric inkjet, rotary screen, or laser imaging systems, typically achieving resolutions from 360 to 1000 dpi at production speeds exceeding 100 linear meters per hour. Its primary purpose is to enable mass customization of surface decoration while eliminating the capital intensity and changeover delays of traditional analog screen printing. Digital printers now lead product type demand as architectural specifiers shift toward shorter-run, design-flexible production models. UV printing technology captures the fastest expansion within the technology dimension, driven by instant cure cycles that reduce work-in-process inventory and enable just-in-time manufacturing for contractor-driven projects. Wall tiles remain the dominant application segment, though decorative tiles command superior margin pools as hospitality and luxury residential end users prioritize bespoke surface aesthetics.
The US EPA oversees volatile organic compound emissions from solvent-based printing operations, while China's MEE enforces dual carbon goals that constrain energy-intensive kiln-curing processes downstream of decoration lines. India's BIS certification requirements for imported printing machinery create non-tariff barriers that favor domestic assembly partnerships or localized manufacturing footprints. Stakeholders must monitor how tightening chemical regulations in multiple jurisdictions interact with energy transition mandates to reshape total cost of ownership calculations for new equipment investments.
Market Dynamics
Digital inkjet technology is compressing analog screen printing economics while REACH pigment restrictions force chemistry reformulation across European supply chains. Equipment suppliers must now balance throughput speed against compliance costs in their platform architectures.
Growth Catalysts
- India's Housing for All schemes:Central government subsidies for low-cost residential construction sustain demand for large-format wall and floor tile production lines requiring high-speed digital decoration systems.
- UV-curing technology maturation:Instant polymerization cycles eliminate intermediate drying stages, enabling just-in-time manufacturing workflows that reduce work-in-process inventory for contractor-driven projects.
- REACH pigment compliance deadlines:European chemical restrictions on heavy metal-based colorants accelerate replacement demand for water-based ink systems compatible with next-generation printhead architectures.
Market Restraints
- Piezoelectric printhead supply concentration:Precision nozzle manufacturing concentrates among Japanese and German component specialists, exposing OEMs to single-source vulnerability and extended lead times for replacement parts.
- Specialized ceramic ink chemistry costs:Pigment particle size distribution requirements and thermal stability specifications drive raw material costs substantially above standard graphic arts ink formulations.
- Energy-intensive kiln curing dependency:Decoration line throughput remains constrained by downstream firing capacity, with China's MEE dual carbon goals limiting expansion of natural gas-fired tunnel kiln infrastructure.
Strategic Opportunities
- Vietnam and Indonesia construction acceleration:Southeast Asian commercial real estate development and hospitality sector expansion create demand for mid-tier digital printing systems with shorter production run capabilities.
- Decorative tile premiumization:Hospitality and luxury residential end-users prioritize bespoke surface aesthetics, expanding addressable margin pools for equipment supporting photorealistic imagery and textured glaze effects.
- EU Green Deal industrial decarbonization incentives:Member state funding programs for energy-efficient manufacturing equipment subsidize UV-LED curing retrofits that reduce thermal energy consumption versus conventional infrared drying.
Industry Challenges
- Cross-disciplinary technician scarcity:Operation of hybrid electromechanical-chemical systems requires simultaneous competency in ink rheology, precision motion control, and color management software calibration.
- Legacy rotary screen integration complexity:Brownfield tile plants face substantial downtime and workflow reconfiguration costs when retrofitting digital print bars alongside existing analog decoration stations.
- BIS certification timeline uncertainty:India's mandatory testing and registration procedures for imported printing machinery create unpredictable market entry delays that complicate project financing and installation scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Tile Printing Machine Market |
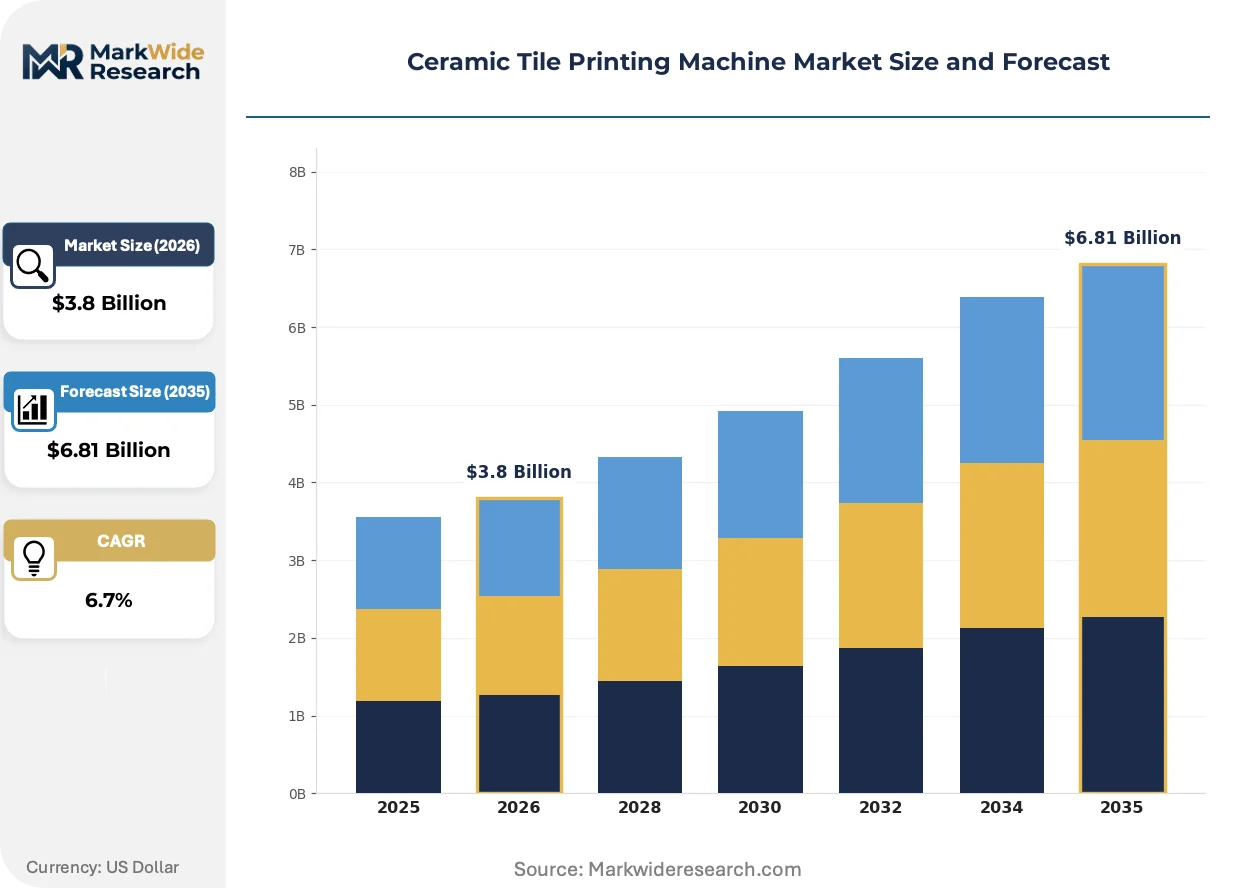
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printers, Inkjet Printers, Rotary Screen Printers, Laser Printers Technology: UV Printing, Solvent Printing, Dye-Sublimation, Direct-to-Object Printing End User: Manufacturers, Retailers, Contractors, DIY Enthusiasts Application: Wall Tiles, Floor Tiles, Decorative Tiles, Industrial Tiles |
| Companies Covered | Ntek, Roland DGA, EFI, Epson, IT Strategies, Neixo, Renishaw, Ferro Corporation, Meitu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Tile Printing Machine Market Emerging Trajectories
Active digitization of decoration workflows is compressing design-to-production cycles while regulatory chemistry constraints and shifting procurement patterns reshape equipment specification criteria. Three converging developments define current competitive positioning.
Single-pass inkjet architectures are integrating drop-on-demand piezoelectric arrays with inline spectrophotometric color measurement to enable real-time density correction without stopping production lines. Large-format tile manufacturers in Italy and Spain deploy these systems for batch-size-one customization serving architect-specified commercial projects. The technology is integrating quality assurance directly into the printing process, eliminating separate inspection stations and reducing labor intensity per square meter output.
REACH Annex XVII restrictions on cadmium and lead compounds in consumer products are forcing reformulation of traditional ceramic pigments toward rare earth and organic alternatives with inferior thermal stability. European tile producers absorb higher ink costs and modified firing curves to maintain color gamut compliance. Decorative tile segments targeting hospitality specification respond fastest, as LEED and BREEAM certification requirements for indoor air quality reinforce chemical safety preferences among project developers.
Tile distributors are consolidating specification influence through digital sample libraries and virtual room visualization tools that bypass traditional manufacturer sales engineer relationships. Commercial contractor procurement teams in Germany and France now specify equipment compatibility with cloud-based design platforms before capital approval. This channel transformation concentrates purchasing power among large distributor groups while fragmenting equipment vendor access to end-user technical requirements.
Ceramic Tile Printing Machine Market Segmentation
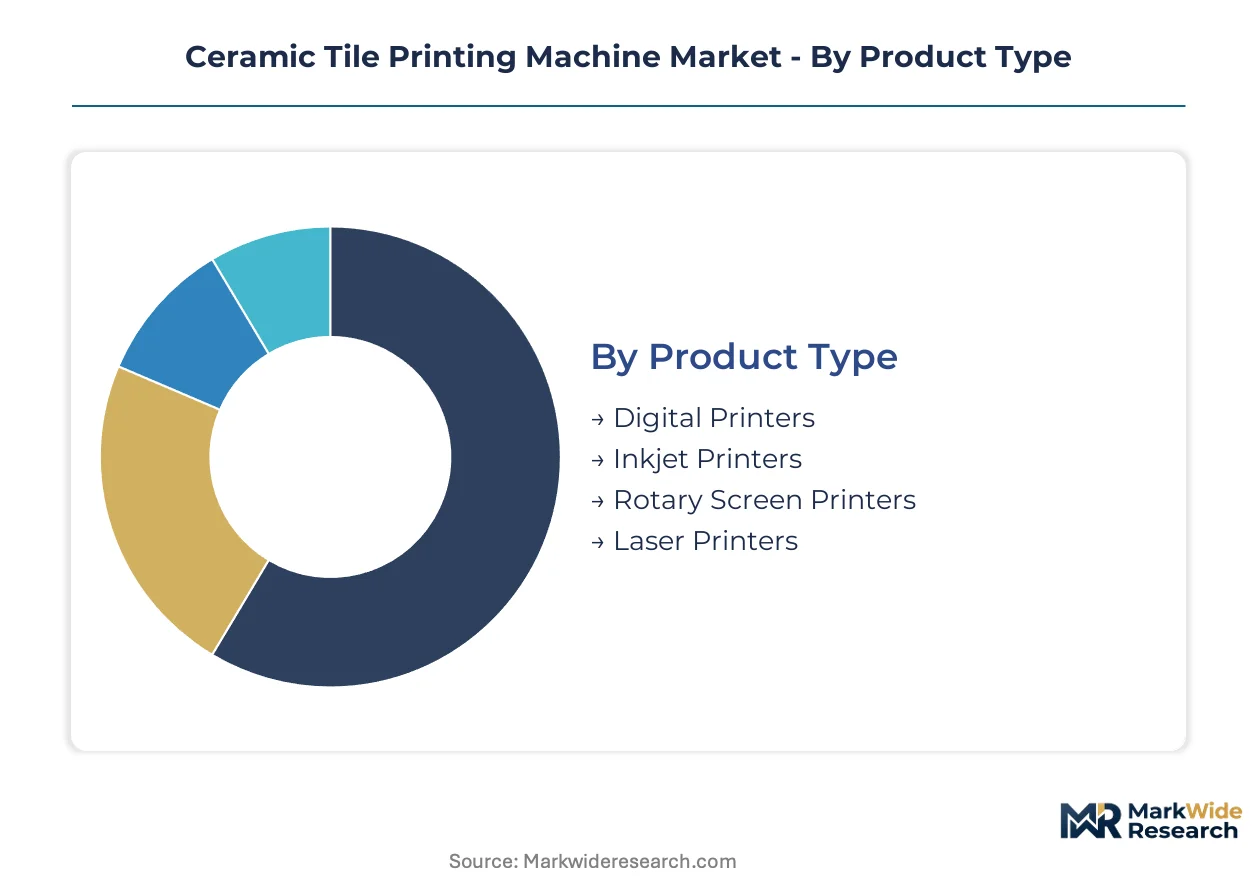
Segmentation in ceramic tile printing equipment reveals how capital allocation, technical requirements, and downstream channel power reshape vendor go-to-market strategies. Buyers diverge sharply between high-volume manufacturers seeking throughput optimization and fragmented decorator segments prioritizing design flexibility over speed.
Product Type:
Equipment selection tracks production scale and changeover frequency, with large-format tile plants favoring single-pass architectures while smaller decorators accept multi-pass trade-offs for capital efficiency.
- Digital Printers:Piezoelectric inkjet arrays deposit ceramic pigments at 360–1000 dpi through fixed print bars, eliminating rotary screen changeover delays. India's Housing for All schemes sustain demand for high-throughput wall and floor tile lines requiring continuous digital decoration.
- Inkjet Printers:Drop-on-demand systems with variable droplet sizing enable photorealistic imagery and textured glaze effects for hospitality specification. European REACH pigment restrictions accelerate replacement demand as producers reformulate toward water-based ink compatibility.
- Rotary Screen Printers:Analog cylinder systems persist in emerging markets where capital constraints outweigh flexibility premiums.
- Laser Printers:Thermal imaging systems niche into precision marking and security applications with limited decorative penetration.
Digital Printers lead volumes today; Inkjet Printers are gaining share fastest.
Technology:
Curing chemistry determines energy consumption profiles and regulatory compliance exposure, with instant-polymerization systems displacing thermal drying in carbon-constrained jurisdictions.
- UV Printing:Photoinitiator-triggered polymerization achieves instant cure cycles, eliminating intermediate drying stages and reducing work-in-process inventory. China's MEE dual carbon goals constrain energy-intensive kiln expansion downstream, amplifying UV-LED retrofit appeal for existing decoration lines.
- Solvent Printing:Volatile organic compound emissions face tightening US EPA oversight and EU industrial emissions limits, compressing addressable market share.
- Dye-Sublimation:Heat-transfer chemistry enables polyester-coated tile decoration with limited ceramic substrate penetration.
- Direct-to-Object Printing:Robotic positioning systems target three-dimensional tile profiles and architectural specialty pieces with low-volume, high-margin economics.
UV Printing commands the steepest expansion trajectory; Solvent Printing retreats under regulatory pressure.
End User:
Procurement authority concentrates with volume aggregators while specification influence fragments across project-driven channels.
- Manufacturers:Integrated tile producers with captive kiln capacity prioritize equipment uptime and predictive maintenance contracts. Southeast Asian commercial real estate acceleration in Vietnam and Indonesia sustains mid-tier digital system demand for large-format production.
- Contractors:Project-driven procurement teams specify just-in-time manufacturing compatibility and cloud-based design platform integration before capital approval.
- Retailers:Distributor consolidation concentrates purchasing power through digital sample libraries and virtual visualization tools that bypass traditional manufacturer relationships.
- DIY Enthusiasts:Compact desktop systems serve customization markets with negligible industrial equipment overlap.
Manufacturers dominate absolute equipment purchases; Contractors are expanding specification influence fastest.
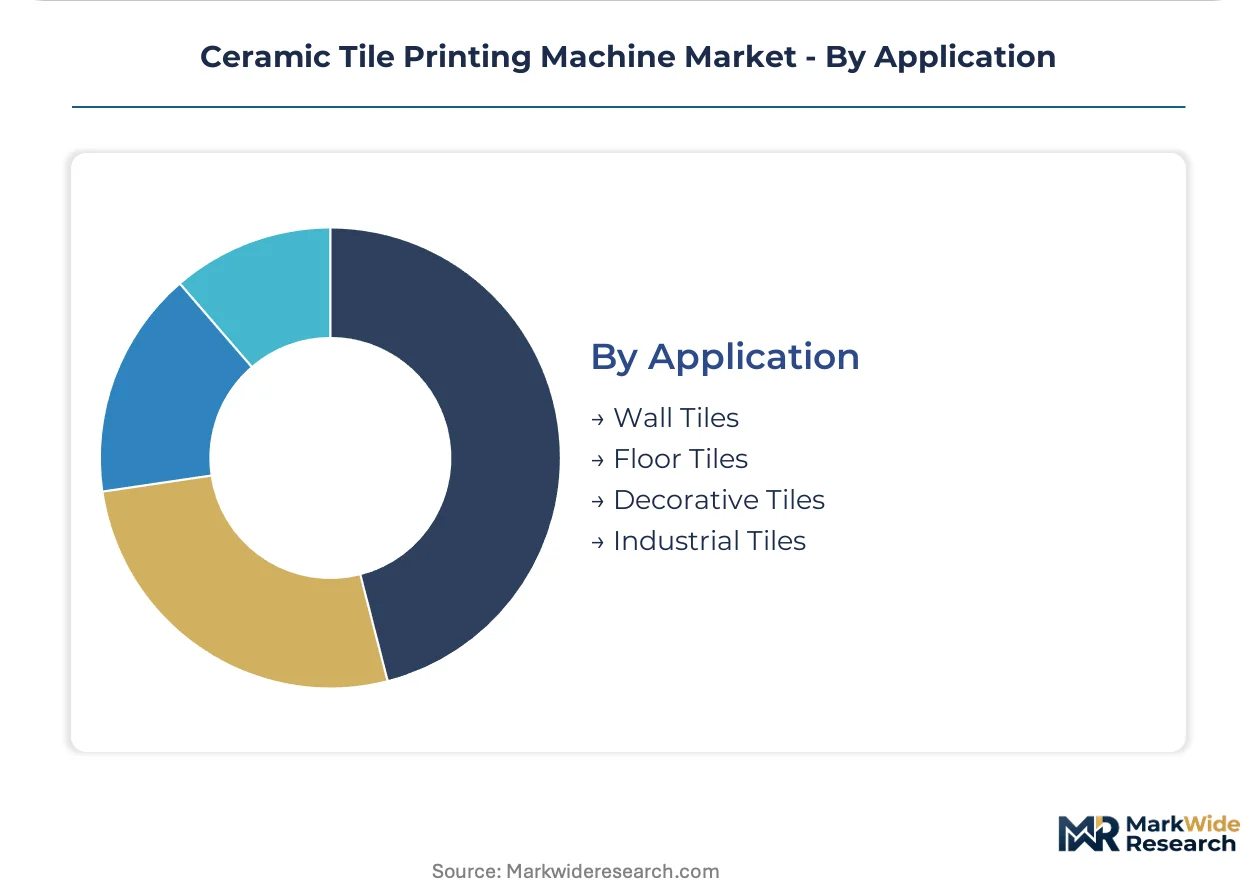
Application:
Surface location and aesthetic premium determine resolution requirements and margin capture potential across architectural specification tiers.
- Wall Tiles:Vertical surfaces tolerate lower abrasion resistance, enabling thinner glaze deposits and faster production speeds. India's government housing schemes and commercial real estate expansion sustain large-format wall tile line investments.
- Decorative Tiles:Bespoke surface aesthetics command superior margin pools as hospitality and luxury residential end-users prioritize photorealistic imagery and textured effects. EU Green Deal industrial decarbonization incentives subsidize energy-efficient equipment retrofits for premium decorative production.
- Floor Tiles:Abrasion resistance requirements drive thicker glaze applications and extended firing curves, constraining throughput relative to wall equivalents.
- Industrial Tiles:Chemical and mechanical durability specifications niche into commercial kitchen, laboratory, and heavy-traffic infrastructure applications.
Wall Tiles anchor current production volumes; Decorative Tiles capture the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian ceramic engineering talent clusters around Sassuolo and Modena anchor equipment design capabilities. German precision manufacturing expertise concentrates piezoelectric component supply. Indian installation technician pools expand alongside domestic production line growth.
Italy
Sassuolo's ceramic district sustains demand for high-resolution digital decoration systems serving architect-specified commercial projects. EU Green Deal industrial decarbonization incentives subsidize UV-LED curing retrofits across Emilia-Romagna production facilities. Modena-based engineering firms integrate inline spectrophotometric color measurement into single-pass architectures.
Germany
Precision nozzle manufacturing concentrates among Baden-Württemberg component specialists serving OEM assembly lines. REACH Annex XVII pigment restrictions drive reformulation partnerships between ink suppliers and Bavaria-based equipment fabricators. KBA oversight of industrial emissions shapes solvent-system compliance requirements for decoration line operators.
India
Housing for All central government subsidies sustain large-format wall and floor tile line investments across Gujarat and Maharashtra. BIS certification requirements for imported printing machinery create non-tariff barriers favoring domestic assembly partnerships. Morbi's ceramic cluster expands digital decoration capacity to serve commercial real estate acceleration.
China
Foshan's tile manufacturing concentration drives UV-curing technology adoption to circumvent MEE dual carbon constraints on kiln expansion. MIIT industrial upgrade programs subsidize energy-efficient equipment retrofits across Guangdong production bases. Yangtze River Delta fabricators integrate cloud-based design platform compatibility for contractor procurement teams.
Vietnam
Hospitality sector expansion and commercial real estate development in Ho Chi Minh City and Hanoi create demand for mid-tier digital systems. Shorter production run capabilities attract decorator segment investment alongside large-format manufacturer growth. Provincial industrial zones offer tariff advantages for equipment importation serving Southeast Asian export markets.
Ceramic Tile Printing Machine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Japanese and German component concentration upstream exposes OEMs to single-source vulnerability for precision nozzle supply. Three archetypes dominate: integrated ink-equipment platforms, UV-curing technology specialists, and mid-tier compact system providers. Consolidation pressure intensifies through strategic partnerships bridging ink chemistry and printhead architecture, while geographic expansion targets Southeast Asian manufacturing clusters.
Among diversified industrial technology groups, Epson and Renishaw occupy positions spanning precision motion control and imaging components. EFI exemplifies the integrated platform archetype through UV-curing specialization aligned with chemical compliance requirements. Roland DGA sits within the mid-tier decorator segment, representing compact digital system architecture engineered for shorter production run economics.
| Leading Market Players |
|---|
| Ntek |
| Roland DGA |
| EFI |
| Epson |
| IT Strategies |
| Neixo |
| Renishaw |
| Ferro Corporation |
| Meitu |
| Others |
Supply Flow & Price Mechanics
Equipment tier divergence between single-pass industrial systems and compact multi-pass units manifests in both capital expenditure structures and supply chain configurations. Premium single-pass architectures command bundled predictive maintenance contracts and captive ink supply agreements, while mid-tier decorator systems compete on unbundled hardware pricing with third-party consumable sourcing flexibility.
Pricing Analysis
Bundled service contracts versus unbundled hardware-only sales split the market into distinct procurement economics. Three-tier pricing structure across premium, standard, and economy levels tracks resolution specifications, printhead array density, and inline quality assurance integration. Price differentiation hinges on UV-LED curing module inclusion and REACH-compliant ink formulation bundling. Cost compression in the mid-tier decorator segment intensifies as Southeast Asian manufacturers localize assembly and reduce import duty exposure. Contractor-driven procurement teams exhibit highest price sensitivity due to project-based financing constraints, while integrated tile manufacturers prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for piezoelectric printhead arrays compel OEMs to qualify secondary nozzle suppliers beyond Japanese and German component specialists. Manufacturing concentrates in Italy for system integration engineering, Germany for precision motion control components, and China for UV-LED curing module fabrication. Raw material dependencies span rare earth pigments for REACH-compliant colorants, silicon wafer substrates for MEMS nozzle fabrication, and specialty photoinitiators for UV ink polymerization. Single-source vulnerability in precision nozzle manufacturing exposes equipment assemblers to extended lead time risk. Distribution runs through direct OEM sales forces for large-format tile producers and regional distributor networks for mid-tier decorator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic tile printing equipment functions as a stable compounder anchored by residential construction cycles and regulatory-driven replacement demand. India's Housing for All schemes and EU chemical compliance deadlines sustain predictable equipment refresh intervals across divergent geographies.
For Market Incumbents: Acquire captive ink formulation capabilities to reduce third-party pigment exposure under tightening REACH Annex XVII restrictions. Consolidate predictive maintenance service contracts to lock in recurring revenue streams and raise switching costs for integrated tile manufacturers. Defend against Chinese UV-curing module suppliers by deepening backward integration into LED driver electronics and photoinitiator chemistry partnerships.
For New Entrants and Emerging Players: Launch via cloud-based design platform integration targeting contractor procurement teams in Vietnam and Indonesia hospitality construction. White-space opportunity concentrates in mid-tier digital systems serving shorter production run economics for Southeast Asian commercial real estate acceleration. Penetrable entry point sits with compact multi-pass architectures for Morbi-based tile decorators seeking BIS-compliant domestic assembly partnerships.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated ink-equipment platform specialists possessing REACH-compliant formulation capabilities and UV-curing technology depth. Long-term viability favors vendors with demonstrated installation technician training infrastructure and aftermarket parts logistics spanning India and Southeast Asia. Signal to watch is BIS certification timeline clarity for imported machinery, which would unlock project financing velocity and accelerate capital deployment into Indian manufacturing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | Captive pigment chemistry reduces REACH compliance exposure and secures margin capture from consumable recurring revenue. |
| UV-LED Curing Retrofit Programs | EU Green Deal subsidies accelerate equipment refresh cycles across Italian and Spanish production facilities. |
| Cloud-Based Design Platform Integration | Contractor specification influence concentrates purchasing power through distributor digital sample libraries. |
| Domestic Assembly Partnership in India | BIS certification barriers favor localized manufacturing footprints serving Gujarat and Maharashtra tile clusters. |
| Predictive Maintenance Service Contracts | Integrated manufacturers prioritize uptime guarantees over capital expenditure minimization in procurement decisions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory assumptions. Primary fieldwork engaged equipment OEM product managers, tile plant maintenance directors, ceramic ink formulation chemists, and distributor specification sales engineers across Italy, Germany, India, and China. Secondary validation drew from SEC filings of listed industrial technology groups, EU ECHA REACH substance restriction updates, Indian BIS machinery certification registries, and Chinese MIIT industrial equipment subsidy disclosures. Bottom-up unit shipment estimates from regional production line installations converged with top-down addressable market calculations based on tile manufacturing capacity expansion announcements.
Segment-weighting approaches distributed total market value across product type, technology, application, and end user dimensions with geographic production cluster adjustments. Modeled variables included digital printer versus analog rotary screen penetration rates, UV-curing versus solvent-based technology mix shifts, and wall tile versus decorative tile application splits. CAGR derivation rested on production line investment cycles, regulatory compliance deadline schedules, and housing construction program funding trajectories. Industry-specific forecast inputs incorporated kiln curing capacity constraints under China's MEE dual carbon goals and REACH pigment reformulation cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt BIS certification timeline extensions or sudden piezoelectric printhead supply disruptions. Projections reflect assumptions regarding sustained Indian government housing subsidy continuity and EU Green Deal industrial decarbonization funding persistence. Deviation in Chinese energy transition enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Piling Machine Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Snow Removal Market
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Walform Machines Market