
 Compact Electric Construction Equipment Market | 2026-2036
Compact Electric Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Electric Construction Equipment Market Intelligence
Equipment-as-a-service leasing is narrowing the capital barrier between rental fleets and direct OEM purchases. Volvo Construction Equipment leverages its captive finance arm to anchor long-term lease penetration in European urban markets. Caterpillar competes through dealer network density, while Sany Group extends manufacturing scale advantages across battery pack integration.
Compact electric construction equipment denotes machinery under 10 metric tons powered by lithium-ion battery packs or hybrid-electric architectures, delivering hydraulic or direct-drive force for earthmoving and material transport with zero tailpipe emissions. Battery-operated excavators dominate unit shipments, though hybrid systems retain share in heavy-cycle applications where charging infrastructure remains sparse. Smart controls represent the fastest-growing technology segment as telematics-enabled fleet management shifts from premium option to baseline procurement requirement among rental services and municipalities.
The EPA's Tier 4 Final emissions standards and the EU Green Deal's construction decarbonization pathways jointly mandate electrification timelines for non-road mobile machinery. China's MIIT enforces GB energy-efficiency certifications that restrict market access for conventional diesel compact equipment in designated low-emission zones. Stakeholders must monitor how municipal procurement rules in Japan's METI-designated smart cities and India's CEA power-grid standards reshape charging infrastructure deployment and equipment duty-cycle specifications.
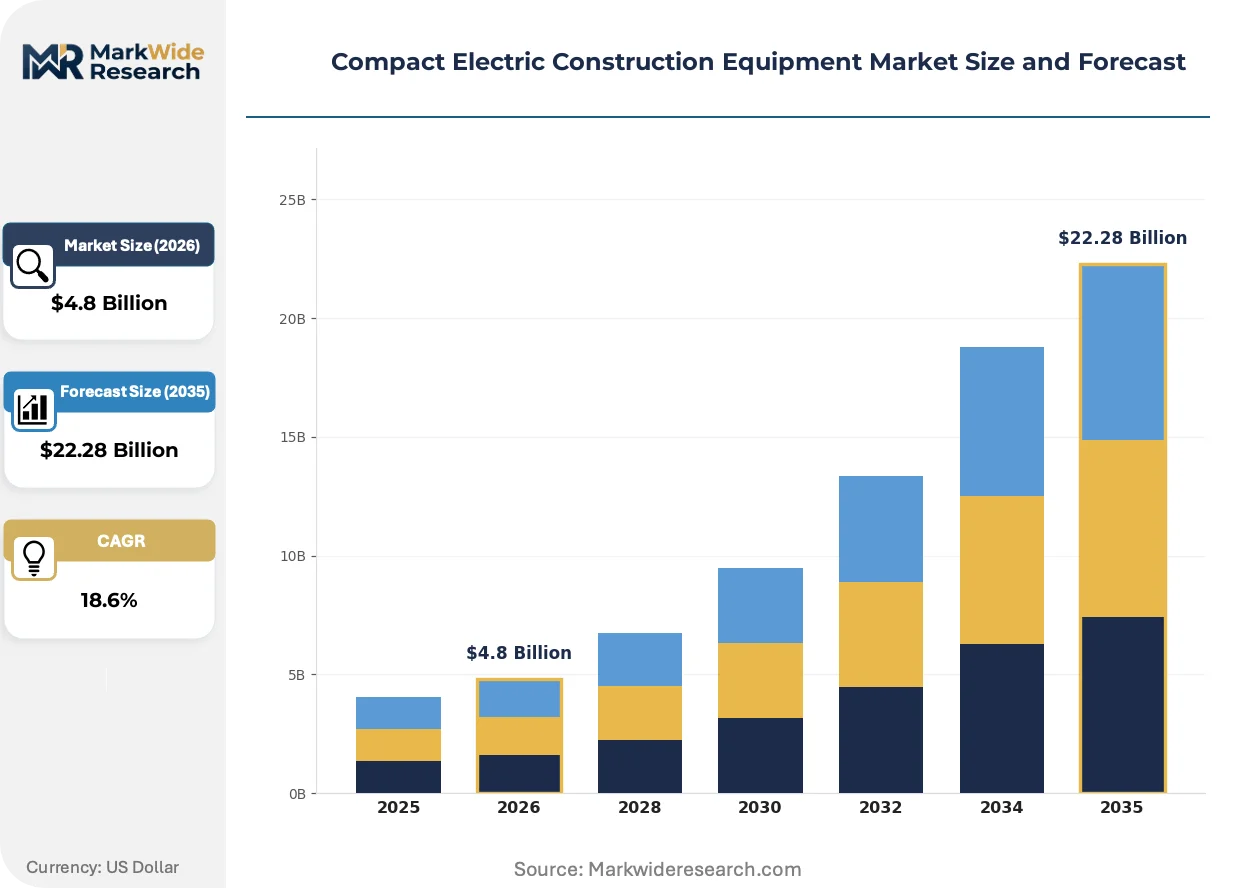
Market Dynamics
Equipment-as-a-service leasing is compressing the capital barrier between rental fleets and direct OEM purchases, forcing manufacturers to restructure pricing and captive finance operations around utilization-based contracts rather than unit sales.
Growth Catalysts
- EU F-Gas Regulation:National diesel bans across Germany, France, and the Netherlands are accelerating OEM shifts to electric drivetrains for compact excavators and wheel loaders.
- Municipal green procurement mandates:Tier-one municipalities in China now prioritize zero-emission equipment in public construction tenders, creating guaranteed demand pools for battery-operated machinery.
- Lithium-ion battery pack cost curves:Energy density improvements and manufacturing scale are narrowing the total-cost-of-ownership gap against diesel equivalents in urban construction cycles.
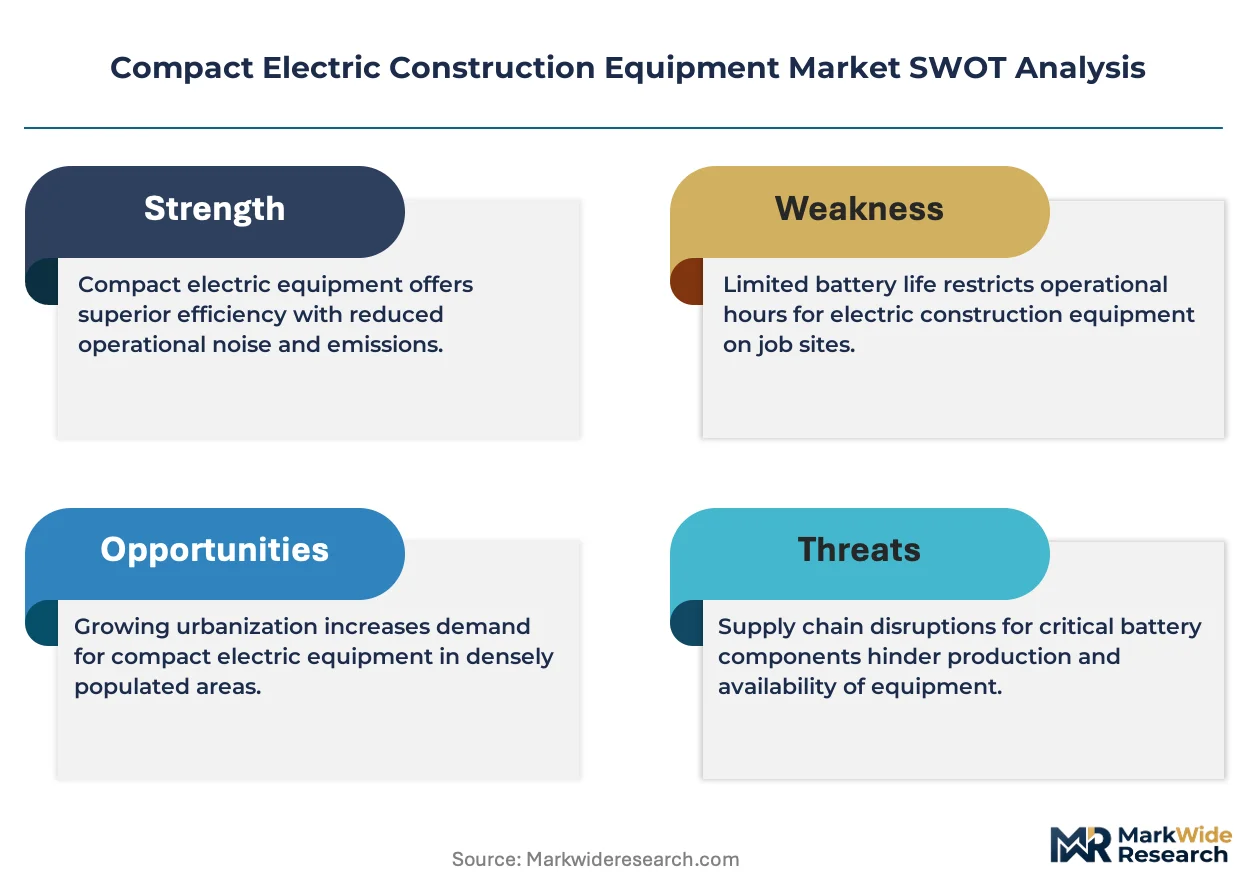
Market Restraints
- Charging infrastructure gaps:Sparse grid capacity at remote construction sites limits pure-electric deployment in heavy-cycle earthmoving applications.
- Cathode material concentration:Processing of lithium, cobalt, and nickel concentrates in a narrow supplier base creates input cost volatility and supply security exposure.
- Battery degradation uncertainty:Residual value risk for second-life equipment fleets dampens secondary market liquidity and finance lease terms.
Strategic Opportunities
- Japan's METI-designated smart cities:Municipal procurement rules in designated urban zones are reshaping charging infrastructure deployment specifications for compact equipment duty cycles.
- Telematics-enabled fleet management:Convergence of IoT sensors and predictive maintenance platforms is shifting smart controls from premium option to baseline procurement requirement among rental services.
- India's CEA power-grid standards:Grid interconnection norms for construction site charging are creating openings for equipment-integrated energy storage and vehicle-to-grid services.
Industry Challenges
- High-voltage technician scarcity:Safe maintenance of battery-electric drivetrains requires specialized training programs that OEM service networks are racing to scale.
- GB energy-efficiency certification timelines:China's MIIT enforcement windows create compliance bottlenecks as manufacturers revalidate diesel-equivalent performance benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Electric Construction Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Forklifts, Graders Technology: Battery Operated, Hybrid Systems, Electric Motors, Smart Controls End User: Construction Firms, Rental Services, Landscaping Companies, Municipalities Application: Site Preparation, Road Construction, Material Handling, Urban Development |
| Companies Covered | Komatsu Ltd., Sany Group, Caterpillar, Wacker Neuson, Hitachi Construction Machinery, Volvo Construction Equipment, Doosan Bobcat, Hyundai Construction Equipment, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Electric Construction Equipment Market Strategic Shifts & Innovations
Digital twin architectures are virtualizing equipment commissioning and operator training, compressing deployment timelines while reducing field failure rates. Three interconnected developments are reshaping competitive positioning.
Digital twin simulation platforms are virtualizing pre-delivery testing and remote operator certification for battery-electric excavators. Rental fleet operators in Germany and the Netherlands are adopting these tools to accelerate technician readiness without physical machine access. This virtualization is compressing training costs and reducing warranty claims from operator error.
The EPA's Tier 4 Final emissions standards and the EU Green Deal's construction decarbonization pathways jointly mandate electrification timelines for non-road mobile machinery. OEMs must now certify zero-emission equivalents alongside conventional diesel models to maintain market access. Compact excavator segments in urban German and French markets face the steepest compliance cliffs.
Outcome-based equipment contracts are displacing traditional lease structures in European municipal fleets. Contractors now pay per cubic meter moved rather than monthly machine rental, transferring utilization risk to OEMs and their captive finance arms. This shift is most visible in noise-restricted urban construction zones where battery-electric uptime guarantees command premium positioning.
Compact Electric Construction Equipment Market Segmentation
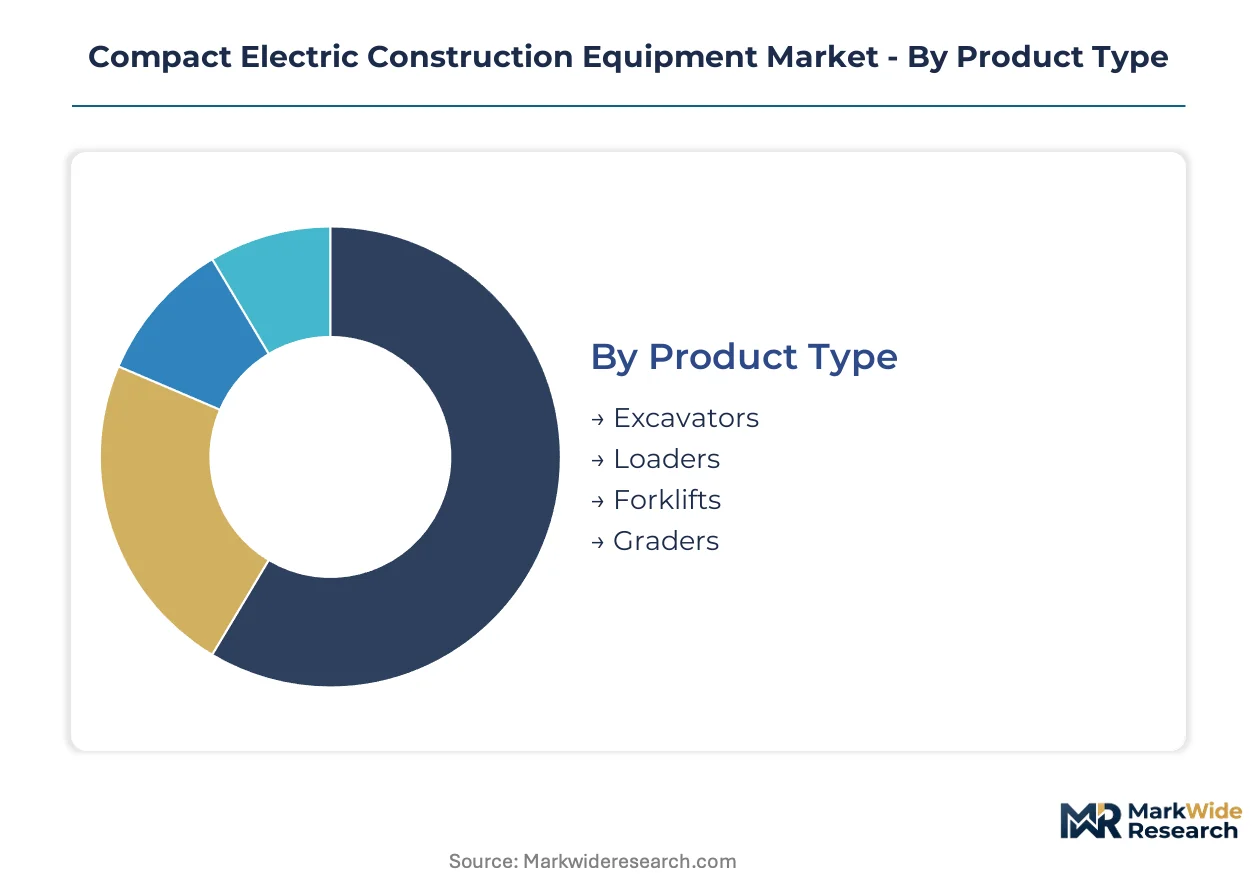
Segmentation in compact electric construction equipment reveals how electrification timelines diverge across duty cycles and customer capital structures. Product type and technology splits determine battery sizing and charging infrastructure requirements, while end-user segmentation exposes financing model preferences that reshape OEM go-to-market strategies.
Product Type:
Cost tier differentiation separates premium battery-electric platforms from value-positioned hybrid alternatives across equipment categories.
- Excavators:Battery-operated units under 10 metric tons dominate urban demolition and utility trenching where EU F-Gas Regulation compliance is mandatory. German construction firms in noise-restricted zones prioritize these for overnight work permits.
- Loaders:Wheel loaders with lithium-ion packs face charging infrastructure constraints at remote sites, limiting pure-electric deployment to municipal fleets with depot charging. Hybrid architectures retain share in heavy-cycle material transport.
- Forklifts:Warehouse and logistics applications drive standardized battery swap protocols.
- Graders:Precision road finishing demands sustained power output challenging current cell chemistry limits.
Excavators hold installed capacity. Loaders are rotating up the share rankings.
Technology:
Application severity determines whether pure battery-electric architectures or hybrid-electric systems match duty-cycle requirements.
- Battery Operated:Lithium-ion packs with 200-400 kWh capacity deliver zero tailpipe emissions for full-shift urban operations. China's tier-one municipalities mandate these for public tender eligibility under green procurement rules.
- Hybrid Systems:Diesel-electric architectures preserve range autonomy where grid capacity is sparse, dominating heavy earthmoving in India's CEA-designated weak-grid zones.
- Electric Motors:Permanent magnet synchronous designs enable direct-drive force transmission without hydraulic losses.
- Smart Controls:Telematics-enabled fleet management platforms integrate predictive maintenance and remote diagnostics.
Hybrid Systems anchor current revenue. Smart Controls are climbing the fastest as baseline procurement requirements spread.
End User:
Customer type segmentation exposes divergent capital constraints and utilization patterns that determine financing structure preferences.
- Construction Firms:Mid-sized contractors in Germany and France face diesel ban compliance deadlines, accelerating equipment-as-a-service adoption to preserve balance sheet capacity. Outcome-based contracts per cubic meter moved transfer utilization risk to OEM captive finance arms.
- Rental Services:Fleet operators demand telematics standardization for cross-brand fleet management, compressing training costs through digital twin virtualization platforms.
- Landscaping Companies:Seasonal utilization patterns favor short-term lease structures over capital purchase.
- Municipalities:Public procurement mandates in China's low-emission zones create guaranteed demand pools with standardized charging infrastructure specifications.
Rental Services hold installed capacity. Municipalities are rotating up the share rankings.
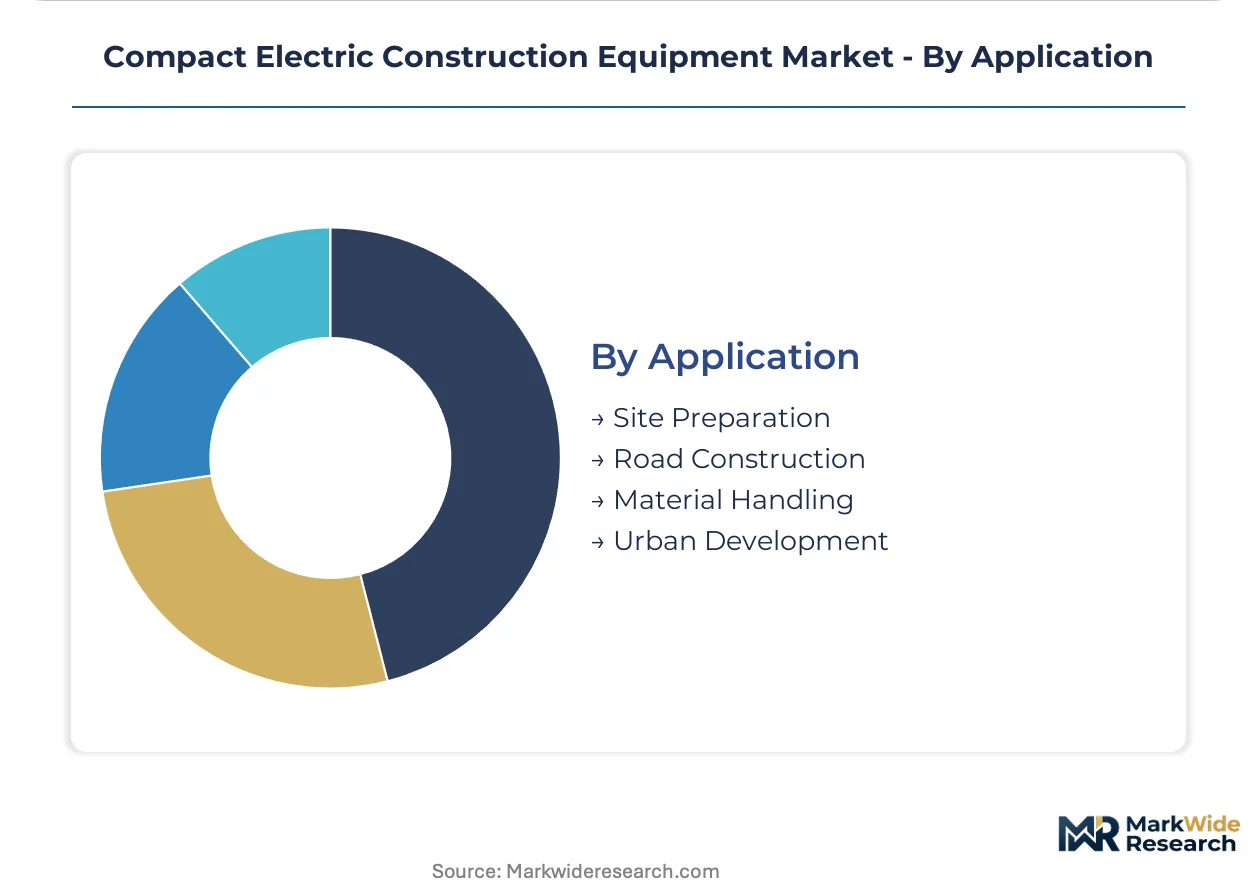
Application:
Volume intensity and site accessibility determine whether pure-electric or hybrid architectures satisfy duty-cycle economics.
- Site Preparation:Heavy-cycle earthmoving in remote locations faces charging infrastructure gaps, preserving hybrid system share despite EU Green Deal decarbonization pathways.
- Road Construction:Linear project geography complicates charging logistics, though Japan's METI-designated smart cities are reshaping grid interconnection specifications for mobile charging trailers.
- Material Handling:Fixed-site operations with predictable duty cycles enable battery swap standardization.
- Urban Development:Noise-restricted zones in German and Dutch cities command premium positioning for battery-electric uptime guarantees.
Site Preparation holds installed capacity. Urban Development is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal divergent electrification trajectories across major construction economies. Germany and China run equipment trade surpluses in battery-electric compact machinery, while the United States and India remain net importers of zero-emission drivetrain components. Japan maintains balanced trade in hybrid-electric systems.
Germany
Bavarian construction consortiums and North Rhine-Westphalian municipal fleets drive procurement of battery-operated excavators for noise-restricted urban zones. The KBA enforces national diesel bans that accelerate OEM compliance deadlines for compact equipment categories. Stuttgart's industrial corridor hosts validation centers for battery pack integration in earthmoving machinery.
China
Shanghai and Beijing municipal tenders create guaranteed demand pools for zero-emission compact excavators under green procurement mandates. MIIT enforces GB energy-efficiency certifications that restrict market access for conventional diesel equipment in designated low-emission zones. The Yangtze River Delta concentrates battery pack manufacturing scale for construction equipment integration.
United States
California's construction firms face the nation's strictest emissions compliance deadlines for non-road mobile machinery. The EPA's Tier 4 Final standards mandate electrification timelines that OEMs must meet to maintain market access. Texas energy sector contractors test hybrid-electric loaders in remote site preparation applications.
Japan
Tokyo and Osaka metropolitan construction authorities specify charging infrastructure requirements for compact equipment duty cycles. METI-designated smart cities reshape grid interconnection standards for battery-electric machinery in urban development zones. Nagoya's manufacturing belt supplies permanent magnet synchronous motors for direct-drive excavator architectures.
India
Maharashtra and Delhi-NCR municipal corporations pilot battery-electric compact loaders in material handling applications. The CEA establishes power-grid interconnection norms for construction site charging that enable equipment-integrated energy storage. Gujarat's industrial zones test hybrid systems in weak-grid zones where charging infrastructure remains sparse.
Compact Electric Construction Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in battery pack and electric motor supply. The vendor base organizes around three tiers: full-line OEMs with captive finance arms, regional specialists with manufacturing scale advantages, and technology licensors providing drivetrain architectures. Consolidation pressures concentrate among mid-tier players lacking vertical integration into battery cell supply or telematics platforms. M&A activity targets charging infrastructure operators and predictive maintenance software providers.
Among Asian-headquartered platform integrators, Komatsu Ltd. and Sany Group occupy positions reflecting divergent geographic anchoring strategies. Volvo Construction Equipment and Caterpillar represent contrasting approaches to equipment-as-a-service penetration in European and North American urban markets. Wacker Neuson exemplifies the mid-cap specialist archetype with concentrated exposure to compact equipment categories.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Sany Group |
| Caterpillar |
| Wacker Neuson |
| Hitachi Construction Machinery |
| Volvo Construction Equipment |
| Doosan Bobcat |
| Hyundai Construction Equipment |
| JCB |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Yangtze River Delta battery pack manufacturing is compressing cell pricing and forcing OEMs to renegotiate long-term offtake terms while absorbing cathode material volatility into equipment list prices.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium battery-electric platforms, standard hybrid architectures, and economy-grade refurbishment programs. Price differentiation rests on GB energy-efficiency certification tier and captive after-sales service bundling. Cost compression in standard hybrid tiers is intensifying because lithium carbonate spot volatility feeds directly into pack cost pass-through clauses. Municipal fleet operators exhibit lowest price sensitivity due to green procurement mandate compliance deadlines, while mid-sized German construction firms face acute capital constraints.
Supply Chain Analysis
CATL and BYD dominate contract manufacturing capacity for construction equipment-integrated battery packs, with LG Energy Solution anchoring South Korean supply for premium European OEM programs. Manufacturing concentrates in China, South Korea, and Japan for cell production, with Germany and the United States hosting pack assembly and thermal management integration. Raw material dependencies center on lithium hydroxide, nickel sulfate, and cobalt concentrate from Indonesian and Chilean processing hubs. Single-source vulnerability in cathode precursor supply creates exposure to export licensing shifts. Distribution runs through OEM captive finance arms and authorized dealer networks with telematics-enabled fleet management attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance subscriptions and battery health monitoring contracts expand faster than underlying equipment hardware sales.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into battery cell supply through joint ventures with Chinese or South Korean manufacturers, and by locking municipal fleet operators into decade-long uptime guarantee contracts that transfer residual value risk from buyers. Diesel ban compliance cliffs in Germany and the Netherlands threaten stranded asset exposure for rental fleets lacking electric alternatives.
For New Entrants and Emerging Players: Build out charging infrastructure-as-a-service offerings targeting India's CEA-designated weak-grid zones where hybrid-to-electric transition timelines lag urban markets by several years. India's state-level municipal corporations present the most penetrable customer segment given limited incumbent service density. A telematics-first go-to-market angle bypasses capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among rental fleet operators with equipment-as-a-service penetration above threshold levels, suggesting superior cash flow quality versus pure manufacturing plays. Long-term viability hinges on backward integration depth and software-defined service attach rates. Acquisition targets should display captive battery supply agreements or proprietary digital twin platforms. Monitor Japan's METI smart city procurement award volumes as an early inflection signal for charging infrastructure deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and LG Energy Solution offtake contracts secure cell allocation for EU F-Gas Regulation compliance deadlines. |
| Charging Infrastructure Partnership | Collaborations with India's CEA-standardized grid operators unlock weak-zone deployment without utility upgrade delays. |
| Platform Integration | Telematics convergence with predictive maintenance software shifts smart controls from premium option to baseline procurement requirement. |
| Acquisition of Specialist Firm | Digital twin virtualization platforms compress technician training costs and warranty exposure for rental fleet operators. |
| Geographic Manufacturing Footprint | Stuttgart-area validation centers anchor German market access under national diesel ban enforcement windows. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement managers, OEM platform engineers, aftermarket service heads, and municipal tender officers; and secondary validation against customs trade records, MIIT GB certification filings, EPA Tier 4 Final compliance databases, and EU Green Deal construction decarbonization pathway documents. Bottom-up equipment shipment modeling and top-down construction expenditure allocation were triangulated against regional regulatory enforcement timelines.
Forecast inputs considered product type splits across excavators, loaders, and graders; technology architectures spanning battery-electric, hybrid, and smart control platforms; and end-user capital structure variations across rental services, municipal fleets, and direct contractor purchases. CAGRs were derived from segment-level adoption curves weighted by charging infrastructure deployment density and diesel ban phase-in schedules. Duty-cycle specifications and battery degradation assumptions shaped residual value modeling.
Practitioners should monitor lithium carbonate spot price movements, GB certification enforcement window delays, and METI smart city procurement award volumes for early signals of forecast revision. Quarterly review of cathode material export licensing shifts and CEA grid interconnection standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Arc Welding Equipment Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Rotomolding Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Press Brakes Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Scaffold Technology Market
Construction Equipment
Roadheaders Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market