
 Portable Chamfering Machines Market | 2026-2036
Portable Chamfering Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Chamfering Machines Market Analytics
ISO 9001 certification requirements for edge-preparation quality in precision metal fabrication is unwinding the competitive landscape for portable chamfering equipment. Ridgid leverages its deep channel presence in North American maintenance sectors to sustain replacement demand. Nitto Kohki anchors its position through specialized pneumatic tool engineering for Japanese shipbuilding applications. Euroboor competes aggressively on magnetic drilling and chamfering combinations that dominate European structural steel workflows.
Portable chamfering machines are handheld or mobile devices that remove material from edges and corners of metal, wood, or composite workpieces using rotating cutters, abrasive wheels, or formed blades, typically operating at spindle speeds between 3,000 and 30,000 RPM depending on workpiece hardness and desired finish. Their primary industrial purpose is to create beveled edges that improve weld penetration, reduce stress concentrations, eliminate sharp hazards, and prepare surfaces for coating adhesion in fabrication and assembly environments. Electric models lead unit volumes across manufacturing end users where consistent shop power supports continuous production, while battery-operated configurations represent the fastest-growing power source segment as lithium-ion energy density improvements enable cord-free mobility on construction sites and in maintenance bays. Metalworking applications command the largest application share due to structural steel and pipeline fabrication standards, though aerospace applications concentrate the highest margin pools because of tight tolerances and superalloy machining requirements.
FDA oversight of medical device manufacturing cleanliness standards indirectly shapes demand for precision edge-finishing in surgical instrument supply chains, while OSHA workplace safety rules on sharp-edge hazards mandate chamfering in fabricated metal goods destined for industrial environments. REACH chemical restrictions in Europe limit certain coating pretreatments, pushing fabricators toward mechanical edge preparation methods including chamfering as a compliant alternative. Stakeholders must monitor how evolving battery transport regulations and cordless tool certification standards reshape power source preferences and distribution channel requirements across key fabrication clusters.
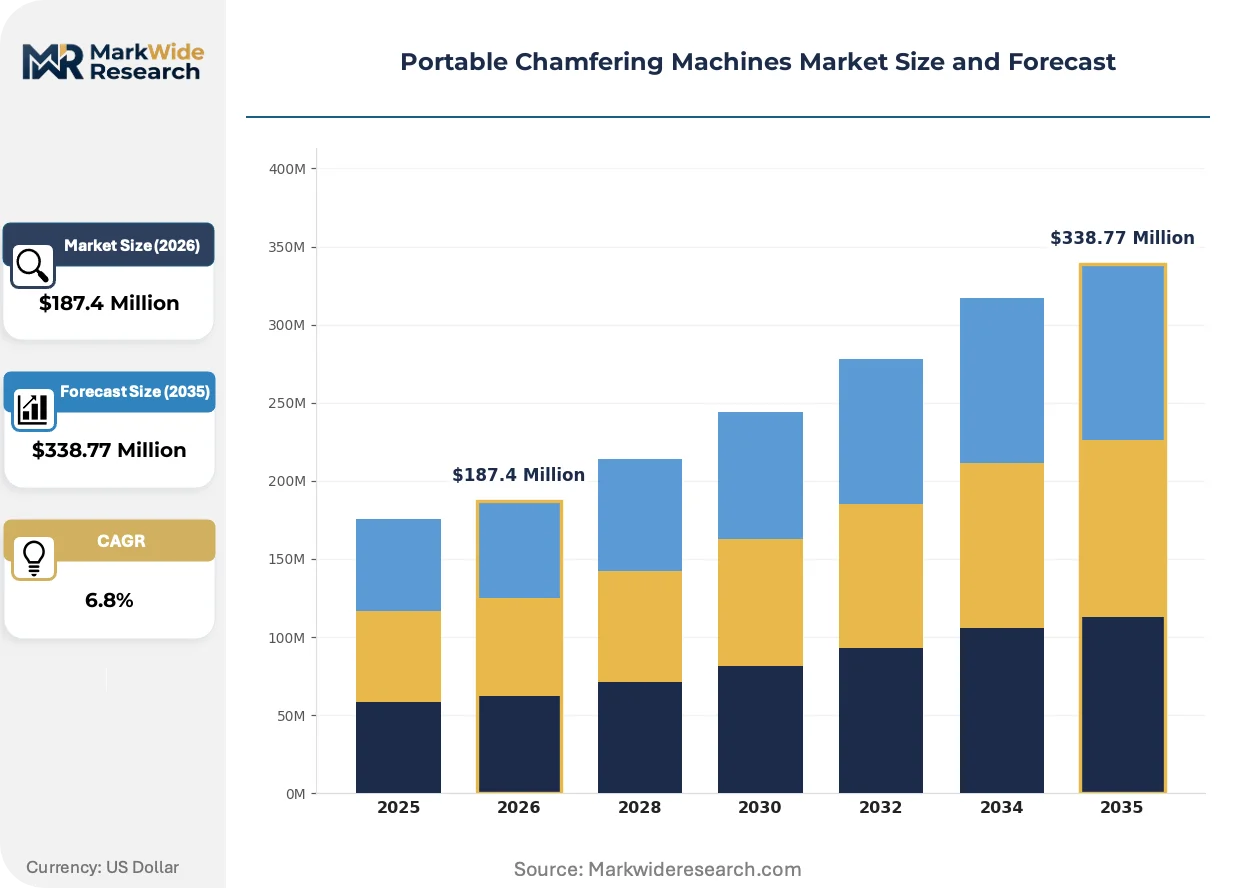
Market Dynamics
ISO 9001 certification mandates for edge-preparation quality are compressing procurement cycles across precision metal fabrication, forcing buyers to standardize on certified equipment configurations that guarantee repeatable bevel geometries and surface finish documentation.
Growth Catalysts
- REACH chemical restrictions:European fabricators are abandoning solvent-based coating pretreatments in favor of mechanical edge preparation, directly expanding chamfering machine deployment in German and Dutch structural steel workshops.
- Japanese shipbuilding:METI efficiency directives favoring cordless shop-floor equipment are accelerating battery-operated model adoption in Yokohama and Nagasaki shipyard clusters.
- Lithium-ion energy density improvements:Cord-free mobility now extends to full-shift operation on construction sites, unlocking demand from pipeline maintenance contractors previously tethered to pneumatic supply infrastructure.
Market Restraints
- Neodymium magnet supply concentration:Rare earth processing dominance in Chinese refining operations creates input cost volatility for magnetic-base chamfering units.
- OSHA silica exposure rules:Dry grinding operations face heightened compliance scrutiny, forcing capital investment in dust extraction systems that inflate total cost of ownership.
- CNC machining center substitution:Integrated five-axis fabrication cells with automated edge-breaking capabilities capture high-volume chamfering tasks in aerospace tier-one supplier facilities.
Strategic Opportunities
- Indian PLI scheme for capital goods:Domestic manufacturing incentives are attracting assembly operations for export-focused portable chamfering equipment serving Middle East pipeline construction.
- Aerospace superalloy applications:Inconel and titanium edge-finishing requirements create premium pricing pools for thermal management optimized spindle designs.
- Rental/channel partner models:Construction equipment leasing platforms in Australia are bundling chamfering tools with magnetic drills for structural steel contractors on project-based contracts.
Industry Challenges
- CE marking timeline compression:EU machinery directive conformity assessment delays for battery-operated variants are extending time-to-revenue for new product introductions.
- Spindle bearing specialist scarcity:Precision high-speed bearing procurement requires qualified supplier relationships that smaller fabricators struggle to establish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Chamfering Machines Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Manual, Hydraulic Application: Metalworking, Woodworking, Automotive, Aerospace Power Source: Battery-operated, AC-powered, Solar-powered, Gas-powered End User: Manufacturing, Construction, Maintenance, Tool Rental |
| Companies Covered | Ridgid, Nitto Kohki, Promotech, Euroboor, Baileigh Industrial, Assfalg GmbH, GERIMA GmbH, PROTEM, BDS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Chamfering Machines Market Evolving Landscape
Power source diversification and connected tool telemetry are rewriting equipment specification criteria, with buyers now prioritizing runtime analytics and fleet management compatibility alongside cutting performance.
Brushless DC motor architecture is fragmenting the traditional power source hierarchy across portable chamfering equipment. Maintenance departments in German automotive stamping plants are specifying these configurations for their thermal efficiency and reduced brush maintenance intervals. The technology is fragmenting supplier tiers by enabling mid-tier manufacturers to match incumbent performance specifications without legacy pneumatic infrastructure investments.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-driven cooling system redesigns in high-duty-cycle chamfering applications. Equipment manufacturers serving Italian pressure vessel fabricators must now certify thermal management systems for lower global warming potential working fluids. This regulatory pressure is concentrating R&D spending among suppliers with in-house compressor engineering capabilities.
Buyer preference for outcome-based maintenance agreements is displacing traditional parts-and-labor service contracts in North American energy sector procurement. Pipeline construction contractors in Texas and Alberta are negotiating guaranteed uptime arrangements that bundle consumables, preventive maintenance, and rapid exchange units. This contracting evolution favors suppliers with regional parts depots and certified technician networks over import-dependent distributors.
Portable Chamfering Machines Market Segmentation
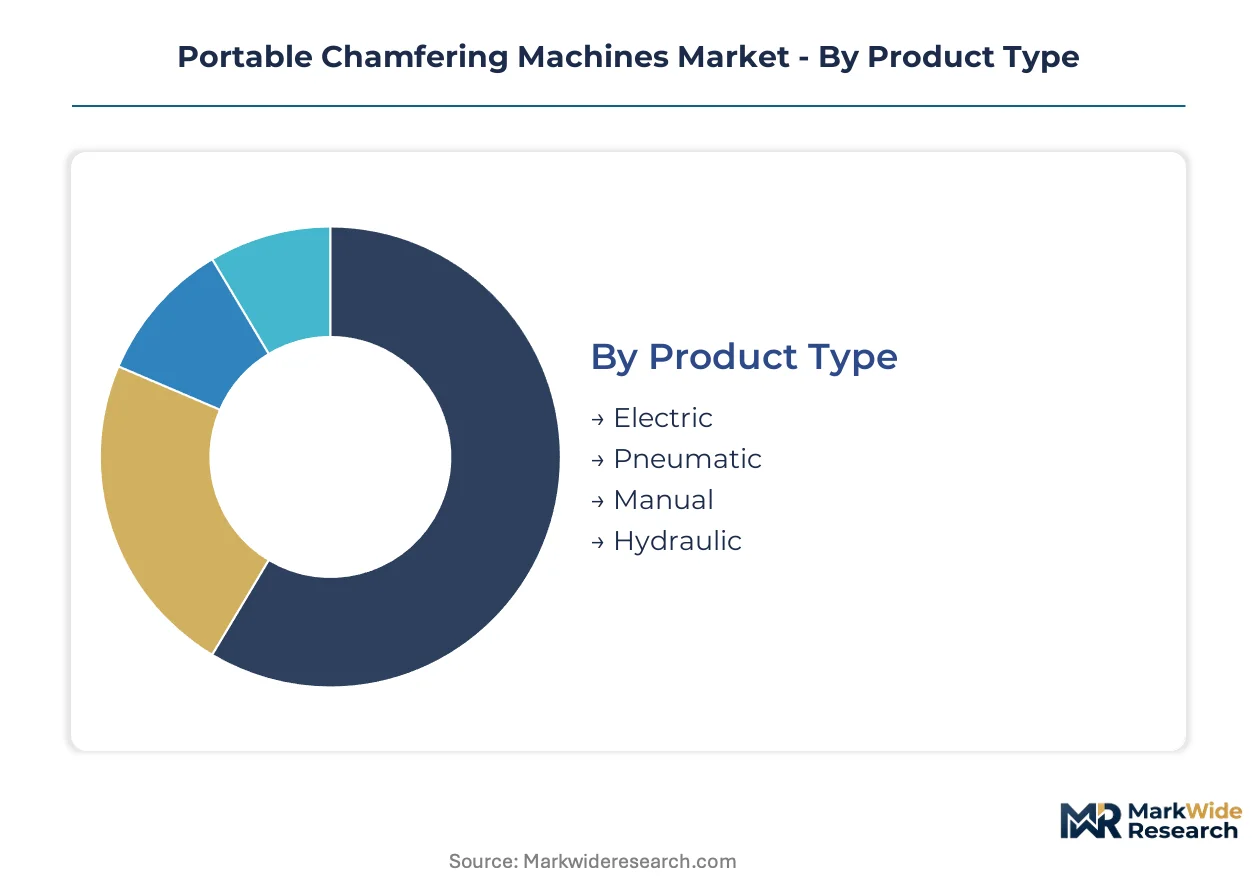
Portable chamfering equipment specification varies sharply across fabrication environments, with power source configuration and application severity dictating performance requirements and total cost of ownership. Procurement patterns diverge between high-volume manufacturing facilities prioritizing throughput consistency and mobile maintenance crews demanding runtime flexibility.
Product Type:
Margin pools concentrate in electric and pneumatic configurations where specialized motor engineering and precision spindle design create defendable technology positions.
- Electric:Brushless DC motor architectures deliver thermal efficiency and extended maintenance intervals for German automotive stamping plants. Continuous shop-floor operation demands consistent spindle speed control across 3,000-30,000 RPM ranges. ISO 9001 documentation requirements favor these units for certified edge-preparation workflows.
- Pneumatic:Compressed-air systems dominate Japanese shipbuilding clusters in Yokohama and Nagasaki where METI efficiency directives favor established pneumatic infrastructure. Nitto Kohki anchors market position through specialized tool engineering for marine fabrication tolerances.
- Manual:Hand-cranked units serve occasional edge-breaking in small fabrication shops with intermittent demand and capital constraints.
- Hydraulic:High-torque configurations address heavy plate beveling in pipeline construction where pneumatic supply lines prove impractical.
Electric holds installed capacity. Battery-operated derivatives are rotating up the share rankings.
Application:
Volume concentration sits with structural steel fabrication, while aerospace commands premium pricing through superalloy machining complexity.
- Metalworking:Structural steel and pipeline fabrication standards mandate edge preparation for weld penetration and coating adhesion. REACH chemical restrictions in Germany and the Netherlands accelerate mechanical chamfering substitution for solvent-based pretreatments. Ridgid sustains replacement demand through deep channel presence in North American maintenance sectors.
- Aerospace:Inconel and titanium edge-finishing requirements demand thermal management optimized spindle designs. Tight tolerances and superalloy specifications create the highest margin pools in the application matrix. Euroboor competes on magnetic drilling and chamfering combinations for European tier-one supplier facilities.
- Woodworking:Furniture and millwork applications prioritize dust extraction integration over precision tolerances.
- Automotive:Stamping plant maintenance departments specify brushless configurations for reduced downtime and thermal efficiency.
Metalworking dominates unit economics. Aerospace is climbing the fastest on value contribution.
Power Source:
Runtime analytics and fleet management compatibility now rival cutting performance in procurement criteria.
- Battery-operated:Lithium-ion energy density improvements enable full-shift cord-free mobility on construction sites and in maintenance bays. Pipeline contractors in Texas and Alberta previously tethered to pneumatic infrastructure now specify these configurations. METI efficiency directives in Japan explicitly favor cordless shop-floor equipment adoption.
- AC-powered:Consistent shop power supports continuous production in manufacturing end users where runtime predictability outweighs mobility requirements. Brushless DC architecture fragmentation enables mid-tier manufacturers to match incumbent specifications without legacy infrastructure investments.
- Solar-powered:Remote site applications with intermittent grid access explore photovoltaic charging for auxiliary power.
- Gas-powered:Off-grid pipeline maintenance in frontier basins employs small combustion engines where battery energy density remains insufficient.
AC-powered retains manufacturing dominance. Battery-operated is expanding most quickly in construction and maintenance segments.
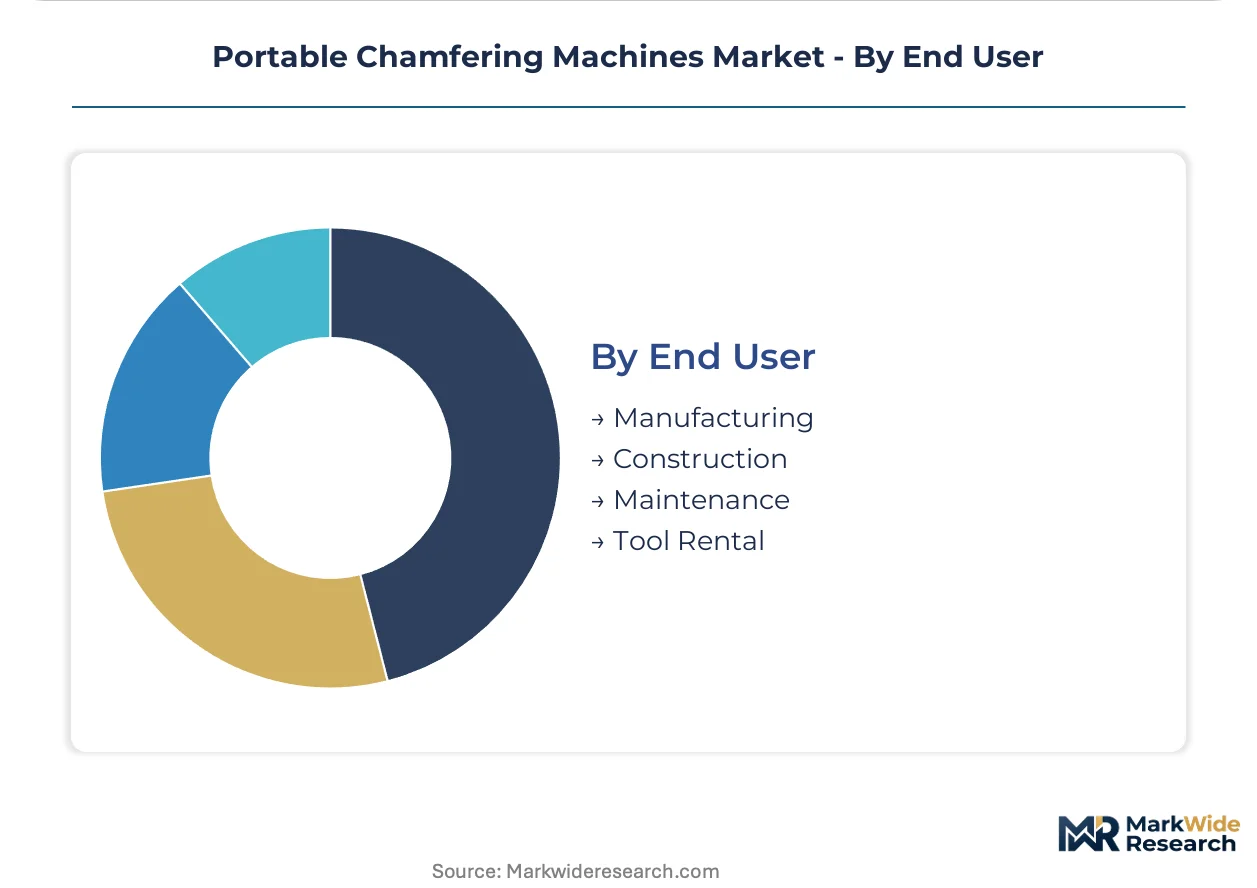
End User:
Contracting evolution toward outcome-based maintenance agreements reshapes supplier qualification requirements across energy sector procurement.
- Manufacturing:High-volume fabrication cells demand certified equipment configurations guaranteeing repeatable bevel geometries and surface finish documentation. ISO 9001 mandates compress procurement cycles toward standardized platforms. German metal fabrication shops drive adoption as quality mandates tighten.
- Construction:Project-based structural steel contractors in Australia favor rental and channel partner models bundling chamfering tools with magnetic drills. Guaranteed uptime arrangements bundle consumables, preventive maintenance, and rapid exchange units.
- Maintenance:Pipeline maintenance contractors prioritize runtime flexibility and dust extraction compliance under OSHA silica exposure rules.
- Tool Rental:Equipment leasing platforms aggregate demand from intermittent users and capital-constrained fabricators.
Manufacturing anchors equipment specification standards. Construction is gaining share fastest through rental model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government efficiency mandates and quality certification requirements are redirecting procurement flows toward certified portable chamfering equipment in major fabrication economies.
Germany
ISO 9001 edge-preparation standards drive replacement cycles in precision metal fabrication. REACH chemical restrictions accelerate mechanical chamfering substitution for solvent-based coating pretreatments. Fabrication clusters in North Rhine-Westphalia and Baden-Württemberg standardize on certified equipment configurations.
Japan
METI efficiency directives explicitly favor cordless shop-floor equipment adoption. Shipbuilding applications in Yokohama and Nagasaki concentrate demand for battery-operated configurations. Japanese automotive stamping plants specify brushless DC architectures for thermal efficiency.
United States
OSHA silica exposure rules force capital investment in dust extraction systems for dry grinding operations. Pipeline maintenance contractors in Texas negotiate outcome-based maintenance agreements bundling consumables and rapid exchange units. Energy sector procurement shifts toward guaranteed uptime arrangements.
India
PLI scheme incentives for capital goods attract assembly operations for export-focused equipment. Domestic manufacturing capacity expands to serve Middle East pipeline construction demand. Fabrication workshops in Maharashtra and Gujarat adopt certified edge-preparation workflows.
Australia
Construction equipment leasing platforms bundle chamfering tools with magnetic drills for structural steel contractors. Project-based contracting models favor rental and channel partner arrangements over direct equipment purchases. Regional parts depot networks determine supplier qualification.
Portable Chamfering Machines Market Competitive Landscape
Listed leaders compete with private specialists across equipment certification and channel depth dimensions. The supplier base organizes around three strategic archetypes: diversified industrial tool conglomerates, pneumatic engineering specialists, and magnetic drilling combination providers. Consolidation pressure concentrates among mid-tier manufacturers lacking certified service networks. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into battery-operated configurations.
Among German-based fabricators, Assfalg GmbH and GERIMA GmbH exemplify the precision engineering archetype serving certified edge-preparation workflows. Ridgid occupies a position representing diversified industrial tool conglomerates with deep channel presence in North American maintenance sectors. Nitto Kohki anchors the pneumatic engineering specialist tier through its concentration on Japanese shipbuilding applications.
| Leading Market Players |
|---|
| Ridgid |
| Nitto Kohki |
| Promotech |
| Euroboor |
| Baileigh Industrial |
| Assfalg GmbH |
| GERIMA GmbH |
| PROTEM |
| BDS |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification gates both supplier qualification and price differentiation across portable chamfering equipment, compressing procurement toward certified configurations that command premium positioning while excluding uncertified competitors from precision fabrication workflows.
Pricing Analysis
Certification level creates the primary spread across portable chamfering equipment tiers. Three-tier pricing structure separates ISO 9001-certified premium units from CE-marked standard configurations and uncertified economy alternatives. Brushless DC motor architectures and thermal management systems drive additional differentiation within the premium band. Cost compression in the economy tier intensifies as Chinese assembly operations expand capacity for export-focused equipment. Construction contractors in Australia and Texas exhibit highest price sensitivity due to project-based procurement cycles, while aerospace tier-one suppliers prioritize certified performance over unit cost.
Supply Chain Analysis
China dominates rare earth magnet refining and lithium-ion cell production for battery-operated configurations. Germany and Japan anchor precision spindle bearing and brushless motor manufacturing. Neodymium supply concentration in Chinese processing operations creates single-source vulnerability for magnetic-base chamfering units. High-speed bearing procurement draws from specialized Japanese and German suppliers with qualified supplier relationships. Distribution runs through industrial tool distributors and construction equipment leasing platforms rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable chamfering equipment sits in early-cycle expansion as battery energy density improvements unlock cord-free mobility in construction and maintenance segments previously tethered to pneumatic infrastructure.
For Market Incumbents: Consolidate certification depth and channel control against mid-tier brushless motor entrants. Deepen backward integration into precision spindle bearing supply to offset Japanese and German supplier scarcity. Expand certified service depot networks in Texas and Alberta to capture outcome-based maintenance contract evolution in energy sector procurement. For New Entrants and Emerging Players: Anchor in Indian assembly operations under PLI scheme incentives for capital goods export to Middle East pipeline construction. Target battery-operated configurations for Australian rental platforms bundling chamfering tools with magnetic drills. Pursue CE marking pathway acceleration to compress time-to-revenue against EU machinery directive conformity delays. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-operated sub-segments as lithium-ion cell costs compress and brushless motor platforms commoditize. Long-term viability favors suppliers with in-house thermal management engineering and regional parts depot networks over import-dependent distributors. Watch METI efficiency directive expansion beyond shipbuilding into broader Japanese manufacturing as adoption inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration | Compresses conformity assessment timelines for battery-operated variants entering EU fabrication clusters. |
| Backward Integration into Bearings | Captures precision spindle supply currently concentrated among qualified Japanese and German specialists. |
| Battery Platform Standardization | Enables runtime analytics and fleet management compatibility prioritized by pipeline contractors. |
| Regional Service Depot Expansion | Supports guaranteed uptime arrangements displacing traditional parts-and-labor contracts in North American energy procurement. |
| Aerospace Superalloy Certification | Unlocks premium pricing pools for Inconel and titanium edge-finishing in tier-one supplier facilities. |
Research Methodology
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview programs. Secondary validation drew from customs trade data, SEC filings of listed industrial tool manufacturers, ISO certification registries, and METI efficiency directive documentation. Bottom-up equipment shipment analysis triangulated against top-down fabrication spending estimates across metalworking, aerospace, and construction end uses.
Forecast outputs were validated against external benchmarks including regional fabrication output indices, capital goods import trajectories, and certified equipment procurement disclosures. Segmentation modeling spanned power source configuration, application severity, and end-user contracting evolution across the projection horizon. CAGRs were derived from fitted growth curves incorporating lithium-ion energy density improvement trajectories and regulatory mandate implementation schedules.
Material uncertainties — rare earth supply disruption, CE marking timeline extensions, and CNC machining center substitution in aerospace — sit outside the modeled envelope. Forecasts reflect assumptions regarding METI directive expansion and OSHA silica rule enforcement consistency. Recalibration cycles align with material shifts in battery transport regulations and cordless tool certification standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Friction Stir Welding Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Backhoes Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Felling Heads Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Shot Blasting Machine Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Roadheaders Market
Construction Equipment
GCC Construction Machinery Market