
 Backhoe Bucket Market | 2026-2036
Backhoe Bucket Market Size, Share, and Industry Trends Forecast 2026-2036
Backhoe Bucket Market Outlook
Municipal fleet operators and rental yard chains are reorganizing procurement priorities around attachment interchangeability and total lifecycle cost. Caterpillar sustains channel dominance through its dealer network coverage and integrated machine-bucket bundling. Komatsu differentiates via precision-fit engineering for its own backhoe loader platforms. Geith International specializes in universal quick-coupler systems that span multiple OEM hydraulic pin configurations.
A backhoe bucket is a curved, reinforced excavation attachment mounted to the loader arm or rear dipper of a backhoe loader, typically fabricated from high-tensile steel plate with hardened cutting edges and wear strips to withstand abrasive soil and rock contact. Its primary purpose is material penetration, load retention, and controlled discharge during trenching, grading, and utility installation tasks. Heavy-duty bucket variants command margin premiums in demolition and quarry applications where material abrasion accelerates wear-part consumption. Ditching buckets are gaining specification share in landscaping and drainage contracts due to their curved profile and sloped sides that enable clean bank finishing without secondary grading passes.
OSHA excavation safety standards and ISO 13031 earth-moving machinery attachment interface specifications shape product design and market access requirements for backhoe bucket manufacturers selling into regulated economies. The EPA Tier 4 Final emission framework indirectly influences bucket demand by extending backhoe loader replacement cycles, pushing fleet managers toward attachment upgrades rather than full machine turnover. Stakeholders must monitor quick-coupler standard consolidation among major OEMs, as interoperability decisions will determine which attachment suppliers retain specification access across pooled rental fleets and mixed-manufacturer job sites.
Market Dynamics
Quick-coupler standard consolidation among major OEMs is fragmenting specification access and forcing attachment suppliers to engineer multi-platform compatibility or risk exclusion from pooled rental fleets and mixed-manufacturer job sites.
Growth Catalysts
- EPA Tier 4 Final emission framework:Extended backhoe loader replacement cycles in the United States push fleet managers toward attachment upgrades rather than full machine turnover, sustaining aftermarket bucket demand.
- Municipal infrastructure departments:Fleet replacement programs for compact utility loaders are expanding across Germany, creating specification pull for standardized quick-coupler systems.
- Wear-resistant alloy compositions:Advanced metallurgy in cutting edges and wear strips extends bucket service intervals in abrasive soil conditions, reducing total lifecycle cost for quarry operators.
Market Restraints
- High-tensile steel plate input volatility:Fluctuations in specialty steel pricing compress fabrication margins for bucket manufacturers serving price-sensitive municipal segments.
- Supply concentration in Chinese foundries:Dependence on a limited geography for cast wear components creates vulnerability to trade policy shifts and logistics disruptions.
- ISO 13031 interface limitations:Incomplete standardization of hydraulic pin configurations across OEM platforms forces redundant engineering and inventory duplication.
Strategic Opportunities
- Indian municipal infrastructure buildout:Underpenetrated demand for utility-grade ditching buckets exists as state governments expand drainage and irrigation contract awards under central funding schemes.
- Telematics-integrated bucket monitoring:Convergence of IoT sensors with wear-part tracking enables predictive maintenance contracts for rental yard chains seeking to differentiate service offerings.
- EU Green Deal circularity mandates:Remanufacturing and recycling specifications for construction equipment attachments create premium positioning for suppliers with closed-loop steel recovery capabilities.
Industry Challenges
- Welding technician scarcity:Certified fabricators capable of high-tensile steel joint preparation are in short supply, constraining production scaling for custom heavy-duty bucket orders.
- Multi-OEM certification timelines:Independent attachment suppliers face protracted validation cycles to achieve factory-approved status for each major loader platform, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backhoe Bucket Market |
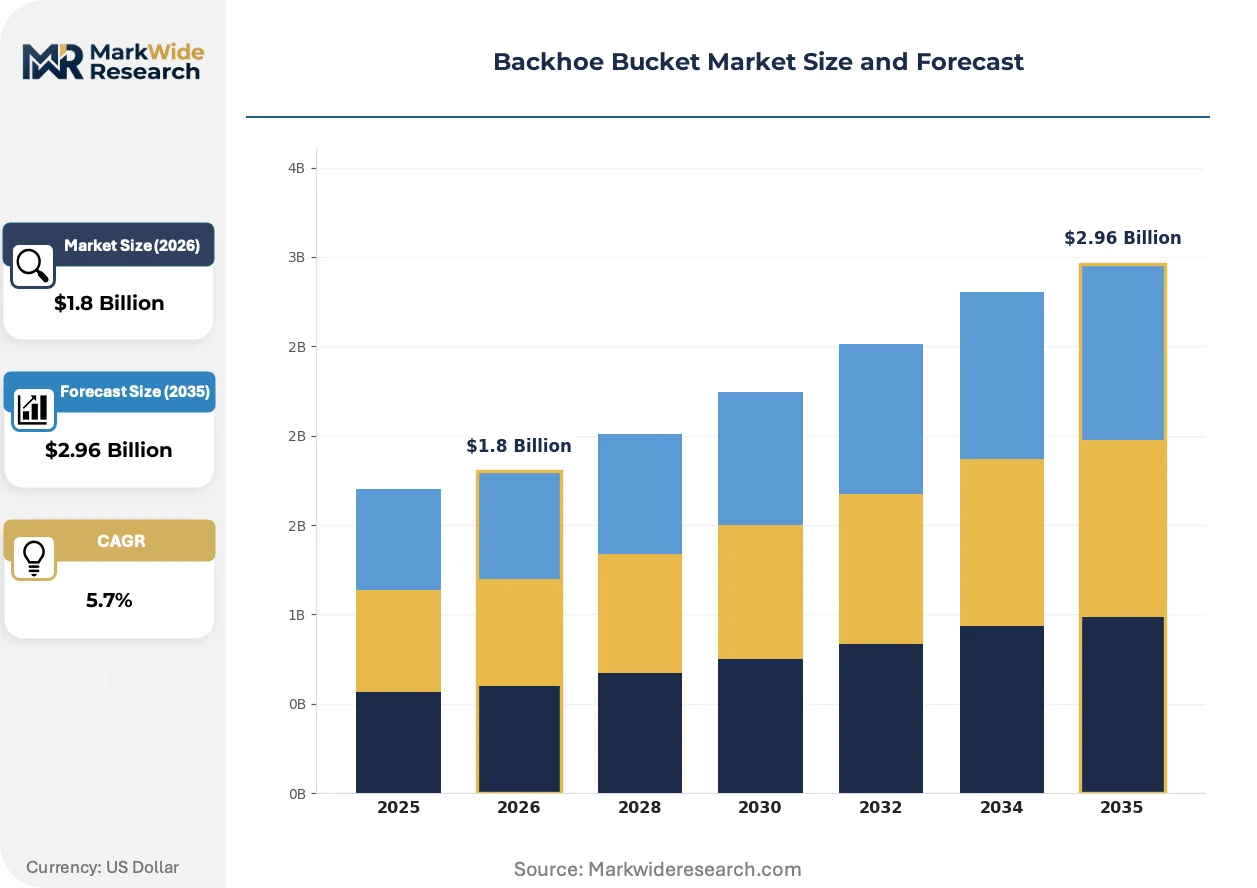
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bucket, Heavy-Duty Bucket, Ditching Bucket, Thumb Bucket Material: Steel, Polyethylene, Alloy, Rubber Size: Small, Medium, Large, Extra Large Application: Construction, Landscaping, Excavation, Demolition |
| Companies Covered | CNH Industrial, XCMG Group, Caterpillar, Geith International, Rockland Manufacturing, Komatsu, Bobcat Company, Liugong Machinery, Deere & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backhoe Bucket Market Strategic Shifts
Attachment engineering is pivoting from proprietary lock-in toward interoperability architectures, while material science and digital integration reshape how buckets are specified, monitored, and maintained across fleet operations.
Advanced composite reinforcement is decomposing the traditional steel-monolith design paradigm in specialized applications. Landscaping contractors in the Netherlands are piloting hybrid buckets with polymer-composite sidewalls that reduce machine payload and fuel consumption. This material transition is decomposing the historical correlation between bucket weight and durability perception in light-duty segments.
REACH substance restrictions on hexavalent chromium plating are forcing European manufacturers to migrate toward thermal spray carbide coatings for wear protection. The regulatory pressure accelerates capital investment in coating equipment but eliminates hazardous waste liabilities in end-of-life processing. German OEMs are responding fastest, integrating the new surface treatments into their 2026 specification sheets ahead of compliance deadlines.
Rental yard chains are unbundling attachment procurement from machine lease agreements, creating standalone bucket subscription tiers. This model displaces the traditional bundled-attachment standard in North American equipment leasing, forcing manufacturers to price and warranty buckets as independent service units. The shift is most visible in Texas and Florida municipal contractor segments where fleet flexibility commands premium positioning.
Backhoe Bucket Market Segmentation
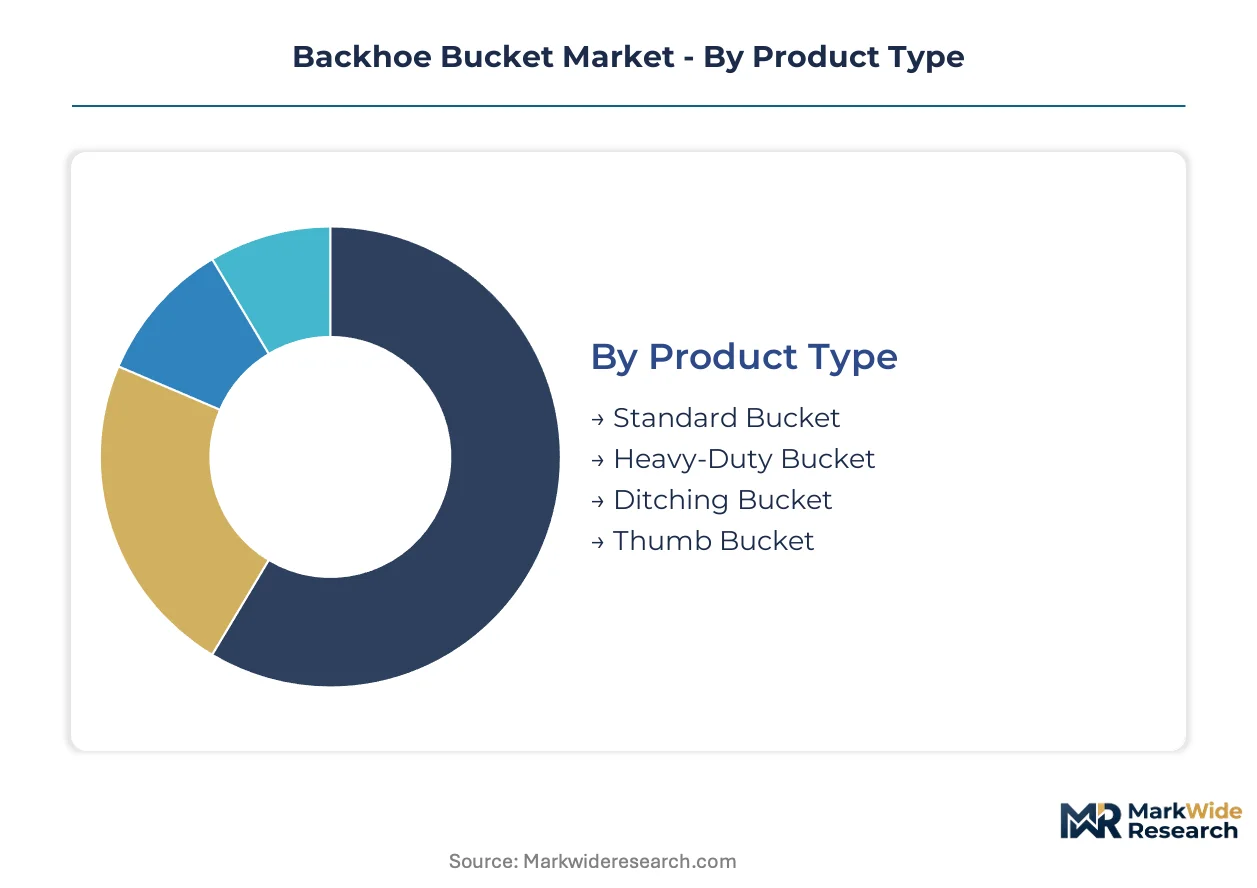
Backhoe bucket procurement diverges sharply across end-use contexts, with material specifications and dimensional requirements tracking directly to machine class and job site abrasion levels. Fleet managers segment purchases by duty cycle intensity rather than upfront unit cost, reshaping supplier positioning across municipal, rental, and contractor channels.
Product Type:
Standard and heavy-duty variants dominate domestic replacement demand in the United States and Germany, while ditching and thumb configurations see stronger export pull into emerging infrastructure markets.
- Standard Bucket:Fabricated from high-tensile steel plate with replaceable bolt-on cutting edges, this configuration serves general trenching and material handling across municipal fleets in Texas and Florida. Demand concentrates in rental yard chains seeking interchangeability across mixed-manufacturer backhoe loader fleets.
- Heavy-Duty Bucket:Reinforced shell construction with integrated wear strips and abrasion-resistant alloy edges withstands rock and demolition debris. Quarry operators in Germany specify these variants despite 40-60% price premiums over standard grades, driven by total lifecycle cost calculations in high-abrasion conditions.
- Ditching Bucket:Curved profile with sloped sides enables clean bank finishing for drainage contractors.
- Thumb Bucket:Integrated hydraulic grapple functionality serves demolition and scrap handling segments.
Heavy-duty buckets command the established base. The steepest expansion runs through ditching configurations.
Material:
Cost tier stratification separates commodity steel from premium alloy and composite alternatives, with polyethylene emerging as a weight-reduction option for light-duty landscaping fleets.
- Steel:Conventional Q345 and Q460 grade plates remain the volume baseline for standard and heavy-duty fabrication across Chinese and Indian foundry supply chains.
- Alloy:Chromium-molybdenum and boron steel compositions extend cutting edge service intervals by 30-50% in abrasive soil conditions.
- Polyethylene:Hybrid polymer-composite sidewalls reduce machine payload and fuel consumption for Dutch landscaping contractors piloting lightweight alternatives.
- Rubber:Specialized edge compounds protect finished surfaces in utility trenching near paved infrastructure.
Steel retains volume dominance. Alloy grades are gaining share fastest in premium specification channels.
Size:
Machine platform compatibility and hydraulic capacity constraints dictate size selection, with compact utility loaders driving small-bucket specification and full-size backhoes requiring large and extra-large variants.
- Small:8-12 inch widths match compact utility loaders in municipal fleets across German cities expanding fleet replacement programs.
- Medium:16-24 inch configurations serve general construction contractors as the default trenching specification.
- Large:30-36 inch widths align with full-size backhoe loader hydraulic systems for bulk material handling.
- Extra Large:42+ inch specialty fabrications address mining and heavy civil applications with dedicated machine platforms.
Medium sizes anchor replacement volume. Small configurations are expanding most quickly through compact loader fleet growth.
Application:
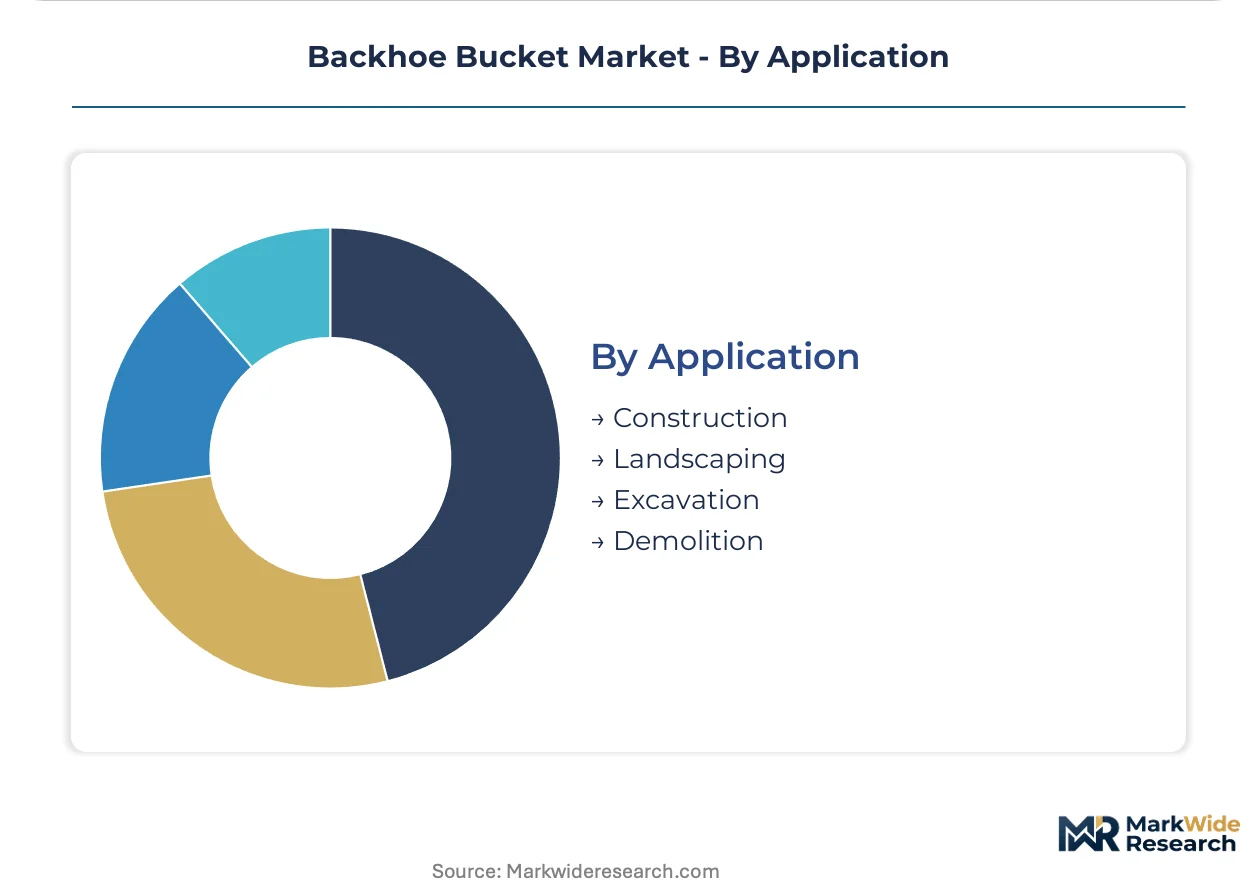
Customer type and project duration shape attachment procurement, with construction and excavation demanding owned-fleet durability while landscaping and demolition favor rental flexibility.
- Construction:General building contractors prioritize quick-coupler compatibility across pooled equipment fleets, standardizing on ISO 13031 interface specifications to minimize downtime during attachment swaps.
- Excavation:Utility trenching contractors in the United States specify ditching buckets with sloped sides to meet OSHA excavation safety standards for clean bank angles without secondary grading passes.
- Landscaping:Finish-grade contractors in the Netherlands adopt polymer-composite hybrid buckets to reduce fuel consumption on sensitive terrain.
- Demolition:Scrap handlers and structure dismantlers require thumb buckets with integrated grapple functions for material sorting.
Construction commands the established base. Landscaping is climbing the fastest through sustainability-driven material transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for cast wear components clusters in Chinese manufacturing hubs, while final assembly and precision fabrication concentrate in Germany and the United States. Municipal fleet replacement programs and OEM attachment standardization are driving divergent demand patterns across major economies.
United States
EPA Tier 4 Final emission frameworks extend backhoe loader replacement cycles, pushing fleet managers toward attachment upgrades rather than full machine turnover. OSHA excavation safety standards mandate clean bank angles for trenching operations, creating specification pull for ditching bucket configurations. Texas and Florida municipal contractor segments lead rental yard unbundling trends where standalone bucket subscriptions displace traditional bundled-attachment leasing.
Germany
Municipal infrastructure departments across German cities are expanding fleet replacement programs for compact utility loaders, generating demand for standardized quick-coupler systems. EU Green Deal circularity mandates accelerate remanufacturing specifications for construction equipment attachments, favoring suppliers with closed-loop steel recovery capabilities. Industrial clusters in North Rhine-Westphalia and Bavaria host precision fabrication facilities serving quarry operators who specify heavy-duty variants despite substantial price premiums.
China
Foundry supply chains for cast wear components concentrate in Chinese manufacturing regions, creating cost advantages for standard-grade bucket fabrication. GB standards and MIIT industrial policy frameworks shape domestic equipment specification requirements. Yangtze River Delta manufacturing hubs supply both domestic construction demand and export markets for compact loader attachments.
India
State governments are expanding drainage and irrigation contract awards under central funding schemes, generating underpenetrated demand for utility-grade ditching buckets. BIS certification requirements and PLI scheme incentives for construction equipment manufacturing are reshaping local supplier capabilities. Maharashtra and Gujarat industrial corridors attract fabrication investment targeting municipal infrastructure buildout.
Netherlands
Landscaping contractors are piloting hybrid buckets with polymer-composite sidewalls that reduce machine payload and fuel consumption on sensitive terrain. REACH substance restrictions on hexavalent chromium plating force migration toward thermal spray carbide coatings for wear protection. Randstad region equipment distributors lead adoption of telematics-integrated bucket monitoring for predictive maintenance contracts.
Backhoe Bucket Market Competitive Environment
Concentration sits with integrated OEMs controlling proprietary attachment interfaces and distribution networks. The market structure divides between full-line equipment manufacturers bundling buckets with loader sales, independent attachment specialists engineering multi-platform compatibility, and regional fabricators serving price-sensitive municipal segments. Strategic archetypes include quick-coupler standard consolidators, wear-resistant alloy developers, and telematics-integrated service providers. Dominant competitive moves center on dealer network expansion for specification access and metallurgy partnerships for extended service interval claims.
Within the integrated OEM tier, Caterpillar and Komatsu anchor proprietary ecosystem strategies where machine-bucket bundling secures aftermarket attachment demand. Among independent specialists, Geith International occupies a position exemplifying universal quick-coupler engineering that spans multiple hydraulic pin configurations. Chinese manufacturers including XCMG Group and Liugong Machinery represent scale-driven fabrication archetypes serving domestic infrastructure expansion and export markets with cost-optimized standard-grade offerings.
| Leading Market Players |
|---|
| CNH Industrial |
| XCMG Group |
| Caterpillar |
| Geith International |
| Rockland Manufacturing |
| Komatsu |
| Bobcat Company |
| Liugong Machinery |
| Deere & Company |
| Others |
Value Chain & Pricing Dynamics
ISO 13031 interface specifications gate both supplier qualification and price differentiation simultaneously, forcing attachment manufacturers to absorb certification costs while OEMs capture premium positioning through proprietary quick-coupler ecosystems. Municipal fleet operators in Texas and Florida exploit this fragmentation to negotiate volume discounts on standard-grade buckets while quarry operators in Germany absorb 40-60% premiums for certified heavy-duty variants.
Pricing Analysis
EPA Tier 4 Final emission dictates the pricing tier structure by extending backhoe loader replacement cycles and redirecting capital toward attachment upgrades rather than full machine turnover. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified heavy-duty buckets from independent aftermarket suppliers and Chinese import-grade fabrications. Price differentiation rests on metallurgy certification and quick-coupler compatibility rather than brand equity alone. Cost compression in municipal segments intensifies because fleet managers benchmark total lifecycle cost against rental yard subscription alternatives. Rental yard chains exhibit highest price sensitivity due to unbundled procurement models, while quarry operators demonstrate lowest sensitivity given abrasion-driven replacement frequency.
Supply Chain Analysis
Container availability constraints on Yangtze River Delta-to-Hamburg lanes elevate inbound logistics costs for European fabricators sourcing cast wear components from Chinese foundries. Geographic supply concentration centers on China for standard-grade steel plate and cast components, Germany for precision fabrication and surface treatment equipment, and the United States for final assembly serving North American rental channels. Raw material dependencies draw from high-tensile Q345/Q460 steel plate, chromium-molybdenum alloy bar stock, and thermal spray carbide feedstock. Single-source vulnerability in Chinese foundry capacity for hardened cutting edges exposes fabricators to trade policy disruption. Distribution runs through OEM dealer networks for bundled machine sales and independent attachment specialists for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The backhoe bucket market sits in early-cycle recovery as municipal infrastructure departments across Germany and the United States accelerate fleet replacement programs deferred during emission framework transition periods.
For Market Incumbents: Secure quick-coupler standard consolidation wins by achieving factory-approved certification across Komatsu and Caterpillar platforms before validation timelines extend further. Deepen backward integration into wear-resistant alloy supply through partnerships with German metallurgy specialists to defend margin position against Chinese cost-optimized entrants. Channel control through dealer network exclusivity agreements remains the priority lever for specification access in pooled rental fleets. For New Entrants and Emerging Players: Lead with telematics-integrated bucket monitoring solutions targeting Randstad region distributors and Texas municipal contractors seeking predictive maintenance differentiation. Indian state drainage contracts under central funding schemes offer the most penetrable geography for utility-grade ditching bucket specification. Go-to-market execution should emphasize BIS certification investment to qualify for Maharashtra and Gujarat industrial corridor procurement. For Investors and Strategic Acquirers: EU Green Deal circularity mandates reshape the acquisition landscape by privileging suppliers with closed-loop steel recovery capabilities in North Rhine-Westphalia and Bavaria industrial clusters. Long-term viability over the projection horizon favors mid-cap fabricators with ISO 13031 multi-platform compatibility and remanufacturing infrastructure. The signal to watch is OEM quick-coupler standard merger announcements that would eliminate redundant engineering costs for independent attachment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Coupler Certification Investment | Factory-approved status across Caterpillar and Komatsu platforms secures specification access in pooled rental fleets. |
| Backward Integration into Alloy Supply | Captive sourcing of chromium-molybdenum bar stock insulates fabrication margins from specialty steel volatility. |
| Telematics-Integrated Bucket Monitoring | IoT sensor convergence with wear-part tracking enables predictive maintenance contracts for Dutch distributors. |
| Remanufacturing Capability Buildout | Closed-loop steel recovery infrastructure qualifies suppliers for EU Green Deal circularity mandates in Germany. |
| Geographic Expansion into Indian Municipal Infrastructure | Maharashtra and Gujarat industrial corridor positioning captures state drainage contract awards under central funding schemes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors at German municipal infrastructure departments, aftermarket service heads at Texas rental yard chains, procurement leads at Caterpillar and Komatsu dealer networks, and plant engineers at North Rhine-Westphalia fabrication facilities. Secondary validation drew from customs/trade data on high-tensile steel plate imports, SEC filings of listed construction equipment manufacturers, OEM parts catalog specifications, and ISO 13031 technical documentation. Bottom-up unit economics triangulated against top-down equipment fleet replacement cycle analysis.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product type, material grade, machine size compatibility, and end-use application intensity. CAGRs were derived from replacement cycle timing, fleet age distribution analysis, and attachment-to-machine ratio assumptions. Industry-specific forecast inputs incorporated EPA Tier 4 Final emission framework compliance timelines, EU Green Deal circularity mandate implementation schedules, and Indian central funding scheme allocation patterns for drainage infrastructure.
The analysis sits within stated boundaries; outcomes outside sustained municipal capital expenditure commitment and stable specialty steel pricing would require recalibration. Forecasts reflect documented assumptions regarding OEM quick-coupler standard consolidation velocity, foundry capacity expansion in Chinese manufacturing hubs, and welding technician labor availability in precision fabrication markets. Recalibration cycles align with material shifts in emission framework enforcement, trade policy on steel inputs, and telematics adoption rates in rental fleet operations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotary Hammers Market
Construction Equipment
Grout Bags Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Global Dragline Excavator Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Rotomolding Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Industrial Ovens Market