
 Global Excavator Attachments Market | 2026-2036
Global Excavator Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Excavator Attachments Market Analysis
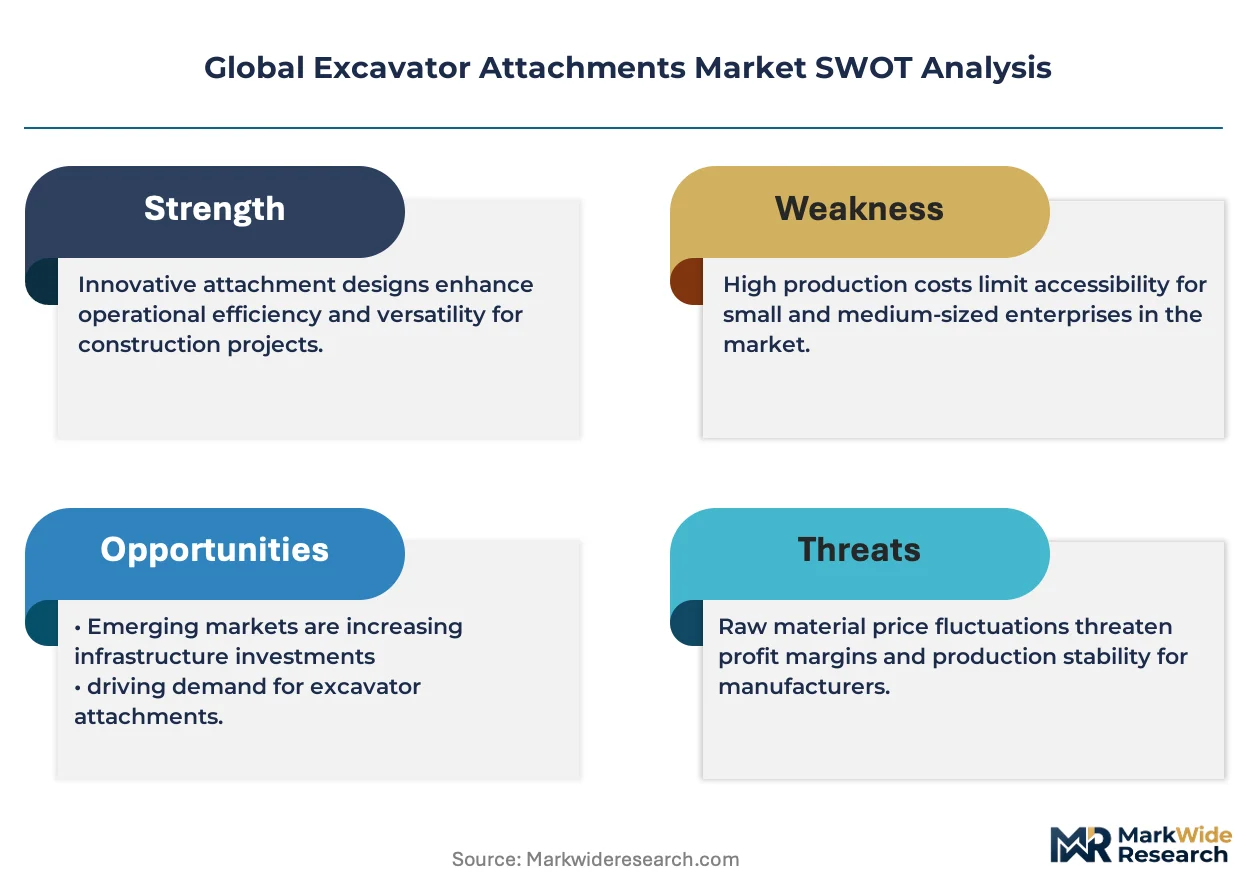
High-strength boron steel is recalibrating cost-performance trade-offs across bucket and grapple fabrication. Caterpillar Inc leverages captive metallurgy R&D to sustain margin advantages in premium attachment tiers. Komatsu Ltd anchors its position through integrated hydraulic system compatibility across its excavator-attachment pairings. JCB competes aggressively on quick-coupler standardization, reducing fleet downtime for European rental contractors.
Excavator attachments are purpose-built implements mounted to boom or stick interfaces via pin or quick-coupler systems, typically fabricated from quenched-and-tempered plate steel with Brinell hardness ratings between 400 and 500 HB to withstand abrasive wear in earthmoving and rock-breaking operations. Their primary purpose is extending machine versatility without dedicated unit procurement across construction, demolition, mining, and forestry tasks. Bucket attachments dominate volume due to foundational trenching and loading utility across contractor fleets. Hammer attachments command premium pricing in urban demolition where noise-abatement housing and vibration-dampening mounts satisfy municipal work-hour restrictions. Grapple systems are gaining share in forestry and material handling as biomass recovery expands across Nordic and North American logging operations.
EPA Tier 4 Final and EU Stage V emissions frameworks are elevating total cost of ownership calculations, pushing end users toward lighter alloy and composite materials that reduce fuel consumption per operating hour. OSHA excavation safety standards in the United States mandate shoring-compatible trenching buckets, creating specification rigidity for domestic suppliers. China's GB standards for construction machinery enforce hydraulic interface uniformity, streamlining aftermarket attachment interchangeability across domestic brands. Stakeholders must monitor alloy price volatility and regulatory convergence between North American and European test protocols to optimize sourcing and certification investments.
Market Dynamics
Emissions-driven weight reduction mandates are compressing attachment design cycles, forcing metallurgical trade-offs between durability and fuel efficiency across contractor procurement decisions.
Growth Catalysts
- Urban Demolition Surge:EPA Tier 4 Final noise-abatement requirements in US metropolitan zones accelerate demand for vibration-dampened hydraulic breakers. Municipal work-hour restrictions tighten equipment specifications.
- Biomass Recovery Expansion:Nordic forestry operations deploy grapple systems for residue collection under EU Green Deal carbon-sequestration incentives. Sweden and Finland lead mechanized logging attachment density.
- China Rail Infrastructure:State-backed high-speed corridor projects sustain bulk procurement of trenching buckets and quick-coupler systems. GB standards enforce hydraulic interface uniformity across domestic brands.
Market Restraints
- Alloy Price Volatility:Quenched-and-tempered boron steel plate costs fluctuate with mining output constraints. Attachment fabricators face margin compression during commodity spikes.
- Supply Concentration Risk:Premium hydraulic cylinder production clusters in Germany and Japan. Tier 2 manufacturers face extended lead times for precision-sealed actuator components.
- Technical Compatibility Limits:Proprietary quick-coupler geometries lock rental fleets into single-brand attachment ecosystems. Interoperability gaps strand capital across mixed-manufacturer deployments.
Strategic Opportunities
- India Infrastructure Buildout:National highway expansion under PM Gati Shakti creates virgin demand for standard-duty buckets. Local fabrication capacity remains underdeveloped versus project pipelines.
- Telematics-Enabled Attachments:IoT sensor integration with hydraulic systems permits usage-based rental pricing. Equipment-as-a-service models penetrate European contractor fleets.
- Battery-Electric Excavator Pairing:Lighter composite grapples and alloy buckets extend electric machine runtime. OEMs co-develop attachment weight classes for zero-emission chassis.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.1 structural welding qualifications for high-strength steel lag demand. Qualified technicians command premium wages in North American fabrication shops.
- Multi-Standard Compliance Overhead:Simultaneous EPA, EU Stage V, and China MEE test protocol adherence stretches R&D budgets. Certification timelines delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Excavator Attachments Market |
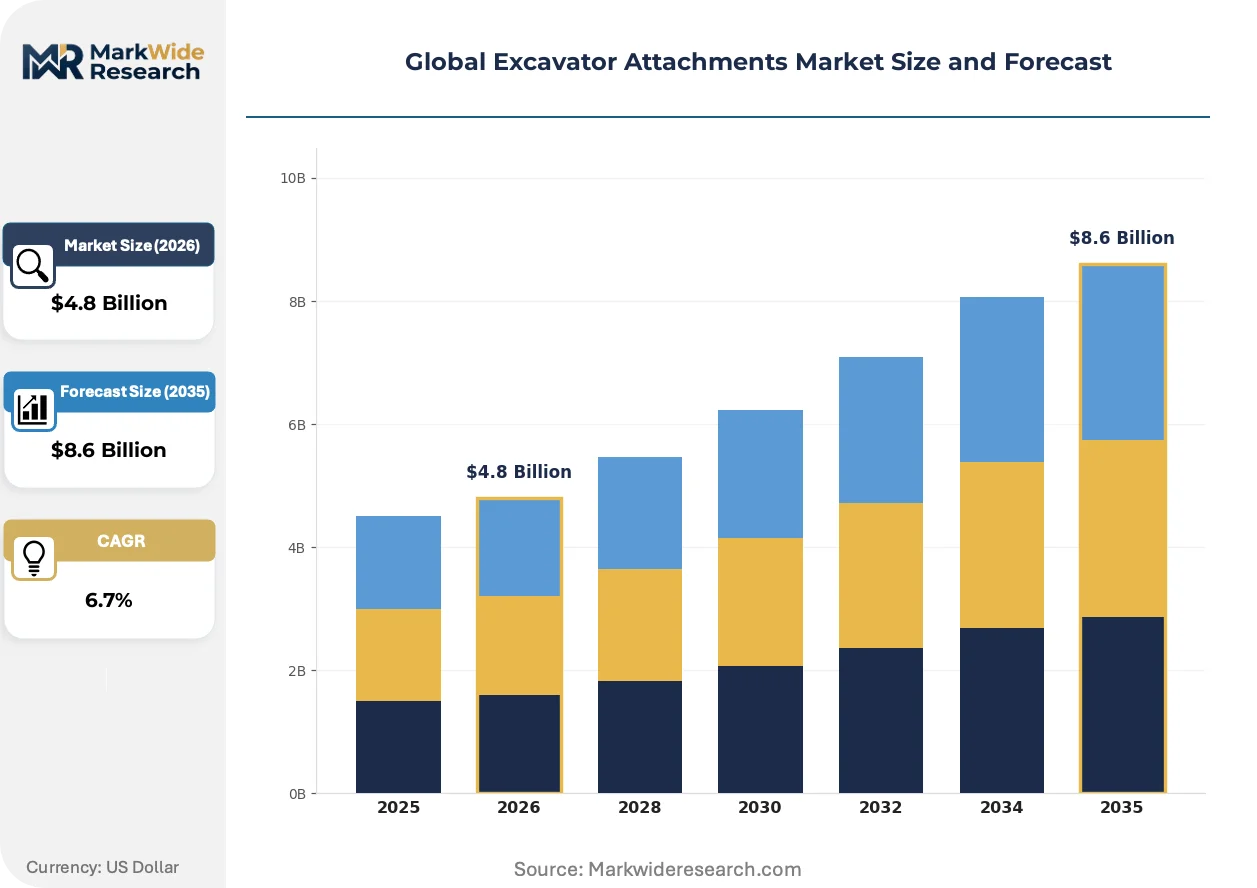
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket, Grapple, Hammer, Auger Application: Construction, Demolition, Mining, Forestry End User: Contractors, Mining Companies, Government, Landscaping Services Material: Steel, Rubber, Composite, Alloy |
| Companies Covered | Hitachi Construction Machinery Co., Ltd., JCB, Caterpillar Inc, CNH Industrial N.V., Liebherr-International AG, Komatsu Ltd, Doosan Corporation, Sandvik AB, Volvo Construction Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Excavator Attachments Market Emerging Trajectories
Attachment intelligence and material science are converging to redefine performance benchmarking, compressing the gap between heavy-duty durability and emissions-compliant lightweighting.
Quick-coupler automation is unifying fleet interchangeability standards across rental and contractor segments. European operators now specify universal pin geometries to minimize downtime during task switching. This interoperability pressure is consolidating proprietary interface designs toward ISO-compliant open architectures.
REACH substance restrictions on hexavalent chromium coatings are accelerating plasma-transferred arc welding adoption for wear-resistant surfaces. German attachment specialists retrofit deposition systems to meet surface treatment mandates. Hardfacing shops in Italy and Poland face equipment upgrade cycles to maintain CE marking eligibility.
Rental channel consolidation is shortening attachment replacement cycles as fleet managers prioritize uptime guarantees over ownership economics. Large European rental houses now bundle attachment maintenance into hourly rate structures. Equipment lessors in the UK and France capture service revenue previously retained by independent repair shops.
Global Excavator Attachments Market Segmentation
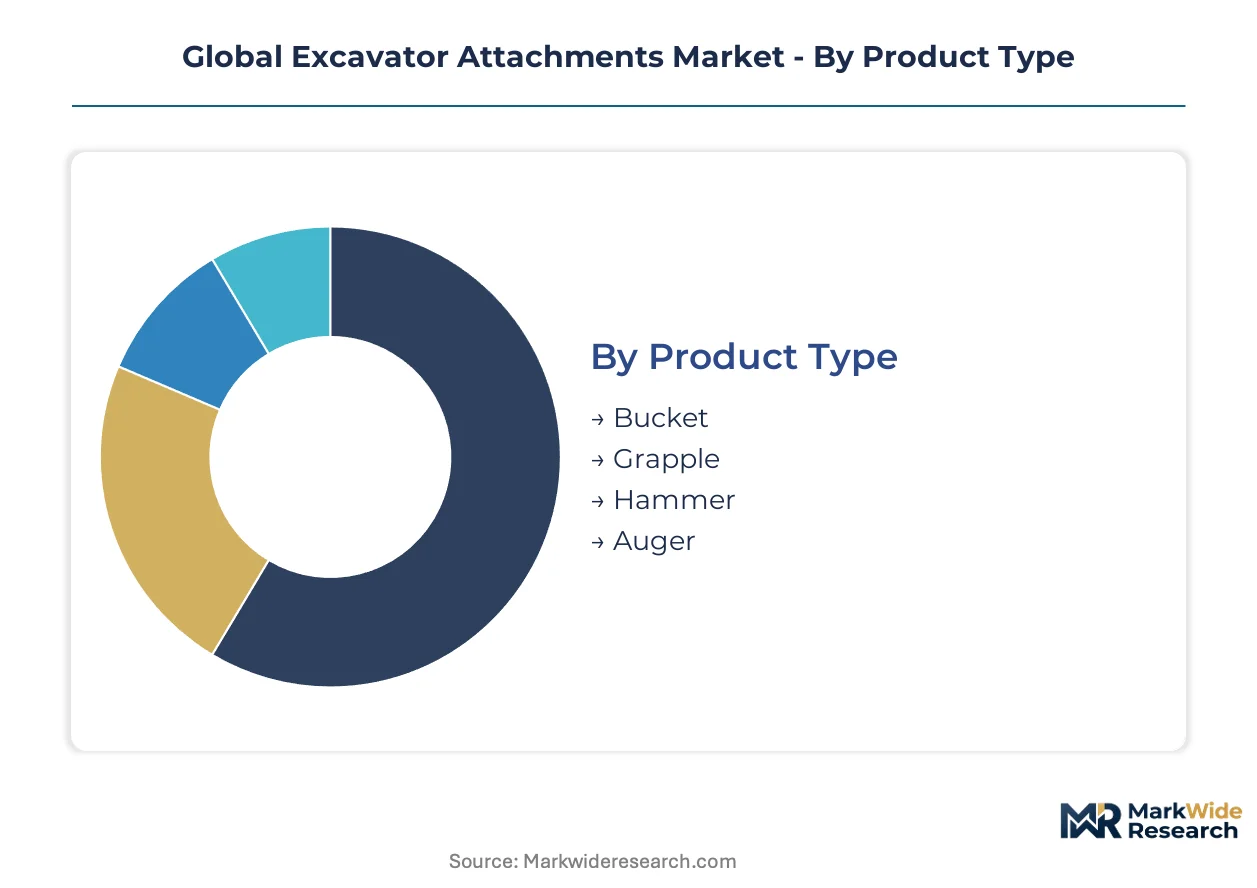
Excavator attachment segmentation reveals divergent replacement cycles across product categories, with urban demolition fleets retiring hammers every 2,500 hours while mining buckets endure 8,000-hour service intervals. Material composition and application severity directly dictate procurement timing and aftermarket service attach rates.
Product Type:
Upgrade cycles vary dramatically by attachment category, with hydraulic breakers demanding frequent rebuilds and grapple systems showing extended depreciation schedules.
- Bucket:Fabricated from quenched-and-tempered boron steel plate rated 450-500 Brinell hardness, these attachments withstand abrasive wear in trenching and loading operations across Chinese rail corridor projects. State-backed infrastructure procurement sustains bulk orders for heavy-duty and ditch-cleaning variants.
- Grapple:Multi-tine hydraulic systems with 360-degree rotation capability capture biomass residue in Swedish and Finnish logging operations under EU Green Deal carbon-sequestration frameworks. Forestry contractors specify oversized models for whole-tree processing.
- Hammer:Vibration-dampened breakers with noise-abatement housing satisfy EPA Tier 4 Final municipal work-hour restrictions in US metropolitan zones.
- Auger:Spiral drilling attachments with torque-limiting clutches prevent stall damage in rocky subsoil conditions.
Volume placements concentrate in Bucket; the faster expansion belongs to Grapple.
Application:
Cost tier differentiation separates premium-specified demolition attachments from standard-duty construction variants, with certification overhead driving pricing stratification.
- Construction:Trenching and foundation work commands the largest fleet deployment, with OSHA excavation safety standards mandating shoring-compatible bucket geometries for US contractors.
- Demolition:Hydraulic breakers with sound-suppression enclosures and dust-suppression systems satisfy municipal noise ordinances in dense urban environments.
- Mining:Extreme-duty rock buckets with reinforced heel plates and wear packages endure 24/7 extraction cycles in Australian and Chilean surface operations.
- Forestry:Grapple sorters and delimber attachments mechanize Nordic biomass recovery, with Sweden operating the highest attachment density per harvester unit globally.
Construction absorbs the highest unit volume; Demolition shows the steepest expansion trajectory as urban renewal accelerates.
End User:
Customer type determines specification rigidity, with government tenders enforcing GB standards compliance while rental fleets prioritize quick-coupler interchangeability.
- Contractors:General construction and specialty demolition firms represent the dominant procurement channel, with European rental houses bundling attachment maintenance into hourly rate structures.
- Mining Companies:Integrated operators specify OEM-matched hydraulic systems to ensure warranty continuity across 10,000-hour duty cycles.
- Government:Chinese state-owned enterprises enforce hydraulic interface uniformity per GB standards, streamlining aftermarket interchangeability across domestic equipment brands.
- Landscaping Services:Small-scale operators favor mini-excavator augers and light-duty buckets for residential hardscaping projects.
Contractors drive baseline volume; Government procurement is climbing the fastest as infrastructure stimulus deploys.
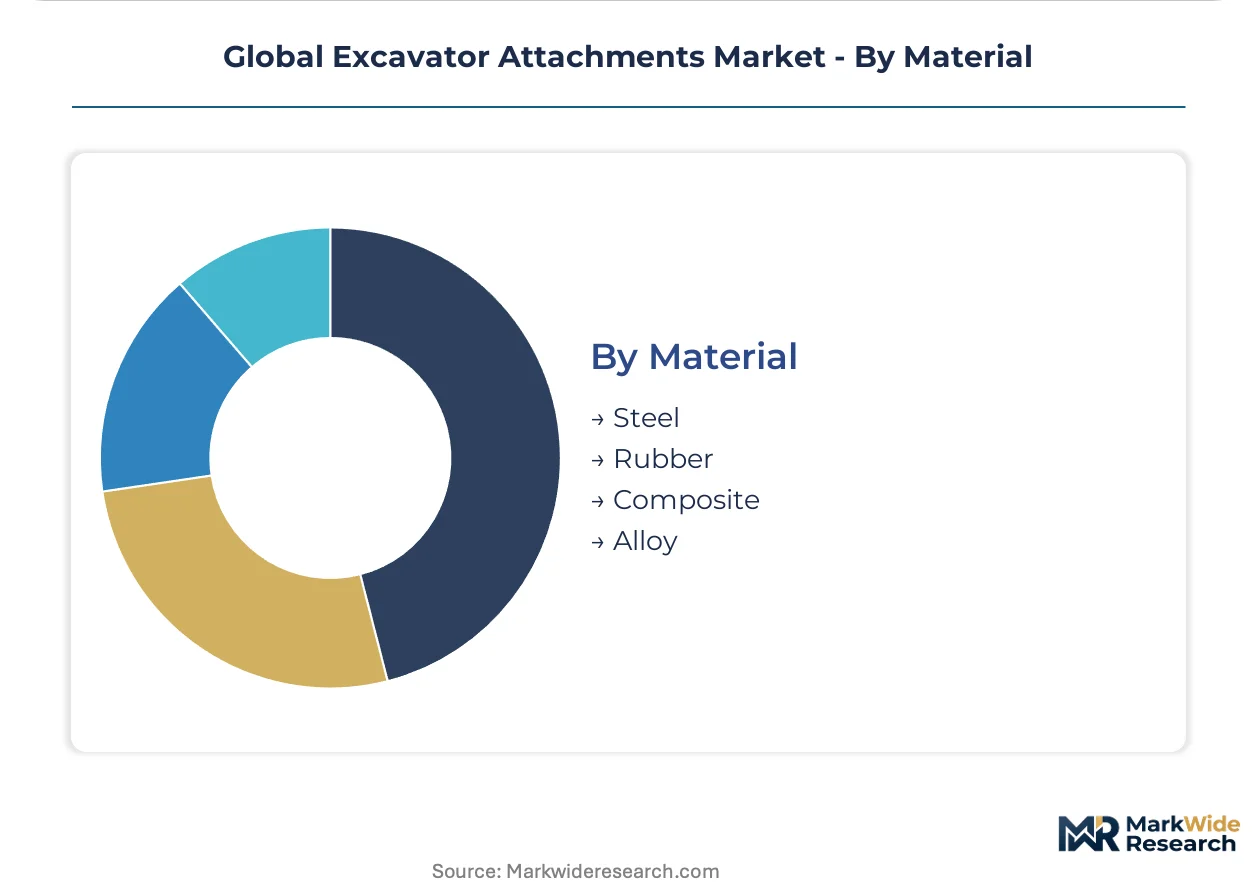
Material:
Supply concentration for high-strength alloys in Germany and Japan shapes material selection trade-offs between durability and weight reduction mandates.
- Steel:Quenched-and-tempered plate dominates heavy-duty fabrication, with boron-alloy grades from Swedish and Finnish mills supplying premium European attachment manufacturers.
- Rubber:Vibration-isolation mounts and wear pads reduce noise transmission in urban demolition hammers.
- Composite:Glass-reinforced polymer components in grapple housings cut mass for battery-electric excavator pairing, extending runtime per charge cycle.
- Alloy:Lightweight aluminum-magnesium castings in quick-coupler mechanisms satisfy EU Stage V emissions-driven weight targets without sacrificing structural integrity.
Steel retains dominant volume placement; Composite is gaining share fastest as electrification pressures mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese state-backed infrastructure programs concentrate bulk procurement of hydraulic breakers and grapple systems, while emissions mandates in Germany and the United States reshape attachment specifications toward lighter alloy compositions.
China
High-speed rail corridor construction and highway expansion sustain volume demand for trenching buckets and quick-coupler systems. GB standards enforce hydraulic interface uniformity across domestic equipment brands, streamlining aftermarket interchangeability. Shanghai and Beijing metropolitan clusters anchor procurement coordination for state-owned construction enterprises.
United States
Urban demolition contractors in metropolitan zones drive specification-grade hydraulic breaker demand under municipal noise ordinances. OSHA excavation safety standards mandate shoring-compatible trenching bucket geometries for domestic contractors. Detroit and Houston industrial corridors concentrate fabrication capacity for extreme-duty mining attachments.
Germany
EU Stage V emissions frameworks compress attachment design cycles toward weight reduction without durability sacrifice. REACH substance restrictions on hexavalent chromium coatings accelerate plasma-transferred arc welding adoption for wear-resistant surfaces. Bavarian and North Rhine-Westphalian fabrication clusters retrofit deposition systems to maintain CE marking eligibility.
Sweden
EU Green Deal carbon-sequestration incentives expand biomass recovery operations, driving grapple system deployment across mechanized logging fleets. Swedish forestry contractors specify oversized grapple models for whole-tree processing. Nordic equipment density per harvester unit peaks in Västerbotten and Norrbotten counties.
India
National highway expansion under PM Gati Shakti creates virgin demand for standard-duty buckets across contractor fleets. Central Electricity Authority regulations indirectly shape equipment mobility requirements for power transmission corridor projects. Maharashtra and Gujarat industrial zones attract attachment distributors seeking proximity to infrastructure project pipelines.
Global Excavator Attachments Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium-tier positioning and independent fabricators capturing replacement-cycle volume. Market structure tilts toward consolidation among full-line construction equipment manufacturers, while regional specialists retain niche positions in forestry and demolition attachments. Three archetypes dominate: captive OEM attachment divisions, independent branded specialists, and private-label contract manufacturers. Competitive moves center on quick-coupler standardization alliances and metallurgical R&D partnerships to satisfy emissions-driven weight mandates.
Among Japanese and European-headquartered manufacturers, Hitachi Construction Machinery Co., Ltd. and Liebherr-International AG occupy positions reflecting integrated equipment-attachment system strategies, while JCB exemplifies the quick-coupler standardization archetype through fleet interchangeability focus. These entities represent contrasting approaches to attachment market participation—captive integration versus interoperability leadership—without exclusive segment lock-in.
| Leading Market Players |
|---|
| Hitachi Construction Machinery Co., Ltd. |
| JCB |
| Caterpillar Inc |
| CNH Industrial N.V. |
| Liebherr-International AG |
| Komatsu Ltd |
| Doosan Corporation |
| Sandvik AB |
| Volvo Construction Equipment |
| Others |
Supply Flow & Price Mechanics
Captive metallurgy R&D at Caterpillar Inc and Komatsu Ltd anchors both supply security and premium pricing power across hydraulic breaker and grapple tiers. Backward integration into high-strength boron steel sourcing shields integrated OEMs from commodity volatility while compressing margin headroom for independent fabricators.
Pricing Analysis
Volume placements concentrate in standard-duty buckets while margins accrue to vibration-dampened hammers with EPA Tier 4 Final certification. Three-tier pricing structure across premium OEM-matched, standard aftermarket, and economy private-label tiers separates warranty-backed hydraulic compatibility from interchangeable quick-coupler variants. Cost compression in economy tiers intensifies as Chinese GB-standard imports penetrate Asian contractor fleets. Rental houses exhibit lowest price sensitivity due to bundled maintenance structures, while small landscaping operators drive aggressive procurement negotiation.
Supply Chain Analysis
AWS D1.1 structural welding qualifications gate North American fabrication capacity, extending lead times for high-strength steel attachment production. Premium hydraulic cylinder supply concentrates in Germany and Japan, drawing from quenched-and-tempered boron steel plate sourced through Swedish and Finnish mills. Single-source vulnerability in precision-sealed actuator components exposes Tier 2 manufacturers to procurement delays. Distribution runs through OEM captive channels, independent attachment specialists, and consolidated European rental houses with integrated fleet management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Stage V and EPA Tier 4 Final certification overhead erects barrier-to-entry moats for capitalized incumbents. Regulatory convergence across test protocols strands underfunded competitors in single-jurisdiction markets.
For Market Incumbents: Cement margin advantages through captive alloy R&D partnerships and quick-coupler standardization alliances that lock rental fleets into proprietary ecosystems. Threat substitution from battery-electric excavator pairings demands preemptive composite grapple co-development with zero-emission chassis OEMs. Capacity addition in Indian fabrication clusters captures PM Gati Shakti infrastructure procurement before local supply matures. For New Entrants and Emerging Players: Launch via telematics-enabled attachment rental models targeting European contractor fleets with usage-based pricing penetration. White-space concentrates in India's standard-duty bucket segment where domestic fabrication capacity lags national highway expansion pipelines. Go-to-market leverage rests on GB standards compliance for Chinese state-owned enterprise procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to construction equipment OEMs seeking full-line attachment portfolios over the next decade. Acquisition targets cluster around independent German hardfacing specialists with plasma-transferred arc welding retrofit capabilities for REACH compliance. Watch alloy price volatility spikes as inflection indicators for margin compression cycles affecting valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Coupler Standardization Alliance | ISO-compliant open architectures reduce fleet downtime for European rental contractors. |
| Composite Material Co-Development | Glass-reinforced polymer grapple housings extend battery-electric excavator runtime per charge. |
| Plasma-Transferred Arc Welding Retrofit | German hardfacing shops maintain CE marking eligibility under REACH hexavalent chromium restrictions. |
| Telematics Sensor Integration | IoT-enabled hydraulic systems unlock equipment-as-a-service pricing for European contractors. |
| India Fabrication Capacity Buildout | Maharashtra and Gujarat proximity captures PM Gati Shakti highway project attachment demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across equipment procurement managers at Chinese state-owned enterprises, aftermarket service heads at European rental houses, maintenance directors at US demolition contractors, and metallurgical R&D leads at integrated OEMs. EPA Tier 4 Final submissions, EU Stage V type-approval documentation, China GB standard enforcement records, and Swedish forestry equipment registration databases supplied validation benchmarks. Bottom-up attachment shipment tallies reconciled against top-down construction machinery production estimates.
Data-stream reconciliation across product type, application severity, end-user procurement channel, material composition, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from weighted-average replacement cycle assumptions and infrastructure project pipeline visibility across the analysis window. Industry-specific forecast inputs incorporated alloy price volatility scenarios and electrification penetration curves for battery-electric excavator pairing.
Alloy commodity spikes, regulatory timeline delays, and electric equipment adoption acceleration are the dominant revision risks warranting model sensitivity testing. Forecasts reflect documented assumptions on attachment replacement intervals and infrastructure stimulus deployment pacing. A model refresh is warranted upon material change in EU Stage V enforcement stringency or Chinese state-backed project commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Gear Grinding Machine Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Line Boring Machine Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Broaching Machine Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market