
 Global Commercial Vehicle Remote Diagnostics Market | 2026-2036
Global Commercial Vehicle Remote Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Vehicle Remote Diagnostics Market Intelligence
SAE J1939 compliance-grade telemetry is unwinding legacy CAN-bus diagnostic architectures across commercial vehicle fleets. Bosch leverages its embedded systems heritage to dominate OEM-integrated telematics control units. Continental sustains R&D intensity in edge computing modules for real-time fault prediction. Geotab competes through cloud analytics platforms that aggregate multi-brand fleet data streams.
Commercial vehicle remote diagnostics encompasses onboard sensor networks, telematics gateways, and cloud-based analytics engines that transmit vehicle health data to centralized monitoring platforms for predictive intervention. Systems typically integrate J1939/OBD-II protocol translators with cellular or satellite modems operating at sub-100-millisecond latency thresholds to enable real-time engine fault isolation and component lifecycle forecasting. Heavy duty trucks anchor hardware revenue pools due to higher per-unit telematics spend and extended duty cycles, while cloud analytics represents the fastest-expanding margin segment as fleet operators shift from capital expenditure to subscription-based operational models. IoT sensors occupy a maturing tier where price compression is offset by volume scale in trailer and delivery van retrofit programs.
The EPA's Phase 3 standards and the EU's F-Gas Regulation are reshaping diagnostic data requirements for emissions compliance verification across multi-jurisdictional fleet operations. Germany's KBA enforces type-approval protocols for aftermarket telematics devices that interface with safety-critical vehicle networks. India's BIS is developing localization mandates for connected vehicle data storage that will fragment cloud architecture strategies. Stakeholders must decide whether to architect platform-agnostic diagnostic stacks or deepen OEM-exclusive partnerships as regulatory data sovereignty requirements proliferate.
Market Dynamics
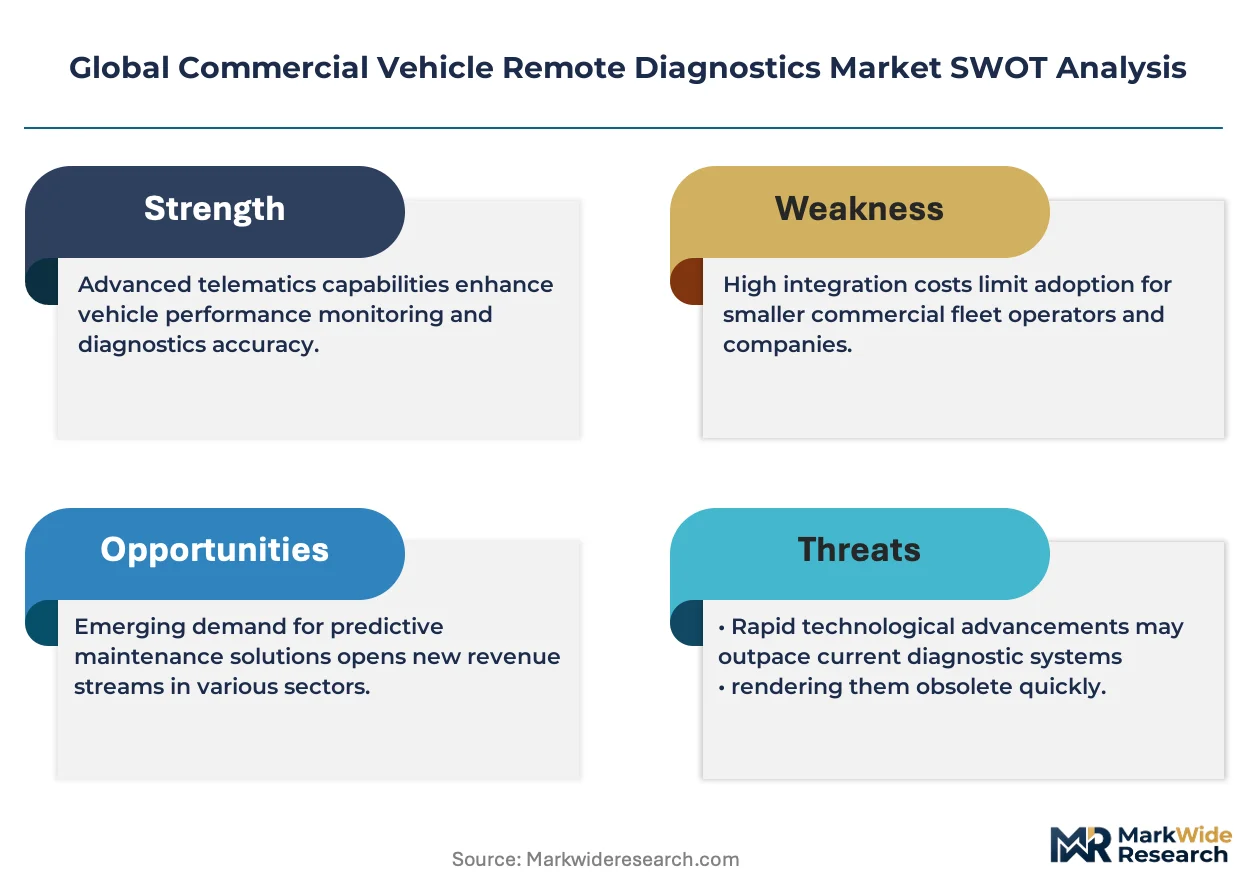
SAE J1939 protocol standardization is compressing legacy CAN-bus diagnostic architectures across commercial vehicle fleets, forcing hardware suppliers to requalify product lines for unified data bus compatibility. This technical displacement concentrates procurement power with OEMs that control embedded gateway specifications.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:Heavy-duty fleet operators in the United States must install continuous emissions monitoring hardware, mandating telematics integration for compliance verification and automated reporting.
- Predictive maintenance platforms:Long-haul trucking corridors across North America are retrofitting sensor networks to reduce unplanned downtime and extend component replacement intervals.
- Edge computing modules:Real-time fault prediction capabilities are compressing latency thresholds below 100 milliseconds, enabling immediate driver alerts and remote engine derating.
Market Restraints
- Semiconductor supply concentration:Telematics control unit production depends on automotive-grade microcontroller availability from concentrated Asian foundry capacity, creating input volatility.
- Cellular modem cost structure:5G and satellite connectivity modules represent 35-45% of hardware bill-of-materials, compressing margins for aftermarket retrofit suppliers.
- Data sovereignty fragmentation:India's BIS localization mandates for connected vehicle data storage force cloud architecture duplication, raising operational complexity for multi-national fleet software platforms.
Strategic Opportunities
- Trailer and delivery van retrofit programs:Light commercial vehicle segments remain underpenetrated for diagnostic hardware, offering volume scale opportunities as IoT sensor prices compress.
- Subscription-based operational models:Fleet operators are shifting from capital expenditure to recurring cloud analytics contracts, expanding margin pools in software services.
- EU F-Gas Regulation compliance:Refrigerated transport units require refrigerant leak detection integration with telematics platforms, creating specialized diagnostic demand in cold-chain logistics.
Industry Challenges
- J1939/OBD-II protocol translation complexity:Multi-brand fleet aggregation requires continuous firmware updates to maintain compatibility across evolving OEM diagnostic implementations.
- Automotive cybersecurity certification:Germany's KBA type-approval protocols for safety-critical network interfaces extend product launch timelines by 12-18 months for aftermarket device manufacturers.
- Telematics gateway integration:Legacy fleet management systems require expensive middleware development to ingest real-time diagnostic streams from heterogeneous hardware sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Vehicle Remote Diagnostics Market |
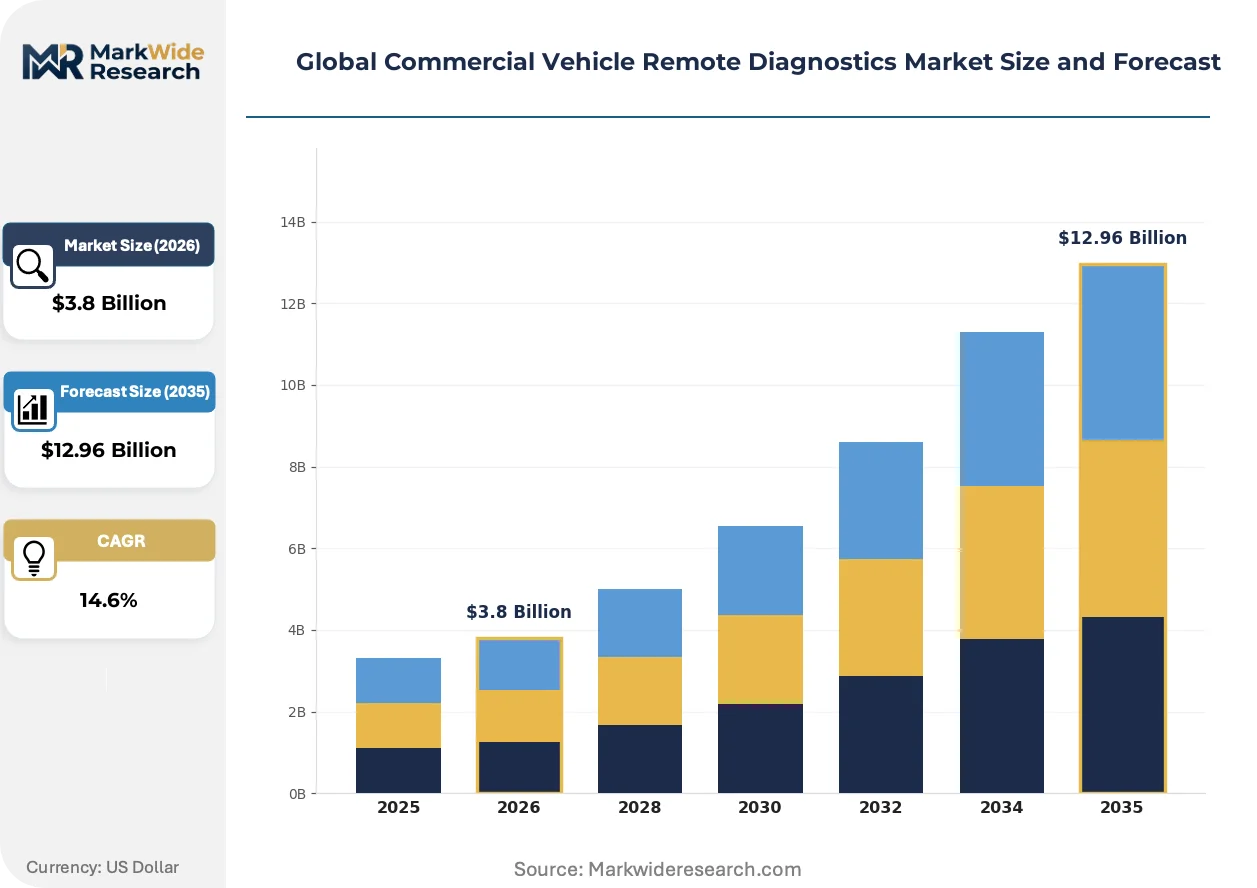
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Commercial Vehicles, Heavy Duty Trucks, Buses, Delivery Vans, Trailers Technology: OBD Telemetry, IoT Sensors, Cloud Analytics, Telematics Control Unit, Edge Computing Application: Predictive Maintenance, Fleet Management, Fuel Efficiency Monitoring, Driver Behavior Analysis, Safety Compliance End User: Fleet Operators, Logistics Providers, Vehicle Maintenance Workshops, Insurance Firms, Leasing Companies |
| Companies Covered | Bosch, Continental, ZF Friedrichshafen, Geotab, Cummins, Volvo Group, Samsara, Verizon Connect, PACCAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Vehicle Remote Diagnostics Market Strategic Shifts & Innovations
Diagnostic hardware form factors are compressing while computational density expands, enabling sensor deployment in previously inaccessible vehicle locations. Three concurrent developments are restructuring competitive requirements across the value chain.
Multi-protocol edge processors are consolidating J1939, OBD-II, and proprietary OEM bus translation into single-chip architectures. Tier 1 suppliers are embedding these processors directly into engine control modules, eliminating standalone gateway boxes. This integration is miniaturizing telematics hardware footprints and collapsing aftermarket retrofit installation times from hours to minutes.
The EU's F-Gas Regulation mandates refrigerant monitoring in transport refrigeration units, requiring diagnostic platforms to integrate pressure and temperature sensors with emissions reporting workflows. Cold-chain logistics operators in Germany and the Netherlands are retrofitting existing trailer fleets to avoid penalties. This compliance pressure is accelerating specialized diagnostic demand in temperature-controlled freight segments.
Fleet procurement departments are unbundling hardware acquisition from software subscriptions, forcing suppliers to compete on recurring platform value rather than upfront device margins. Large trucking operators in the United States are consolidating vendor relationships to single telematics platforms covering mixed OEM fleets. This concentration is compressing switching costs and raising barriers for point-solution providers lacking cloud analytics depth.
Global Commercial Vehicle Remote Diagnostics Market Segmentation
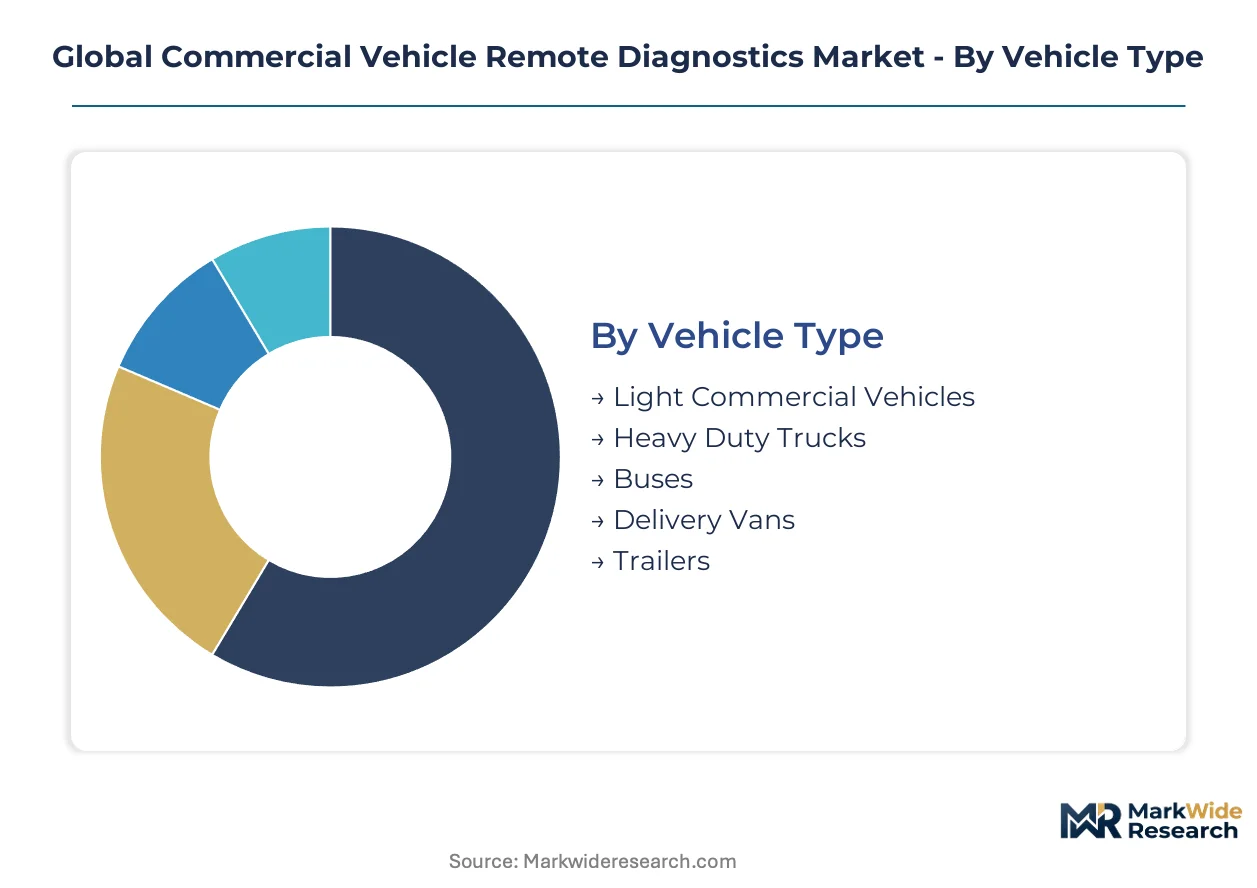
Commercial vehicle remote diagnostics segments along four intersecting dimensions that determine procurement priorities and margin structures. Fleet operators select technology bundles based on regulatory compliance tiers, vehicle duty cycles, and operational cost visibility requirements.
Vehicle Type:
EPA Phase 3 greenhouse gas standards and EU F-Gas Regulation create divergent hardware requirements across vehicle weight classes and use profiles.
- Light Commercial Vehicles:Compact telematics gateways integrate OBD-II translators with cellular modems for last-mile delivery fleets. Adoption concentrates among urban logistics providers in Germany and the Netherlands seeking real-time route optimization and emissions compliance verification for low-emission zones.
- Heavy Duty Trucks:SAE J1939-compliant diagnostic architectures dominate with embedded sensor networks monitoring engine performance, aftertreatment systems, and brake wear. Long-haul operators across United States interstate corridors deploy these systems to satisfy continuous emissions monitoring mandates and minimize unplanned downtime.
- Buses:Municipal transit authorities install integrated telematics for passenger safety systems and propulsion health monitoring. Procurement prioritizes cybersecurity certification under Germany's KBA protocols for safety-critical network interfaces.
- Delivery Vans:Aftermarket retrofit programs target temperature-controlled cargo compartments with refrigerant leak detection sensors. India's BIS localization mandates for connected vehicle data storage are fragmenting cloud architecture strategies for multi-national fleet deployments.
- Trailers:Battery-powered IoT sensors monitor tire pressure, brake temperature, and cargo environment with minimal installation complexity. Cold-chain logistics operators retrofit existing fleets to avoid EU F-Gas Regulation penalties for refrigerant monitoring gaps.
Established volume favors Heavy Duty Trucks; emerging adoption favors Delivery Vans.
Technology:
Cost tier differentiation separates capital-intensive embedded systems from rapidly commoditizing sensor hardware and high-margin recurring software services.
- OBD Telemetry:Protocol translators convert J1939 and OBD-II data streams into standardized formats for fleet management platforms. Demand clusters in aftermarket retrofit channels where multi-brand compatibility commands premium pricing.
- IoT Sensors:Temperature, pressure, and vibration monitors deploy in trailers and cargo compartments at declining unit costs. Volume scale in light commercial vehicle segments offsets price compression as sensor manufacturing concentrates in Asian foundries.
- Cloud Analytics:Subscription-based platforms aggregate multi-brand fleet data for predictive maintenance algorithms and regulatory reporting automation. Fleet operators in the United States are consolidating vendor relationships to single platforms covering mixed OEM fleets, compressing switching costs for point-solution providers.
- Telematics Control Unit:Integrated gateways combine cellular modems, GPS receivers, and edge processors in hardened automotive enclosures. Bosch dominates OEM-integrated specifications through embedded systems heritage, while Continental sustains R&D intensity in next-generation architectures.
- Edge Computing:Real-time fault prediction modules process diagnostic data locally to compress latency below 100 milliseconds for immediate driver alerts and remote engine derating. Heavy-duty fleet operators prioritize these capabilities for safety-critical intervention in long-haul corridors.
Hardware margins concentrate in Telematics Control Units; recurring revenue expansion favors Cloud Analytics.
Application:
Customer type determines feature prioritization, with large fleet operators demanding integrated platforms and smaller operators accepting modular point solutions.
- Predictive Maintenance:Machine learning models analyze engine fault codes, vibration patterns, and component lifecycle data to forecast failures before operational impact. North American long-haul trucking corridors are retrofitting sensor networks to extend replacement intervals and reduce roadside breakdowns.
- Fleet Management:Unified dashboards track vehicle location, driver hours, fuel consumption, and maintenance scheduling across heterogeneous asset bases. Procurement departments unbundle hardware acquisition from software subscriptions, forcing suppliers to compete on recurring platform value.
- Fuel Efficiency Monitoring:Real-time feedback systems correlate driving behavior with fuel consumption patterns to identify training opportunities and route optimization potential.
- Driver Behavior Analysis:Accelerometer and gyroscope data capture harsh braking, rapid acceleration, and cornering severity for safety scoring and insurance risk assessment.
- Safety Compliance:Automated logging of vehicle inspections, driver qualifications, and hours-of-service regulations replaces paper-based recordkeeping for regulatory audits.
Operational necessity anchors Fleet Management; technology differentiation favors Predictive Maintenance.
End User:
Volume concentration sits with integrated logistics providers, while margin expansion targets insurance and leasing sectors seeking usage-based pricing models.
- Fleet Operators:Large trucking companies and delivery services procure enterprise telematics platforms with custom analytics development and dedicated support contracts. These customers drive standardization toward single-vendor solutions covering mixed OEM fleets.
- Logistics Providers:Third-party freight managers require visibility across subcontractor vehicles with limited capital expenditure, favoring bring-your-own-device compatibility and rapid deployment.
- Vehicle Maintenance Workshops:Independent service centers leverage remote diagnostic access to pre-order parts and schedule bay capacity before vehicle arrival, compressing repair turnaround.
- Insurance Firms:Usage-based coverage models depend on verified telematics data for risk segmentation and claims validation, creating demand for tamper-proof data logging.
- Leasing Companies:Asset financiers monitor vehicle health and utilization to optimize residual value forecasting and end-of-lease condition assessment.
Procurement scale favors Fleet Operators; margin expansion favors Insurance Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in commercial vehicle remote diagnostics equipment favor export-oriented manufacturing clusters in Germany and the United States, while import-dependent fleet operators in India and Brazil drive aftermarket retrofit demand. Regulatory divergence across jurisdictions is fragmenting cloud architecture strategies and forcing suppliers to duplicate compliance infrastructure.
United States
Long-haul trucking corridors spanning Interstate 10 and Interstate 80 routes anchor hardware deployment for predictive maintenance platforms. EPA Phase 3 greenhouse gas standards mandate continuous emissions monitoring hardware, compelling fleet operators to integrate telematics for automated compliance reporting. Detroit-Warren automotive cluster concentrates OEM-embedded gateway production for heavy-duty vehicle specifications.
Germany
Kraftfahrt-Bundesamt type-approval protocols for safety-critical network interfaces extend product launch timelines for aftermarket device manufacturers by 12-18 months. EU F-Gas Regulation drives refrigerant leak detection integration in cold-chain logistics fleets operating across Rhine-Ruhr industrial corridor. Stuttgart and Munich engineering clusters sustain embedded systems heritage for telematics control unit architectures.
India
Bureau of Indian Standards localization mandates for connected vehicle data storage fragment cloud architecture strategies for multi-national fleet software platforms. Last-mile delivery operators in Mumbai and Delhi-NCR retrofit compact OBD-II gateways for urban emissions compliance verification. Tamil Nadu automotive belt concentrates domestic telematics hardware assembly for price-sensitive light commercial vehicle segments.
China
Ministry of Industry and Information Technology connected vehicle standards accelerate domestic telematics platform development for commercial vehicle fleets. Yangtze River Delta manufacturing corridor integrates edge computing modules into engine control systems for real-time fault prediction. Shenzhen electronics cluster supplies cellular modem components at scale for regional telematics gateway production.
Brazil
Agência Nacional de Transportes Terrestres mandates for commercial vehicle tracking create baseline telematics demand across long-haul freight corridors. São Paulo state logistics operators adopt subscription-based cloud analytics to shift from capital expenditure to operational expenditure models. ABC Paulista industrial region concentrates aftermarket retrofit installation capacity for heterogeneous mixed-OEM fleets.
Global Commercial Vehicle Remote Diagnostics Market Key Industry Players
Listed automotive suppliers compete with private telematics specialists across embedded hardware and cloud software dimensions. Market structure concentrates procurement power with OEM-integrated Tier 1 suppliers while aftermarket channels fragment across point-solution providers. Three archetypes dominate: diversified automotive conglomerates with embedded systems heritage, pure-play telematics platform operators, and engine manufacturers with captive diagnostic capabilities. Competitive moves center on strategic partnerships for multi-brand fleet data aggregation and vertical integration into edge computing silicon.
Within the diversified automotive conglomerate tier, Bosch and Continental exemplify embedded gateway specification control through heritage automotive electronics positions. Geotab occupies a specialist archetype as a private telematics platform operator competing through cloud analytics depth rather than hardware margins. These three anchors represent divergent strategic postures: captive OEM integration versus platform-agnostic aftermarket aggregation.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| ZF Friedrichshafen |
| Geotab |
| Cummins |
| Volvo Group |
| Samsara |
| Verizon Connect |
| PACCAR |
| Others |
Cost & Logistics Intelligence
Automotive-grade microcontroller foundry utilization rates above 90 percent in Taiwan and South Korea compress margin buffers for telematics control unit manufacturers while elevating price floors for aftermarket retrofit suppliers. This capacity tightness feeds directly into hardware bill-of-materials pressure, where 5G and satellite modem modules already claim dominant cost share.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade under Germany's KBA type-approval protocols and volume scale serving as the primary differentiation drivers. Pricing pressure stems from cellular modem cost concentration, where module expenses compress margins for aftermarket retrofit suppliers serving price-sensitive light commercial vehicle operators. Fleet operators with enterprise-scale procurement exhibit lowest price sensitivity due to subscription-based operational model shifts, while independent service centers and small logistics providers demonstrate acute cost consciousness.
Supply Chain Analysis
Container availability constraints across the Shanghai-Rotterdam trade lane elevate inbound logistics costs for European telematics gateway assembly operations. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with automotive-grade microcontrollers and edge processors drawing from concentrated Asian foundry capacity. Single-source vulnerability pervades cellular modem supply, where Qualcomm and MediaTek architectures dominate. Distribution runs through OEM-embedded channels for heavy-duty specifications and aftermarket retrofit networks for light commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as fleet procurement departments consolidate vendor relationships to single telematics platforms covering mixed OEM fleets. This interoperability inflection elevates cloud analytics depth over hardware margins as the decisive capability.
For Market Incumbents: Compound embedded gateway specification control by deepening OEM-exclusive partnerships and accelerating edge computing module R&D to defend against pure-play telematics platform operators. Prioritize certification investment under Germany's KBA protocols to extend aftermarket device launch timelines for competitors. Lock in multi-year microcontroller supply agreements with Taiwanese foundries to mitigate semiconductor availability volatility. For New Entrants and Emerging Players: Lead with trailer and delivery van retrofit programs, where IoT sensor price compression enables volume scale without confronting Bosch and Continental's OEM-integrated dominance. Target cold-chain logistics operators facing EU F-Gas Regulation compliance deadlines for refrigerant leak detection integration. Pursue bring-your-own-device compatibility as the go-to-market angle to bypass entrenched fleet management system incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud analytics platform operators serving large fleet operators with subscription-based contracts. Long-term viability favors acquisition targets with demonstrated multi-brand fleet data aggregation capabilities and established API ecosystems for third-party integration. Monitor EPA enforcement patterns for Phase 3 greenhouse gas standards as the inflection indicator for telematics hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies J1939 and OBD-II data streams for multi-brand fleet aggregation under single vendor relationships. |
| Edge Computing Module Development | Compresses latency below 100 milliseconds for real-time fault prediction in safety-critical long-haul corridors. |
| Regulatory Certification Investment | Secures KBA type-approval for safety-critical network interfaces, extending competitor launch timelines. |
| Strategic Partnership | Links telematics platforms with refrigerated transport operators facing EU F-Gas Regulation compliance deadlines. |
| Geographic Expansion | Establishes cloud architecture duplication in India to satisfy BIS localization mandates for connected vehicle data storage. |
Research Approach
The analysis maps telematics control unit hardware, cloud analytics platforms, IoT sensor networks, and edge computing modules, each validated through fleet operations directors, OEM platform engineers, aftermarket distribution channel heads, and regulatory compliance officers. Primary interview findings triangulate against customs and trade data, SEC filings from listed automotive suppliers, EPA regulatory dockets, and vehicle production databases. Bottom-up segment sizing and top-down market reconciliation ensure consistency across value chain estimates.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models vehicle type, technology tier, application use case, and end-user archetype as segmentation dimensions. CAGRs derive from installed base growth, replacement cycle dynamics, and subscription conversion rates in cloud analytics. Forecast inputs include EPA Phase 3 compliance timeline assumptions and EU F-Gas Regulation enforcement patterns.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor foundry capacity expansion or altered EPA enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation schedules and fleet operator procurement consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Van Market