
 Commercial Truck Use APU Market | 2026-2036
Commercial Truck Use APU Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Truck Use APU Market Insights
Multi-source procurement among fleet buyers is broadening supplier access across the APU value chain. Thermo King leverages its thermal management heritage to anchor premium diesel-electric hybrid lines. Bergstrom competes through specialized HVAC integration for sleeper cabs. Carrier ComfortPro sustains North American channel control with extensive dealer service networks.
Commercial truck auxiliary power units are self-contained engine or battery systems that generate electricity and climate control independent of the main truck engine, typically rated between 5-15 kW output for sleeper cab operations. Diesel APUs retain the largest installed base among long-distance haulage fleets, though electric APUs represent the fastest-growing product category as lithium-ion energy storage costs decline and charging infrastructure expands. Fleet operators constitute the dominant end-user segment by volume, while owner-operators generate higher per-unit margins due to preference for premium remote monitoring features.
The EPA enforces idle reduction standards that directly mandate or incentivize APU adoption in heavy-duty trucking, while NHTSA safety regulations govern battery placement and exhaust routing in cab configurations. CARB complements federal rules with stricter zero-emission corridor timelines affecting California-based fleets and interstate operators serving West Coast ports. Stakeholders must weigh electrification timing against residual diesel infrastructure value as regulatory thresholds tighten without uniform federal replacement deadlines.
Market Dynamics
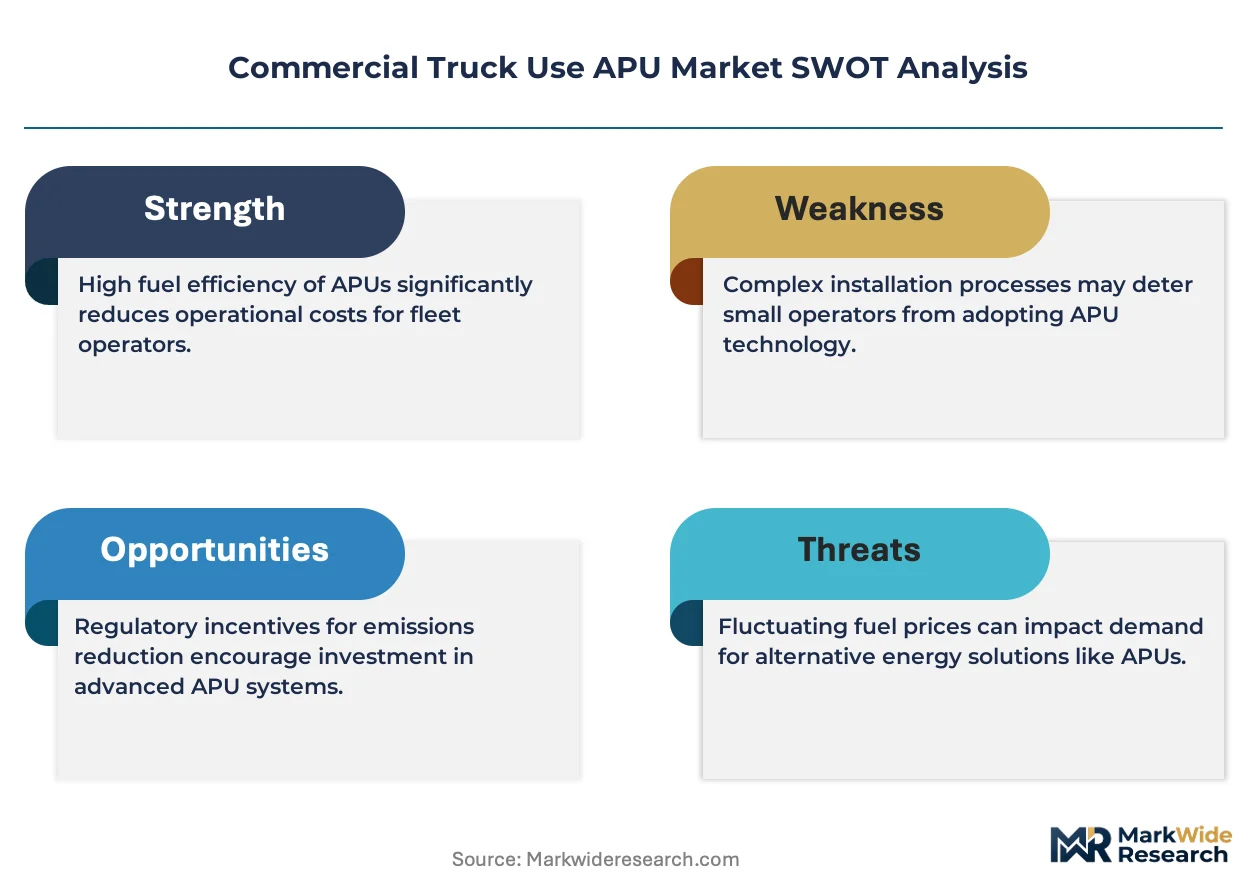
The EPA's escalating idle emissions enforcement is compressing fleet operator upgrade cycles, forcing simultaneous infrastructure investments in charging hardware and battery-electric APUs across the long-haul corridor.
Growth Catalysts
- EPA Phase 3 Standards:Federal greenhouse gas rules for heavy-duty vehicles tighten idle emission limits, mandating APU installation or equivalent idle-reduction technology for compliance.
- Lithium-Ion Cost Curves:Battery pack prices have fallen sufficiently to narrow total-cost-of-ownership gaps against diesel APUs, accelerating fleet electrification roadmaps.
- Texas-to-Michigan Freight Density:The I-35 and I-75 corridors concentrate overnight sleeper cab operations where climate control demands drive highest APU utilization rates.
Market Restraints
- Cobalt and Lithium Supply Concentration:Battery raw material processing concentrates in the DRC and Chile, exposing electric APU manufacturers to geopolitical supply disruptions and price volatility.
- Residual Diesel Infrastructure:Decades of fleet investment in diesel maintenance capabilities and fueling networks create asset-stranding risks that slow electric conversion timelines.
- CARB Zero-Emission Corridor Fragmentation:California's accelerated deadlines diverge from federal Phase 3 timelines, forcing interstate operators to maintain dual-compliance equipment configurations.
Strategic Opportunities
- Midwest Fleet Electrification Hubs:Ohio and Indiana-based terminal operators are piloting centralized battery-swap infrastructure that reduces onboard battery weight requirements.
- Telematics-Integrated Predictive Maintenance:Convergence of cellular IoT modules with battery management systems enables remote diagnostics that cut unplanned downtime.
- IRA Commercial Clean Vehicle Credits:Federal tax incentives offset up to 30% of electric APU acquisition costs for qualifying fleet operators.
Industry Challenges
- High-Voltage Technician Scarcity:Fleet maintenance departments lack certified electricians capable of servicing 400V+ battery systems, forcing reliance on OEM service networks.
- Dual-Certification Burden:NHTSA crashworthiness testing and EPA emissions certification create parallel approval pathways that extend product launch timelines.
- Legacy Cab Integration Complexity:Sleeper cab HVAC ducting and electrical architectures vary across truck OEM platforms, complicating standardized APU mounting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Truck Use APU Market |
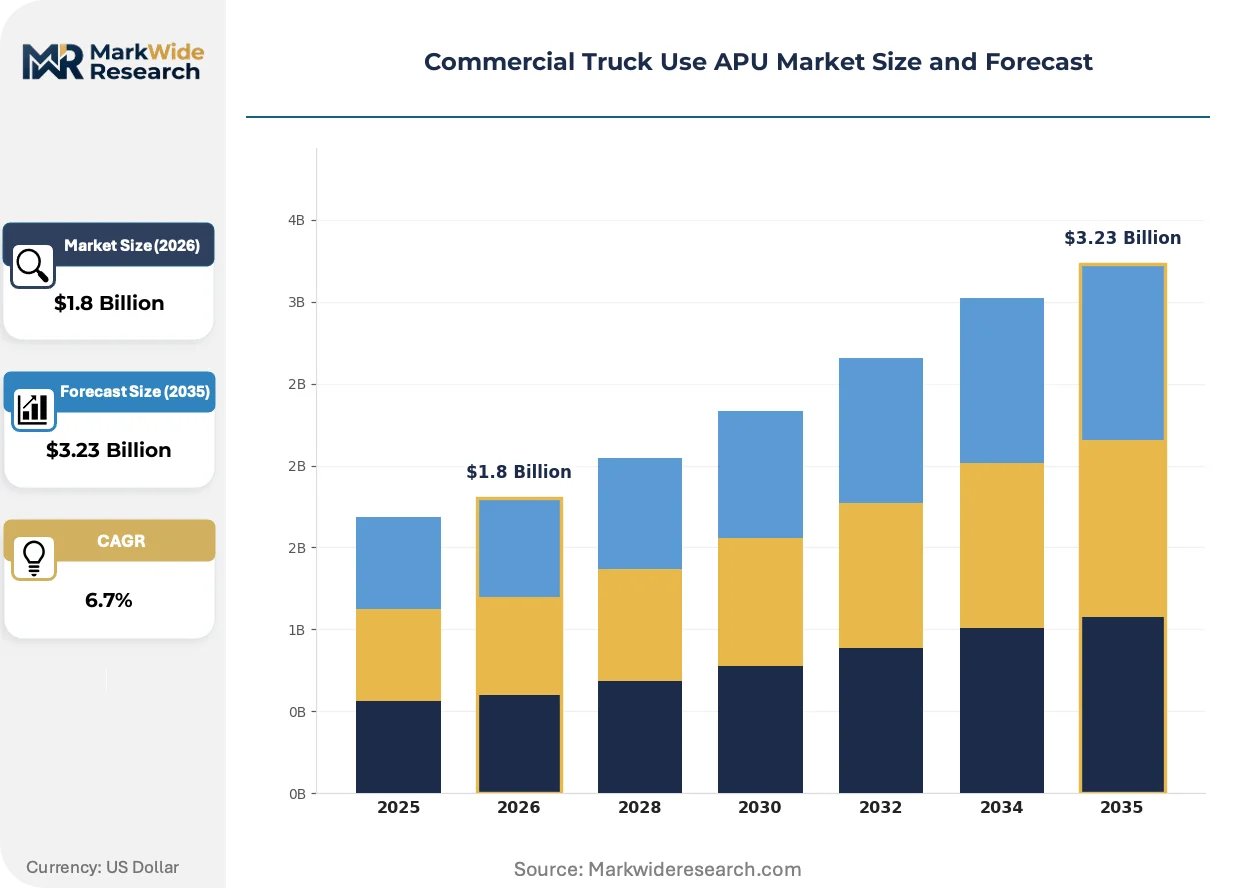
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel APU, Electric APU, Hybrid APU, Solar APU Application: Long-Distance Haulage, City Delivery, Refrigerated Transport, Construction End User: Fleet Operators, Owner-Operators, Logistics Companies, Construction Firms Technology: Thermal Management, Energy Storage, Power Generation, Remote Monitoring |
| Companies Covered | Dynasys, Rigmaster Power International, Thermo King, Dragonfly Energy, CCS Lightning, Carrier ComfortPro, Go Green APU, Bergstrom, Green APU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Truck Use APU Market Trends and Innovations
Electrification is collapsing the traditional divide between power generation and thermal management, creating integrated systems that redefine how fleets spec auxiliary equipment.
Battery-electric APUs with integrated heat pump architecture are unifying climate control and hotel load power into single-unit designs. Large fleet operators running dedicated routes are specifying these systems for 2025 tractor orders. The technology is unifying what were separate diesel APU and electric HVAC procurement decisions into consolidated vendor relationships.
The EPA's 2027 Phase 3 greenhouse gas standards will tighten allowable idle emissions from heavy-duty engines. Manufacturers face redesign cycles to certify electric APUs as compliant idle-reduction alternatives. Sleeper cab configurations serving cross-country routes bear the steepest compliance burden and are driving pre-buy activity ahead of enforcement dates.
Specifying decisions are migrating from individual owner-operators toward centralized fleet procurement functions with standardized equipment mandates. Large carriers with 500-plus tractor fleets are consolidating supplier relationships and negotiating enterprise service agreements. This concentration is most visible among refrigerated haulers operating under strict delivery windows where APU reliability directly affects cargo integrity.
Commercial Truck Use APU Market Segmentation
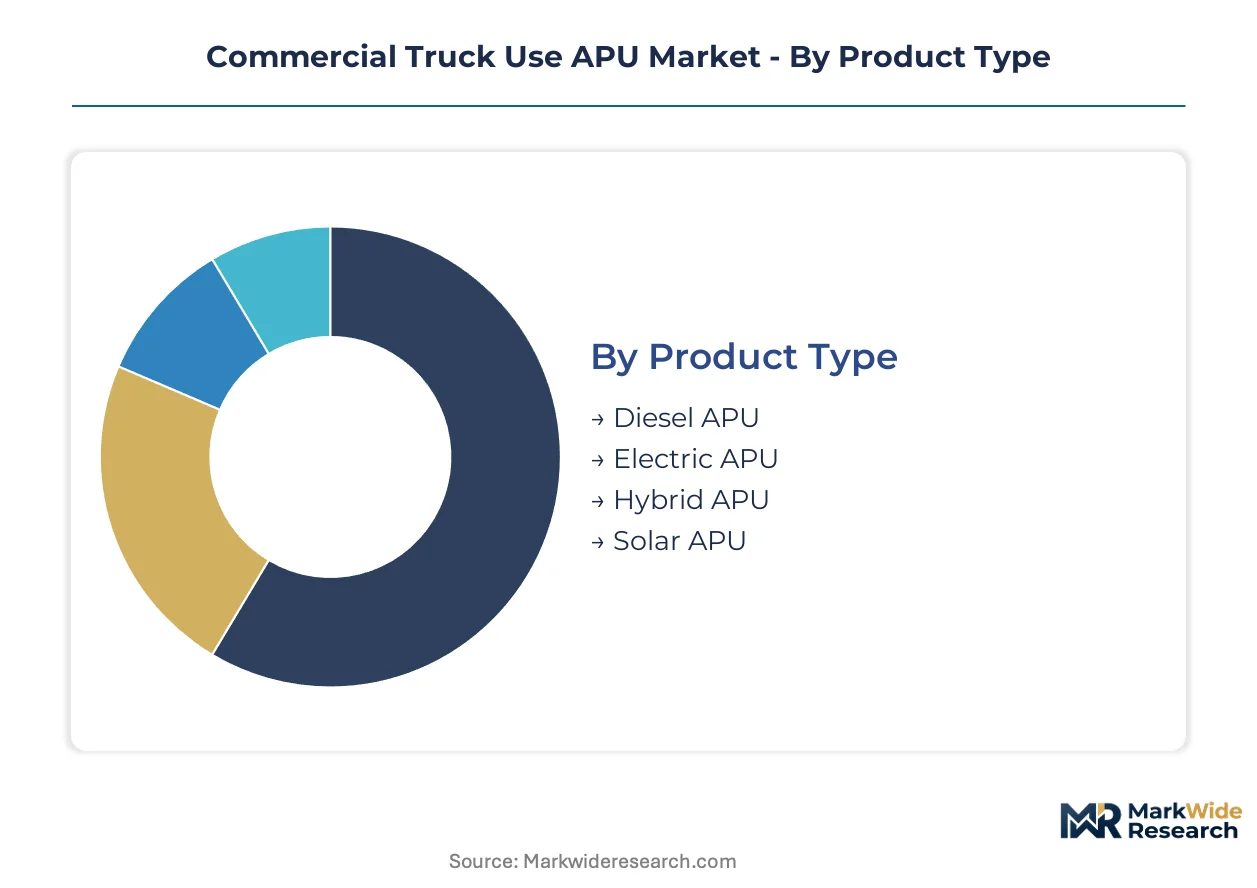
APU procurement decisions fragment across four distinct dimensions, each reflecting divergent upgrade economics and regulatory exposure. Fleet buyers weight total-cost-of-ownership differently against reliability thresholds depending on which segmentation lens they apply.
Product Type:
Replacement-cycle timing varies sharply by powertrain architecture, with diesel-to-electric conversions accelerating where EPA enforcement is tightest.
- Diesel APU:Compression-ignition engines rated 5-15 kW dominate installed base among long-haul fleets with established maintenance infrastructure. Demand concentrates in Texas and the lower Midwest where residual fueling networks and technician familiarity slow electrification timelines.
- Electric APU:Lithium-ion battery systems with integrated inverters are displacing diesel units fastest along the I-75 corridor where CARB-aligned state rules apply. Fleets running dedicated Ohio-to-Michigan loops pilot these for overnight hotel loads.
- Hybrid APU:Diesel-electric combinations optimize for extended autonomy without charging infrastructure.
- Solar APU:Photovoltaic-augmented systems reduce battery cycling in high-insolation regions.
Volume placements concentrate in Diesel APU; the faster expansion belongs to Electric APU.
Application:
Route characteristics dictate climate-control duty cycles and therefore APU sizing specifications.
- Long-Distance Haulage:Sleeper cab operations exceeding 500 miles daily generate 8-10 hour overnight idling demands. The Texas-to-Great Lakes freight corridor drives highest utilization rates where temperature swings exceed 40°F between day and night.
- Refrigerated Transport:Temperature-sensitive cargo mandates continuous power for trailer refrigeration units alongside cab climate control. Fleets serving produce lanes from California's Central Valley to Chicago distribution hubs specify redundant APU capacity.
- City Delivery:Short-haul return-to-base routes enable plug-in charging.
- Construction:Off-grid equipment power needs favor ruggedized diesel units.
Long-Distance Haulage captures the largest installed base; Refrigerated Transport commands the steepest premium pricing.
End User:
Procurement centralization separates enterprise fleet decisions from individual owner-operator preferences.
- Fleet Operators:Carriers with 500-plus tractor fleets standardize on single-vendor service agreements and negotiate enterprise pricing. These buyers prioritize telematics integration and predictive maintenance capabilities across the Midwest terminal network.
- Owner-Operators:Independent drivers self-finance equipment and favor premium remote monitoring features. This segment generates higher per-unit margins due to preference for extended warranties and mobile service coverage.
- Logistics Companies:Third-party freight brokers influence specifications through shipper sustainability mandates.
- Construction Firms:Equipment rental fleets cycle APUs on heavy-duty vocational chassis.
Fleet Operators drive absolute unit volume; Owner-Operators sustain margin extraction.
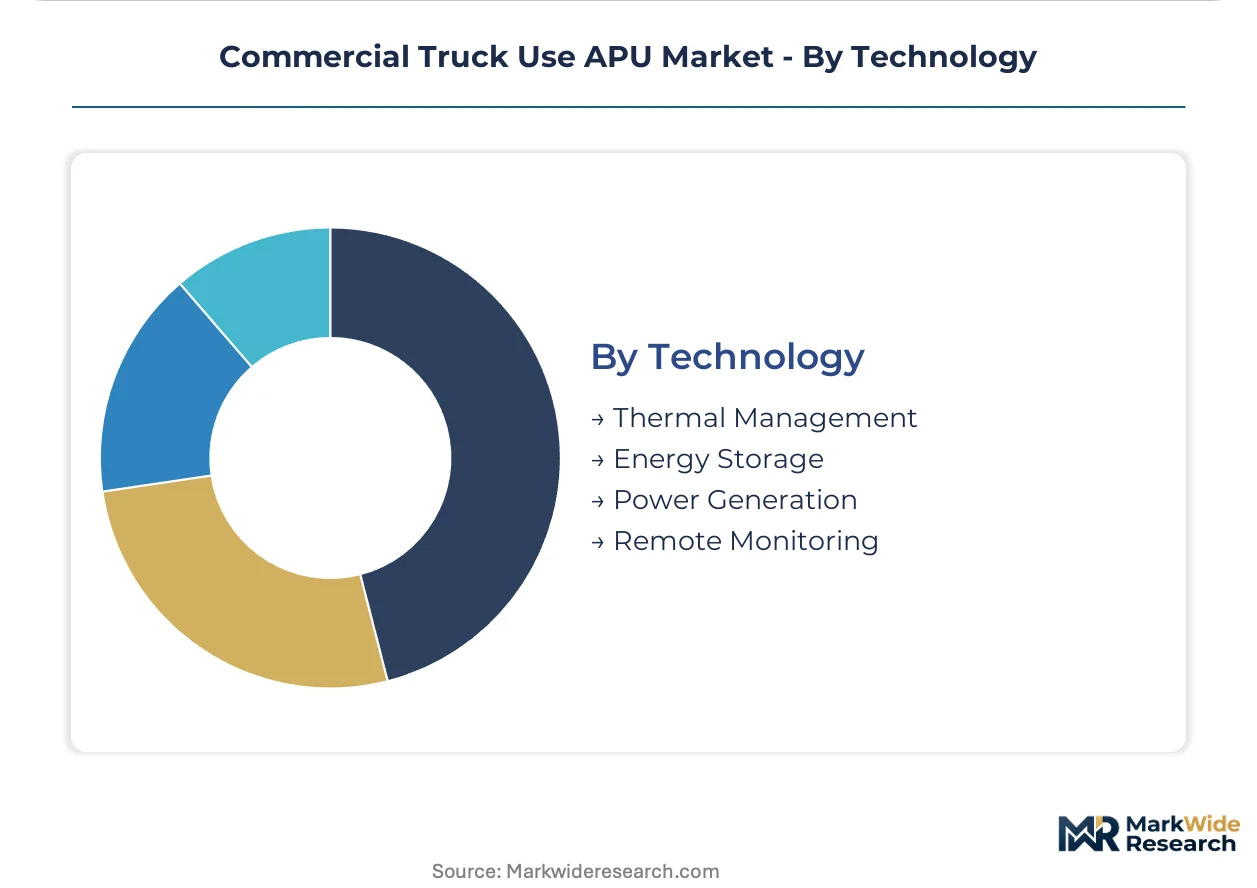
Technology:
System integration depth separates component suppliers from full-platform vendors.
- Thermal Management:Heat pump and HVAC integration unifies climate control with power generation in next-generation designs. This capability concentrates procurement decisions among refrigerated haulers where cargo integrity depends on temperature stability.
- Energy Storage:Battery management systems and pack architecture determine cycle life and safety certification. Lithium iron phosphate chemistries are gaining favor among risk-averse fleet safety officers.
- Power Generation:Inverter and generator set specifications define electrical output quality.
- Remote Monitoring:Cellular IoT modules enable predictive maintenance and warranty compliance tracking.
Thermal Management anchors platform differentiation; Energy Storage is climbing the fastest as electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Chile's Atacama Desert and cobalt processing in the Democratic Republic of Congo anchor raw material flows for electric APU battery packs. These supply chains feed assembly operations concentrated near North American freight corridors and European logistics hubs.
United States
The I-35 corridor from Texas through Oklahoma and the I-75 spine from Ohio to Michigan concentrate overnight sleeper cab operations where temperature swings drive APU utilization. EPA Phase 3 standards tighten idle emissions limits for heavy-duty vehicles through 2027. Fleets in Columbus, Ohio and Detroit, Michigan pilot centralized battery-swap infrastructure to reduce onboard weight.
Germany
The Rhine-Ruhr logistics cluster and Bavarian freight terminals generate sustained demand for auxiliary power in cross-border haulage. EU Green Deal regulations and the F-Gas Regulation push fleet operators toward zero-emission idle reduction technologies. Stuttgart-based engineering consultancies advise multinational carriers on diesel-to-electric conversion roadmaps.
China
Domestic long-haul routes connecting manufacturing zones in Guangdong to consumption centers in Sichuan create overnight parking demand at highway service stations. MIIT efficiency standards and provincial dual carbon goals accelerate electric APU trials. Ningbo-Zhoushan port logistics operators test integrated battery systems for refrigerated container haulage.
Canada
The Windsor-Quebec City corridor and Prairie grain transport routes sustain diesel APU demand where charging infrastructure remains sparse. Environment and Climate Change Canada aligns heavy-duty vehicle regulations with EPA timelines. Alberta fleet operators evaluate solar-augmented systems for high-insolation prairie operations.
Mexico
Cross-border manufacturing supply chains linking Monterrey to Texas distribution hubs generate overnight truck parking demand at border crossings. SEMARNAT emissions standards tighten for heavy-duty vehicles serving USMCA trade corridors. Nuevo León-based carriers face compliance pressure from US-based shipper sustainability mandates.
Commercial Truck Use APU Market Competitive Landscape
Global majors compete with regional champions across thermal management integration and electrification roadmaps. The vendor base separates into three tiers: diversified HVAC conglomerates with captive APU divisions, specialized auxiliary power manufacturers, and battery-system integrators entering from adjacent energy storage markets. Dominant competitive moves include strategic partnerships between battery cell suppliers and thermal management specialists, plus geographic expansion through dealer network acquisitions.
Within the diversified industrial tier, Thermo King and Carrier ComfortPro exemplify platform breadth spanning refrigeration and cab climate control. Bergstrom occupies a position among HVAC specialists with sleeper cab integration heritage. Dragonfly Energy represents battery-system integrators leveraging lithium-ion expertise from adjacent marine and recreational vehicle markets.
| Leading Market Players |
|---|
| Dynasys |
| Rigmaster Power International |
| Thermo King |
| Dragonfly Energy |
| CCS Lightning |
| Carrier ComfortPro |
| Go Green APU |
| Bergstrom |
| Green APU |
| Others |
Pricing and Supply Chain Analysis
Captive battery cell production by Tier 1 thermal management conglomerates anchors both supply security and pricing power across the electric APU segment, insulating integrated vendors from lithium price volatility while forcing specialized assemblers into spot-market exposure.
Pricing Analysis
Warranty and service bundling separates premium vendor tiers from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UL certification grade and telematics integration depth. Cost compression in the economy tier is intensifying because Chinese battery integrators are flooding the aftermarket with uncertified units. Fleet operators with enterprise service agreements demonstrate lowest price sensitivity, while independent owner-operators negotiate hardest on upfront hardware costs.
Supply Chain Analysis
UL 1973 and UN 38.3 certification gating restricts qualified cell suppliers to a narrow tier of tested manufacturers. Battery pack assembly concentrates in China, South Korea, and Michigan-based operations serving North American OEMs. Cobalt cathode precursors and lithium hexafluorophosphate electrolytes draw from DRC and Chilean upstream nodes. Single-source vulnerability in cathode active material exposes assemblers to forced labor compliance audits. Distribution runs through OEM dealer networks and independent truck equipment installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 idle emissions standards have transformed APU procurement from a fuel-saving option into a cost-of-compliance mandate, erecting certification barriers that protect incumbent vendors with established EPA and NHTSA approval pathways.
For Market Incumbents: Extend service network density along the I-75 corridor to defend against battery-system integrators entering from adjacent marine markets. Deepen backward integration into lithium iron phosphate cell supply through offtake agreements with Tier 1 cathode producers. Prioritize NHTSA crashworthiness pre-certification to accelerate electric APU platform launches ahead of 2027 enforcement deadlines. For New Entrants and Emerging Players: Launch via direct fleet procurement channels targeting refrigerated haulers with cargo-integrity-driven reliability requirements. White-space opportunities concentrate in solar-augmented systems for high-insolation prairie operations and battery-swap service models for dedicated-loop Midwest fleets. Avoid competing on upfront price against established diesel APU incumbents with amortized R&D. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified HVAC conglomerates seeking electrification capabilities. Five-to-ten-year viability favors vendors with integrated thermal management platforms over pure-play battery assemblers. Monitor CARB zero-emission corridor timeline acceleration as the signal to watch for electric APU demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium iron phosphate capacity for EPA-compliant electric APU platforms. |
| Thermal Management Integration | Unifies HVAC and power generation procurement for refrigerated fleet operators. |
| Telematics Platform Partnership | Enables predictive maintenance contracts with large Midwest fleet accounts. |
| Dealer Network Acquisition | Expands service coverage along Texas-to-Michigan freight corridors. |
| Certification Investment | Accelerates UL 1973 and UN 38.3 approvals for battery safety compliance. |
Research Methodology
EPA regulatory filings, NHTSA safety certification databases, and fleet operator equipment procurement records formed the secondary backbone. Primary interviews with fleet maintenance directors, OEM platform engineers, thermal management R&D heads, and aftermarket distributor principals validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down fleet penetration rates across the analysis window.
Historical trendline analysis of diesel-to-electric conversion rates informed projection frameworks across powertrain architecture, application duty cycle, end-user procurement centralization, and technology integration depth. CAGRs derived from segment-level growth trajectories weighted by EPA enforcement phase-in schedules. Forecast inputs incorporated lithium-ion cost curve assumptions and charging infrastructure buildout timelines.
Regulatory timeline delays, raw material price spikes, and fleet capital expenditure freezes are the dominant revision risks. Forecasts reflect assumptions about Phase 3 compliance adherence and battery swap pilot scalability. A model refresh is warranted upon material change in CARB zero-emission corridor enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market