
 UAE Commercial Vehicles Market | 2026-2036
UAE Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Commercial Vehicles Market Insights
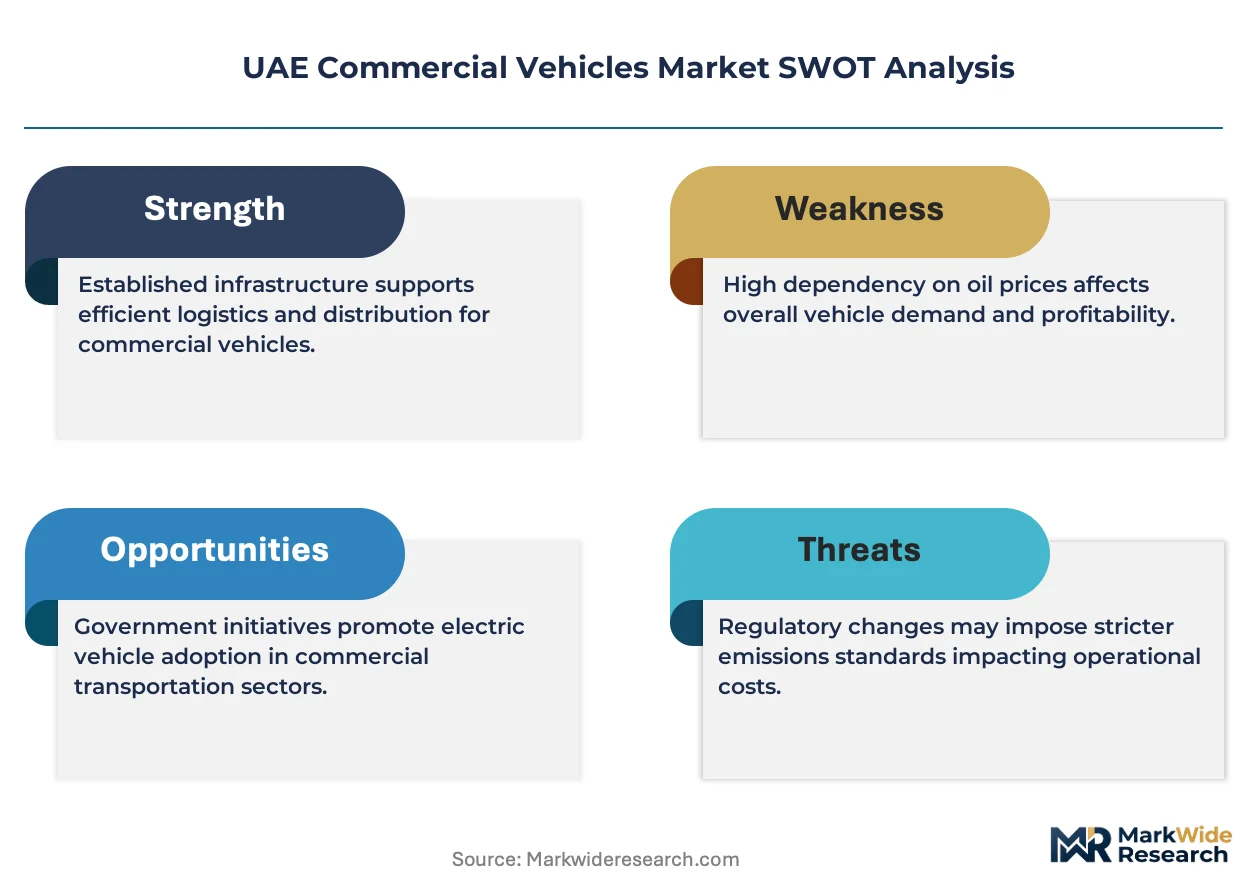
The divergence between premium European-built fleets and commodity Asian-sourced vehicles is realigning procurement patterns across UAE fleet operators. Mercedes-Benz Group leverages its established service network to sustain premium positioning in long-haul heavy truck segments. Tata Motors competes aggressively on total cost of ownership, anchoring volume sales in light truck categories favored by small and mid-sized logistics contractors.
Commercial vehicles encompass motor vehicles designed for goods carriage or passenger transport exceeding nine seats, with gross vehicle weight ratings spanning 3.5 to over 40 tonnes and powertrain configurations optimized for desert climate endurance and high ambient temperature operation. Heavy trucks dominate value pools due to extended replacement cycles and higher specification content, while electric fuel type categories attract disproportionate policy support despite infrastructure immaturity. Light trucks and vans occupy the highest transaction volume tiers, though margin compression intensifies as Chinese manufacturers extend distribution reach through Dubai-based trading houses.
MOHAP vehicle registration standards, Ministry of Climate Change and Environment emissions protocols, and Abu Dhabi Quality and Conformity Council safety certifications collectively shape product compliance requirements and market access conditions for imported commercial vehicles. The UAE's alignment with Gulf Standardization Organization technical regulations further harmonizes specification demands across emirate-level jurisdictions. Stakeholders must monitor charging infrastructure deployment timelines and hydrogen pilot program outcomes to calibrate powertrain portfolio commitments.
Market Dynamics
Logistics fleet operators in the Emirates face a structural pivot as MOHAP emissions protocols force Euro 5-equivalent powertrain transitions before charging infrastructure matures, compressing procurement timelines and supplier qualification windows.
Growth Catalysts
- E-commerce fulfillment networks:Last-mile delivery contractors across Dubai's Jebel Ali corridor are expanding light truck and van procurement to serve same-day delivery commitments from regional distribution centers.
- MOHAP emissions alignment:The Ministry of Health and Prevention's vehicle registration standards are accelerating replacement cycles for pre-2020 heavy truck fleets in Abu Dhabi's Khalifa Industrial Zone.
- Desert climate engineering:Cooling system and powertrain modifications optimized for 50°C ambient operation are opening specification premiums for vehicles qualified under Gulf Standardization Organization technical regulations.
Market Restraints
- Charging infrastructure immaturity:Fleet electrification timelines face delays as inter-emirate fast-charging corridors for heavy commercial vehicles remain under construction.
- Import supply concentration:Light truck volume depends heavily on Asian manufacturing hubs funneled through Dubai-based trading houses, creating exposure to shipping lane disruptions.
- Hydrogen pilot uncertainty:Abu Dhabi and Dubai hydrogen fuel cell trials for long-haul freight lack committed refueling station deployment schedules, freezing powertrain portfolio decisions.
Strategic Opportunities
- Al Ain logistics corridor expansion:Underpenetrated inland freight routes connecting Abu Dhabi's eastern region to Saudi border crossings offer first-mover positioning for medium-duty truck specialists.
- Telematics-integrated leasing:Usage-based financing models combining vehicle, maintenance, and route optimization software are displacing traditional asset ownership among mid-sized contractors.
- Ministry of Climate Change and Environment incentives:Early-adopter credits for zero-emission commercial vehicle registrations are creating procurement windows ahead of 2030 mandate phases.
Industry Challenges
- Powertrain technician scarcity:High-voltage electric and hydrogen fuel cell maintenance certification programs have not scaled to match fleet electrification timelines.
- Multi-emirate compliance complexity:Abu Dhabi Quality and Conformity Council safety certifications diverge from Dubai's technical requirements, fragmenting homologation processes for national fleet operators.
- Aftermarket parts availability:Extended replacement cycles for premium European heavy trucks strain local inventory depth for specialized driveline components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Commercial Vehicles Market |
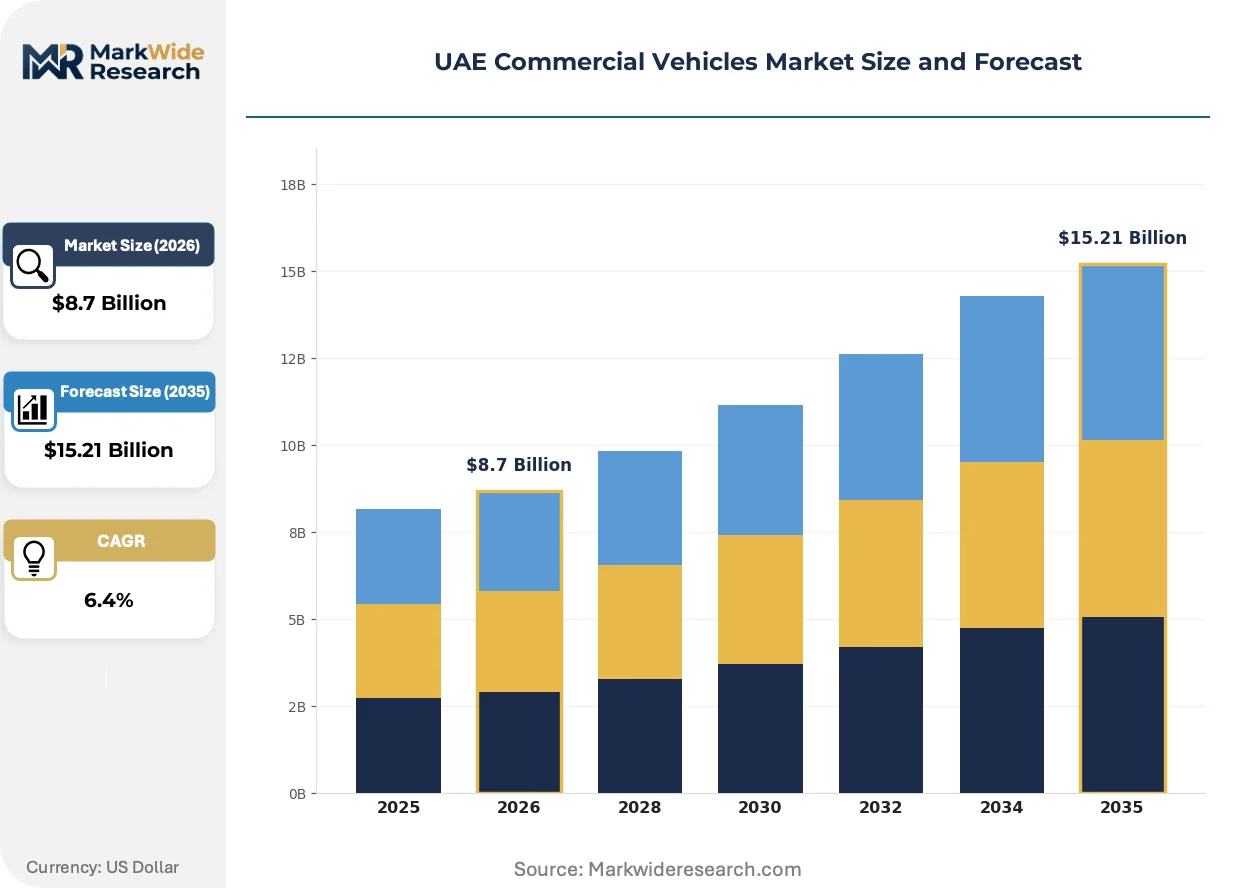
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Heavy Trucks, Light Trucks, Buses, Vans End User: Logistics, Construction, Public Transport, Mining Fuel Type: Diesel, CNG, Petrol, Electric Application: Freight Transport, Passenger Transport, Construction Services, Waste Management |
| Companies Covered | Mercedes-Benz Group, Volvo Group, Tata Motors, Dongfeng Commercial Vehicle Company Limited, Volkswagen AG, Toyota Motor Corporation, Nissan Motor Co., Ltd., Mitsubishi Fuso Truck and Bus Corporation, Isuzu Motors Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Commercial Vehicles Market Trends and Innovations
Technology convergence and regulatory compression are redefining how UAE fleet operators specify, finance, and maintain commercial vehicle assets across the emirates.
Advanced driver-assistance systems for heavy trucks are automating lane-keeping and adaptive cruise functions in long-haul desert corridor operations. Major logistics contractors in Dubai's Jebel Ali zone are piloting Level 2 automation for hub-to-hub freight routes. This capability is automating driver workload reduction specifications in fleet procurement tenders, compressing price premiums for baseline safety packages.
MOHAP vehicle registration standards now mandate onboard diagnostics compatibility with federal emissions monitoring infrastructure. The Ministry of Health and Prevention's alignment with Gulf Standardization Organization protocols forces importers to pre-certify engine management systems before customs clearance. Heavy truck distributors are responding by consolidating homologation resources in Dubai to serve all seven emirates.
Fleet operators are consolidating procurement authority at the holding-company level, displacing decentralized buying by individual logistics subsidiaries. Centralized tendering committees in Abu Dhabi and Dubai are bundling vehicle, maintenance, and telematics contracts into multi-year agreements. This concentration is most visible among e-commerce fulfillment specialists operating across the Khalifa Industrial Zone and Dubai South logistics clusters.
UAE Commercial Vehicles Market Segmentation
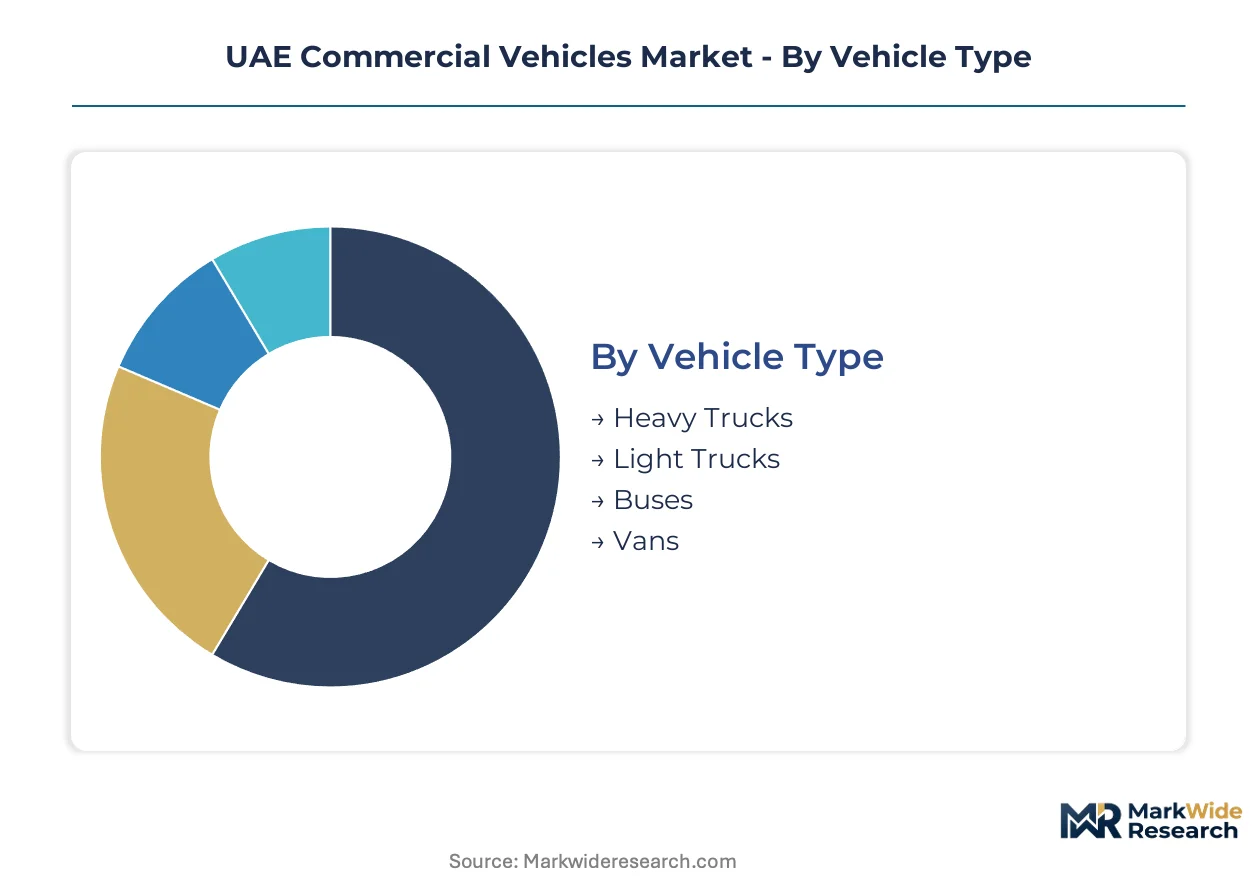
UAE fleet operators specify vehicles across four intersecting dimensions that determine compliance pathways, financing structures, and service network requirements. Procurement committees weight these categories differently depending on emirate-level regulations and corridor-specific operational demands.
Vehicle Type:
Customization intensity spans from standardized van platforms to bespoke heavy truck configurations engineered for desert climate endurance.
- Heavy Trucks:Gross vehicle weight ratings exceeding 16 tonnes with reinforced cooling systems and powertrain modifications for 50°C ambient operation. Demand concentrates in Abu Dhabi's Khalifa Industrial Zone where long-haul contractors face compressed replacement cycles under MOHAP emissions protocols.
- Light Trucks:Weight classes between 3.5 and 16 tonnes GVWR serving last-mile logistics networks. Dubai's Jebel Ali corridor contractors are expanding procurement to fulfill same-day delivery commitments from regional distribution centers.
- Buses:Passenger configurations exceeding nine seats with climate-controlled cabins for inter-emirate transit routes.
- Vans:Compact cargo platforms dominating transaction volumes among small logistics contractors and independent delivery operators.
Leading the category by volume: Light Trucks. Growing fastest: Heavy Trucks.
End User:
Customer sophistication tiers separate enterprise fleet operators with centralized procurement from fragmented contractor segments.
- Logistics:E-commerce fulfillment specialists and third-party logistics providers operating across Dubai South and Khalifa Industrial Zone clusters. These operators bundle vehicle, maintenance, and telematics contracts into multi-year agreements.
- Construction:Heavy civil contractors and infrastructure developers requiring specialized tipper and mixer configurations for megaproject sites.
- Public Transport:Municipal and intercity bus operators under emirate-level transport authorities with standardized fleet specifications.
- Mining:Quarry and aggregate extraction operators in Ras Al Khaimah and Fujairah requiring extreme-duty chassis modifications.
Highest procurement concentration: Logistics. Steepest expansion trajectory: Construction.
Fuel Type:
Powertrain portfolios span mature diesel infrastructure through emerging zero-emission platforms with uneven regulatory support.
- Diesel:Dominant fuel category for heavy freight applications with established service networks and parts availability across all seven emirates.
- CNG:Compressed natural gas configurations gaining traction among municipal fleet operators with access to pipeline infrastructure in Abu Dhabi and Dubai.
- Petrol:Light truck and van applications where total cost of ownership calculations favor lower upfront capital requirements over fuel efficiency.
- Electric:Battery-electric platforms attracting Ministry of Climate Change and Environment incentives despite inter-emirate charging corridor immaturity for heavy commercial vehicles.
Current volume leader: Diesel. Gaining share fastest: Electric.
Application:
Operational intensity differentiates high-utilization freight corridors from intermittent service deployments.
- Freight Transport:Hub-to-hub and last-mile cargo movement connecting Jebel Ali port facilities to inland distribution nodes across the Emirates.
- Passenger Transport:Scheduled intercity services and employee shuttle operations requiring compliance with Abu Dhabi Quality and Conformity Council safety certifications.
- Construction Services:Material delivery and on-site logistics supporting concurrent megaproject execution in Dubai and Abu Dhabi.
- Waste Management:Municipal collection fleets and industrial hazardous material transport with specialized body equipment requirements.
Dominant application by fleet value: Freight Transport. Expanding most quickly: Waste Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali logistics corridor anchors commercial vehicle demand across the Emirates, with fleet procurement concentrated in port-adjacent free zones and inland distribution clusters stretching toward Abu Dhabi.
Dubai
Last-mile delivery contractors are expanding light truck and van fleets to fulfill same-day e-commerce commitments from regional distribution centers. MOHAP vehicle registration standards mandate Euro 5-equivalent emissions compliance for all new registrations. The Jebel Ali corridor and Dubai South logistics cluster host the densest concentration of third-party logistics procurement activity.
Abu Dhabi
Heavy truck replacement cycles are compressing as pre-2020 diesel fleets face accelerated phase-out under Ministry of Climate Change and Environment protocols. The Khalifa Industrial Zone serves as the primary hub for long-haul freight operators serving Saudi border crossings. Fleet operators here are consolidating procurement authority at holding-company level for multi-year maintenance and telematics bundling.
Sharjah
Mid-sized logistics contractors favor light truck categories sourced through Dubai-based trading houses for cost-sensitive construction material transport. The emirate's industrial zones benefit from proximity to both Dubai's port infrastructure and northern emirate quarry operations. Cooling system specifications optimized for 50°C ambient operation command specification premiums in Sharjah's inland freight routes.
Northern Emirates
Ras Al Khaimah and Fujairah quarry operators require extreme-duty chassis modifications for aggregate extraction and heavy-civil material movement. Mining fleet procurement prioritizes desert climate endurance over emissions compliance timelines. The underpenetrated Al Ain logistics corridor connecting Abu Dhabi's eastern region to Saudi border crossings offers positioning opportunities for medium-duty specialists.
UAE Commercial Vehicles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service network depth and specification content, with European manufacturers commanding position in heavy truck segments while Asian competitors anchor volume tiers in light commercial categories. The vendor base organizes into three strategic archetypes: established premium brands with certified service infrastructure, scale-driven Asian manufacturers competing on total cost of ownership, and emerging Chinese entrants penetrating through Dubai-based trading channels. Consolidation pressure is intensifying through centralized fleet procurement at holding-company level, while distributor-level partnerships are displacing direct manufacturer presence in after-sales service.
Among European premium manufacturers, Mercedes-Benz Group and Volvo Group exemplify the service-network-dependent archetype, with established homologation resources consolidated in Dubai to serve all seven emirates. Tata Motors anchors the Asian scale-driven tier, competing aggressively on total cost of ownership in light truck categories favored by small and mid-sized logistics contractors.
| Leading Market Players |
|---|
| Mercedes-Benz Group |
| Volvo Group |
| Tata Motors |
| Dongfeng Commercial Vehicle Company Limited |
| Volkswagen AG |
| Toyota Motor Corporation |
| Nissan Motor Co., Ltd. |
| Mitsubishi Fuso Truck and Bus Corporation |
| Isuzu Motors Ltd. |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum input costs flow from East Asian mills through Dubai-based trading houses before reaching procurement committees at UAE fleet operators, compressing margin structures for light truck distributors while reinforcing premium positioning for European heavy truck manufacturers with captive after-sales networks.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for heavy truck fleets operating across Abu Dhabi's Khalifa Industrial Zone and Dubai's Jebel Ali corridor. Three-tier pricing structure across premium, standard, and economy levels separates Mercedes-Benz and Volvo service-bundled offerings from Tata Motors TCO-focused propositions and Chinese trading-house imports. Cost compression in light truck categories is intensifying because Dubai-based distributors are absorbing currency volatility to maintain volume commitments with Asian manufacturers. Small and mid-sized logistics contractors show highest price sensitivity, while enterprise fleet operators with centralized procurement prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Regional distribution centers in Jebel Ali Free Zone and Dubai Industrial City orchestrate hub-and-spoke patterns radiating to northern emirate contractors and Saudi border crossings. Manufacturing concentrates in India, Thailand, and China for light commercial vehicles, while European heavy truck assembly feeds from Germany, Sweden, and the Netherlands. Critical component dependencies include high-pressure common-rail injection systems, desert-rated cooling modules, and telematics hardware. Single-source vulnerability runs through specialized driveline components for premium European fleets. Distribution runs through authorized dealer networks for premium brands and independent trading houses for Asian-sourced volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE fleet procurement is transitioning from diesel-dominant specifications toward Euro 5-equivalent and zero-emission powertrains, with battery-electric platforms displacing legacy diesel in light truck categories ahead of heavy freight electrification.
For Market Incumbents: Lock in service network exclusivity across Dubai and Abu Dhabi before Chinese manufacturers establish certified maintenance partnerships. Consolidate homologation resources to serve all seven emirates under unified Gulf Standardization Organization protocols. Defend against trading-house import erosion by embedding telematics and predictive maintenance into multi-year lease contracts. Prioritize technician certification scaling for high-voltage electric and hydrogen fuel cell systems. For New Entrants and Emerging Players: Begin with medium-duty truck positioning in the underpenetrated Al Ain logistics corridor connecting Abu Dhabi's eastern region to Saudi border crossings. Target construction material transport contractors in Sharjah's industrial zones where cost sensitivity exceeds brand loyalty. Penetrate through usage-based leasing models bundling vehicle, maintenance, and route optimization software rather than competing on upfront asset sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor telematics-integrated fleet lessors in Dubai with established MOHAP registration relationships and scalable software platforms. Long-term viability hinges on powertrain portfolio flexibility across diesel, electric, and hydrogen through the decade ahead. Monitor hydrogen pilot program commitment schedules from Abu Dhabi and Dubai transport authorities as the critical inflection signal for fuel cell commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Service Network Certification Expansion | MOHAP-aligned maintenance partnerships lock out trading-house competitors from premium fleet contracts. |
| Telematics-Integrated Leasing Platforms | Usage-based financing displaces asset ownership among mid-sized Jebel Ali corridor contractors. |
| Hydrogen Fuel Cell Pilot Participation | Early engagement with Ministry of Climate Change and Environment trials secures refueling infrastructure priority. |
| Cross-Emirate Homologation Consolidation | Unified Gulf Standardization Organization certification reduces compliance fragmentation for national fleet operators. |
| Technician Training Program Scaling | High-voltage electric and hydrogen maintenance certification addresses powertrain technician scarcity before fleet electrification accelerates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet procurement directors at Dubai and Abu Dhabi logistics holding companies, MOHAP vehicle registration officials, aftermarket service network managers, and trading house import specialists. Secondary sources included Ministry of Climate Change and Environment emissions protocols, Abu Dhabi Quality and Conformity Council safety certifications, Gulf Standardization Organization technical regulations, and vehicle production databases. Bottom-up fleet operator demand modeling and top-down macroeconomic indicators were triangulated to validate market sizing.
Data-stream reconciliation across vehicle registration volumes, import customs declarations, and distributor sales disclosures informed the analytical framework. Segmentation dimensions modeled span vehicle type, end user category, fuel type, and application intensity across the projection horizon. CAGRs were derived from replacement cycle compression under emissions protocols and e-commerce fulfillment fleet expansion. Industry-specific forecast inputs included charging infrastructure deployment timelines and hydrogen pilot program commitment schedules.
Underlying measurement precision varies by segment; heavy truck value pools and logistics end-user categories carry tighter precision than mining and construction applications. Forecasts reflect assumptions around regulatory phase-in schedules and infrastructure investment commitments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market