
 Malaysia Box Truck Market | 2026-2036
Malaysia Box Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Box Truck Market Outlook
Market Overview
Aftermarket service revenue is narrowing as a margin pool as original equipment manufacturers tighten control over parts distribution and authorized servicing networks. Isuzu Motors Ltd. leverages its established dealer infrastructure to capture recurring maintenance spend from fleet operators. Hino Motors Ltd. anchors its position through backward integration into engine and transmission refurbishment capabilities. Tata Motors Limited competes on total cost of ownership positioning for price-sensitive logistics buyers in Peninsular Malaysia.
Technical Definition and Segment Structure
A box truck is a rigid commercial vehicle with a fully enclosed rectangular cargo body mounted on a ladder-frame chassis, typically featuring gross vehicle weights from 3.5 to 26 tonnes and cube-shaped load compartments optimized for palletized freight. Its primary commercial purpose is last-mile and inter-urban distribution of packaged goods where weather protection and security outweigh the flexibility of curtain-sided or flatbed alternatives. Light duty vehicles dominate unit volumes for urban e-commerce fulfillment, while medium duty configurations carry the strongest margin pools due to their versatility across food transport and construction material hauling. Electric propulsion remains nascent but attracts fleet trial orders as charging infrastructure deploys along the North-South Expressway corridor.
Regulatory Environment and Outlook
Malaysia's Road Transport Department enforces commercial vehicle fitness certification under the Motor Vehicles Act, while the Department of Environment administers emission thresholds that will tighten with Euro 5 implementation. BIS standards govern braking performance and occupant safety, creating compliance barriers for imported used trucks. The Ministry of Investment, Trade and Industry coordinates PLI scheme incentives for local assembly of electric commercial vehicles. Stakeholders must monitor how carbon-border adjustment mechanisms in EU destination markets reshape specifications for export-linked logistics fleets.
Market Dynamics
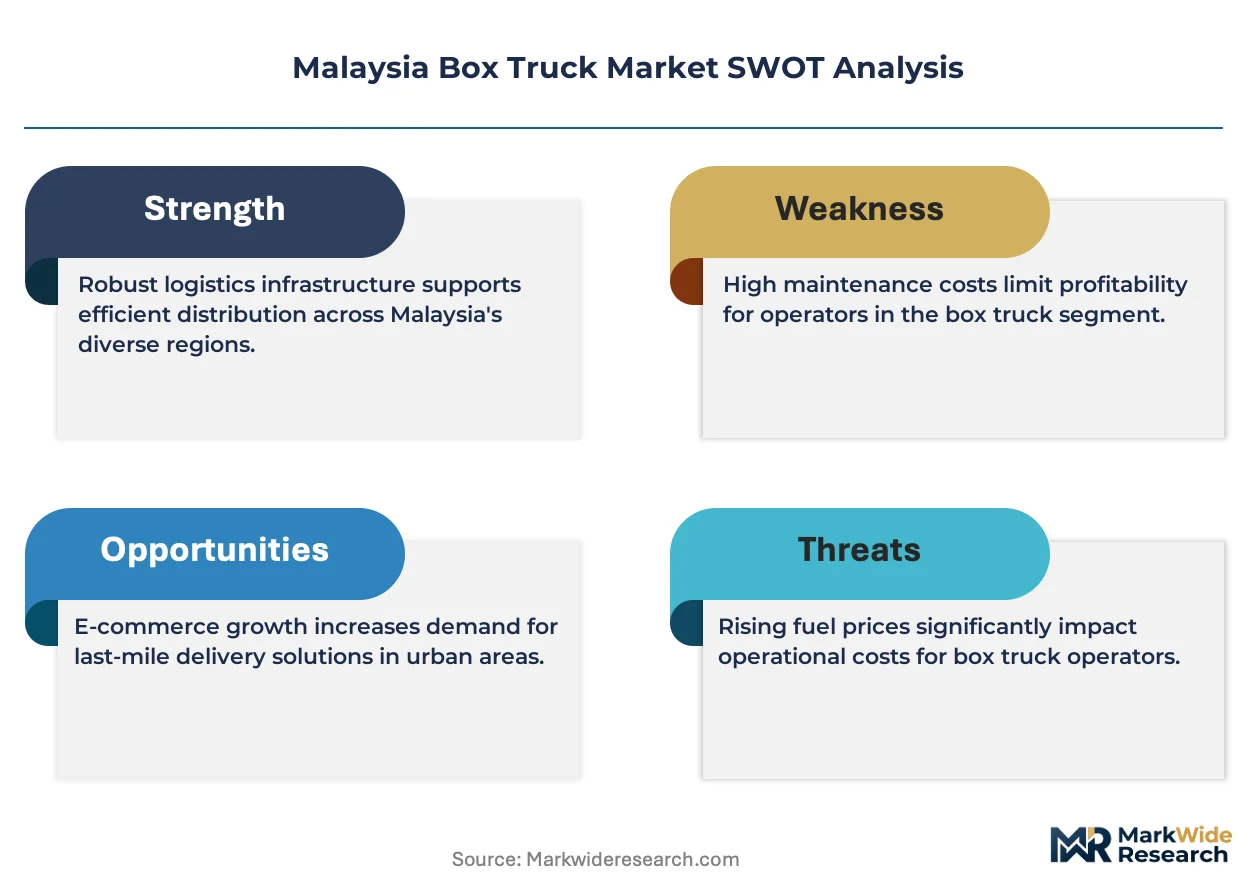
Euro 5 emission norms are compressing the operational window for diesel-powered fleets while accelerating capital rotation toward cleaner propulsion alternatives across Peninsular Malaysia's logistics corridors.
Growth Catalysts
- Port-linked manufacturing zones:Selangor and Johor's distribution corridors generate concentrated freight demand from electronics and palm oil export processing facilities.
- PLI scheme incentives:Malaysia's Ministry of Investment, Trade and Industry offers production-linked subsidies for local assembly of electric commercial vehicles, lowering entry barriers for fleet electrification.
- E-commerce fulfillment infrastructure:Urban last-mile networks require weather-protected cargo bodies, driving specification upgrades among third-party logistics operators.
Market Restraints
- Steel and aluminum input volatility:Ladder-frame chassis and enclosed body fabrication costs fluctuate with regional metal commodity pricing, squeezing assembler margins.
- Used truck import barriers:BIS-aligned vehicle safety standards block pre-owned vehicle inflows, constraining price-sensitive buyer alternatives.
- Charging infrastructure gaps:Battery-electric range limitations persist outside the North-South Expressway corridor, delaying fleet-wide electrification timelines.
Strategic Opportunities
- East Malaysia penetration:Sarawak and Sabah's road freight networks remain undersupplied with modern box truck specifications, offering first-mover positioning.
- Food transport cold-chain convergence:Insulated box body integration with refrigeration units addresses expanding fresh produce distribution requirements.
- Euro 5 pre-buy acceleration:Fleet operators advance replacement cycles ahead of 2025 implementation, creating concentrated order windows.
Industry Challenges
- Certified technician scarcity:Euro 5 engine diagnostics and electric powertrain maintenance require specialized training programs that Malaysian technical institutes have not yet scaled.
- Multi-emission standard inventory complexity:Dealers must stock parts and service capabilities across Euro 2 through Euro 5 vehicle populations, fragmenting spare parts working capital.
Report Scope
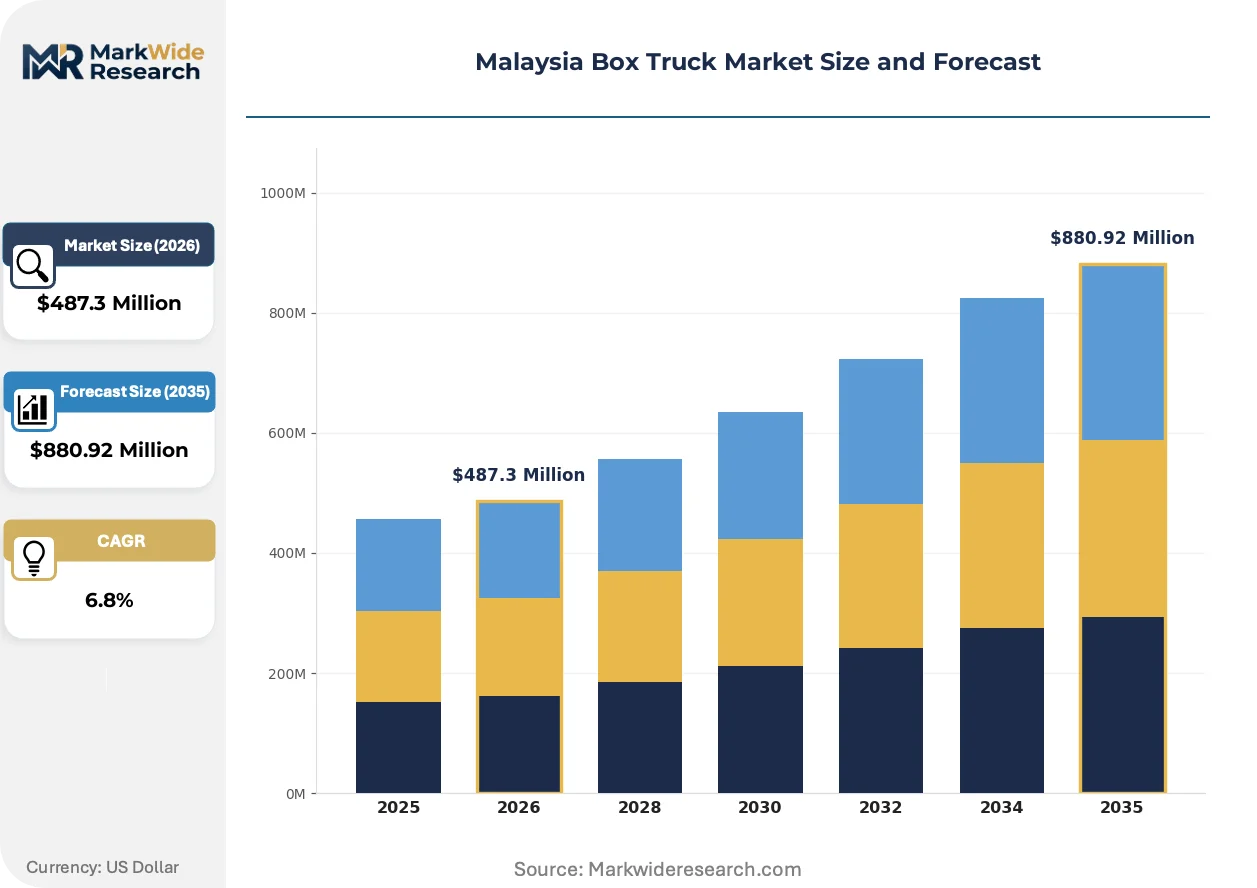
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Box Truck Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Specialty Trucks Payload Capacity: Below 2 Tons, 2-5 Tons, 5-10 Tons, Above 10 Tons Fuel Type: Diesel, Petrol, CNG, Electric Application: Food Transport, E-commerce, Construction, Logistics |
| Companies Covered | Isuzu Motors Ltd., Hino Motors Ltd., Tata Motors Limited, Mitsubishi Fuso Truck and Bus Corporation, UD Trucks Corp., Traton Group, EMAC Power Ltd., Swift Haulage Berhad, A-Plus Manufacturing Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Box Truck Market Strategic Shifts
Propulsion technology and connected fleet management are rewriting procurement criteria, with buyers prioritizing total operating cost visibility over upfront acquisition price.
Telematics-enabled predictive maintenance is migrating from premium fleet segments to mid-duty operator mandates. Large logistics buyers now require onboard diagnostics as a contract precondition. This capability compression is forcing smaller dealers to bundle third-party connectivity solutions or surrender service revenue to OEM-controlled platforms.
Malaysia's Department of Environment administers emission thresholds tightening with Euro 5 implementation, effective for new vehicle registrations. Engine manufacturers must recalibrate after-treatment systems for local fuel sulfur content. Medium-duty configurations face the steepest compliance cost increases, pushing some buyers toward light-duty upsizing.
Third-party logistics operators are consolidating vendor relationships, reducing approved supplier lists from multiple brands to single-source frameworks with national service coverage. This concentration displaces smaller regional dealers dependent on transactional spot sales. The shift is most visible in Selangor's Klang Valley distribution clusters, where warehouse operators prioritize uptime guarantees over capital expenditure flexibility.
Malaysia Box Truck Market Segmentation
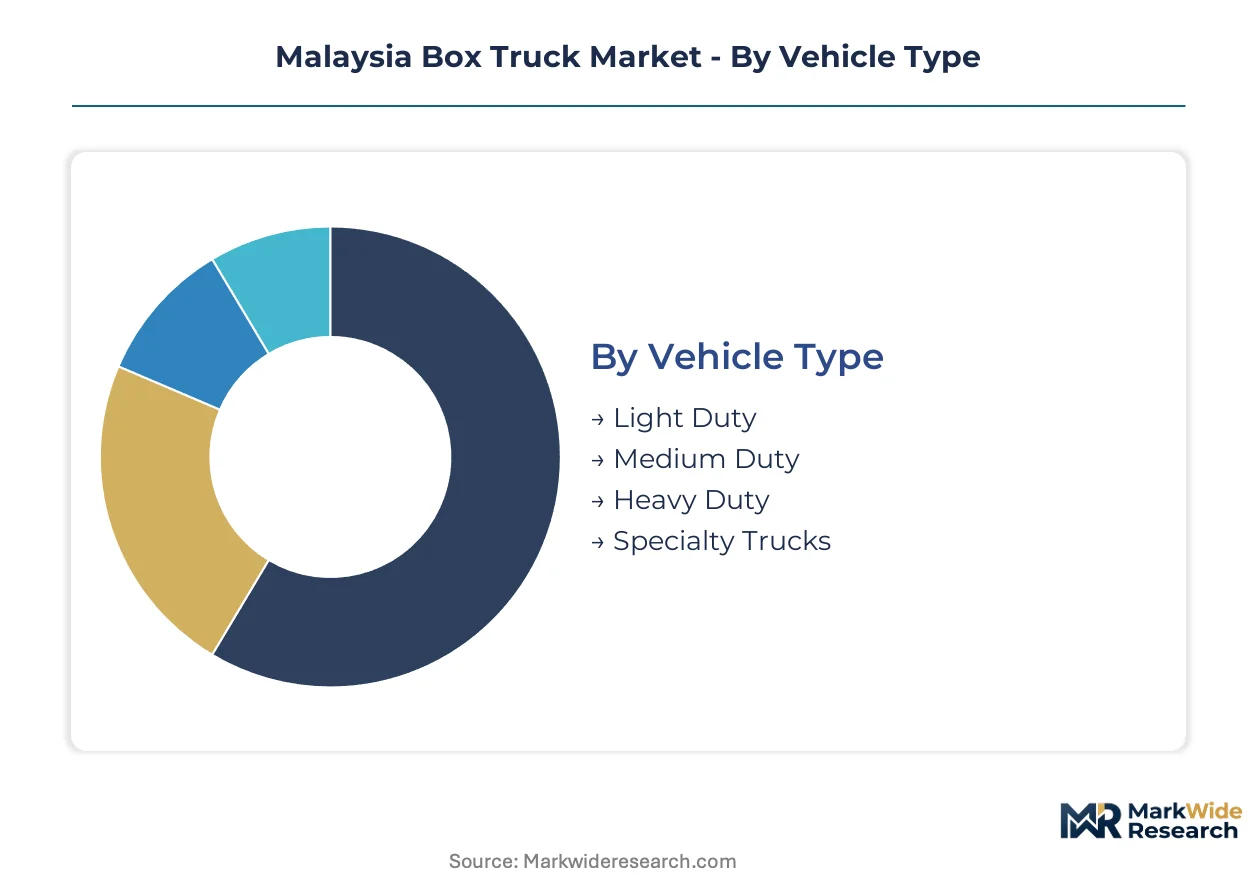
Box truck segmentation in Malaysia reflects divergent service intensity requirements across fleet categories. Light duty vehicles demand rapid-turnaround maintenance networks for urban e-commerce density, while heavy duty configurations require specialized diagnostic capabilities and extended warranty structures.
Vehicle Type:
After-sales-service intensity varies dramatically across weight classes, with medium duty configurations requiring the most complex parts logistics due to their cross-application deployment.
- Light Duty:Rigid chassis designs with gross vehicle weights below 7.5 tonnes dominate Selangor's Klang Valley last-mile corridors. E-commerce fulfillment centers in Shah Alam and Petaling Jaya specify these units for multi-drop parcel density where maneuverability trumps payload.
- Medium Duty:Versatile ladder-frame platforms spanning 7.5 to 16 tonnes gross vehicle weight carry the strongest margin pools. Food transport operators in Johor's Iskandar Malaysia zone favor this class for refrigerated body integration flexibility.
- Heavy Duty:Configurations exceeding 16 tonnes serve construction material haulage and palm oil kernel transport.
- Specialty Trucks:Custom body applications include mobile workshops and hazmat containment for industrial estates.
By volume, Light Duty leads. By growth pace, Medium Duty is expanding most quickly.
Payload Capacity:
Cost tier stratification separates premium fleet specifications from price-sensitive owner-operator purchases, with financing availability tightening at higher tonnage thresholds.
- Below 2 Tons:Compact urban delivery vehicles with unibody or light ladder-frame construction serve neighborhood parcel networks. Penang Island's congested Georgetown district generates concentrated demand for sub-2-tonne maneuverability where parking constraints dominate routing decisions.
- 2-5 Tons:Standard palletized freight capacity aligns with retail distribution center specifications. Cold-chain food distributors in Kuala Lumpur's wholesale markets specify this bracket for refrigerated body upfitting compatibility.
- 5-10 Tons:Mid-range capacity serves regional haulage and construction material delivery.
- Above 10 Tons:Maximum payload configurations for bulk commodity transport and heavy equipment logistics.
By volume, 2-5 Tons leads. By growth pace, Below 2 Tons is gaining share fastest.
Fuel Type:
Application-driven procurement patterns separate long-haul diesel dependence from emerging urban electrification mandates, with total cost of ownership calculations shifting as charging infrastructure deploys.
- Diesel:Compression-ignition engines with after-treatment systems dominate inter-urban freight corridors. Euro 5 compliance costs are compressing operational windows for aging fleet populations across North-South Expressway-linked distribution networks.
- Electric:Battery-electric powertrains with 150-300 kilometer range specifications attract trial orders from PLI scheme beneficiaries. Fleet operators along the North-South Expressway corridor are piloting depot-charged units for fixed-route warehouse distribution.
- Petrol:Spark-ignition engines for light duty urban applications with lower utilization intensity.
- CNG:Compressed natural gas conversions for cost-sensitive regional operators with refueling infrastructure access.
By volume, Diesel leads. By growth pace, Electric shows the steepest expansion trajectory.
Application:
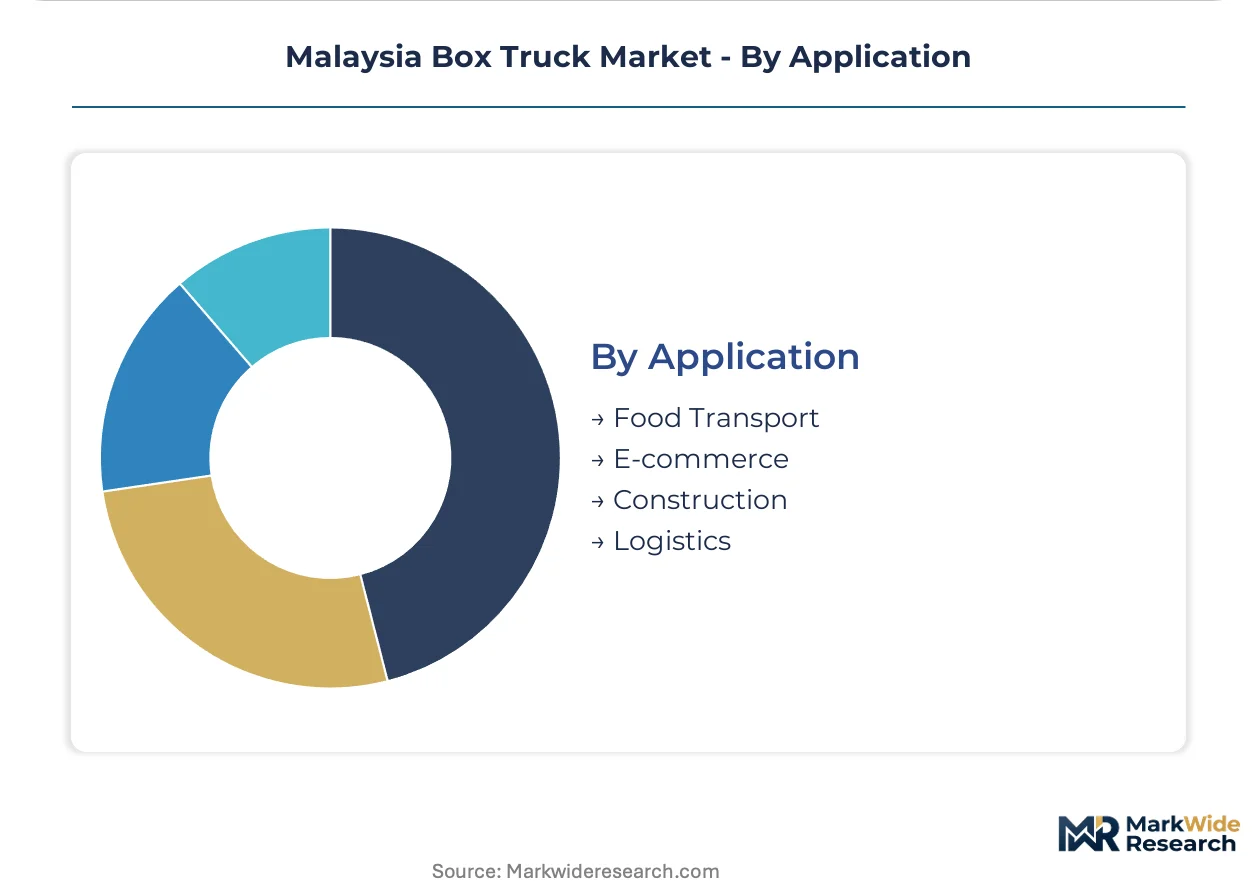
Customer type concentration drives specification divergence, with third-party logistics operators consolidating around uptime-guaranteed service frameworks while owner-operators prioritize acquisition cost minimization.
- E-commerce:Weather-protected cargo bodies with multi-drop interior configurations serve fulfillment center-to-locker distribution. Third-party logistics operators in Selangor's Cyberjaya logistics park are consolidating vendor relationships around single-source frameworks with national service coverage.
- Food Transport:Insulated and refrigerated body integration addresses fresh produce and frozen distribution requirements. Cold-chain convergence in Johor's Senai airport-linked zones drives specification upgrades for seafood and pharmaceutical temperature integrity.
- Construction:Reinforced flooring and side-panel protection for aggregate and equipment haulage.
- Logistics:General freight forwarding and contract distribution serving manufacturing supply chains.
By volume, Logistics leads. By growth pace, E-commerce is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet buyers in Peninsular Malaysia's port-linked corridors show low price elasticity due to uptime-dependent contracts, while East Malaysian operators remain highly sensitive to capital outlay given financing constraints and infrastructure gaps.
Selangor
Electronics export processing and e-commerce fulfillment centers drive concentrated demand for light-duty urban delivery specifications. The Road Transport Department enforces commercial vehicle fitness certification under the Motor Vehicles Act, tightening operational compliance. Shah Alam and Petaling Jaya warehouse clusters are consolidating vendor relationships around single-source service frameworks with national coverage guarantees.
Johor
Palm oil kernel transport and cross-border Singapore-linked logistics sustain medium-duty fleet rotations. The Department of Environment administers emission thresholds tightening toward Euro 5 implementation for new registrations. Iskandar Malaysia's Senai airport-linked zones are driving cold-chain specification upgrades for seafood and pharmaceutical temperature integrity.
Penang
Semiconductor manufacturing supply chains generate just-in-time freight demand requiring high-availability vehicle specifications. BIS-aligned vehicle safety standards govern braking performance and occupant protection, creating compliance barriers for non-conforming imports. Georgetown's congested urban core is generating concentrated demand for sub-2-tonne maneuverability where parking constraints dominate routing decisions.
Sarawak
Timber processing and agricultural commodity haulage sustain heavy-duty applications with lower service intensity requirements. The Ministry of Investment, Trade and Industry coordinates PLI scheme incentives for local assembly of electric commercial vehicles, though charging infrastructure remains sparse. Kuching and Sibu distribution networks are undersupplied with modern box truck specifications, offering first-mover positioning for established Peninsular brands.
Sabah
Palm oil plantation logistics and regional inter-island freight create dispersed demand patterns favoring durable, low-maintenance configurations. Euro 5 pre-buy acceleration is compressing replacement cycles ahead of implementation deadlines. Kota Kinabalu's port-linked corridors are seeing trial orders for depot-charged electric units as charging infrastructure deploys along limited highway segments.
Malaysia Box Truck Market Competitive Environment
Capability concentration sits with Japanese and European original equipment manufacturers; scale advantage sits with Indian and emerging Asian challengers targeting price-sensitive fleet segments. The market structures around three tiers: premium OEMs with captive financing and service networks, mid-market assemblers with local body-building partnerships, and value-positioned importers competing on acquisition cost. Strategic moves center on backward integration into powertrain refurbishment capabilities and exclusive distribution agreements locking out rival parts suppliers.
Among Japanese manufacturers, Isuzu Motors Ltd. and Hino Motors Ltd. exemplify the premium-tier archetype through established dealer infrastructure and recurring maintenance revenue capture. Tata Motors Limited occupies a distinct position as a value-oriented challenger competing on total cost of ownership calculations for price-sensitive logistics buyers in Peninsular Malaysia. These three anchors illustrate the market's fundamental segmentation between uptime-guaranteed service frameworks and capital-minimization procurement strategies.
| Leading Market Players |
|---|
| Isuzu Motors Ltd. |
| Hino Motors Ltd. |
| Tata Motors Limited |
| Mitsubishi Fuso Truck and Bus Corporation |
| UD Trucks Corp. |
| Traton Group |
| EMAC Power Ltd. |
| Swift Haulage Berhad |
| A-Plus Manufacturing Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Shah Alam's chassis assembly clusters concentrate fabrication capacity for Peninsular Malaysia's logistics corridors, translating manufacturing density into pricing leverage for authorized dealer networks against independent body builders. OEM-controlled parts distribution tightens margin capture from aftermarket service revenue, while steel and aluminum commodity volatility feeds through to ladder-frame chassis quotations within quarterly contract windows.
Pricing Analysis
After-sales service contracts drive lifetime value differentiation across fleet operator relationships. Three-tier pricing structure across premium, standard, and economy levels separates Isuzu and Hino's uptime-guaranteed frameworks from Tata's total cost of ownership positioning. Cost compression in medium-duty configurations intensifies because Euro 5 after-treatment system integration raises manufacturing outlays. Owner-operators in East Malaysia show highest price sensitivity, while Selangor's third-party logistics buyers prioritize service coverage over acquisition cost.
Supply Chain Analysis
Tariff exposure between Japan and Malaysia shapes powertrain component landed costs for diesel engine assemblies. Supply draws from Thailand, Indonesia, and Japan for transmission and axle subsystems. Steel coil and aluminum sheet dependencies from regional mills feed ladder-frame chassis fabrication. Single-source vulnerability concentrates in electronic control module sourcing for Euro 5 compliance. Distribution runs through OEM-authorized dealer networks with captive parts warehousing, displacing independent distributors in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics platform interoperability is reconfiguring procurement criteria as large logistics buyers mandate onboard diagnostics as contract preconditions, collapsing service revenue toward OEM-controlled data architectures.
For Market Incumbents: Pre-empt connectivity platform consolidation by bundling predictive maintenance subscriptions with vehicle financing, locking out third-party telematics providers from fleet operator relationships. Deepen backward integration into engine refurbishment capabilities to capture Euro 5 service revenue as certified technician scarcity widens margin pools for in-house technical training programs. For New Entrants and Emerging Players: Pursue Sarawak and Sabah's undersupplied road freight networks where modern box truck specifications remain sparse and established dealer infrastructure is thin. Target cold-chain food transport applications in Johor's Senai airport-linked zones for insulated body integration partnerships with regional refrigeration equipment installers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with captive financing arms and national service coverage guarantees, positioning these archetypes for sustained cash flow quality across fleet replacement cycles. Acquisition targets should demonstrate telematics platform integration capabilities or exclusive distribution agreements locking out rival parts suppliers. Watch for PLI scheme beneficiary announcements as inflection indicators for electric commercial vehicle assembly scale-up timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Refurbishment | Captures Euro 5 service revenue as technician scarcity widens margin pools for in-house capabilities. |
| Telematics Platform Bundling | Locks fleet operators into OEM-controlled data architectures, displacing third-party connectivity providers. |
| East Malaysia Distribution Expansion | Establishes first-mover positioning in Sarawak and Sabah's undersupplied road freight corridors. |
| Cold-Chain Body Integration Partnerships | Addresses Johor's Senai airport-linked seafood and pharmaceutical temperature integrity requirements. |
| PLI Scheme Electric Assembly Qualification | Secures production-linked subsidies for local battery-electric commercial vehicle manufacturing scale-up. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade records, Road Transport Department vehicle registration databases, and Ministry of Investment, Trade and Industry incentive disclosures. Interviews with fleet operations managers, OEM dealer principals, aftermarket service heads, and cold-chain logistics coordinators informed demand-side validation. Bottom-up unit shipment estimates triangulate against top-down GDP-linked freight intensity models.
Forecast inputs span vehicle type, payload capacity, fuel type, and application segmentation across the projection horizon. CAGRs derive from logistic diffusion curves fitted to electrification trial order trajectories and Euro 5 pre-buy acceleration patterns. Modeled variables include charging infrastructure deployment pace along the North-South Expressway corridor and PLI scheme beneficiary qualification timelines.
Sensitivities concentrate around Euro 5 implementation enforcement consistency, steel commodity price volatility, and electric vehicle subsidy continuity. Forecasts reflect assumptions on fleet replacement cycle compression and telematics adoption penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Europe LCV Rental Market