
 Refrigerated Trailer Door Lock Market | 2026-2036
Refrigerated Trailer Door Lock Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Trailer Door Lock Market Analytics
Food distributor fleet procurement is restructuring around tamper-evident security protocols, pulling refrigerated trailer door locks into broader cold chain compliance budgets. Master Lock Company leverages its commercial distribution network to sustain institutional channel dominance across North American grocery logistics. STRATTEC Security anchors automotive-grade lock engineering into heavy-duty trailer applications, while PACLOCK specializes in keyed-alike systems that reduce fleet key management complexity for multi-unit operators.
A refrigerated trailer door lock is a mechanical or electromechanical security device engineered to seal cargo access points on temperature-controlled transport units, typically constructed from hardened stainless steel or aluminum alloys with corrosion-resistant finishes rated for thermal cycling between minus twenty and plus fifty degrees Celsius. Electronic lock variants integrate RFID credentialing, GPS tracking, and remote audit logging to satisfy pharmaceutical and fresh-produce chain-of-custody requirements. Deadbolt lock configurations retain the largest installed base due to proven mechanical reliability in extreme weather, though electronic lock demand is accelerating fastest as cold chain providers adopt outcome-based fleet management platforms. Aftermarket installation channels capture significant volume from owner-operator retrofit cycles, while factory-installed positions tighten through OEM-preferred supplier agreements with trailer manufacturers.
The US FDA Food Safety Modernization Act mandates sanitary transportation practices that elevate lock integrity to enforceable compliance scope, while the EPA refrigerant management framework indirectly pressures fleet operators to minimize door seal failures that compromise temperature control. ISO 17712 high-security seal standards and the EU's incoming digital product passport requirements for transport equipment are reshaping product development roadmaps across manufacturers. Stakeholders must weigh mechanical durability against connected security investments as regulatory audit granularity tightens across pharmaceutical and perishable cargo lanes.
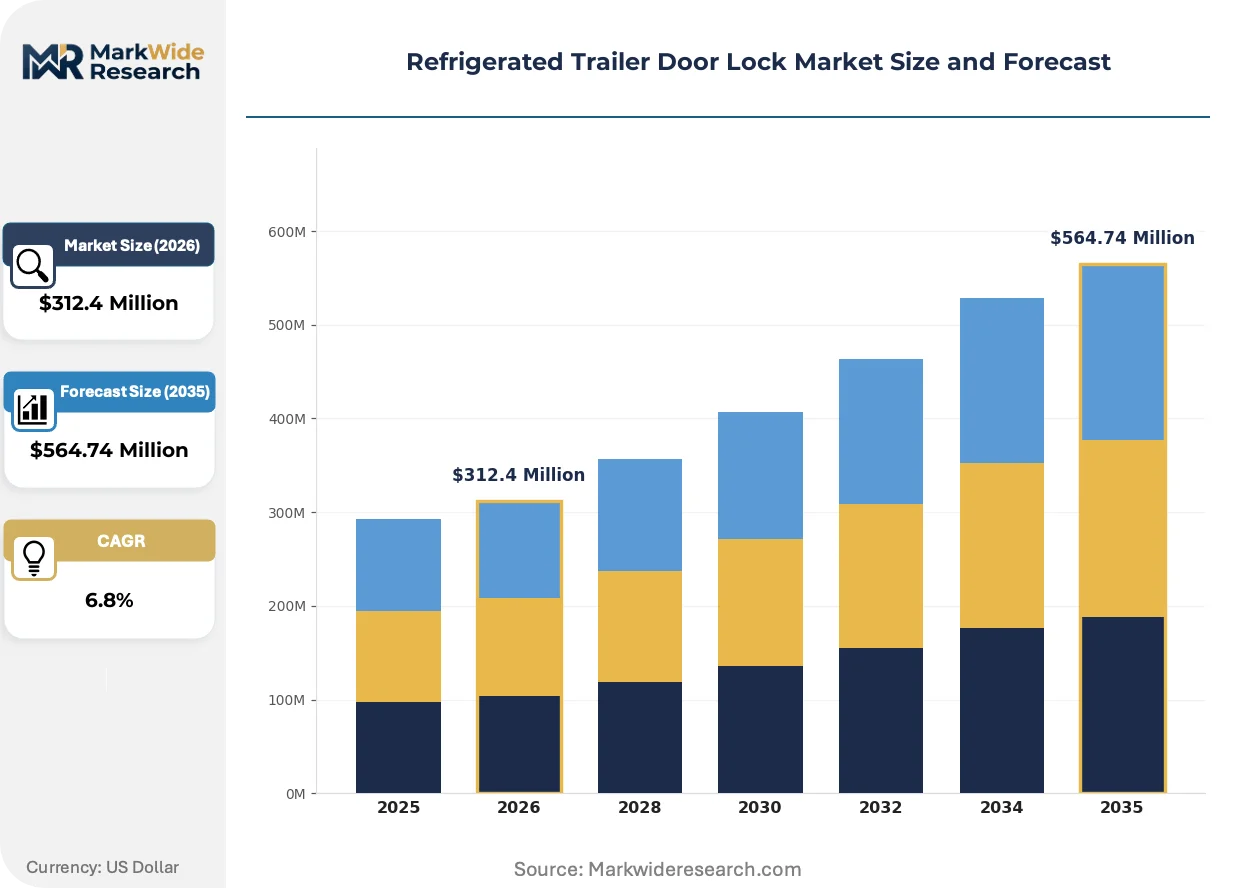
Market Dynamics
The refrigerated trailer door lock market pivots on the collision between mechanical reliability demands and the regulatory push for auditable cargo security, as fleet operators face simultaneous pressure from FDA traceability mandates and insurance carriers demanding remote monitoring capabilities.
Growth Catalysts
- Food Safety Modernization Act enforcement:The FDA's sanitary transportation rules now explicitly cover seal integrity, forcing cold chain logistics providers to upgrade from passive mechanical locks to tamper-evident systems with documented chain-of-custody capabilities.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is accelerating adoption of electronic locks with integrated temperature logging across North American and European lanes handling gene therapies and vaccines.
- Stainless steel corrosion resistance:Hardened 316-grade alloys rated for thermal cycling between -20°C and +50°C are extending service intervals in coastal and de-icing salt environments, reducing fleet maintenance downtime.
Market Restraints
- Electronic lock cost premiums:RFID-credentialing and GPS-enabled units carry three-to-four-fold hardware cost multiples versus deadbolt configurations, compressing adoption among owner-operators with sub-ten-unit fleets.
- Semiconductor supply concentration:GPS and cellular connectivity modules depend on concentrated Asian foundry capacity, exposing lead times to geopolitical friction and export control volatility.
- Mechanical reliability bias:Extreme weather performance data favors deadbolt architectures in field conditions, creating adoption resistance among risk-averse fleet maintenance directors.
Strategic Opportunities
- EU digital product passport mandate:Incoming transport equipment traceability requirements will favor lock manufacturers with embedded RFID and blockchain-ready audit architectures.
- Key management complexity reduction:Keyed-alike and master-keyed fleet systems remain underpenetrated among mid-size regional distributors, creating channel expansion potential for specialized providers.
- Retrofit aftermarket cycles:Owner-operator equipment refresh patterns, typically triggered by DOT inspection failures, present recurring installation revenue streams independent of OEM trailer production cycles.
Industry Challenges
- Electromechanical integration complexity:Electronic lock deployment requires coordination between fleet telematics platforms, third-party logistics software, and maintenance management systems, stretching IT capabilities at mid-market operators.
- ISO 17712 certification timelines:High-security seal compliance testing and customs-recognized laboratory validation create six-to-nine-month product development delays for new mechanical lock configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Trailer Door Lock Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deadbolt Lock, Padlock, Cylinder Lock, Electronic Lock End User: Logistics Companies, Food Distributors, Grocery Retailers, Cold Chain Providers Installation Type: Factory-installed, Aftermarket, DIY, Custom Installations Material: Stainless Steel, Aluminum, Plastic, Carbon Steel |
| Companies Covered | Destata Transport, Master Lock Company, Trimax Locks, Bolt Lock, Pacific Lock, Bulldog Security Products, PACLOCK, STRATTEC Security, Eagle Locks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Trailer Door Lock Market Evolving Landscape
Connected security architectures are reconfiguring competitive advantage around data ownership rather than physical hardware durability, as fleet operators prioritize outcome-based cargo protection over capital equipment specifications.
Bluetooth Low Energy credentialing is decentralizing access control authority from centralized dispatch offices to individual drivers and facility gate personnel. Pharmaceutical distributors and fresh-produce wholesalers are piloting smartphone-based unlock protocols that eliminate physical key inventory. This shift is decentralizing procurement influence from fleet maintenance departments toward IT and compliance officers who control telematics platform selection.
REACH substance restrictions and the EU F-Gas Regulation are indirectly elevating lock seal performance standards by tightening penalties for temperature excursions that trace to door seal failures. Trailer manufacturers serving European lanes now specify corrosion-resistant finishes and thermal expansion-tolerant alloys in factory-installed positions. Cold chain providers operating cross-border pharmaceutical routes are prioritizing suppliers with EU-type examination certificates.
Fleet procurement departments are consolidating vendor relationships around integrated security-telemetics bundles rather than standalone hardware purchases. Third-party logistics providers managing multi-shipper networks are displacing piecemeal lock procurement with platform subscriptions that include hardware, software, and monitoring services. This consolidation is most visible among refrigerated carriers operating dedicated lanes between Chicago, Dallas, and Los Angeles distribution hubs.
Refrigerated Trailer Door Lock Market Segmentation
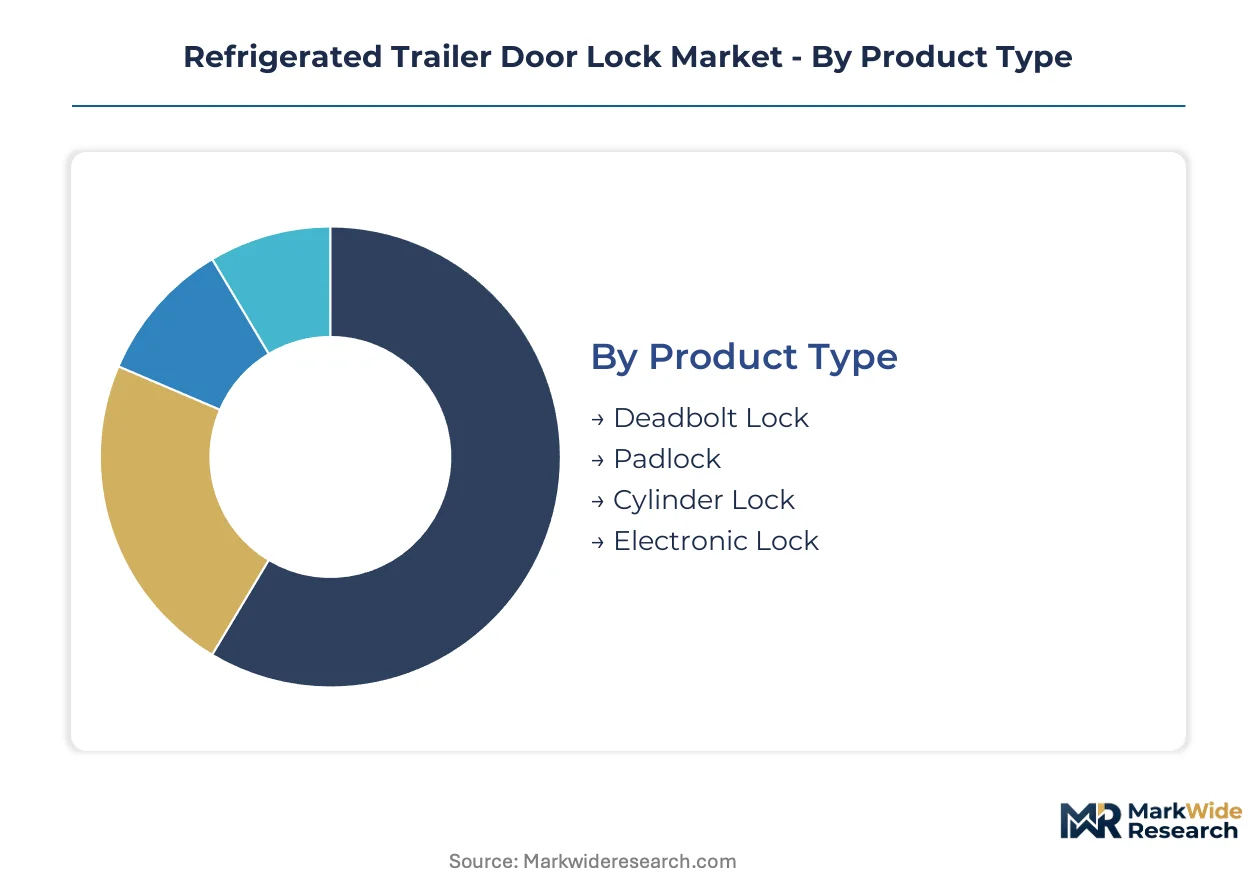
Fleet procurement decisions in the refrigerated trailer door lock market hinge on upgrade cycles triggered by regulatory compliance deadlines, OEM trailer replacement waves, and retrofit installations following DOT inspection failures. Understanding how these replacement patterns distribute across product configurations, end-user categories, and installation channels clarifies where manufacturers must align R&D investment with actual purchasing behavior.
Product Type:
Upgrade cycles vary dramatically by lock architecture, with mechanical systems following predictable wear-based replacement schedules while electronic units trigger refresh decisions through telematics platform migrations and cybersecurity protocol updates.
- Deadbolt Lock:Hardened steel deadbolts with tamper-evident hasps dominate fleet retrofit specifications due to proven performance in thermal cycling between -20°C and +50°C. Food distributors operating Interstate highway corridors from Chicago to Los Angeles specify deadbolt configurations for their reliability in extreme weather where electronic systems risk battery failure.
- Electronic Lock:RFID-credentialing and GPS-enabled units integrate temperature logging with access audit trails, satisfying pharmaceutical cold chain mandates from the FDA and EMA. Cold chain providers handling gene therapies across North American distribution hubs are consolidating procurement around electronic systems despite three-to-four-fold hardware cost premiums.
- Padlock:Shackle-style padlocks with hardened boron alloy construction serve owner-operator fleets seeking portable security solutions for mixed trailer pools.
- Cylinder Lock:Pin-tumbler mechanisms with master-keyed configurations reduce key management complexity for regional distributors operating fifty-to-two-hundred-unit fleets.
Deadbolt lock configurations sit at the top of the volume ranking, with electronic lock demand climbing the fastest as FDA traceability mandates tighten across pharmaceutical and fresh-produce lanes.
End User:
Procurement authority concentrates differently across customer types, with enterprise fleets centralizing purchasing through telematics platform decisions while independent operators respond to spot compliance failures.
- Logistics Companies:Third-party logistics providers managing multi-shipper networks are displacing standalone hardware purchases with integrated security-telematics subscriptions. These operators prioritize outcome-based cargo protection over capital equipment specifications, consolidating vendor relationships around platform bundles.
- Cold Chain Providers:Temperature-controlled logistics specialists face the strictest regulatory audit granularity from the FDA Food Safety Modernization Act and EU digital product passport requirements. Their procurement teams specify corrosion-resistant 316-grade stainless steel finishes and embedded RFID architectures for cross-border pharmaceutical routes.
- Food Distributors:Grocery logistics operators anchor institutional channel demand through Master Lock Company's commercial distribution network, prioritizing keyed-alike fleet systems.
- Grocery Retailers:Private fleet operators at major retail chains specify factory-installed positions through OEM-preferred supplier agreements with trailer manufacturers.
Logistics companies command the largest procurement volume, with cold chain providers expanding their share most quickly as biologics distribution accelerates.
Installation Type:
Channel structure determines margin capture and customer relationship durability, with factory-installed positions locking in multi-year OEM supply agreements while aftermarket channels serve fragmented retrofit demand.
- Factory-installed:Trailer manufacturers serving European lanes now specify corrosion-resistant finishes and thermal expansion-tolerant alloys in original equipment positions, tightening supplier relationships through EU-type examination certificate requirements.
- Aftermarket:Owner-operator equipment refresh patterns triggered by DOT inspection failures present recurring installation revenue streams independent of OEM trailer production cycles. This channel captures significant volume from retrofit cycles in the Interstate highway network connecting Dallas and Los Angeles distribution hubs.
- DIY:Independent owner-operators with sub-ten-unit fleets purchase through commercial hardware distributors, prioritizing mechanical reliability over connected features.
- Custom Installations:Specialized integrators configure hybrid mechanical-electronic systems for pharmaceutical carriers requiring redundant security architectures.
Factory-installed positions dominate new trailer procurement, with aftermarket installations gaining share fastest among regional distributors extending fleet lifecycles.
Material:
Material selection tradeoffs between corrosion resistance, thermal expansion tolerance, and unit economics shape specification patterns across coastal, inland, and extreme climate operating environments.
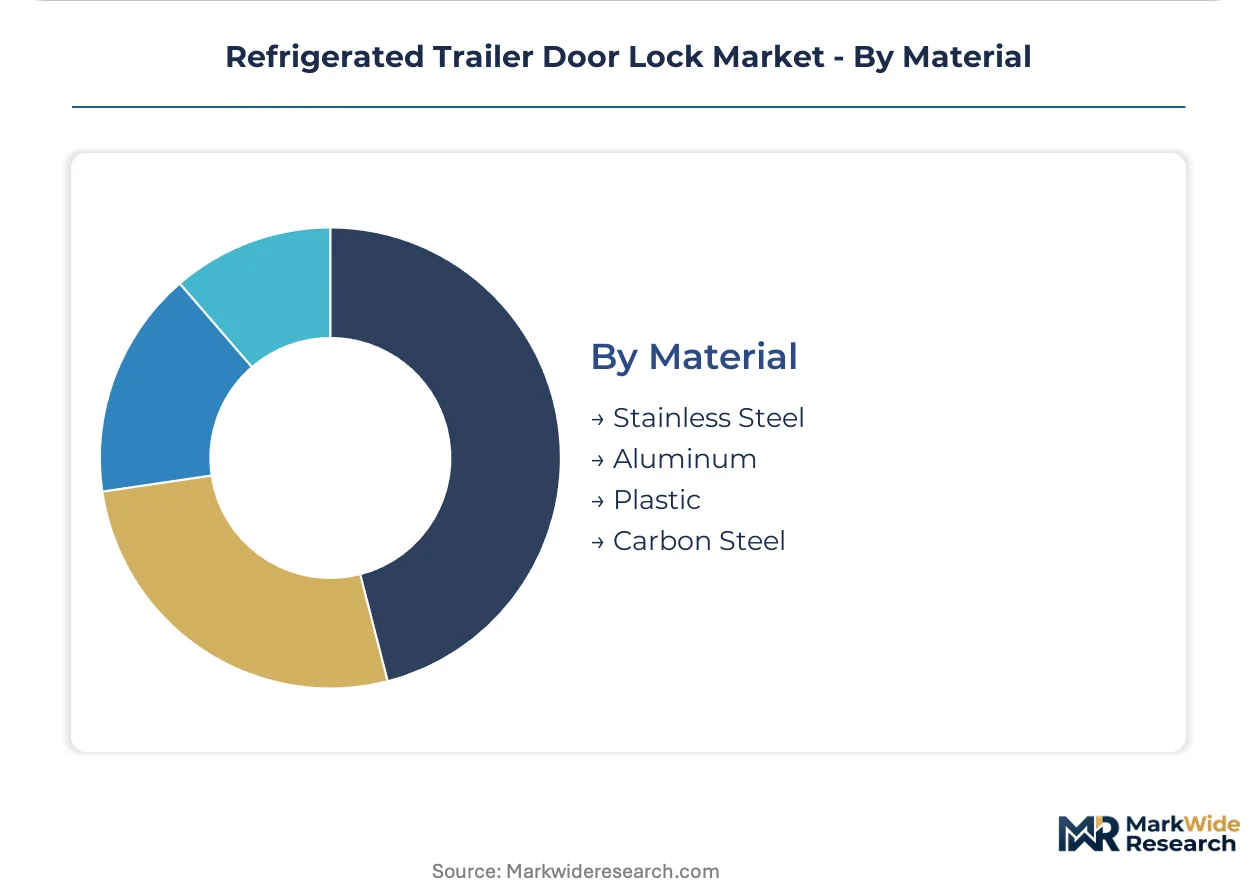
- Stainless Steel:316-grade alloys rated for thermal cycling extend service intervals in coastal and de-icing salt environments, reducing fleet maintenance downtime. Cold chain providers specify hardened stainless steel for FDA-compliant sanitary transportation practices.
- Aluminum:Lightweight alloys with anodized finishes serve weight-sensitive refrigerated trailers where payload optimization drives fuel efficiency calculations.
- Plastic:Glass-reinforced polymer housings reduce galvanic corrosion in mixed-metal trailer assemblies for short-haul distribution.
- Carbon Steel:Zinc-plated carbon steel configurations serve price-sensitive owner-operators in inland climates with minimal salt exposure.
Stainless steel commands the highest volume specification, with aluminum alloys expanding most quickly as fleet operators prioritize weight reduction for fuel economy compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting refrigerated trailer door lock procurement toward markets with harmonized cold chain standards. Manufacturers relocate final assembly to minimize dual-certification burdens while fleet operators concentrate investments in corridors with unified FDA-EMA traceability protocols.
United States
Pharmaceutical distribution hubs in Chicago, Dallas, and Los Angeles drive specification demand for electronic locks with integrated temperature logging. FDA Food Safety Modernization Act enforcement mandates tamper-evident seals with documented chain-of-custody capabilities across Interstate highway corridors. Cold chain providers in these distribution clusters are consolidating procurement around RFID-credentialing systems despite hardware cost premiums.
Germany
EU digital product passport requirements for transport equipment are accelerating embedded RFID and blockchain-ready audit architectures among lock manufacturers. ECHA REACH substance restrictions elevate corrosion-resistant finish specifications for cross-border pharmaceutical routes serving the Rhine-Ruhr industrial zone. Trailer manufacturers in Baden-Württemberg now specify thermal expansion-tolerant alloys in factory-installed positions.
China
Domestic cold chain infrastructure expansion supports demand for mechanical deadbolt configurations in temperature-controlled logistics serving the Yangtze River Delta. NMPA pharmaceutical distribution regulations are tightening traceability requirements for biologics transport between Shanghai and Beijing-Tianjin-Hebei clusters. Local manufacturers concentrate production in Zhejiang and Jiangsu provinces for cost-competitive export positioning.
Netherlands
Rotterdam port logistics and Amsterdam-Schiphol pharmaceutical air freight corridors prioritize ISO 17712 high-security seal compliance for cross-border EU lanes. The country's central distribution geography positions it as a specification gatekeeper for REACH-compliant finishes entering broader European markets. Fleet operators in the Randstad region are piloting Bluetooth Low Energy credentialing systems for multi-shipper networks.
India
Cold chain infrastructure gaps in pharmaceutical distribution are driving aftermarket retrofit demand for mechanical padlock configurations among owner-operators. FSSAI sanitary transportation guidelines are elevating fleet security investments in the Maharashtra-Gujarat pharmaceutical manufacturing corridor. Regional distributors in Delhi-NCR and Bangalore are adopting keyed-alike systems to reduce key management complexity.
Refrigerated Trailer Door Lock Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional channel dominance concentrating among legacy security brands while OEM-preferred supplier agreements tighten factory-installed positions. The market structure tiers around three strategic archetypes: diversified lock manufacturers with commercial distribution networks, automotive-grade security engineering specialists, and keyed-alike fleet system providers. Competitive moves center on telematics platform integration partnerships and corrosion-resistant material certifications for extreme climate performance.
Among North American branded specialists, Master Lock Company and STRATTEC Security exemplify divergent positioning archetypes. Master Lock Company anchors institutional channel presence through commercial distribution networks serving grocery logistics procurement. STRATTEC Security occupies a position translating automotive-grade lock engineering into heavy-duty trailer applications. PACLOCK represents the keyed-alike specialization vector, targeting mid-size regional distributors with fleet key management simplification. These three companies illustrate how competitive advantage fragments across channel access, engineering heritage, and operational complexity reduction rather than concentrating in scale-driven consolidation.
| Leading Market Players |
|---|
| Destata Transport |
| Master Lock Company |
| Trimax Locks |
| Bolt Lock |
| Pacific Lock |
| Bulldog Security Products |
| PACLOCK |
| STRATTEC Security |
| Eagle Locks |
| Others |
Value Network & Pricing Analysis
Captive in-house production of hardened 316-grade stainless steel components anchors both supply security and pricing power for tier-one manufacturers serving pharmaceutical cold chain mandates. This backward integration into corrosion-resistant alloy processing insulates producers from spot price volatility in specialty steel markets while enabling premium positioning for FDA-compliant sanitary transportation applications.
Pricing Analysis
Distributor margin layering separates factory-direct OEM pricing from aftermarket channel markups, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and volume scale differentiation. Electronic lock configurations with RFID-credentialing and GPS modules command hardware cost multiples over deadbolt units due to semiconductor content and telematics platform integration. Cost compression in entry-tier mechanical configurations is intensifying because of Asian contract manufacturer competition. Owner-operators with sub-ten-unit fleets exhibit highest price sensitivity, while enterprise cold chain providers prioritize outcome-based cargo protection over unit economics.
Supply Chain Analysis
Domestic-content mandates in the US Buy American Act and EU procurement directives are reshaping sourcing patterns for government-contracted pharmaceutical distribution fleets. Manufacturing concentrates in China, Taiwan, and Germany for electronic lock modules, with Zhejiang and Jiangsu provinces hosting cost-competitive mechanical lock production. Hardened steel alloys, RFID chips, and GPS-cellular connectivity modules constitute critical input dependencies. Single-source vulnerability in Asian foundry capacity for semiconductor components exposes lead time risk. Distribution runs through commercial hardware distributors serving aftermarket retrofit demand and OEM-preferred supplier agreements capturing factory-installed positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through premium-tier electronic lock adoption as FDA traceability mandates displace commodity mechanical configurations. Cost-down drivers in Bluetooth Low Energy credentialing and smartphone-based access protocols reduce hardware complexity while maintaining audit compliance.
For Market Incumbents: Deepen telematics platform integration partnerships to lock in switching costs as fleet operators consolidate vendor relationships around bundled security-monitoring subscriptions. Invest in EU-type examination certificates and REACH-compliant finish certifications to defend factory-installed positions against emerging Asian competitors. Prioritize corrosion-resistant 316-grade alloy captive supply to maintain margin advantage in coastal and de-icing salt environments.
For New Entrants and Emerging Players: Regional distributors operating fifty-to-two-hundred-unit fleets represent an underserved buyer archetype with unmet key management complexity reduction needs. Target mid-size cold chain providers in the Interstate highway network connecting Dallas and Los Angeles distribution hubs with keyed-alike fleet systems. Pursue aftermarket installation partnerships with DOT inspection service centers to capture recurring retrofit revenue independent of OEM trailer production cycles.
For Investors and Strategic Acquirers: Roll-up economics work for specialized keyed-alike fleet system providers because customer switching costs in multi-unit key management create sticky recurring revenue streams. Platform consolidation opportunities concentrate among telematics-integrated electronic lock vendors with pharmaceutical cold chain credentials. Watch FDA enforcement action on sanitary transportation practices as the inflection indicator for accelerated electronic lock replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Bundles hardware, software, and monitoring services into sticky subscription relationships with cold chain providers. |
| EU-Type Examination Certification | Unlocks factory-installed positions with trailer manufacturers serving REACH-regulated pharmaceutical routes. |
| Bluetooth Low Energy Credentialing | Decentralizes access control to smartphone-based protocols, reducing physical key inventory for fleet operators. |
| Corrosion-Resistant Alloy Investment | Extends service intervals in coastal and de-icing salt environments, reducing fleet maintenance downtime. |
| Aftermarket Channel Expansion | Captures DOT inspection-triggered retrofit demand independent of OEM trailer production volatility. |
Research Methodology
Direct dialogue with fleet maintenance directors, cold chain compliance officers, trailer manufacturer procurement teams, and aftermarket installation service providers grounded qualitative findings. Secondary validation drew from FDA enforcement records, EPA refrigerant management filings, ISO 17712 certification databases, and customs trade data for hardened steel alloy imports. Bottom-up unit economics triangulated against top-down cold chain fleet investment surveys to establish market sizing.
Bottom-up modeling of replacement cycles across mechanical and electronic lock configurations, segmented by fleet size tier, installation channel, and end-user category, structured the analytical framework. The projection horizon incorporates regulatory compliance deadlines, OEM trailer replacement waves, and retrofit installation patterns triggered by DOT inspections. CAGRs derived from logistic curve penetration modeling for electronic locks against established mechanical installed base decay. Pharmaceutical cold chain expansion and FDA Food Safety Modernization Act enforcement timelines informed demand elasticity assumptions.
Underlying measurement precision varies by segment; electronic lock adoption rates and pharmaceutical cold chain procurement carry tighter precision than owner-operator aftermarket retrofit patterns. Forecasts reflect assumptions on regulatory enforcement intensity, semiconductor supply availability, and cold chain infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Front Forks Market
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Rail Components Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Collapsible Jerry Can Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
EV Connectors Market
Vehicle Components
Seating and Positioning Belts Market