
 Global Automotive Remote Diagnostics Market | 2026-2036
Global Automotive Remote Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Remote Diagnostics Market Intelligence
German Tier-1 supplier capacity in embedded diagnostic controllers is hardening as OEMs mandate over-the-air update compatibility. Robert Bosch GmbH leverages its powertrain electronics heritage to anchor firmware-level diagnostic integration across European vehicle platforms. Continental AG competes through its Body & Security division, which sustains long-term supply relationships with premium German manufacturers. Denso Corporation dominates Asian OEM programs, where its thermal management expertise extends into battery health monitoring for electrified fleets.
Automotive remote diagnostics encompasses the continuous acquisition, transmission, and analysis of vehicle health data through embedded sensors, telematics control units, and backend cloud infrastructure operating at sub-100-millisecond latency thresholds for critical fault codes. The primary commercial purpose centers on shifting maintenance from reactive breakdown repair to predictive intervention, thereby reducing total cost of ownership for fleet operators and preserving residual value for lessors. Onboard diagnostics and telematics devices together form the hardware backbone where margin pools concentrate due to semiconductor content and calibration complexity. Diagnostic software and cloud platforms represent the fastest-expanding value layer, as recurring SaaS revenue models displace one-time hardware sales and enable tiered feature monetization across fleet size segments.
The European Union's GDPR and Cyber Resilience Act impose stringent data governance and security-by-design obligations on cross-border vehicle data flows, compelling vendors to architect regionally segmented cloud instances. The U.S. NHTSA and EPA jointly shape demand through recall automation mandates and emissions compliance verification that require standardized diagnostic trouble code reporting. Stakeholders must monitor the divergence between EU software liability frameworks and U.S. self-certification approaches, as this regulatory asymmetry threatens to fragment platform development roadmaps and inflate compliance engineering costs for multi-region suppliers.
Market Dynamics
Fleet operators now mandate predictive maintenance architectures that compress vehicle downtime across distributed logistics networks, while the EU Green Deal and escalating emissions enforcement accelerate OEM integration of real-time monitoring systems.
Growth Catalysts
- EU Green Deal mandates:The European Commission's emissions enforcement protocols compel OEMs to deploy continuous diagnostic monitoring for compliance verification and automated recall management.
- Fleet digitization:Logistics operators across Germany and the United States now require sub-100-millisecond latency fault detection to minimize unplanned downtime in electrified vehicle pools.
- Telematics hardware maturation:Semiconductor integration into embedded diagnostic controllers enables over-the-air firmware updates that extend platform lifecycles and reduce physical service visits.
Market Restraints
- GDPR compliance architecture:The European Union's data governance obligations force vendors to deploy regionally segmented cloud instances, inflating infrastructure costs for cross-border vehicle data flows.
- Semiconductor supply concentration:Foundry capacity constraints in Taiwan and South Korea create input bottlenecks for telematics control unit production.
- Cybersecurity-by-design mandates:The EU Cyber Resilience Act imposes stringent security certification timelines that delay platform commercialization by 12-18 months.
Strategic Opportunities
- India fleet electrification:The country's PLI scheme for automotive manufacturing creates demand for battery health monitoring systems in commercial vehicle segments.
- Edge-to-cloud convergence:Integration of onboard diagnostic processing with centralized analytics platforms enables tiered SaaS monetization across fleet size segments.
- US recall automation:NHTSA mandates for standardized diagnostic trouble code reporting create compliance-driven procurement pull from domestic fleet operators.
Industry Challenges
- Embedded systems engineering scarcity:Firmware-level diagnostic calibration requires specialized talent pools concentrated in German and Japanese automotive clusters.
- Multi-region certification complexity:Divergence between EU software liability frameworks and US self-certification approaches fragments platform development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Remote Diagnostics Market |
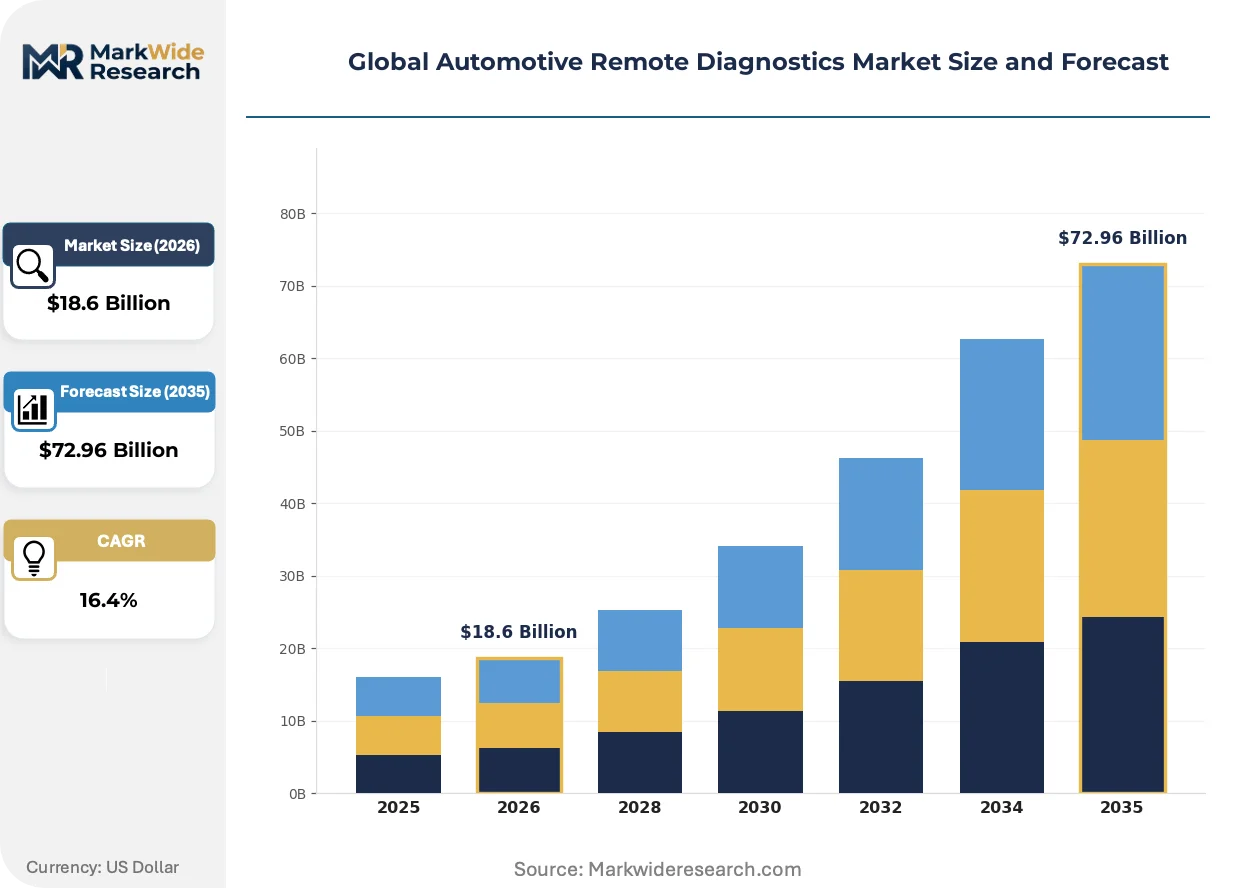
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $72.96 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Diagnostics, Telematics Devices, Diagnostic Software, Cloud Platforms Technology: Bluetooth, Cellular Networks, Wi-Fi, Satellite Communication Application: Fleet Management, Vehicle Maintenance, Warranty Services, Insurance Telematics End User Industry: OEMs, Vehicle Assemblers, Aftermarket Providers, Dealerships |
| Companies Covered | Denso Corporation, Snap-on Incorporated, Robert Bosch GmbH, Vector Informatik GmbH, Octo Group, Continental AG, Verizon Connect, Geotab Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Remote Diagnostics Market Strategic Shifts & Innovations
Diagnostic software architectures are absorbing artificial intelligence inference capabilities at the edge, enabling real-time anomaly detection without cloud dependency. Three developments dominate competitive positioning.
Edge AI inference engines are absorbing computational workloads previously routed to centralized cloud infrastructure. Tier-1 suppliers deploy neural network accelerators within telematics control units to process sensor arrays locally. Fleet operators in Germany and Japan prioritize this capability to reduce latency for critical fault codes while maintaining data sovereignty compliance.
REACH chemical disclosure requirements and the EU AI Act's risk classification framework now govern diagnostic algorithm transparency. Automotive suppliers must document training data provenance and decision logic for predictive maintenance models. Premium German manufacturers face the steepest compliance burden as their vehicle platforms integrate the most sophisticated diagnostic AI layers.
Subscription-based feature activation is displacing perpetual hardware licensing in fleet procurement contracts. Operators in the United States and United Kingdom now demand usage-based diagnostic tiers rather than capital-intensive upfront platform purchases. This compresses vendor cash conversion cycles while expanding addressable market penetration among mid-size logistics providers.
Global Automotive Remote Diagnostics Market Segmentation
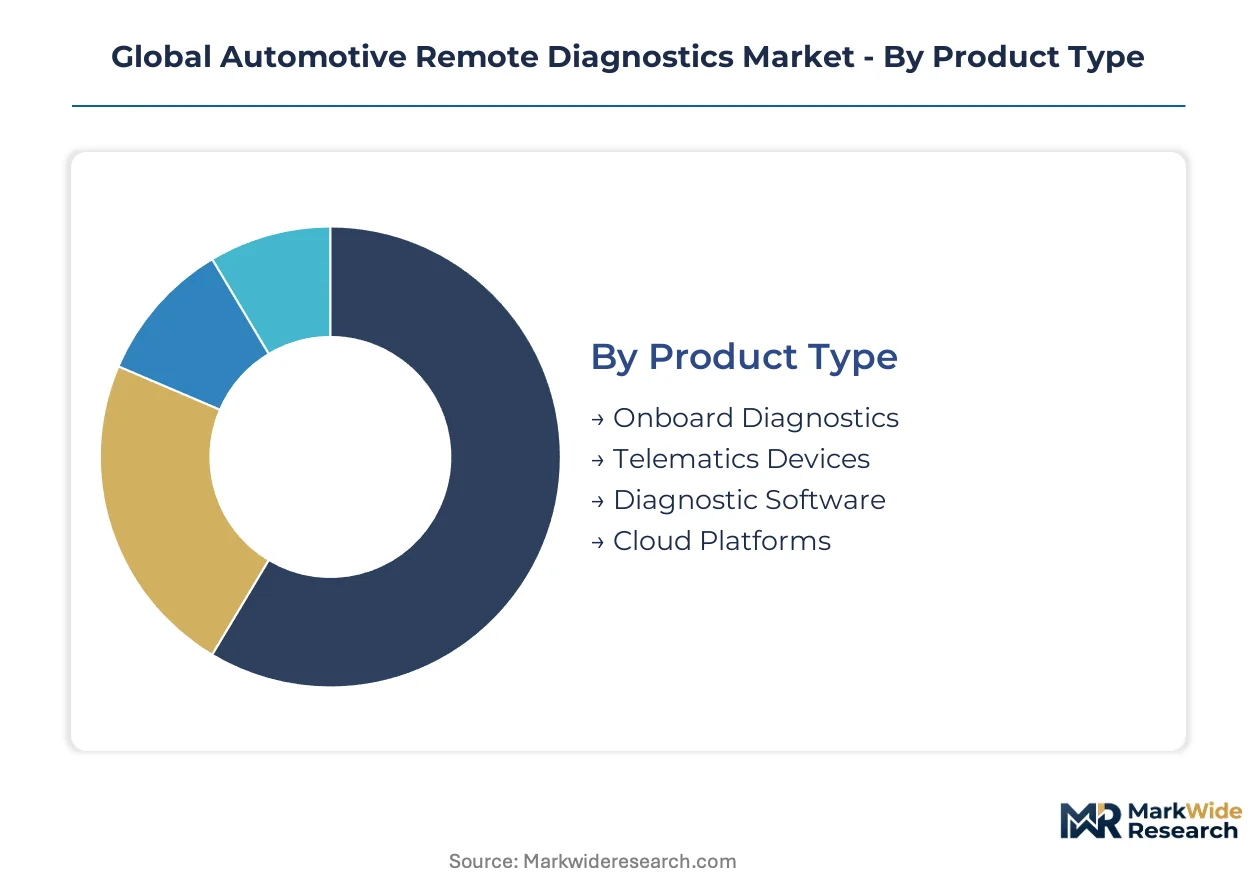
Segmentation in automotive remote diagnostics reveals distinct margin architectures across hardware, connectivity, and software layers. Product type determines capital intensity and recurring revenue potential. Technology choices shape latency performance for critical fault detection. Application focus separates fleet-scale deployments from consumer-facing warranty services.
Product Type:
Integration depth varies sharply — standalone diagnostic hardware serves retrofit markets while embedded firmware layers anchor OEM production programs.
- Onboard Diagnostics:Embedded controller modules process engine and powertrain sensor arrays at the firmware level. German premium manufacturers mandate these units for emissions compliance verification under KBA type-approval protocols.
- Telematics Devices:Hardware units combining GPS, accelerometer, and cellular modem functionality for real-time data transmission. Fleet operators in the United States procure these for sub-100-millisecond latency fault alerting across distributed logistics networks.
- Diagnostic Software:Algorithm layers interpreting fault codes and predicting component degradation. Japanese OEMs integrate these stacks for battery health monitoring in electrified vehicle platforms.
- Cloud Platforms:Backend infrastructure for data aggregation, analytics, and over-the-air update orchestration. EU GDPR requirements force regional instance segmentation, inflating deployment costs for cross-border operators.
Onboard diagnostics leads volumes today; cloud platforms are gaining share fastest.
Technology:
Connectivity protocols stratify by bandwidth requirements and infrastructure dependency — low-power options suit battery-constrained deployments while high-bandwidth channels enable real-time video diagnostics.
- Bluetooth:Short-range protocol for technician proximity diagnostics and smartphone-tethered maintenance apps. Aftermarket providers in India leverage this for cost-sensitive commercial vehicle retrofits under PLI scheme incentives.
- Cellular Networks:4G and 5G modems enabling continuous wide-area connectivity. Fleet management platforms depend on this for uninterrupted data streaming across interstate corridors.
- Wi-Fi:High-bandwidth local connectivity for depot-based bulk data uploads and firmware updates. German logistics hubs deploy this for overnight vehicle pool synchronization.
- Satellite Communication:Coverage for remote and cross-border routes lacking cellular infrastructure. Mining and agricultural fleet operators in Australia and Canada require this for equipment operating beyond terrestrial network reach.
Cellular networks dominate installed base; satellite communication shows steepest expansion trajectory in resource extraction segments.
Application:
Use case economics diverge — operational efficiency applications command SaaS pricing while risk-transfer services monetize per-vehicle-event.
- Fleet Management:Integrated platforms combining tracking, diagnostics, and maintenance scheduling. United Kingdom logistics operators now mandate predictive maintenance modules to minimize electrified vehicle downtime.
- Vehicle Maintenance:Service interval optimization and component replacement forecasting. German independent workshops adopt these tools to compete with authorized dealership networks.
- Warranty Services:Automated claims validation and fraud detection through driving behavior correlation. OEMs deploy this to reduce goodwill expenditure on powertrain failures.
- Insurance Telematics:Usage-based pricing through real-time risk scoring. United States personal auto carriers require standardized diagnostic trouble code feeds for policy tiering.
Fleet management captures the largest revenue pool; insurance telematics is climbing the fastest among consumer-facing applications.
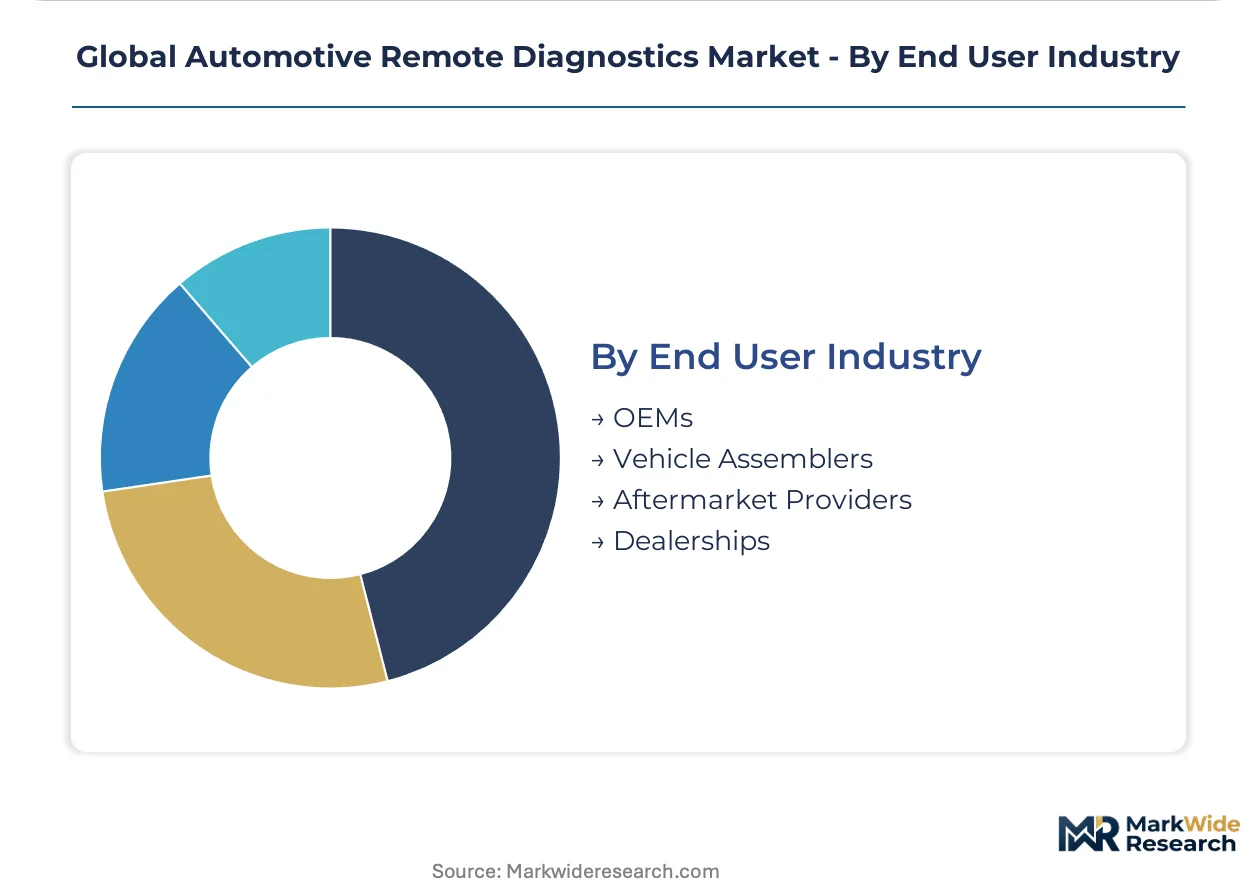
End User Industry:
Procurement authority sits at different value chain positions — production-integrated solutions versus aftermarket retrofit channels.
- OEMs:Original equipment manufacturers specifying embedded diagnostic architectures during vehicle platform development. Their purchasing power concentrates semiconductor procurement for telematics control units.
- Vehicle Assemblers:Contract manufacturers integrating Tier-1 supplied diagnostic modules into final assembly. Their cost pressure drives standardization of diagnostic interfaces.
- Aftermarket Providers:Independent suppliers of retrofit diagnostic hardware and software subscriptions. This channel serves aging vehicle populations in price-sensitive emerging markets.
- Dealerships:Authorized service networks leveraging diagnostic platforms for customer retention and service revenue. Their investment prioritizes manufacturer-certified calibration tools.
OEMs command the highest per-unit spending; aftermarket providers are expanding most quickly in electrified commercial vehicle conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates embedded diagnostic engineering talent, while the United States drives fleet-scale telematics procurement through logistics operator demand. China accelerates domestic platform development for electrified vehicle monitoring. India and Japan round out the geographic map with distinct regulatory and industrial drivers.
United States
Fleet operators across interstate corridors mandate sub-100-millisecond latency fault detection for electrified vehicle pools. The NHTSA's recall automation protocols require standardized diagnostic trouble code reporting from all commercial platforms. Detroit's automotive engineering clusters anchor Tier-1 supplier relationships with domestic OEMs.
Germany
Premium manufacturers demand firmware-level diagnostic integration for emissions compliance verification under KBA type-approval protocols. The EU Green Deal compels continuous monitoring deployment for automated recall management. Stuttgart and Munich engineering clusters concentrate embedded controller calibration expertise.
China
Domestic OEMs accelerate proprietary diagnostic platform development for battery health monitoring in electrified fleets. The MIIT mandates connected vehicle data standards that shape telematics architecture requirements. Shanghai and Shenzhen technology corridors concentrate cloud infrastructure deployment for regional data sovereignty.
Japan
Automotive suppliers integrate thermal management expertise into battery diagnostic systems for hybrid and electric platforms. METI standards govern cybersecurity certification timelines for connected vehicle components. Nagoya's industrial corridor sustains long-term supply relationships with domestic OEM production networks.
India
Commercial vehicle operators under the PLI scheme for automotive manufacturing create demand for retrofit diagnostic hardware in electrified conversions. The BIS develops national standards for telematics device interoperability across state transport networks. Tamil Nadu and Maharashtra manufacturing clusters attract Tier-1 diagnostic module assembly investments.
Global Automotive Remote Diagnostics Market Key Industry Players
German producers anchor one tier; Japanese and American specialists hold differentiated positions in hardware and software layers. The vendor base stratifies across three tiers: integrated Tier-1 automotive suppliers, pure-play telematics platform operators, and aftermarket diagnostic tool providers. Two strategic archetypes dominate: vertically integrated electronics conglomerates with powertrain heritage, and cloud-native fleet software specialists with recurring revenue models. Competitive moves center on semiconductor procurement consolidation and over-the-air update capability acquisition.
Within the integrated Tier-1 tier, Robert Bosch GmbH and Continental AG exemplify the electronics conglomerate archetype with embedded controller heritage. Denso Corporation occupies a parallel position among Japanese suppliers. Snap-on Incorporated represents the aftermarket diagnostic tool specialist archetype. Verizon Connect and Geotab Inc. sit within the cloud-native fleet platform tier. These six entities collectively span the value chain from firmware-level hardware through SaaS delivery.
| Leading Market Players |
|---|
| Denso Corporation |
| Snap-on Incorporated |
| Robert Bosch GmbH |
| Vector Informatik GmbH |
| Octo Group |
| Continental AG |
| Verizon Connect |
| Geotab Inc. |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
A sharp divergence between embedded OEM-grade diagnostic controllers and aftermarket retrofit hardware manifests in both margin structures and supply chain configurations. Premium firmware-integrated units command recurring SaaS attach rates under EU Cyber Resilience Act certification timelines, while commodity telematics devices face cost compression from Indian and Chinese assembly competition.
Pricing Analysis
Distributor margins in the aftermarket channel absorb 25-35 points before reaching fleet operators, whereas direct-to-OEM supply contracts trade volume discounts for platform exclusivity. Pricing stratifies across premium, standard, and economy tiers based on latency performance and GDPR-compliant cloud instance segmentation. Cost compression in the hardware layer intensifies as Taiwanese foundry allocation tightens for telematics control unit semiconductors. Mid-size logistics providers in the United Kingdom exhibit the highest price sensitivity, while German premium manufacturers prioritize firmware calibration accuracy over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for diagnostic module fulfillment. Semiconductor fabrication draws from Taiwan and South Korea, while battery health monitoring sensors source from Japanese thermal management specialists. Single-source vulnerability concentrates in 5G modem chipsets for cellular-enabled telematics units. Distribution runs through authorized Tier-1 supplier networks for OEM production, with independent distributors serving aftermarket retrofit demand in India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
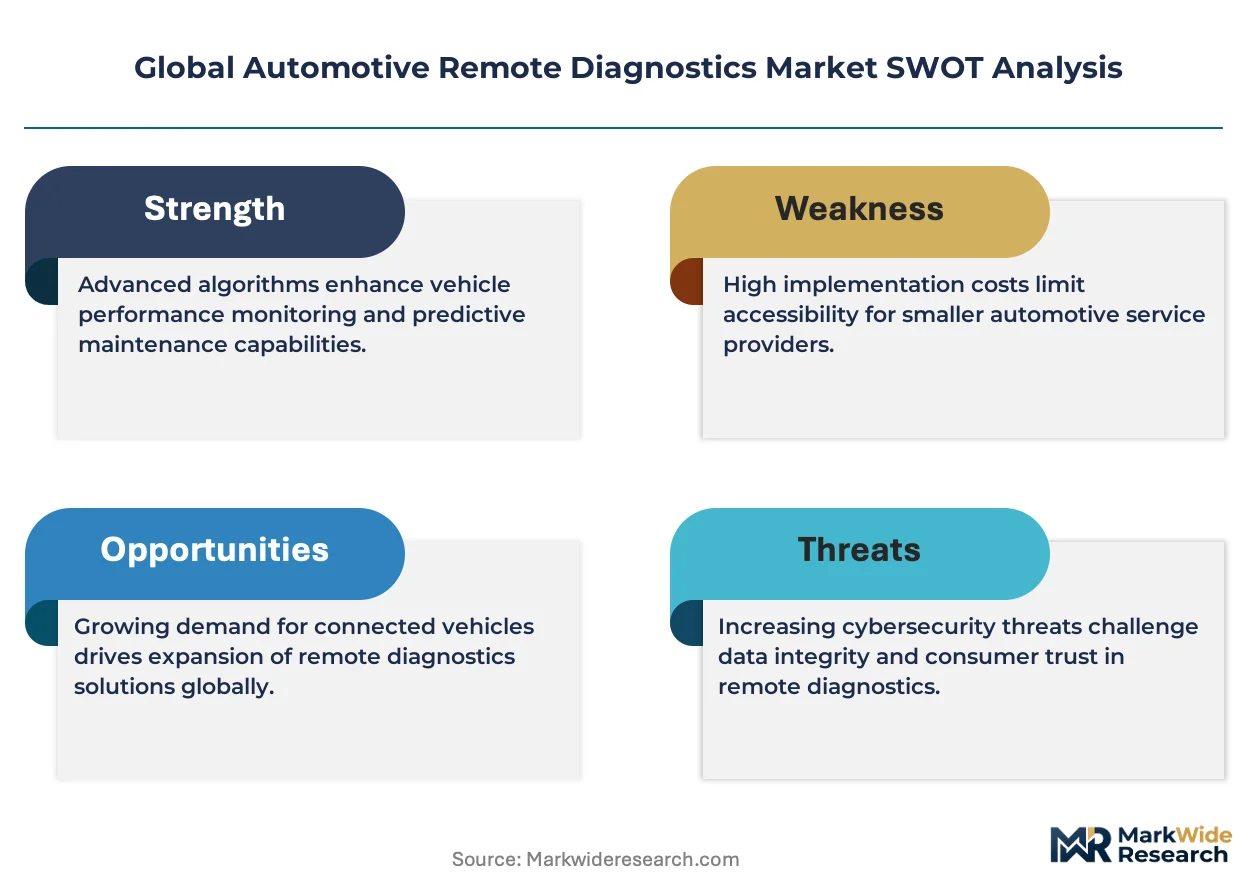
The EU Cyber Resilience Act's 12-18 month certification timeline against the US self-certification approach creates a regulatory cost arbitrage favoring American cloud-native platform operators over European hardware incumbents.
For Market Incumbents: Deepen captive semiconductor procurement through long-term foundry agreements in Taiwan and South Korea to offset allocation risk. Invest in edge AI inference engine calibration capabilities to defend against cloud-native fleet software specialists encroaching on firmware-level diagnostic integration. Prioritize GDPR-compliant cloud instance segmentation as a compliance moat against American competitors lacking European data sovereignty architecture. For New Entrants and Emerging Players: Mid-size electrified fleet operators in India under the PLI scheme represent the most penetrable buyer archetype, underserved by incumbent Tier-1 supplier relationships optimized for premium German OEMs. Target battery health monitoring retrofits for commercial vehicle conversions through Bluetooth-enabled hardware paired with usage-based SaaS tiers. Pursue direct sales partnerships with Tamil Nadu and Maharashtra manufacturing clusters to bypass established distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded controller firmware expertise concentrates in Stuttgart and Munich engineering clusters against cloud platform scale economies. Frame long-term viability around 5-10 year software-defined vehicle transition timelines where diagnostic AI layers displace hardware-centric business models. Target acquisition profiles featuring edge-to-cloud convergence capabilities and regional cloud instance deployment. Watch NHTSA recall automation mandate enforcement velocity as the signal for US fleet procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Over-the-Air Update Capability Investment | Extends platform lifecycles and reduces physical service visits for OEMs under EU Green Deal mandates. |
| Edge AI Inference Engine Development | Enables sub-100-millisecond latency fault detection without cloud dependency for German fleet operators. |
| Regional Cloud Instance Segmentation | Satisfies GDPR data sovereignty requirements and inflates infrastructure costs for cross-border competitors. |
| Battery Health Monitoring Partnership | Leverages Japanese thermal management expertise for electrified fleet predictive maintenance contracts. |
| Semiconductor Procurement Consolidation | Secures foundry allocation for telematics control units amid Taiwan and South Korea capacity constraints. |
Research Approach
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, fleet operations directors, and aftermarket distribution channel heads grounded the qualitative foundation. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and EU regulatory filings under the Cyber Resilience Act and GDPR. Bottom-up sizing of telematics hardware shipments and top-down triangulation against fleet management software revenue pools produced convergent estimates.
Segment-level projections across onboard diagnostics, telematics devices, diagnostic software, and cloud platforms were modeled over the analysis window using propulsion architecture splits and regional production cluster data. CAGRs were derived from logistic diffusion curves fitted to electrified vehicle penetration rates and predictive maintenance adoption thresholds. Forecast inputs included semiconductor supply allocation forecasts and EU emissions enforcement protocol implementation timelines.
Underlying measurement precision varies by segment; cloud platform SaaS revenue carries tighter precision than aftermarket hardware retrofit volumes given disclosure practices. Forecasts reflect assumptions around regulatory implementation velocity and foundry capacity expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market