
 Southeast Asia Box Truck Market | 2026-2036
Southeast Asia Box Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Box Truck Market Analytics
Modular cargo box configurations with interchangeable dry van, refrigerated, and flatbed inserts is repositioning fleet procurement strategies across Southeast Asia. Isuzu Motor Co. Ltd leverages its dominant diesel engine platform to sustain aftermarket parts revenue throughout the region. Mitsubishi Fuso Truck and Bus Corporation anchors its position through localized assembly plants in Indonesia and Thailand. Hyundai Motor Company competes on electric and hybrid drivetrain development for urban delivery routes.
A box truck integrates a rigid chassis cab with an enclosed rectangular cargo container, typically constructed from aluminum or composite panels over a steel frame, designed for urban and intercity freight distribution with gross vehicle weights ranging from 3.5 to 12 tonnes. Light duty vehicles dominate unit sales across ASEAN capitals due to narrow street infrastructure and weight restrictions, while electric powertrains represent the fastest-expanding fuel category as charging networks proliferate in Singapore and Bangkok. E-commerce end users command premium pricing for refrigerated and specialized configurations, whereas logistics operators optimize total cost of ownership through diesel medium duty platforms serving regional hub-and-spoke networks.
Thailand's Department of Land Transport enforces Euro V emission compliance for commercial vehicle registrations, while Indonesia's Ministry of Environment and Forestry coordinates with industry on carbon reduction timelines for freight fleets. Singapore's Land Transport Authority mandates electric vehicle readiness standards for new commercial developments, directly shaping charging infrastructure investment and box truck electrification roadmaps. Fleet operators and OEMs must monitor divergent national electrification timelines and emission enforcement intensity when allocating product development budgets across ASEAN markets.
Market Dynamics
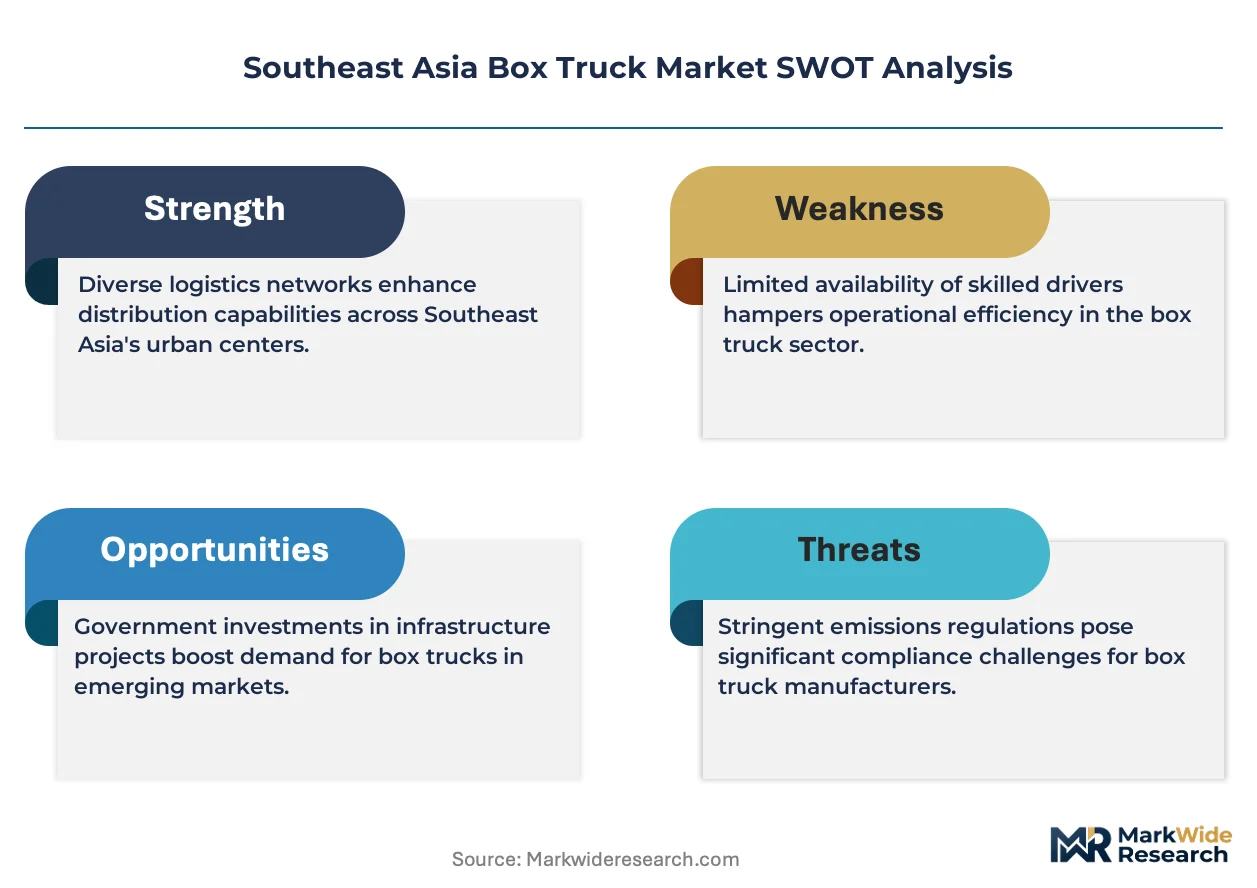
Euro V and Euro VI emission standards are forcing diesel engine upgrades and accelerating electric powertrain trials across ASEAN member states, reshaping fleet procurement timelines and aftermarket parts economics throughout Indonesia, Thailand, and Vietnam.
Growth Catalysts
- E-commerce fulfillment fleets:Last-mile delivery operations are scaling across Indonesia, Thailand, and Vietnam, generating sustained demand for light and medium duty configurations with rapid turnaround requirements.
- Modular cargo box configurations:Interchangeable dry van, refrigerated, and flatbed inserts enable fleet operators to repurpose single chassis across multiple service contracts, improving asset utilization rates.
- Singapore's Land Transport Authority mandates:Electric vehicle readiness standards for new commercial developments are accelerating charging infrastructure investment and box truck electrification roadmaps in urban corridors.
Market Restraints
- Diesel engine upgrade costs:Euro V compliance requirements impose capital burdens on small fleet operators in Indonesia and Vietnam, compressing replacement cycle frequencies.
- Charging infrastructure gaps:Proliferation remains concentrated in Singapore and Bangkok, leaving intercity routes across the Java corridor and Eastern Economic Corridor underserved for electric deployment.
- Steel and aluminum input volatility:Cargo container manufacturing faces margin pressure from fluctuating commodity prices, constraining pricing flexibility for OEMs.
Strategic Opportunities
- Refrigerated configurations for pharmaceutical cold chain:ASEAN's expanding vaccine distribution networks and temperature-sensitive biologics trade create premium service tiers.
- Battery swapping stations for urban delivery:Thailand's Eastern Economic Corridor manufacturing zones present concentrated demand for rapid energy replenishment without charging downtime.
- Telematics-enabled fleet management:Integration of route optimization and predictive maintenance software is converging with hardware procurement decisions, creating recurring revenue streams.
Industry Challenges
- Technician training for electric powertrain diagnostics:Southeast Asia's vocational education infrastructure lags behind electrification roadmaps, creating service bottlenecks.
- Divergent national electrification timelines:Fleet operators must navigate Indonesia's Ministry of Environment coordination processes alongside Thailand's Department of Land Transport enforcement calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Box Truck Market |
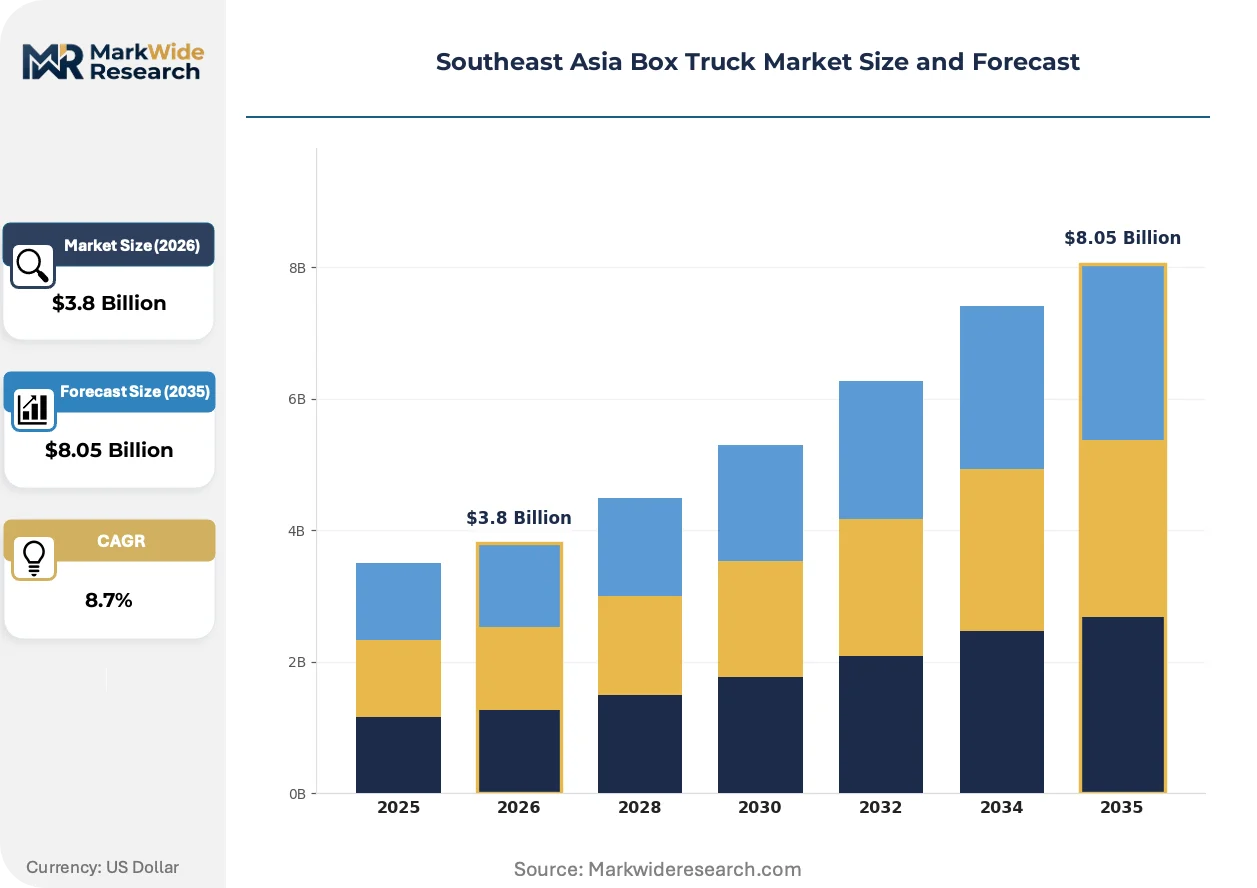
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Specialized Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: Retail, Logistics, Construction, E-Commerce Sales Channel: Direct Sales, Distributors, Online Platforms, Auctions |
| Companies Covered | Isuzu Motor Co. Ltd, Hino Motors, Ltd., Mitsubishi Fuso Truck and Bus Corporation, Ford Motor Company, UD Trucks Corp., IVECO Group (CNH Industrial NV), Mercedes-Benz Group AG, Toyota Motor Corporation, Hyundai Motor Company, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Box Truck Market Evolving Landscape
Digital freight matching platforms and battery chemistry advances are compressing traditional procurement cycles and enabling new ownership models across ASEAN logistics networks.
Light duty electric box trucks are converging with fast-charging infrastructure deployments in Bangkok and Singapore, where urban delivery fleets face strict idling restrictions and congestion pricing. E-commerce operators with high daily mileage requirements are piloting these configurations for fixed-route distribution. The technology is converging with route density optimization algorithms to enable total cost of ownership parity with diesel alternatives in high-utilization scenarios.
Thailand's Department of Land Transport enforces Euro V emission compliance for commercial vehicle registrations, compelling diesel engine retrofits and accelerating hybrid powertrain adoption. Industrial consequence includes compressed replacement demand for pre-compliant vehicles and aftermarket parts inventory rebalancing. Medium duty fleet operators serving regional hub-and-spoke networks face the most concentrated compliance costs and are responding with extended lease terms to defer capital outlays.
Asset-light fleet management contracts are displacing traditional vehicle ownership among third-party logistics providers, particularly in Vietnam's emerging e-commerce corridors. Leasing aggregators and mobility-as-a-service platforms are capturing procurement decisions previously held by fleet managers. This shift is most visible in Jakarta and Ho Chi Minh City, where venture-backed delivery startups prioritize operational flexibility over balance sheet control.
Southeast Asia Box Truck Market Segmentation
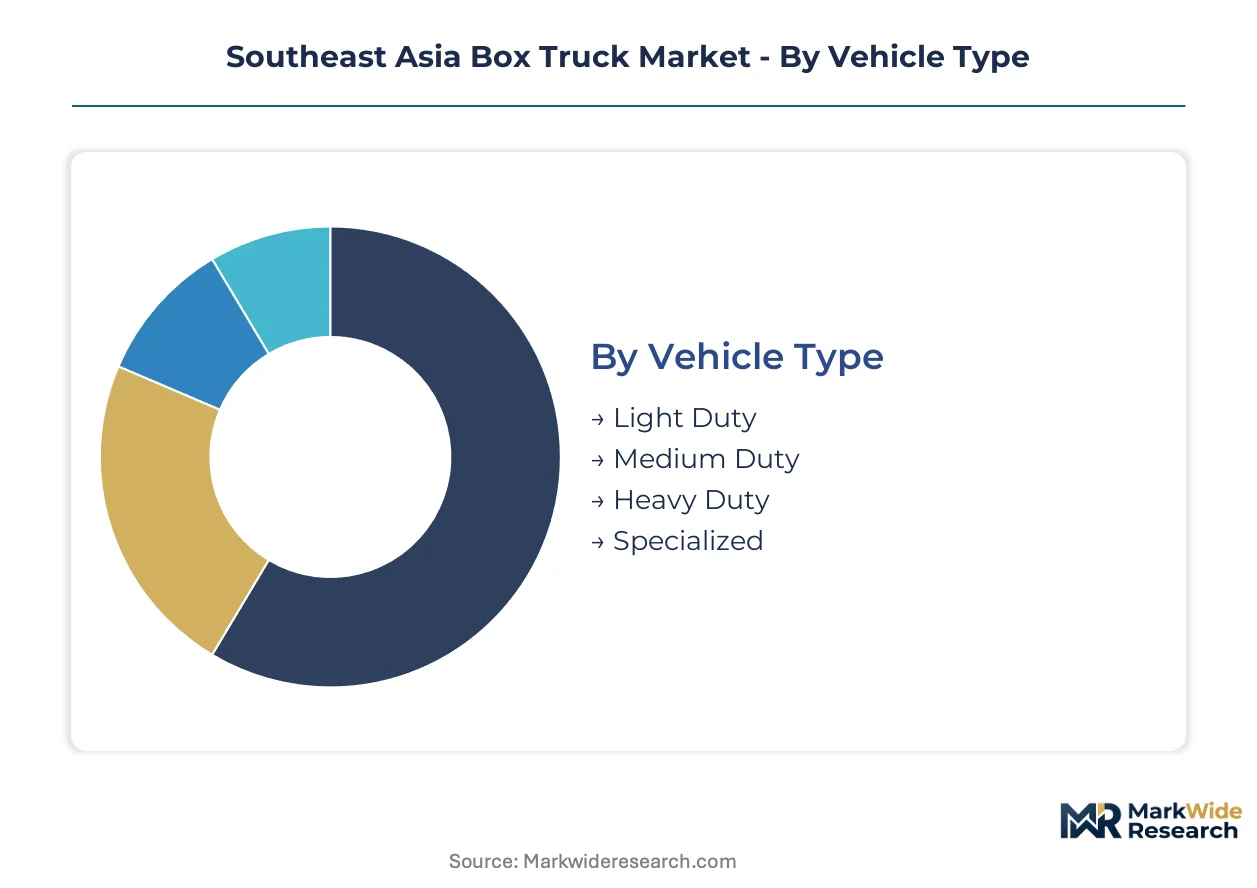
Segmentation reveals how procurement priorities diverge across ASEAN freight corridors. Fleet operators in Jakarta and Bangkok weight vehicle specifications against regulatory timelines and route density constraints.
Vehicle Type:
Payload capacity and maneuverability requirements drive chassis selection across urban delivery networks and intercity haulage.
- Light Duty:Gross vehicle weights from 3.5 to 7.5 tonnes suit narrow street infrastructure in ASEAN capitals. Demand concentrates in Vietnam's Ho Chi Minh City corridors where weight restrictions and congestion pricing favor compact configurations for last-mile e-commerce fulfillment.
- Medium Duty:Ranging 7.5 to 12 tonnes, these chassis anchor hub-and-spoke distribution across Thailand's Eastern Economic Corridor manufacturing zones. Logistics operators optimize total cost of ownership through diesel platforms serving regional freight consolidation points.
- Heavy Duty:Configurations exceeding 12 tonnes serve specialized industrial and construction material transport with reinforced suspension systems.
- Specialized:Custom wheelbases and axle configurations address refrigerated pharmaceutical cold chain and oversized cargo requirements.
Volume sits with Light Duty; growth tilts toward Medium Duty as regional logistics networks densify.
Fuel Type:
Emission compliance deadlines and energy infrastructure maturity reshape powertrain procurement calendars across divergent national timelines.
- Diesel:Euro V and Euro VI compliant engines retain dominance in intercity routes where refueling infrastructure is established. Indonesia's Java corridor and Thailand's Eastern Economic Corridor manufacturing zones sustain concentrated demand for medium duty diesel platforms serving hub-and-spoke networks.
- Electric:Battery-electric powertrains with 150-300 kilometer ranges are gaining share fastest in Singapore and Bangkok urban delivery fleets facing strict idling restrictions. Singapore's Land Transport Authority mandates for commercial development charging readiness accelerate deployment timelines.
- Gasoline:Lower upfront capital requirements attract small fleet operators in Vietnam's emerging logistics corridors with less stringent emission enforcement.
- Hybrid:Diesel-electric configurations bridge compliance gaps where charging infrastructure remains underdeveloped across intercity routes.
Diesel retains volume leadership; electric configurations show steepest expansion trajectory where charging networks mature.
End User:
Service contract structures and asset utilization rates determine specification priorities across contrasting operational models.
- E-Commerce:High-frequency delivery requirements with rapid turnaround times command premium specifications including telematics integration and modular cargo configurations. Indonesia's fulfillment networks and Vietnam's venture-backed delivery startups prioritize operational flexibility over balance sheet ownership.
- Logistics:Third-party operators serving multiple client contracts favor interchangeable dry van and refrigerated inserts to improve asset utilization across seasonal demand fluctuations.
- Retail:Fixed-route distribution from distribution centers to store networks favors standardized specifications with predictable maintenance schedules.
- Construction:Material transport requirements drive demand for flatbed configurations and reinforced chassis specifications.
Logistics commands current volume; e-commerce operators are expanding most quickly as digital retail penetration deepens across ASEAN markets.
Sales Channel:
Procurement authority is shifting from fleet managers to leasing aggregators and digital platforms across ASEAN urban centers.
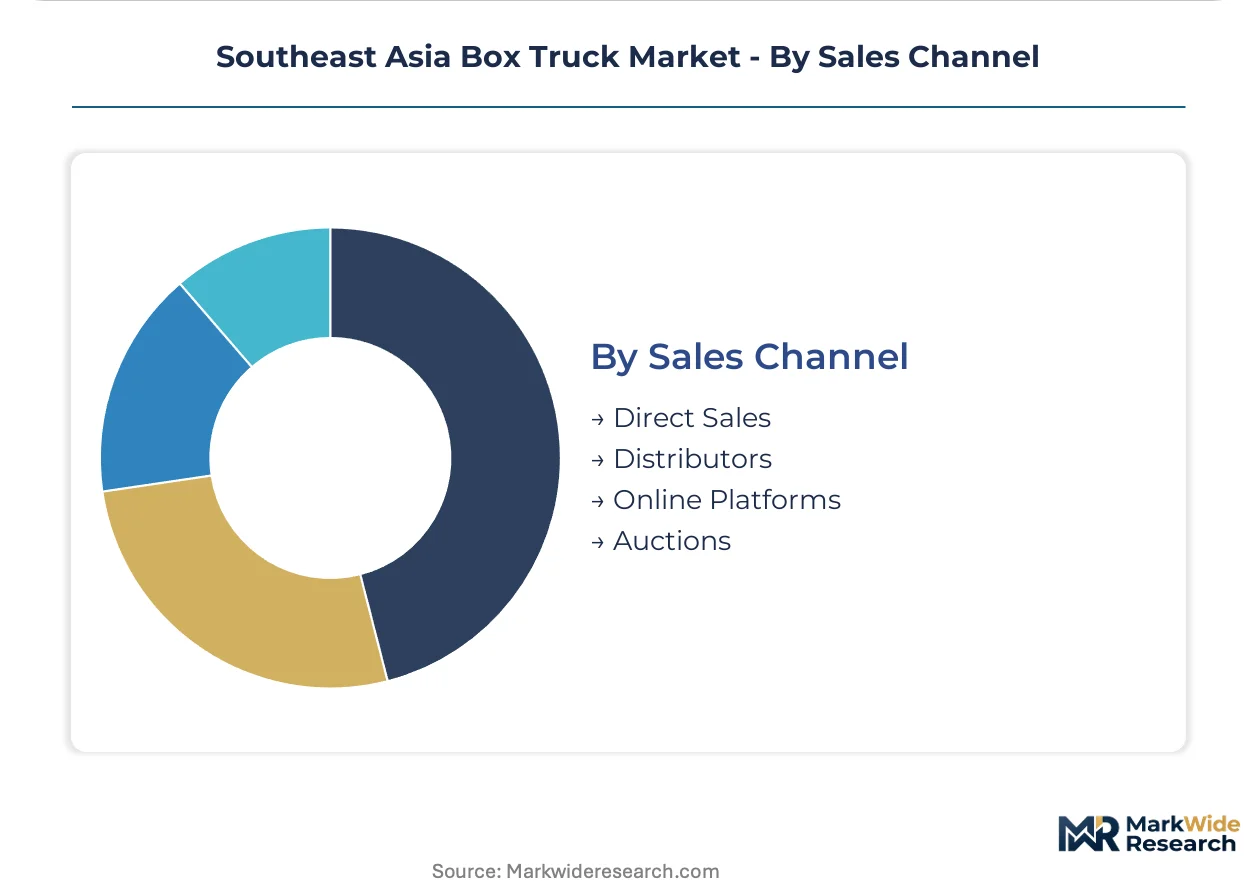
- Distributors:Localized dealer networks with service capabilities dominate medium duty procurement in Indonesia and Thailand where aftermarket support influences purchase decisions.
- Direct Sales:OEM relationship programs serve large fleet operators with volume pricing and customized specification negotiations.
- Online Platforms:Digital marketplaces are capturing light duty transactions among small operators in Vietnam and Indonesia seeking transparent pricing and rapid procurement cycles.
- Auctions:Secondary market channels support fleet refresh programs and asset disposal for operators deferring new vehicle capital outlays amid emission upgrade pressures.
Distributors retain volume primacy; online platforms are climbing the fastest as asset-light fleet management models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Thailand's Eastern Economic Corridor while consumption spreads across Indonesia's Java corridor and Vietnam's emerging logistics hubs. Manufacturing investments lag fleet expansion in high-growth demand centers.
Indonesia
E-commerce fulfillment networks and last-mile delivery scaling drive chassis demand across Java's urban corridors. The Ministry of Environment and Forestry coordinates carbon reduction timelines with freight fleet operators. Jakarta and Surabaya anchor procurement volumes for light duty configurations serving narrow street infrastructure.
Thailand
Eastern Economic Corridor manufacturing zones sustain medium duty platform demand for regional hub-and-spoke distribution. The Department of Land Transport enforces Euro V emission compliance for commercial vehicle registrations. Bangkok's urban delivery fleets face strict idling restrictions that accelerate electric powertrain trials.
Vietnam
Venture-backed delivery startups and emerging third-party logistics operators expand fleet footprints in Ho Chi Minh City corridors. National emission enforcement remains less stringent than ASEAN peers, attracting gasoline configurations with lower upfront capital requirements. The Mekong Delta industrial zones generate intercity haulage demand for refrigerated pharmaceutical transport.
Singapore
Urban delivery electrification advances fastest where charging infrastructure density supports battery-electric deployment. The Land Transport Authority mandates electric vehicle readiness standards for new commercial developments. City-state logistics operators pilot 150-300 kilometer range configurations for fixed-route distribution under congestion pricing regimes.
Malaysia
Peninsular Malaysia's logistics networks bridge Singapore-Indonesia freight corridors with medium duty diesel platforms. National regulators align emission timelines with ASEAN harmonization frameworks. Johor Bahru and Port Klang industrial clusters concentrate fleet procurement for cross-border haulage operations.
Southeast Asia Box Truck Market Competitive Landscape
The competitive structure tilts toward established Japanese and Korean OEMs with localized assembly infrastructure. Market concentration reflects high barriers to aftermarket parts networks and dealer service capabilities. Three archetypes dominate: legacy diesel engine specialists, electric powertrain entrants, and modular cargo system integrators. Capacity expansion and strategic partnerships represent the primary competitive vectors as emission deadlines compress procurement calendars.
Among Japanese-origin manufacturers, Isuzu Motor Co. Ltd and Mitsubishi Fuso Truck and Bus Corporation exemplify the diesel platform archetype with established regional assembly positions. Hyundai Motor Company represents the electrification-focused tier competing on urban delivery powertrain development. These three anchors occupy distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Isuzu Motor Co. Ltd |
| Hino Motors, Ltd. |
| Mitsubishi Fuso Truck and Bus Corporation |
| Ford Motor Company |
| UD Trucks Corp. |
| IVECO Group (CNH Industrial NV) |
| Mercedes-Benz Group AG |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Others |
Value Network & Pricing Analysis
Euro V and Euro VI emission mandates gate qualified supply and premium-tier pricing access for ASEAN fleet operators, compressing margins for non-compliant chassis while elevating certified configurations. Indonesia's Ministry of Environment and Forestry coordinates carbon reduction timelines that tether procurement eligibility to compliance tiers, forcing price stratification across diesel upgrade and electric powertrain categories.
Pricing Analysis
Cost-down pressure on medium duty diesel platforms accelerates because Euro V retrofit requirements compress replacement cycles for Indonesian and Vietnamese small fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates telematics-integrated refrigerated configurations from basic dry van inserts and gasoline-powered light duty alternatives. Price differentiation traces to certification grade and after-sales service bundling, with e-commerce fulfillment fleets showing least price sensitivity for rapid-turnaround specifications while independent logistics operators in Vietnam's emerging corridors prioritize lowest upfront capital outlays.
Supply Chain Analysis
Remanufacturing flows for diesel engine blocks and battery pack refurbishment anchor aftermarket revenue streams for Isuzu and Mitsubishi Fuso's regional assembly networks. Manufacturing concentrates in Thailand's Eastern Economic Corridor, Indonesia's Java corridor assembly plants, and South Korean component hubs for electric drivetrain modules. Steel and aluminum cargo container inputs draw from Chinese and Australian smelters, exposing margins to commodity price volatility. Distribution runs through localized dealer networks with service capabilities across Jakarta, Bangkok, and Ho Chi Minh City corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric powertrains are displacing diesel dominance across Singapore and Bangkok urban delivery fleets, compressing procurement timelines for legacy engine platforms throughout the analysis window.
For Market Incumbents: Hedge emission compliance exposure by accelerating hybrid powertrain development for Thailand's Eastern Economic Corridor intercity routes while consolidating aftermarket parts inventory for Euro V diesel platforms serving Indonesia's Java corridor hub-and-spoke networks. Channel control through localized assembly plants remains the critical defensive lever against Korean electric entrants. For New Entrants and Emerging Players: Leasing aggregators and mobility-as-a-service platforms offer the most penetrable channel for asset-light fleet management contracts displacing traditional ownership among Vietnam's venture-backed delivery startups. Target refrigerated pharmaceutical cold chain configurations in the Mekong Delta industrial zones where temperature-sensitive biologics trade creates premium service tiers underserved by incumbent dry van specialists. For Investors and Strategic Acquirers: Thailand's Department of Land Transport accelerating Euro V enforcement calendars is the leading indicator that compliance-ready electric powertrain portfolios will command valuation premiums over legacy diesel-dependent asset bases. Acquisition targets should screen for modular cargo system integrators with telematics-enabled fleet management software recurring revenue streams rather than pure hardware manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell capacity for Hyundai's Bangkok electric delivery pilots against Korean supplier allocation constraints. |
| Charging Infrastructure Partnership | Aligns Singapore Land Transport Authority mandates with fleet operator electrification roadmaps in urban corridors. |
| Platform Standardization | Enables Isuzu's modular cargo configurations to interchange across light and medium duty chassis variants. |
| Backward Integration | Captures steel frame manufacturing margin for Mitsubishi Fuso's Indonesian assembly operations. |
| Software-Defined Vehicle Investment | Converges route optimization algorithms with hardware procurement for Jakarta e-commerce fulfillment networks. |
Research Methodology
Multi-period observation of fleet procurement volumes, emission compliance registrations, and charging infrastructure deployments anchored the trend analysis, supplemented by interviews with fleet operations directors, OEM platform engineers, aftermarket service heads, and logistics procurement managers at third-party operators across Indonesia, Thailand, and Vietnam. Secondary validation drew from ASEAN automotive production databases, Department of Land Transport registration filings, Ministry of Environment coordination documents, and customs records for steel and aluminum inputs. Bottom-up chassis shipment tallies triangulated against top-down freight demand modeling.
Input-output matrices mapped vehicle type, fuel category, end-user segment, and sales channel dimensions across the projection horizon, with CAGRs derived from regression against macro freight indicators and e-commerce penetration trajectories. Modeling incorporated battery cost decline curves, Euro V enforcement intensity differentials across national regulators, and modular cargo attachment rates by logistics operator contract structures.
Caveats apply where Indonesia's Ministry of Environment and Forestry carbon timeline revisions or Thailand's Department of Land Transport enforcement calendar shifts could materially shift the outlook for diesel platform replacement demand. Practitioners should monitor Singapore Land Transport Authority charging readiness mandate expansion and battery swapping station pilot outcomes in the Eastern Economic Corridor for early signals of electric powertrain adoption inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Robotic Haul Trucks Market