
 Telematics and Connectivity Processors Market | 2026-2036
Telematics and Connectivity Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Telematics and Connectivity Processors Market Analytics
Commercial fleet management is expanding as the dominant demand vertical for telematics and connectivity processors, displacing earlier consumer-navigation-centric procurement patterns. Qualcomm Technologies leverages its cellular modem leadership to anchor premium chipset supply for connected commercial vehicles. Robert Bosch GmbH sustains R&D intensity across V2X protocol stacks and edge-computing architectures for automotive OEMs. Continental AG competes through manufacturing scale in integrated hardware-software modules purpose-built for heavy-duty logistics applications.
Telematics and connectivity processors are semiconductor-based computing engines that integrate GPS basebands, cellular modems, CAN bus controllers, and cryptographic accelerators within single-package system-on-chip designs, typically operating across temperature ranges from minus forty to eighty-five degrees Celsius to survive engine-bay and under-vehicle mounting locations. Their primary commercial purpose is to ingest, process, and transmit vehicle-generated data to cloud platforms while executing real-time safety and navigation algorithms at the edge. Hardware modules retain the largest revenue share among product type segments due to BOM concentration and replacement cycles, while software solutions capture expanding margin pools as over-the-air update architectures proliferate. V2X connectivity technology is growing fastest among technology segments, driven by regulatory mandates for direct vehicle-to-infrastructure communication in European and East Asian markets.
The European Union's Cyber Resilience Act and the UN ECE WP.29 cybersecurity regulations are reshaping processor design requirements, mandating hardware security modules and secure boot architectures as preconditions for type approval in regulated vehicle categories. The US NHTSA and FCC jointly influence demand through vehicle safety standards and spectrum allocation for dedicated short-range communications. Stakeholders must monitor divergence between regional certification regimes, as fragmentation between EU cybersecurity mandates and US spectrum policy threatens to splinter product architectures and inflate compliance costs for multi-market suppliers.
Market Dynamics
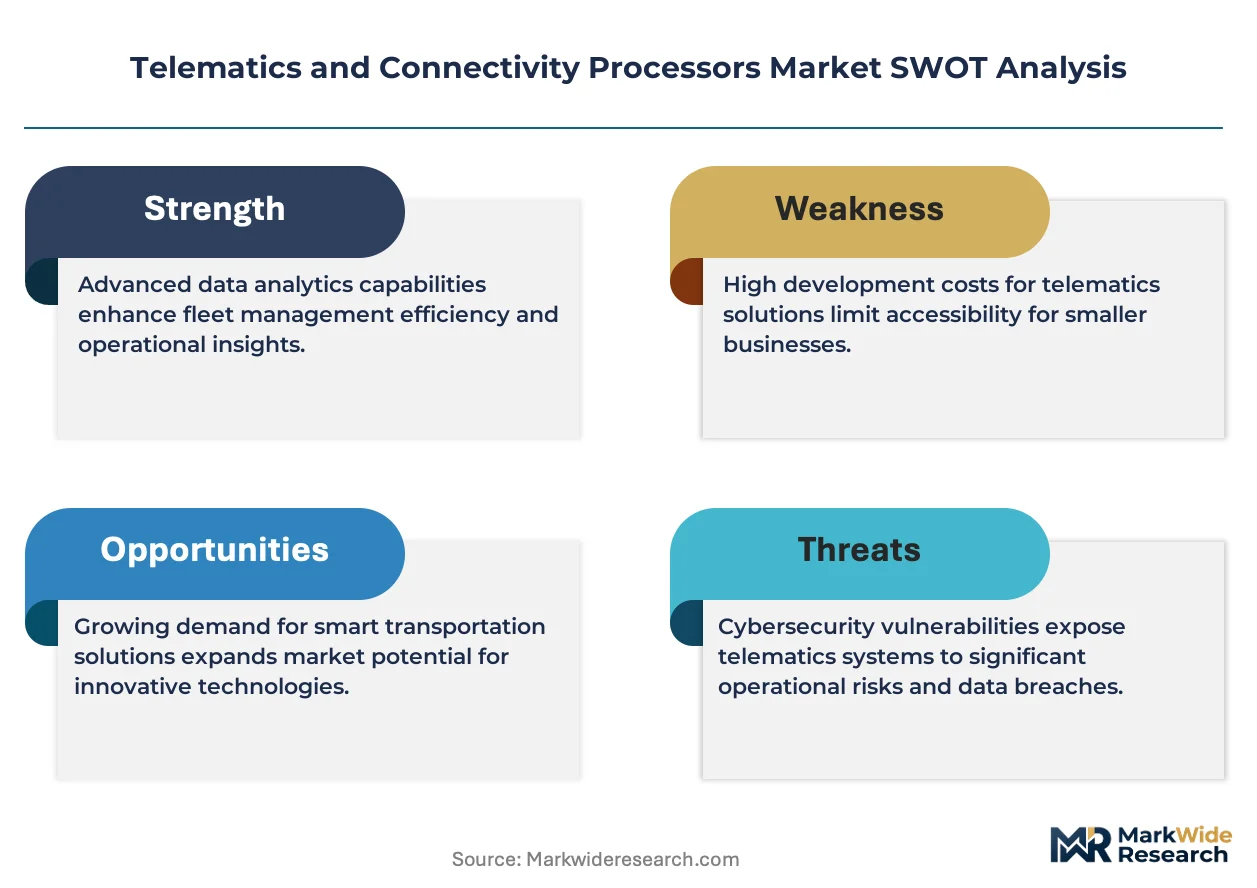
Commercial fleet operators are consolidating procurement around embedded connectivity platforms, forcing processor architectures toward integrated hardware-software stacks with predictive maintenance capabilities and real-time cargo telemetry.
Growth Catalysts
- EU Cyber Resilience Act:Mandates hardware-level encryption and secure boot architectures for connected vehicle components, creating baseline demand for security-hardened processors across regulated vehicle categories.
- Cellular V2X protocol maturation:Direct vehicle-to-infrastructure communication standards are reaching production readiness, enabling processor suppliers to capture value from roadside unit integration projects.
- German automotive cluster density:Stuttgart and Ingolstadt development ecosystems concentrate tier-one supplier R&D spending, generating localized demand pull for advanced telematics silicon.
Market Restraints
- Advanced node wafer costs:7nm and 5nm semiconductor fabrication for high-integration modems concentrates supply among three foundry operators, exposing buyers to capacity allocation volatility.
- Automotive-grade qualification timelines:AEC-Q100 stress testing and PPAP documentation cycles extend processor time-to-revenue beyond eighteen months, compressing effective product lifecycles.
- Silicon carbide power electronics substitution:Edge computing architectures in heavy-duty vehicles are shifting compute loads toward centralized domain controllers, threatening standalone telematics processor attach rates.
Strategic Opportunities
- India commercial vehicle telematics:Regulatory mandates for commercial fleet tracking under AIS-140 standards are creating first-mover openings for localized hardware-software module suppliers.
- Software-defined vehicle architectures:Over-the-air update proliferation is decoupling hardware refresh cycles from feature delivery, enabling recurring revenue models for cybersecurity and analytics stacks.
- 5G-Advanced and sidelink convergence:Integration of cellular broadband with direct-mode V2X communication in single-chip designs reduces BOM complexity for multi-protocol commercial platforms.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-B and ASIL-D certification expertise remains concentrated among semiconductor veterans, constraining supplier scaling velocity.
- Multi-regime compliance fragmentation:Divergence between UN ECE WP.29 cybersecurity mandates and US spectrum allocation policies forces parallel product architectures, inflating engineering overhead.
- Legacy CAN bus integration complexity:Mixed fleets require backward compatibility with 1990s-era vehicle networks, complicating processor software stack maintenance and security patching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telematics and Connectivity Processors Market |
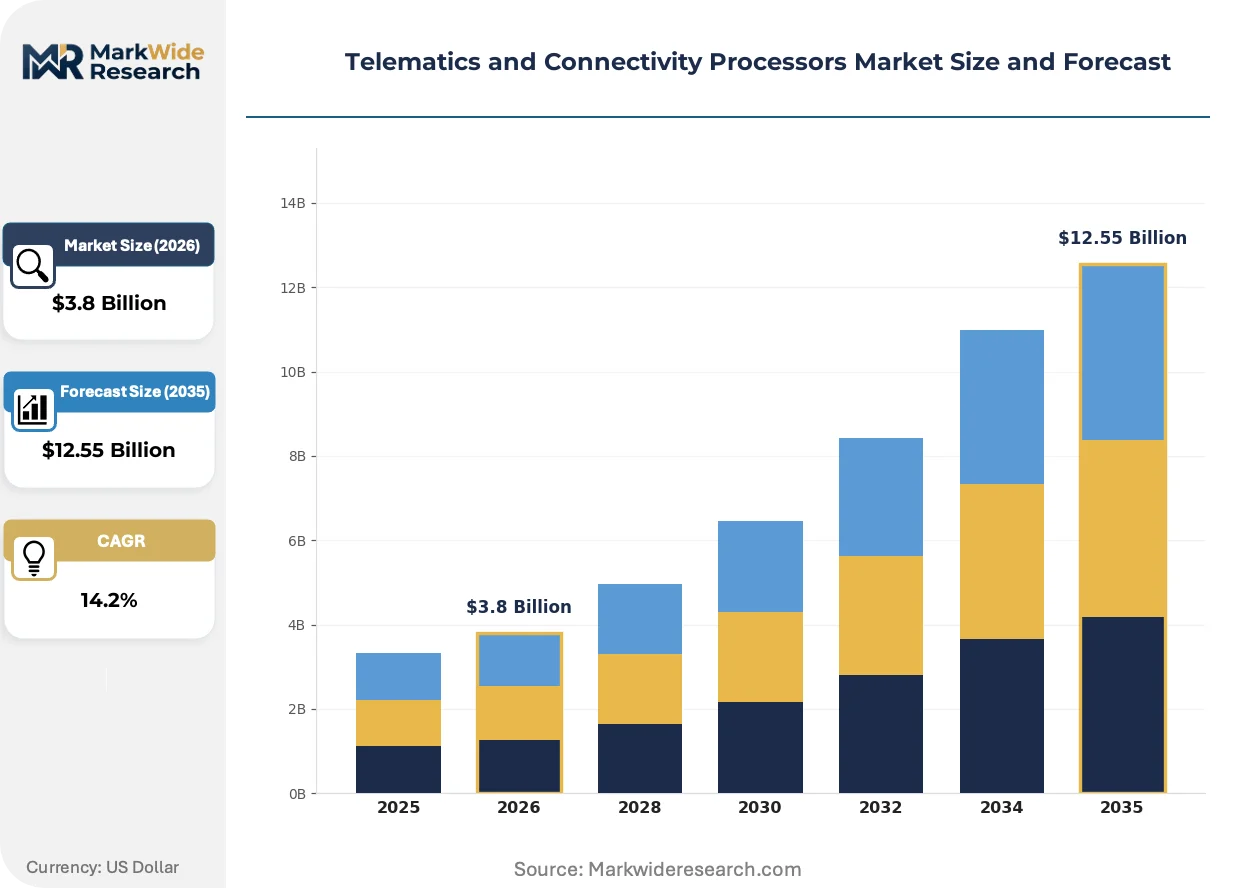
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Modules, Software Solutions, Integrated Circuits, Communication Devices End User: OEMs, Fleet Management, Insurance Companies, Logistics Providers Technology: GPS Tracking, RFID Systems, Cellular Communication, V2X Connectivity Application: Navigation Systems, Vehicle Diagnostics, Remote Monitoring, Safety Services |
| Companies Covered | Continental AG, Robert Bosch GmbH, LG Electronics, Harman International, Denso Corporation, Valeo, Qualcomm Technologies, ZF Friedrichshafen AG, TomTom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telematics and Connectivity Processors Market Evolving Landscape
Edge computing architectures are redistributing intelligence across vehicle networks, compressing the traditional cloud-dependent telemetry model and enabling real-time decision-making at the point of data generation.
Multi-access edge computing (MEC) integration is decentralizing processing workloads from centralized cloud platforms toward roadside infrastructure and vehicle-mounted compute nodes. Commercial fleet operators in Germany and Japan are deploying MEC-enabled processors for sub-10-millisecond latency in autonomous convoy coordination. This topology is decentralizing the historical telematics value chain, compressing carrier data revenue while elevating silicon content at the network edge.
REACH substance restrictions and RoHS recast directives are eliminating hexavalent chromium and specific flame retardants from automotive PCB assemblies, forcing processor packaging redesigns. Module suppliers must requalify solder joint reliability and thermal interface materials under revised environmental compliance frameworks. European tier-one integrators are absorbing these certification costs through selective supplier consolidation favoring vertically capable semiconductor houses.
Subscription-based feature activation is replacing perpetual-license procurement for connectivity stacks and cybersecurity services. Fleet management providers are unbundling hardware acquisition from software entitlement, compressing upfront capital requirements while elongating vendor revenue recognition timelines. This pattern is most pronounced in North American long-haul logistics, where asset-light operators prioritize operational expenditure flexibility over balance-sheet ownership.
Telematics and Connectivity Processors Market Segmentation
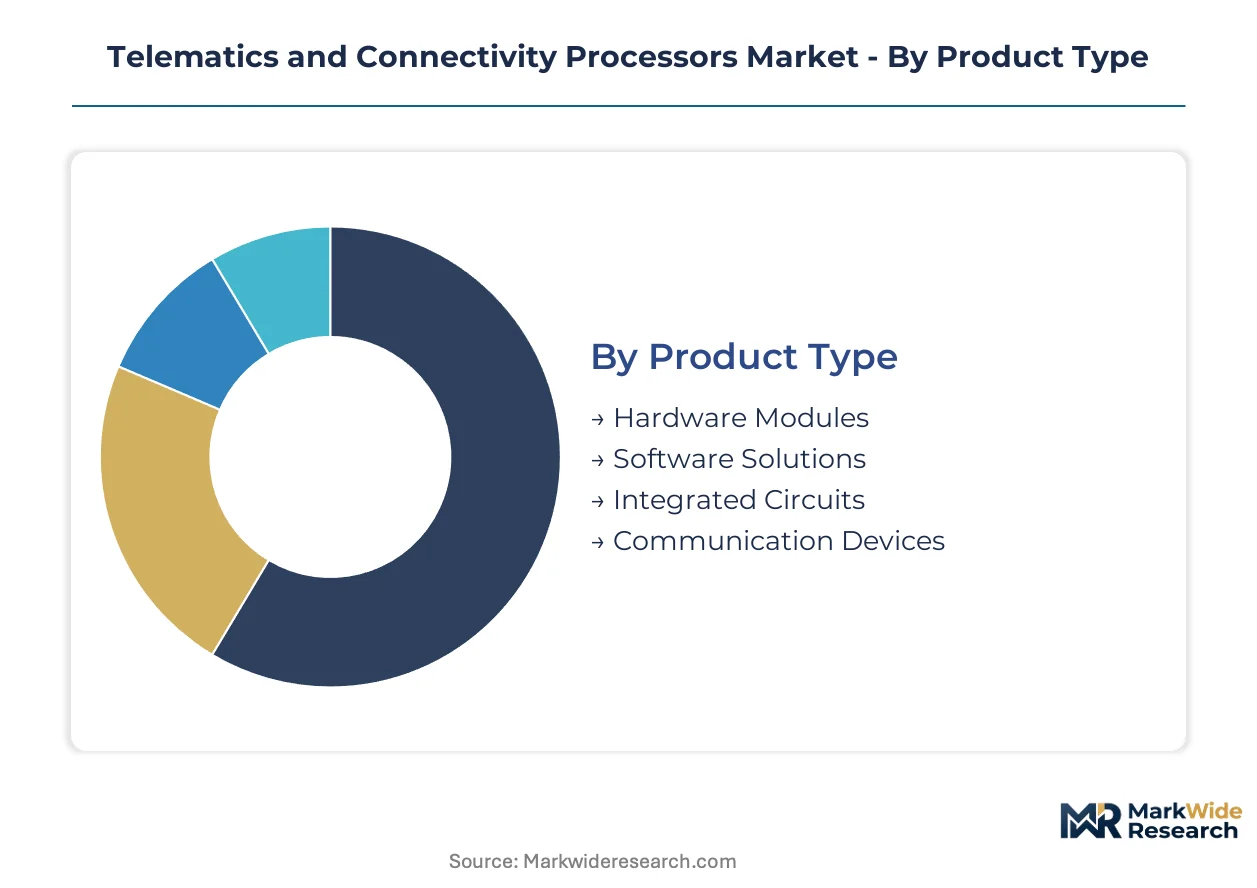
Telematics and connectivity processors serve heterogeneous demand pools with divergent technical specifications, procurement cycles, and margin structures. Segmentation reveals how hardware-centric fleet operators prioritize ruggedized modules while software-defined vehicle architectures elevate recurring revenue from connectivity stacks.
Product Type:
Fleet procurement patterns split sharply between capital-intensive hardware acquisition and operational-expenditure software models.
- Hardware Modules:System-on-chip designs integrate GPS basebands, cellular modems, CAN bus controllers, and cryptographic accelerators within single-package architectures rated for minus forty to eighty-five degrees Celsius operation. German commercial fleet operators around Stuttgart and Ingolstadt concentrate procurement here for engine-bay and under-vehicle mounting durability.
- Software Solutions:Over-the-air update architectures and cybersecurity entitlement platforms decouple feature delivery from hardware refresh cycles. North American long-haul logistics providers are unbundling these from module purchases to preserve operational expenditure flexibility.
- Integrated Circuits:Discrete silicon components for custom board designs serve tier-one suppliers with captive integration capabilities.
- Communication Devices:Peripheral transceivers and antenna modules complete connectivity subsystems for mixed fleet retrofits.
Hardware Modules lead volumes today; Software Solutions is gaining share fastest.
End User:
Customer archetypes span asset ownership models from vehicle manufacturers to third-party fleet operators.
- OEMs:Original equipment manufacturers embed processors during vehicle assembly, demanding AEC-Q100 qualification and PPAP documentation for type approval integration.
- Fleet Management:Commercial operators consolidate procurement around predictive maintenance platforms with real-time cargo telemetry, representing the dominant demand vertical for embedded connectivity.
- Insurance Companies:Usage-based underwriting models drive telematics adoption for driver behavior scoring and claims verification.
- Logistics Providers:Asset-light operators prioritize subscription-based feature activation over balance-sheet hardware ownership.
Fleet Management leads volumes today; Logistics Providers is expanding most quickly.
Technology:
Protocol selection determines regulatory compliance posture and spectrum access rights across jurisdictions.
- GPS Tracking:Multi-constellation baseband receivers provide meter-level positioning for navigation and geofencing applications across commercial vehicle categories.
- Cellular Communication:LTE and 5G modem integration enables broadband cloud connectivity for over-the-air updates and streaming telemetry.
- V2X Connectivity:Direct vehicle-to-infrastructure communication protocols are reaching production readiness, with EU and East Asian regulatory mandates accelerating roadside unit integration projects.
- RFID Systems:Short-range identification supports yard management and automated toll collection for captive fleet operations.
Cellular Communication leads volumes today; V2X Connectivity shows the steepest expansion trajectory.
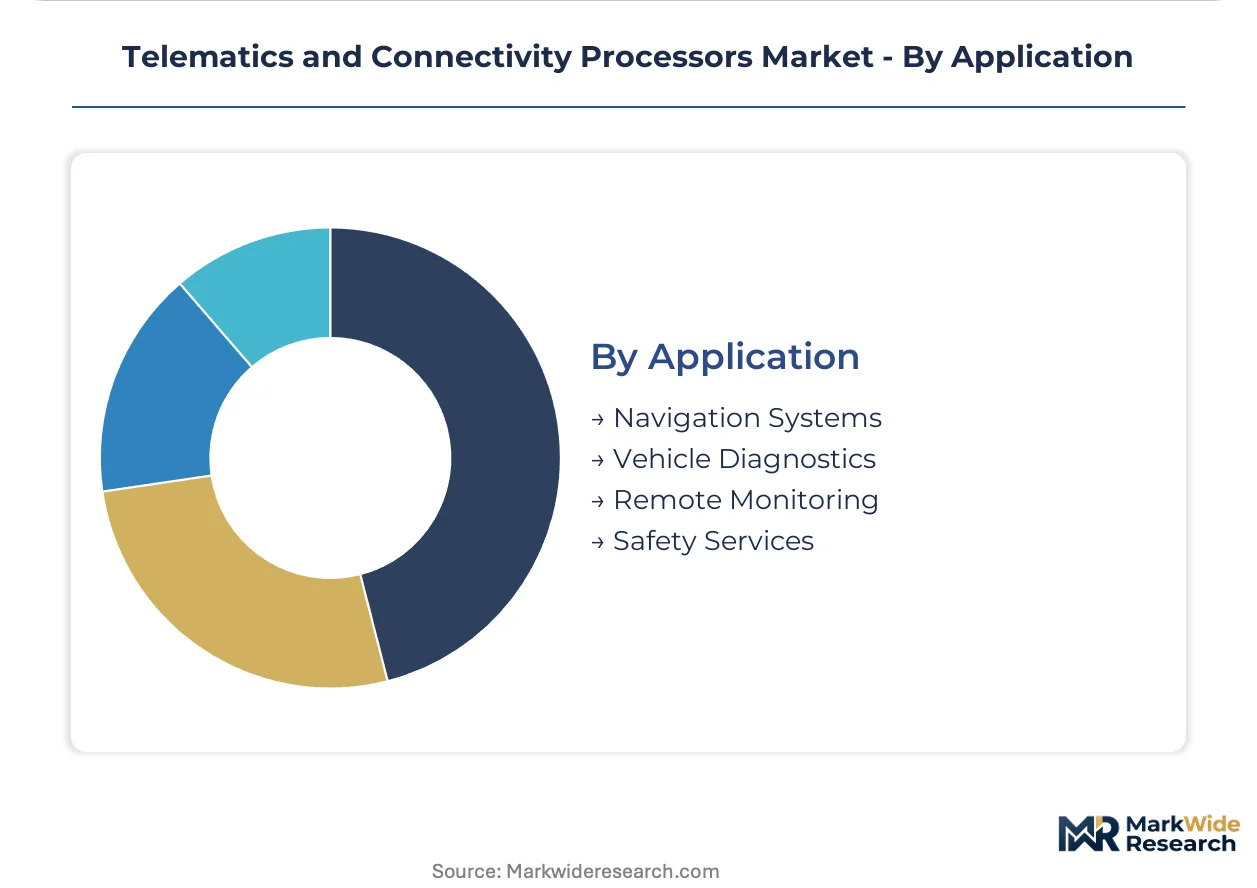
Application:
Use case prioritization reflects divergence between driver-centric features and fleet-operator efficiency tools.
- Vehicle Diagnostics:Predictive maintenance algorithms process CAN bus data to forecast component failures before roadside breakdowns occur.
- Remote Monitoring:Real-time cargo telemetry and asset tracking dominate commercial fleet procurement, displacing earlier consumer-navigation-centric patterns.
- Navigation Systems:Turn-by-turn routing and mapping services retain relevance in passenger vehicle segments.
- Safety Services:Automatic crash notification and stolen vehicle tracking satisfy regulatory mandates and insurance requirements.
Remote Monitoring leads volumes today; Vehicle Diagnostics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting telematics processor sourcing toward jurisdictions with harmonized certification regimes, compressing margins for suppliers serving fragmented multi-market demand pools.
Germany
Commercial fleet operators around Stuttgart and Ingolstadt are consolidating procurement of embedded connectivity platforms with predictive maintenance capabilities. The KBA enforces UN ECE WP.29 cybersecurity regulations for type approval, mandating hardware security modules in connected vehicle components. Bosch and Continental maintain dense R&D clusters in Baden-Württemberg and Lower Saxony, anchoring European silicon design for heavy-duty logistics applications.
United States
Long-haul logistics providers are unbundling hardware acquisition from software entitlement to preserve operational expenditure flexibility. The NHTSA and FCC jointly influence demand through vehicle safety standards and spectrum allocation for dedicated short-range communications. Michigan and Texas development corridors concentrate tier-one supplier engineering for integrated hardware-software stacks serving North American fleet operators.
China
Domestic OEMs are accelerating procurement of cellular V2X chipsets for smart city infrastructure integration. MIIT governs connected vehicle cybersecurity through GB standards and spectrum licensing for C-V2X deployment. The Yangtze River Delta manufacturing belt around Shanghai hosts captive semiconductor packaging capacity for automotive-grade telematics modules.
Japan
Commercial operators are deploying multi-access edge computing processors for autonomous convoy coordination with sub-10-millisecond latency requirements. METI coordinates V2X protocol maturation and roadside unit integration standards through public-private partnerships. The Nagoya-Chubu corridor concentrates Denso and tier-one supplier R&D spending for East Asian telematics silicon demand.
India
Regulatory mandates for commercial fleet tracking under AIS-140 standards are creating first-mover openings for localized hardware-software module suppliers. The Ministry of Road Transport and Highways enforces GPS-based vehicle location and emergency button requirements for public service vehicles. The Delhi-NCR and Maharashtra industrial corridors are absorbing certification costs through selective supplier consolidation favoring vertically capable semiconductor houses.
Telematics and Connectivity Processors Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to bridge capability gaps in functional safety engineering and multi-regime compliance. The vendor base stratifies across three tiers: integrated automotive electronics conglomerates with captive silicon design, specialized telematics module fabricators with regional certification expertise, and semiconductor houses supplying discrete components to tier-one integrators. Principal competitive moves include technology licensing for V2X protocol stacks and geographic expansion into India's AIS-140 compliance market.
Within the integrated tier, Continental AG and Robert Bosch GmbH exemplify European automotive electronics conglomerates with captive telematics processor development. Qualcomm Technologies occupies a position among semiconductor houses supplying cellular modem leadership for premium connected commercial vehicle platforms. These anchors represent divergent strategic postures: hardware-software integration versus discrete component supply.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| LG Electronics |
| Harman International |
| Denso Corporation |
| Valeo |
| Qualcomm Technologies |
| ZF Friedrichshafen AG |
| TomTom |
| Others |
Value Network & Pricing Analysis
Silicon wafer spot indices and automotive-grade packaging material costs cascade through three distinct pricing tiers for telematics processors, compressing margins for unqualified suppliers while concentrating procurement power among vertically integrated tier-one integrators serving German OEM clusters.
Pricing Analysis
Distributor margins of 12-18 percent on discrete components compress to 4-7 percent for direct-to-OEM volume contracts, creating a bifurcated pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified modules from commercial-grade alternatives and aftermarket retrofit units. Pricing pressure stems from foundry capacity allocation volatility at 7nm and 5nm nodes, forcing cost compression in the standard tier. Fleet management operators exhibit highest price sensitivity due to hardware refresh cycle elongation, while OEM embedded programs show lowest sensitivity given type approval lock-in effects.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart and Ingolstadt automotive clusters, while tier-two distributors serve fragmented aftermarket retrofit demand. Taiwan, South Korea, and the United States concentrate advanced node foundry supply for cellular modem integration. Raw material dependencies include silicon wafers, AEC-Q100 qualified packaging substrates, and RoHS-compliant thermal interface materials. Single-source vulnerability at leading-edge foundries exposes buyers to allocation rationing during capacity crunches. Distribution runs through authorized tier-one integrators with captive regulatory certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telematics processor market reads as a late-cycle quality story where procurement consolidation around predictive maintenance platforms rewards suppliers with functional safety certification depth and multi-regime compliance capabilities.
For Market Incumbents: Cement hardware-software integration advantages through captive V2X protocol stack development and ASIL-D certification investment. Defensive consolidation should prioritize backward integration into secure boot architecture IP to offset silicon carbide power electronics substitution threats. Capacity addition in India around Delhi-NCR industrial corridors captures AIS-140 regulatory mandate timing before localized competitors achieve qualification scale. For New Entrants and Emerging Players: Tier-two commercial fleet operators in North American long-haul logistics represent the most penetrable buyer segment given their operational expenditure flexibility and software-entitlement preference. White-space targets include subscription-based cybersecurity stacks and MEC-enabled edge computing modules for autonomous convoy applications. A channel partnership strategy with aftermarket distributors serving mixed fleet retrofits bypasses OEM type approval barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized telematics module fabricators possessing regional certification expertise in India's AIS-140 compliance market. Long-term viability over a 5-10 year window favors suppliers with demonstrated UN ECE WP.29 and FCC dual-certification track records. Monitor cellular V2X roadside unit deployment velocity in European smart city infrastructure as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Integration | EU Cyber Resilience Act mandates hardware-level encryption for type approval eligibility. |
| Cellular V2X Protocol Licensing | Roadside unit integration projects in Germany and Japan require production-ready direct communication standards. |
| India Manufacturing Localization | AIS-140 fleet tracking mandates create first-mover certification advantages for vertically capable suppliers. |
| Software-Defined Vehicle Platform Investment | Over-the-air update architectures decouple hardware refresh from feature delivery, enabling recurring revenue models. |
| Multi-Access Edge Computing Partnership | Sub-10-millisecond latency requirements for autonomous convoy coordination elevate silicon content at network edge. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and commercial fleet operations managers were validated against secondary sources including UN ECE WP.29 regulatory filings, FCC spectrum allocation dockets, AIS-140 compliance databases, and automotive production registration data. Triangulation between demand-side procurement patterns and supply-side fabrication constraints ensures segmentation integrity.
Input-output matrices map processor content per vehicle across propulsion architectures, vehicle classes, and regional production clusters. Segmentation dimensions include product type, end user archetype, communication protocol technology, and application use case. CAGRs were derived from regression analysis of historical procurement volumes against regulatory mandate timelines and foundry capacity expansion schedules. Forecast inputs incorporate AEC-Q100 qualification timeline assumptions and V2X protocol maturation curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to foundry node transition timing and divergence between EU cybersecurity mandates and US spectrum policy. Forecasts reflect documented assumptions regarding fleet electrification penetration and software-defined vehicle architecture adoption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Commercial Telematics Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
In-Car Infotainment Market