
 Indonesia Box Truck Market | 2026-2036
Indonesia Box Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Box Truck Market Foresight
Multi-source component procurement is broadening across Indonesian box truck assembly operations as manufacturers reduce dependency on single-source drivetrain suppliers. Isuzu Motor Co. Ltd leverages its established ASEAN manufacturing footprint to anchor fleet contracts with domestic logistics providers. Mitsubishi Fuso Truck and Bus Corporation sustains competitive positioning through localized assembly partnerships. Hino Motors, Ltd. differentiates via service network density across the archipelago's secondary ports.
Indonesia box trucks are enclosed-cab commercial vehicles with fixed cargo compartments typically rated between 3.5 and 12 tonnes gross vehicle weight, engineered for weather-protected freight movement across tropical climates with high humidity and monsoon exposure. Their primary purpose is last-mile and inter-city distribution of packaged consumer goods, construction materials, and temperature-sensitive cargo across Indonesia's fragmented island geography. Light-Duty units dominate urban e-commerce fulfillment where narrow street access limits vehicle dimensions, while Medium-Duty configurations capture margin pools in regional distribution linking Java's manufacturing zones to outer island depots. Heavy-Duty segments serve long-haul routes across Sumatra and Sulawesi where load consolidation drives per-kilometer economics.
BIS-equivalent national standards and Ministry of Transportation type-approval protocols govern vehicle safety, emissions compliance, and axle load limits for commercial freight registration across Indonesia's 34 provinces. The Ministry of Environment and Forestry coordinates with transport regulators to phase Euro 4-equivalent emission thresholds, compelling fleet operators to accelerate replacement cycles for older diesel units. Stakeholders must monitor enforcement consistency between Java's major ports and outer island registration authorities where compliance gaps persist.
Market Dynamics
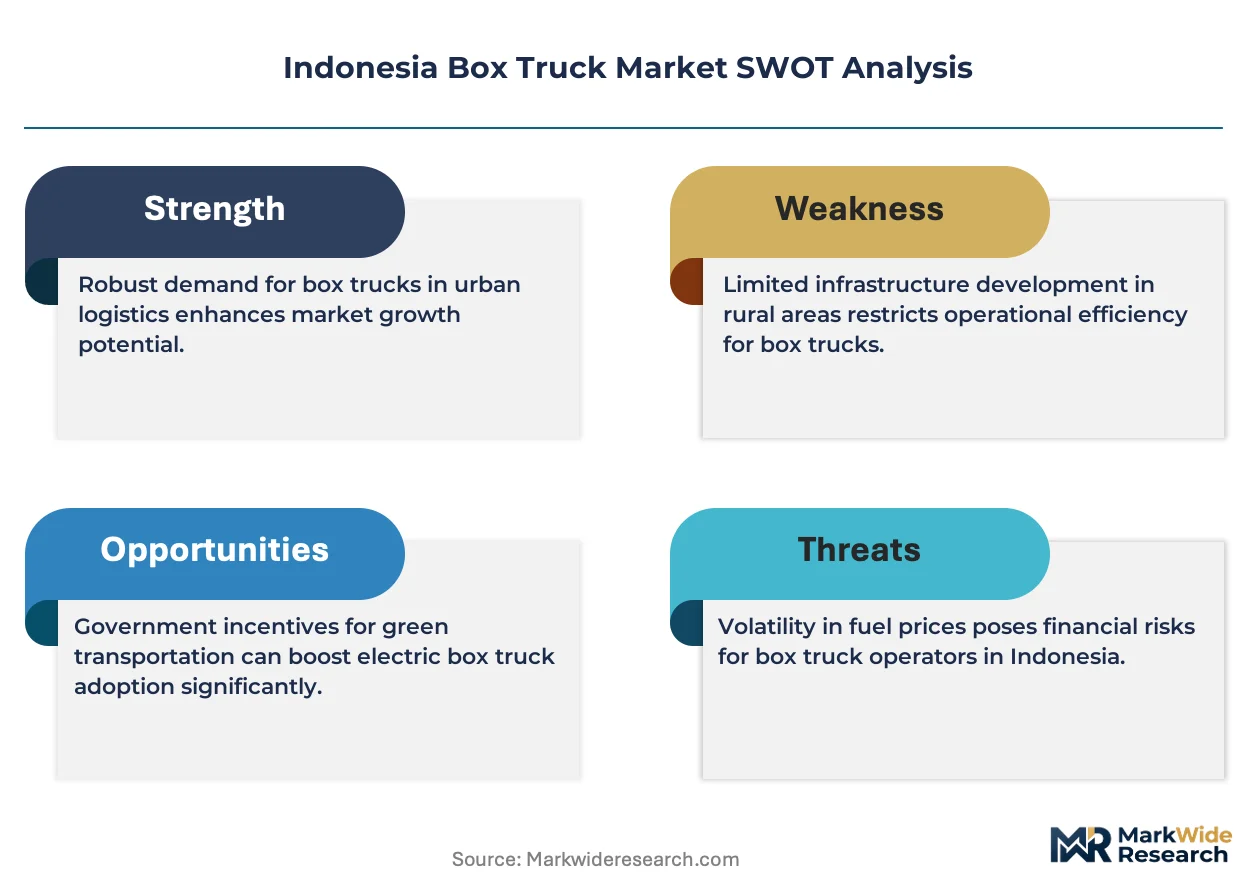
Euro 4-equivalent emission mandates from Indonesia's Ministry of Environment and Forestry are compressing replacement cycles for aging diesel fleets while tightening compliance costs for logistics operators across Java's distribution corridors.
Growth Catalysts
- E-commerce logistics expansion:Jakarta and Surabaya fulfillment networks are scaling last-mile capacity to serve archipelago-wide consumer goods flow, driving fleet renewal programs among domestic operators.
- BIS-equivalent safety standards:National vehicle type-approval protocols are mandating load integrity systems and axle limit enforcement, creating upgrade demand for compliant chassis configurations.
- Archipelago distribution infrastructure:Inter-island ferry integration and secondary port development are extending box truck operational range beyond Java into Sumatra and Sulawesi corridors.
Market Restraints
- Drivetrain supply concentration:Heavy reliance on Japanese engine imports creates vulnerability to yen volatility and ASEAN trade route disruptions.
- Euro 4 compliance cost escalation:Aftertreatment system integration adds procurement burden for small fleet operators in outer island provinces.
- Used vehicle substitution:Pre-2015 diesel trucks circulating in secondary markets undercut new unit pricing in cost-sensitive segments.
Strategic Opportunities
- Outer island depot networks:Kalimantan and Papua distribution hubs remain underserved by modern fleet capacity, offering first-mover positioning for regional logistics integrators.
- Temperature-controlled cargo specialization:Cold chain pharmaceutical and fresh produce segments are expanding refrigerated box truck specifications beyond standard dry freight.
- Domestic assembly localization:Ministry of Industry incentives for component sourcing are enabling captive production of axles and braking systems.
Industry Challenges
- Technician certification gaps:Euro 4 aftertreatment diagnostics and electronic engine management require training infrastructure that remains concentrated in Java.
- Enforcement inconsistency:Registration authority interpretation of BIS-equivalent standards varies between major ports and outer island jurisdictions, complicating fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Box Truck Market |
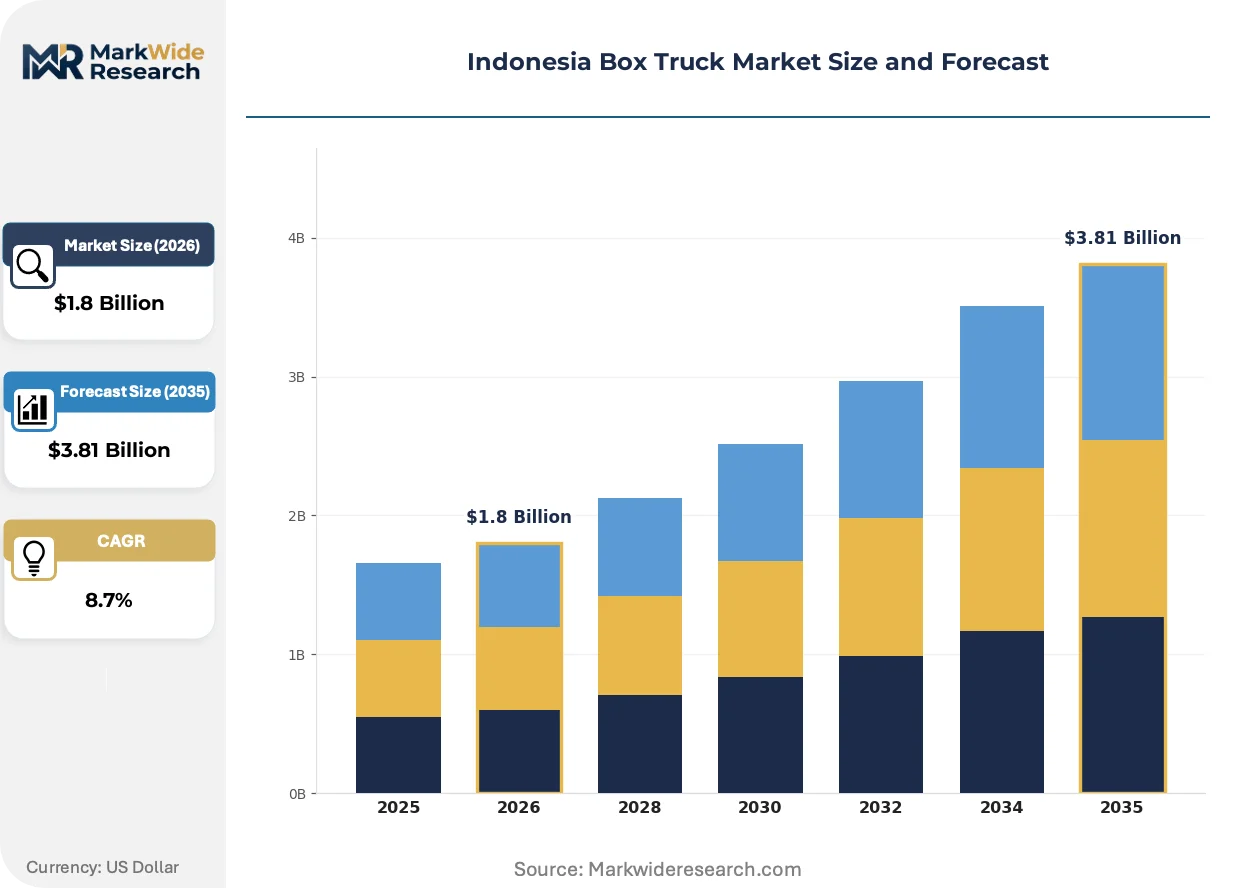
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Duty, Medium-Duty, Heavy-Duty, Super-Duty End User: Retail, Construction, Logistics, Automotive Fuel Type: Diesel, Gasoline, CNG, Hybrid Application: City Delivery, Long Haul, E-Commerce, Perishable Goods |
| Companies Covered | Ford Motor Company, Mercedes-Benz Group AG, Isuzu Motor Co. Ltd, Daimler Commercial Vehicles Indonesia, General Motors, Mitsubishi Fuso Truck and Bus Corporation, IVECO GROUP Company, Fiat Chrysler Automobiles, Hino Motors, Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Box Truck Market Shifts & Advancements
Telematics integration and alternative fuel trials are redefining fleet management economics while regulatory pressure accelerates hardware refresh cycles across Indonesian logistics networks.
Telematics-enabled predictive maintenance is absorbing operational data from engine control modules and brake wear sensors to compress unplanned downtime for medium-duty distribution fleets. Third-party logistics providers in Surabaya are adopting these systems fastest, using real-time diagnostics to schedule service intervals around delivery windows rather than fixed calendar periods. The technology is absorbing traditional break-fix maintenance contracts into subscription-based fleet management services.
Indonesia's Ministry of Environment and Forestry is coordinating Euro 4-equivalent emission thresholds with the Ministry of Transportation's vehicle registration protocols. Engine manufacturers must now secure dual certification for type-approval and environmental compliance before commercial deployment. Medium-duty segments serving regional distribution routes face the steepest retrofit burden as these units accumulated the highest pre-2015 fleet penetration.
Consolidated fleet procurement is displacing fragmented owner-operator purchasing across Java-based e-commerce logistics networks. Large fulfillment operators are negotiating multi-year chassis supply agreements directly with assembly plants, bypassing traditional dealer intermediaries. This concentration is most visible in Jakarta's same-day delivery corridors where scale economics favor standardized vehicle specifications over customized configurations.
Indonesia Box Truck Market Segmentation
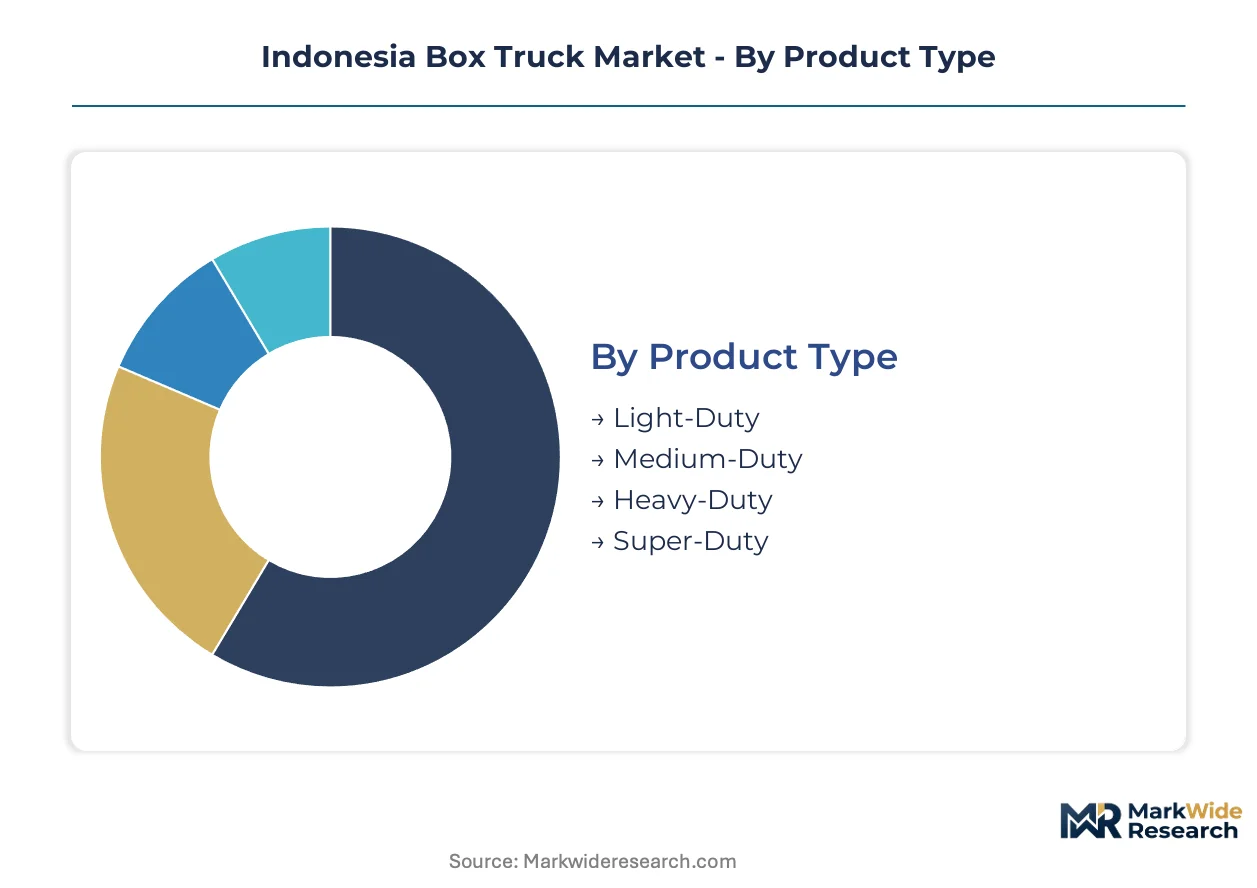
Segmentation in Indonesia's box truck market reveals how capital deployment, regulatory exposure, and operational intensity vary across fleet specifications. Procurement patterns diverge sharply between urban last-mile operators and inter-island heavy haulers, with each segment carrying distinct compliance burdens and financing structures.
Product Type:
Capital intensity escalates dramatically with gross vehicle weight ratings, as heavier configurations demand reinforced chassis engineering and more sophisticated aftertreatment systems to satisfy Euro 4-equivalent mandates.
- Light-Duty:Units rated below 3.5 tonnes GVW dominate Jakarta and Surabaya e-commerce corridors where narrow street geometry restricts vehicle dimensions. Fleet operators in these same-day delivery networks prioritize maneuverability over payload capacity, absorbing units through operating lease structures that transfer residual value risk to lessors.
- Medium-Duty:Configurations between 3.5 and 12 tonnes capture regional distribution linking Java manufacturing zones to outer island ferry ports. These units face the steepest replacement pressure from pre-2015 diesel fleets, driving consolidation toward telematics-enabled models that compress maintenance intervals around delivery windows.
- Heavy-Duty:Long-haul specifications serving Sumatra and Sulawesi corridors require load consolidation economics to justify higher upfront acquisition costs.
- Super-Duty:Specialized mining and plantation logistics applications in Kalimantan and Papua demand extreme durability ratings under tropical humidity exposure.
Medium-Duty absorbs the bulk of installed capacity; Light-Duty is expanding most quickly.
End User:
Customer procurement sophistication separates price-tolerant owner-operators from volume-negotiating enterprise fleets, with logistics integrators capturing disproportionate influence over manufacturer specifications.
- Logistics:Third-party providers and dedicated fleet operators across Java's distribution corridors negotiate multi-year chassis supply agreements directly with assembly plants, bypassing traditional dealer intermediaries. Their consolidated purchasing power is standardizing vehicle configurations around telematics integration and predictive maintenance subscriptions.
- Retail:Modern trade and fast-moving consumer goods distributors in Jakarta's fulfillment networks specify refrigerated box configurations for temperature-sensitive cargo, expanding beyond dry freight specifications as cold chain infrastructure matures.
- Construction:Building material haulers face cyclical demand tied to Ministry of Public Works infrastructure spending across outer island provinces.
- Automotive:Vehicle component and finished goods transporters serving Bekasi and Karawang manufacturing clusters require just-in-time delivery precision.
Logistics commands the dominant share of new unit procurement; Retail is climbing the fastest as cold chain pharmaceutical and fresh produce segments expand refrigerated specifications.
Fuel Type:
Compliance cost trajectories diverge sharply across powertrain technologies, with emission aftertreatment integration creating procurement friction for smaller operators in outer island provinces.
- Diesel:Compression-ignition engines remain the incumbent technology across all duty ratings, though Euro 4-equivalent aftertreatment systems add procurement burden. Ministry of Environment and Forestry phase-in timelines are compressing replacement cycles for pre-2015 units circulating in secondary markets.
- CNG:Compressed natural gas trials are gaining traction among municipal fleet operators in Surabaya and Bandung where refueling infrastructure concentrates, offering lower per-kilometer fuel economics despite higher upfront vehicle premiums.
- Gasoline:Spark-ignition variants serve limited light-duty applications where acquisition cost sensitivity outweighs fuel efficiency considerations.
- Hybrid:Parallel hybrid configurations remain experimental, with pilot deployments concentrated in Jakarta's urban access zones where stop-start traffic patterns maximize regenerative braking recovery.
Diesel retains overwhelming fleet penetration; CNG is gaining share fastest where municipal infrastructure investment precedes national network rollout.
Application:
Route characteristics and cargo protection requirements dictate chassis specification, with urban access constraints and inter-island ferry logistics creating distinct operational profiles.
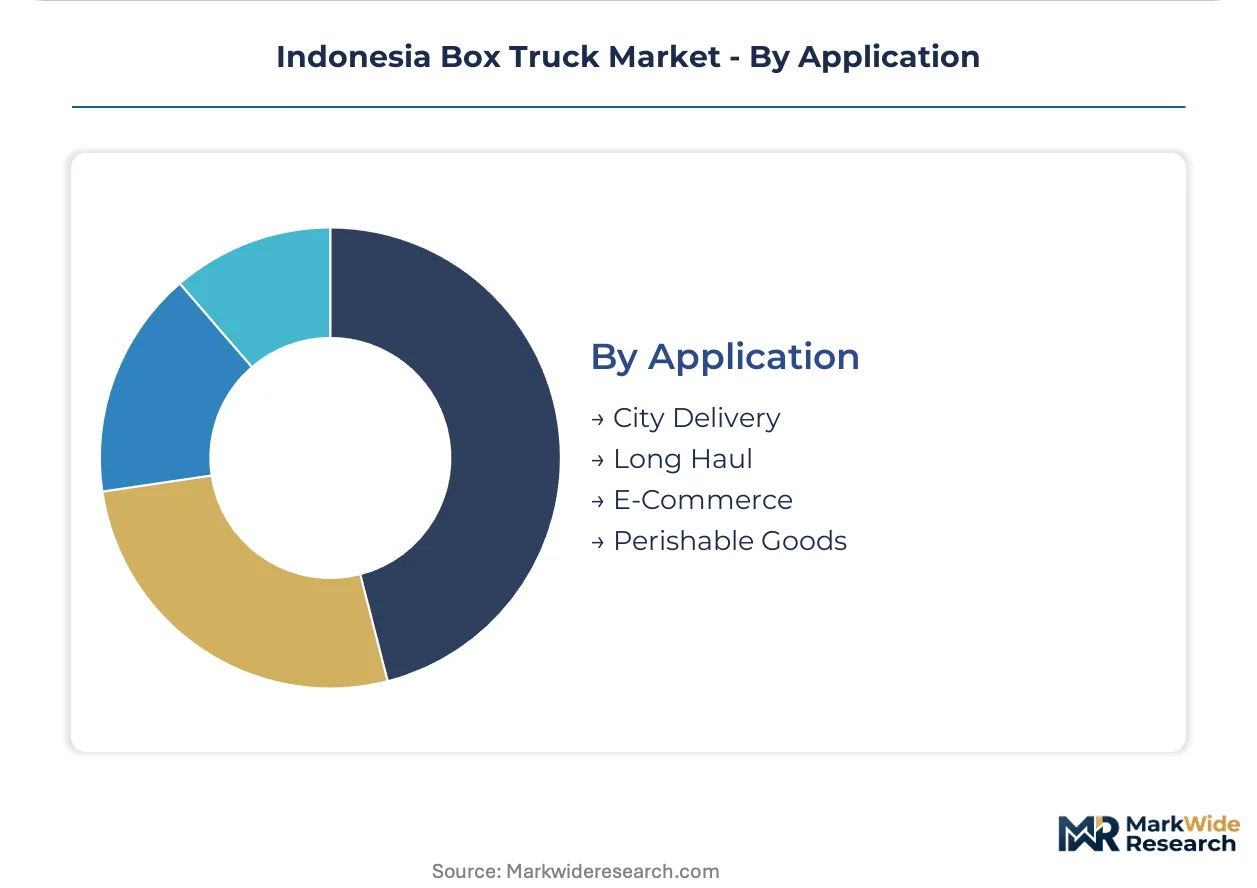
- E-Commerce:Same-day and next-day fulfillment networks in Jakarta, Surabaya, and Medan are scaling last-mile capacity to serve archipelago-wide consumer goods flow. These operations prioritize light-duty configurations with telematics integration for real-time delivery tracking and customer notification systems.
- City Delivery:General freight distribution within urban centers faces narrowing street access and escalating congestion charges in Jakarta's central business district, favoring compact cab designs and tight turning radius specifications.
- Long Haul:Inter-island routes across Sumatra and Sulawesi demand heavy-duty durability ratings and sleeper cab configurations for driver rotation compliance.
- Perishable Goods:Temperature-controlled pharmaceutical and fresh produce segments are expanding refrigerated box truck specifications, with cold chain integrity requirements exceeding standard dry freight cargo protection.
E-Commerce absorbs the dominant share of fleet expansion investment; Perishable Goods is expanding most steeply as pharmaceutical distribution networks extend beyond Java.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java's steel fabrication clusters and Surabaya's port infrastructure anchor Indonesia's box truck manufacturing base, with component supply chains radiating across the archipelago's distribution corridors.
Java
Jakarta and Surabaya fulfillment networks are scaling last-mile capacity to serve archipelago-wide consumer goods flow, absorbing light-duty and medium-duty fleet orders. The Ministry of Transportation's BIS-equivalent type-approval protocols mandate load integrity systems and axle limit enforcement, compressing replacement cycles for pre-2015 diesel units. Bekasi and Karawang manufacturing clusters concentrate chassis assembly operations serving domestic logistics providers.
Sumatra
Inter-island ferry integration and secondary port development are extending box truck operational range beyond Java into Sumatra distribution corridors, driving heavy-duty specifications for load consolidation economics. The Ministry of Environment and Forestry coordinates Euro 4-equivalent emission thresholds with provincial registration authorities, though enforcement consistency gaps persist in outer island jurisdictions. Medan anchors northern Sumatra's freight consolidation points for palm oil and rubber exports.
Sulawesi
Regional distribution linking manufacturing zones to outer island depots is capturing medium-duty configurations with telematics-enabled predictive maintenance. National vehicle safety standards tighten around emissions compliance, compelling fleet operators to accelerate hardware refresh cycles. Makassar's port infrastructure serves as the primary logistics hub for eastern Indonesia consumer goods distribution.
Kalimantan
Mining and plantation logistics applications demand extreme durability ratings under tropical humidity exposure, absorbing super-duty box truck specifications. Ministry of Industry incentives for component sourcing are enabling captive production of axles and braking systems for domestic assembly. Balikpapan and Samarinda concentrate heavy fleet deployment serving extractive industry supply chains.
Papua
Distribution hubs remain underserved by modern fleet capacity, offering first-mover positioning for regional logistics integrators targeting temperature-controlled cargo specialization. Euro 4 aftertreatment diagnostics and electronic engine management require training infrastructure that remains concentrated in Java, creating technician certification gaps. Jayapura's limited port infrastructure constrains large-scale fleet deployment despite expanding consumer goods demand.
Indonesia Box Truck Market Competitive Landscape
Global majors compete with regional champions across manufacturing footprint and service network density, creating a tiered structure where scale economics separate consolidated fleet suppliers from fragmented dealer channels. Japanese manufacturers anchor medium-duty and heavy-duty segments through localized assembly partnerships, while European brands occupy premium positioning in specialized applications. Two strategic archetypes dominate: integrated chassis-body fabricators with captive component supply, and assembly operations reliant on multi-source drivetrain procurement. Competitive moves concentrate on direct fleet procurement agreements bypassing traditional intermediaries, and telematics integration absorbing maintenance contracts into subscription services.
Within the Japanese manufacturing tier, Isuzu Motor Co. Ltd, Mitsubishi Fuso Truck and Bus Corporation, and Hino Motors, Ltd. exemplify the integrated service network archetype, each representing distinct approaches to archipelago coverage. Isuzu leverages established ASEAN manufacturing footprint to anchor fleet contracts, while Mitsubishi Fuso sustains positioning through localized assembly partnerships. Hino differentiates via service network density across secondary ports. These three occupy the core competitive terrain where domestic logistics providers consolidate procurement power.
| Leading Market Players |
|---|
| Ford Motor Company |
| Mercedes-Benz Group AG |
| Isuzu Motor Co. Ltd |
| Daimler Commercial Vehicles Indonesia |
| General Motors |
| Mitsubishi Fuso Truck and Bus Corporation |
| IVECO GROUP Company |
| Fiat Chrysler Automobiles |
| Hino Motors, Ltd. |
| Others |
Supply & Pricing Matrix
Steel chassis fabrication costs originating in Bekasi and Karawang manufacturing clusters cascade through three distinct pricing tiers as they absorb Euro 4 aftertreatment system premiums and telematics bundling. Japanese drivetrain import exposure to yen volatility compresses margins for unbundled service offerings while fleet operators with direct assembly plant contracts capture scale discounts unavailable to fragmented owner-operators.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium fleet supply agreements from economy-tier dealer transactions. Three-tier pricing structure across premium, standard, and economy levels reflects telematics integration depth and aftertreatment warranty duration. Pricing pressure stems from used pre-2015 diesel trucks circulating in secondary markets, undercutting new unit positioning. Small fleet operators in outer island provinces exhibit highest price sensitivity, while consolidated e-commerce logistics integrators absorb premium specifications with least friction.
Supply Chain Analysis
Dual-sourcing requirements for engine control modules and axle assemblies are mandating multi-supplier qualification across Japanese and domestic component manufacturers. Supply concentration rests on Japan for precision drivetrain components, Thailand for ASEAN-sourced transmissions, and Indonesia for steel fabrication and braking systems. Critical dependencies include high-strength steel plate, electronic fuel injection systems, and selective catalytic reduction substrates. Single-source vulnerability in yen-denominated engine imports creates tariff exposure and currency hedge requirements. Distribution runs through Bekasi assembly plants to Java-based fleet operators, with secondary port dealers serving outer island markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's box truck market sits at a technology-transition inflection as Euro 4-equivalent emission mandates displace legacy diesel fleets. Telematics-enabled predictive maintenance is absorbing traditional break-fix service contracts into subscription-based fleet management offerings.
For Market Incumbents: Anchor service network density across secondary ports as the primary defensive moat against emerging domestic assembly challengers. Deepen captive production of axles and braking systems through Ministry of Industry localization incentives. Accelerate technician certification infrastructure for Euro 4 aftertreatment diagnostics to close the Java-outer island capability gap.
For New Entrants and Emerging Players: Begin with refrigerated box truck specifications targeting pharmaceutical cold chain expansion beyond Java. Papua and Kalimantan distribution hubs remain underserved by modern fleet capacity, offering first-mover positioning for regional logistics integrators. Pursue direct fleet procurement agreements with mid-sized e-commerce fulfillment operators bypassing established dealer networks.
For Investors and Strategic Acquirers: Consolidated fleet procurement displacing fragmented owner-operator purchasing is the leading indicator that scale economics will concentrate procurement power among three to four dominant logistics integrators. Long-term viability favors assembly operations with captive component supply and telematics platform integration. Monitor enforcement consistency gaps between Java's major ports and outer island registration authorities as the signal for regulatory arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Absorbs maintenance contracts into subscription services for Surabaya-based third-party logistics providers. |
| Domestic Assembly Localization | Captures Ministry of Industry incentives for axle and braking system production in Bekasi clusters. |
| Refrigerated Specification Expansion | Targets pharmaceutical and fresh produce cold chain growth beyond Java's distribution corridors. |
| Secondary Port Service Network Buildout | Closes technician certification gaps for Euro 4 diagnostics in Sulawesi and Papua markets. |
| Direct Fleet Procurement Agreements | Bypasses dealer intermediaries for Jakarta same-day delivery corridor scale economics. |
Research Methodology
Multi-period observation of fleet replacement cycles, emission compliance timelines, and chassis assembly capacity anchored the trend analysis, supplemented by interviews with logistics fleet managers, Ministry of Transportation type-approval officers, assembly plant procurement directors, and aftermarket service heads. Secondary validation drew from customs import records for Japanese drivetrain components, Ministry of Environment and Forestry regulatory filings, and vehicle registration databases across Indonesia's 34 provinces. Bottom-up unit deployment estimates triangulated against top-down manufacturing capacity assessments.
Segment-weighting across product type, end user, fuel technology, and application dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from installed base turnover rates, replacement cycle compression from Euro 4 mandates, and e-commerce logistics capital deployment trajectories. Forecast inputs incorporated ferry integration timelines for inter-island route expansion and cold chain infrastructure investment patterns.
Underlying measurement precision varies by segment; Java-based fleet deployment data carries tighter precision than outer island estimates where registration authority reporting lags. Forecasts reflect assumptions around enforcement consistency for BIS-equivalent standards and yen exchange rate stability for drivetrain imports. Deviation in Ministry of Environment and Forestry emission mandate phase-in timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Utility Vehicle Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market