
 Truck-As-A-Service Market | 2026-2036
Truck-As-A-Service Market Size, Share, and Industry Trends Forecast 2026-2036
Truck-As-A-Service Market Outlook
Multi-source fleet procurement is realigning how logistics operators balance asset ownership against operational flexibility. Daimler Truck AG leverages its integrated service platform to bundle leasing with predictive maintenance contracts. AB Volvo anchors its European presence through subscription models targeting regional freight networks. Einride AB differentiates by specializing in autonomous-capable electric truck subscriptions for closed-loop industrial routes.
Truck-As-A-Service denotes a commercial model where fleet operators access vehicle capacity through contractual arrangements rather than direct purchase, typically encompassing telematics-enabled performance monitoring and bundled maintenance obligations. The primary purpose is to convert fixed capital expenditures into variable operating costs while ensuring regulatory compliance across emission and safety standards. Lease and subscription structures capture the dominant share of contracted value, though pay-per-use arrangements are expanding fastest among last-mile delivery networks seeking demand-responsive capacity. Electric trucks within the vehicle type category concentrate investment attention as battery-electric drivetrains approach total cost parity with diesel alternatives in urban freight cycles.
The European Union's Green Deal framework and CO2 emission standards for heavy-duty vehicles mandate progressive fleet decarbonization, directly expanding addressable demand for electric Truck-As-A-Service offerings. Germany's KBA enforces type-approval protocols that shape vehicle eligibility for national subsidy programs tied to leased electric commercial vehicles. In the United States, EPA Phase 3 greenhouse gas standards and the IRA's commercial clean vehicle tax credits alter total-cost calculations favoring outsourced electric fleet transitions. Fleet managers and service providers must monitor regulatory calibration timelines to align contract structures with evolving compliance thresholds and incentive windows.
Market Dynamics
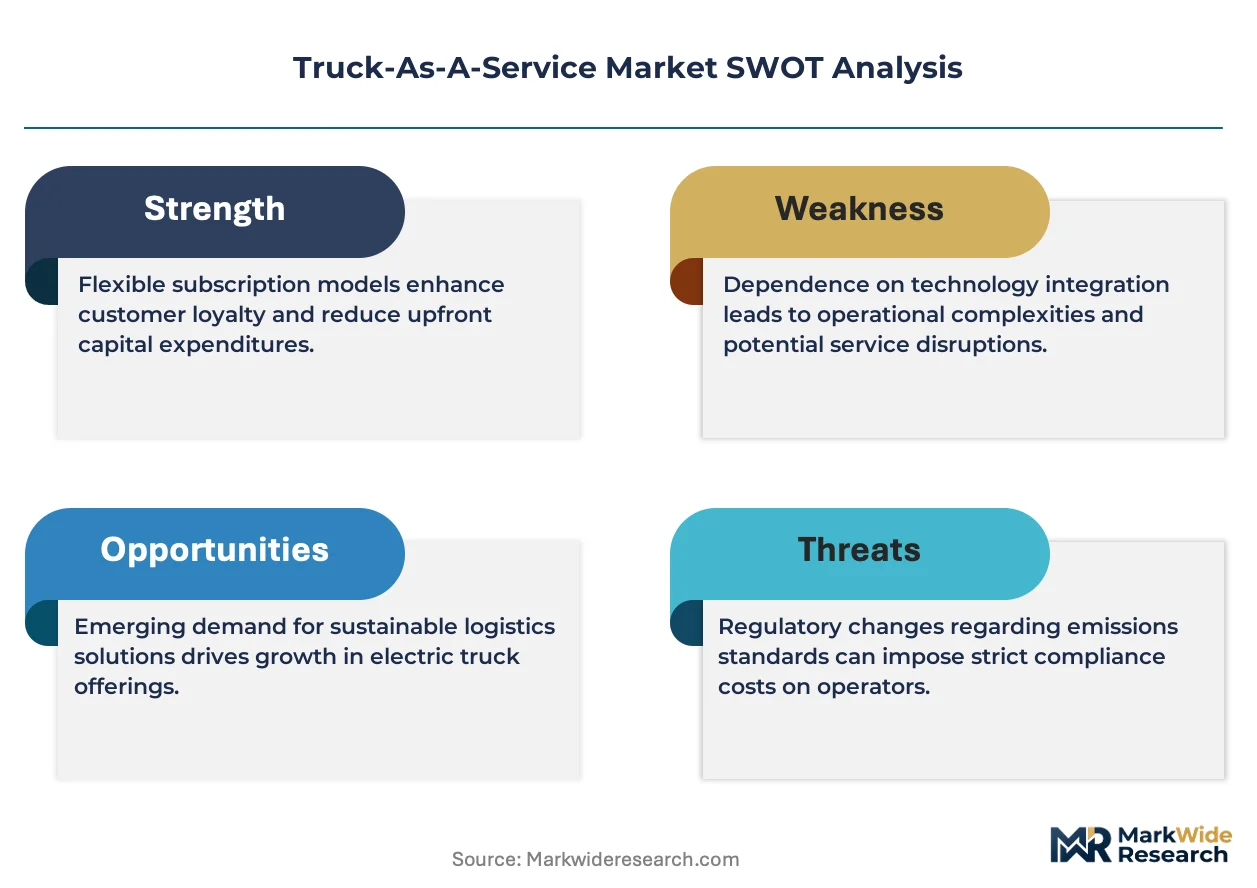
EU Green Deal CO2 emission standards for heavy-duty vehicles are forcing freight operators to convert capital-intensive diesel fleets into variable-cost electric subscriptions, compressing ownership tenures and expanding addressable demand for bundled service contracts.
Growth Catalysts
- EU Green Deal mandates:Progressive CO2 emission standards for heavy-duty vehicles create compliance-driven demand for electric Truck-As-A-Service offerings, particularly in Germany where KBA type-approval protocols unlock national subsidy programs for leased commercial vehicles.
- E-commerce logistics expansion:Last-mile delivery networks are outsourcing fleet capacity to reduce capital exposure, accelerating pay-per-use arrangements that match vehicle availability to demand volatility in urban freight cycles.
- Battery-electric drivetrains:Total cost parity with diesel alternatives in short-haul routes is rewriting operator calculus, concentrating investment attention on electric vehicle subscriptions over conventional leasing structures.
Market Restraints
- Charging infrastructure gaps:Depot electrification requires substantial grid upgrades, creating deployment friction for fleet operators seeking to transition from diesel without captive charging assets.
- Battery supply concentration:Cell manufacturing capacity clusters in China, exposing European Truck-As-A-Service providers to input cost volatility and geopolitical supply risk.
- Residual value uncertainty:Rapid battery technology evolution compresses secondary market confidence for electric commercial vehicles, elevating lessor risk premiums in long-dated contracts.
Strategic Opportunities
- Autonomous-capable subscriptions:Closed-loop industrial routes in mining and port logistics present white space for self-driving electric truck deployments without regulatory complexity of open-road autonomy.
- IRA commercial clean vehicle tax credits:United States incentive structures alter total-cost calculations for outsourced electric fleet transitions, expanding addressable market for subscription-based models.
- Predictive maintenance bundling:Telematics-enabled performance monitoring converges with AI-driven failure prediction, enabling outcome-based service contracts that capture lifecycle value beyond vehicle provision.
Industry Challenges
- Technician skill gaps:High-voltage electric drivetrain diagnostics require specialized certification that outpaces vocational training pipeline capacity, constraining service network expansion.
- Legacy fleet integration:Mixed diesel-electric operations complicate route optimization and driver scheduling, elevating operational coordination costs during transition periods.
- Contract structure calibration:Misalignment between regulatory incentive windows and lease tenures creates repricing risk for providers underwriting multi-year electric vehicle subscriptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck-As-A-Service Market |
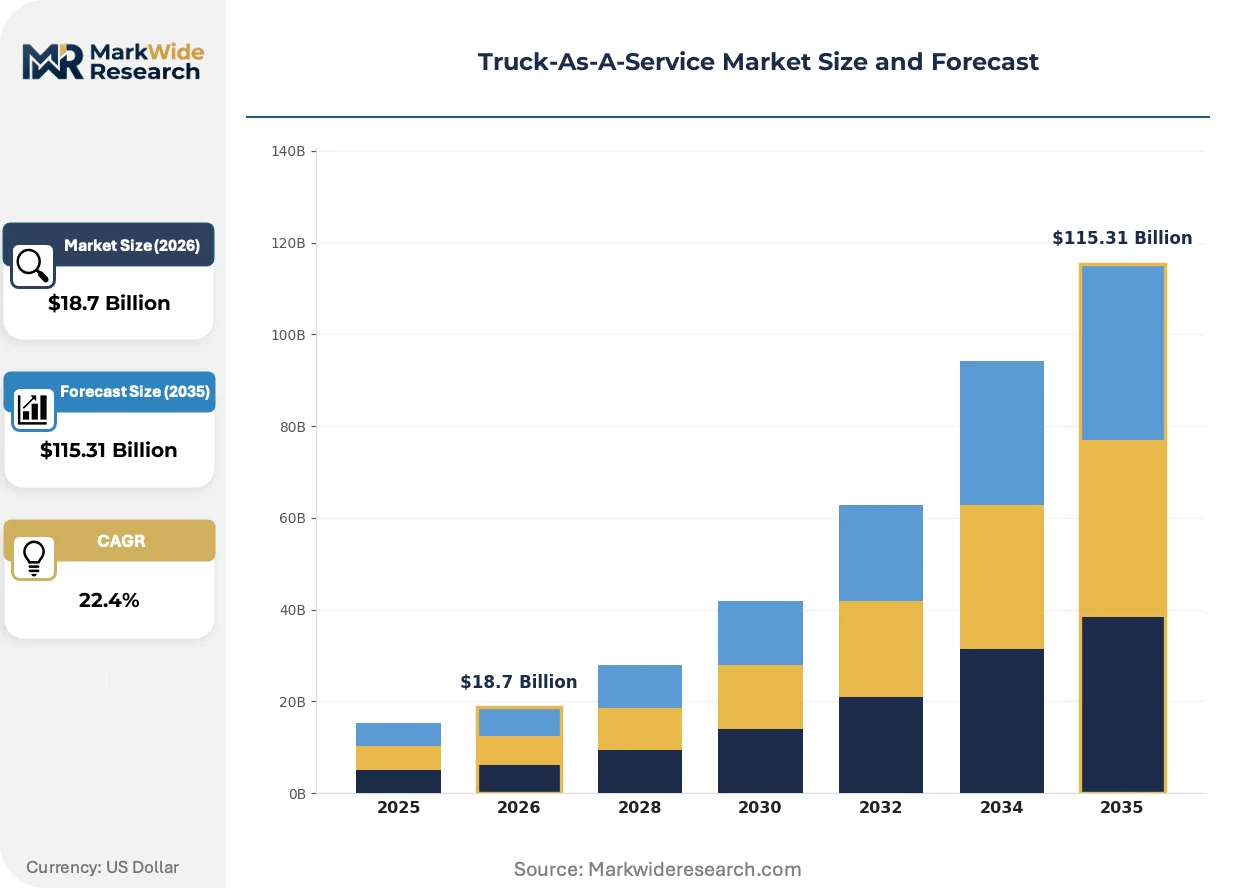
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lease, Subscription, Pay-Per-Use, Financing End User: Logistics Companies, E-Commerce Firms, Retailers, Manufacturers Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Electric Trucks, Refrigerated Trucks Technology: Telematics, Fleet Management, Route Optimization, Autonomous Vehicles |
| Companies Covered | Daimler Truck AG, AB Volvo, TRATON SE, Tata Motors Limited, Volta Trucks, Einride AB, BYD Company Limited, Trimble Transportation, Fleet Advantage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck-As-A-Service Market Strategic Shifts
Telematics-enabled performance monitoring is compressing the traditional separation between vehicle provision and operational optimization, bundling predictive maintenance with real-time route intelligence into single-contract offerings.
Battery-electric drivetrains paired with vehicle-to-grid capability are rewriting how fleet operators monetize parked assets. Large logistics providers in Germany are piloting bidirectional charging contracts that sell stored energy back to grid operators during peak demand windows. This convergence of mobility and energy storage is creating new revenue streams that subsidize subscription costs.
EPA Phase 3 greenhouse gas standards in the United States are tightening compliance pathways for heavy-duty fleets, accelerating outsourced transitions to electric capacity. The regulatory pressure is most acute for regional freight networks operating aging diesel tractors, which are responding with shorter-term subscription pilots to defer capital commitment until technology matures.
Third-party logistics providers are consolidating procurement authority previously dispersed across operating subsidiaries. Centralized fleet decisions at e-commerce fulfillment networks are displacing decentralized leasing arrangements, concentrating contract value with integrated Truck-As-A-Service platforms that bundle national coverage with uniform telematics standards. This pattern is most visible in Netherlands-based European distribution hubs seeking continental consistency.
Truck-As-A-Service Market Segmentation
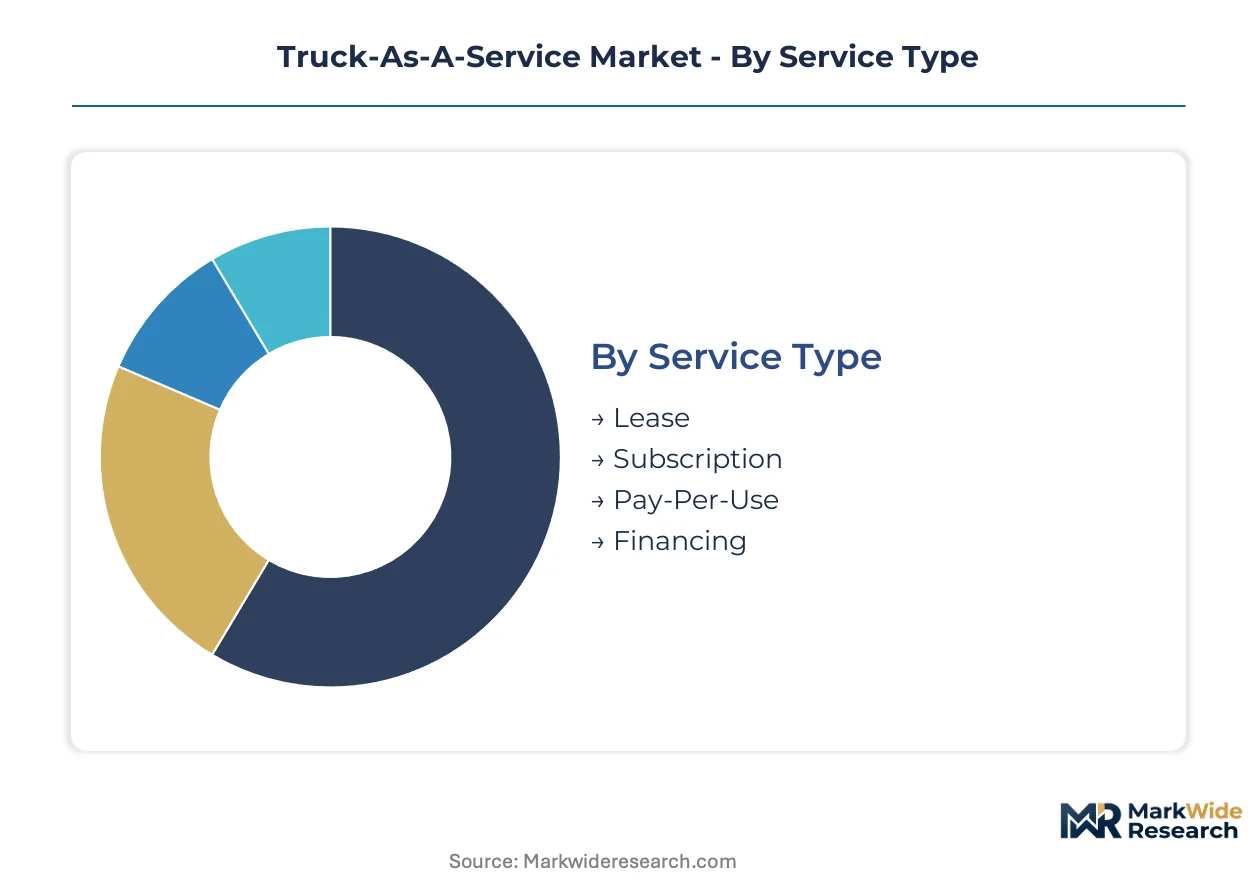
Truck-As-A-Service providers structure contracts around operational intensity, asset flexibility, and technology integration. Segment boundaries shift as battery-electric drivetrains rewrite total-cost calculations and telematics platforms bundle predictive maintenance into single-contract offerings.
Service Type:
Lease structures dominate contracted value through fixed-tenure agreements that transfer residual risk to lessors, while subscription and pay-per-use models capture volume growth from operators seeking demand-responsive capacity.
- Lease:Fixed-tenure contracts typically spanning 3-5 years bundle vehicle provision with maintenance obligations and telematics monitoring. German freight operators favor lease structures to access KBA type-approval subsidies for electric commercial vehicles while preserving balance-sheet flexibility.
- Subscription:Monthly or annual recurring contracts enable rapid fleet scaling without capital commitment. E-commerce logistics providers in urban freight cycles are expanding subscription adoption to match vehicle availability with seasonal demand volatility.
- Pay-Per-Use:Mileage or hour-based billing aligns costs directly with asset utilization. Last-mile delivery networks piloting pay-per-use arrangements include depot-based charging costs in per-kilometer rates.
- Financing:Credit structures preserve ownership pathways while deferring capital outlay. Regional freight operators use financing to bridge incentive windows and technology maturation timelines.
Today's leader: Lease. Tomorrow's challenger: Subscription.
End User:
Procurement authority concentrates at logistics companies managing multi-client fleets, while e-commerce firms drive fastest adoption of variable-cost structures for last-mile capacity.
- Logistics Companies:Third-party operators consolidate previously decentralized leasing decisions, concentrating contract value with integrated platforms offering national coverage and uniform telematics standards. Netherlands-based European distribution hubs exemplify this pattern.
- E-Commerce Firms:Direct-to-consumer fulfillment networks outsource fleet capacity to reduce capital exposure during demand volatility. These operators are expanding pay-per-use pilots that match vehicle availability to delivery volume fluctuations.
- Retailers:Grocery and general merchandise chains deploy refrigerated Truck-As-A-Service for temperature-controlled distribution. Subscription structures help retailers navigate seasonal inventory cycles without permanent fleet expansion.
- Manufacturers:Industrial shippers favor closed-loop route contracts for plant-to-warehouse movements. Mining and port logistics present white space for autonomous-capable electric truck subscriptions.
Logistics companies anchor current demand. E-commerce firms are climbing the fastest.
Vehicle Type:
Heavy-duty configurations generate premium contract value, while electric trucks concentrate investment attention as battery-electric drivetrains approach total cost parity with diesel alternatives in short-haul cycles.
- Light-Duty Trucks:Urban delivery vehicles under 3.5 tonnes gross vehicle weight dominate last-mile subscription volumes. These configurations integrate most readily with existing depot charging infrastructure.
- Heavy-Duty Trucks:Tractor-trailer combinations for regional and long-haul freight command higher per-vehicle contract values. EU Green Deal CO2 standards are compressing diesel ownership tenures in this category.
- Electric Trucks:Battery-electric drivetrains with vehicle-to-grid capability enable bidirectional charging contracts that monetize parked assets. German operators pilot energy resale agreements that subsidize subscription costs.
- Refrigerated Trucks:Temperature-controlled units with electric transport refrigeration units face infrastructure constraints for charging during multi-drop routes. Cold chain operators seek bundled service contracts covering both vehicle and refrigeration system maintenance.
Heavy-duty trucks dominate contract value. Electric trucks show the steepest expansion trajectory.
Technology:
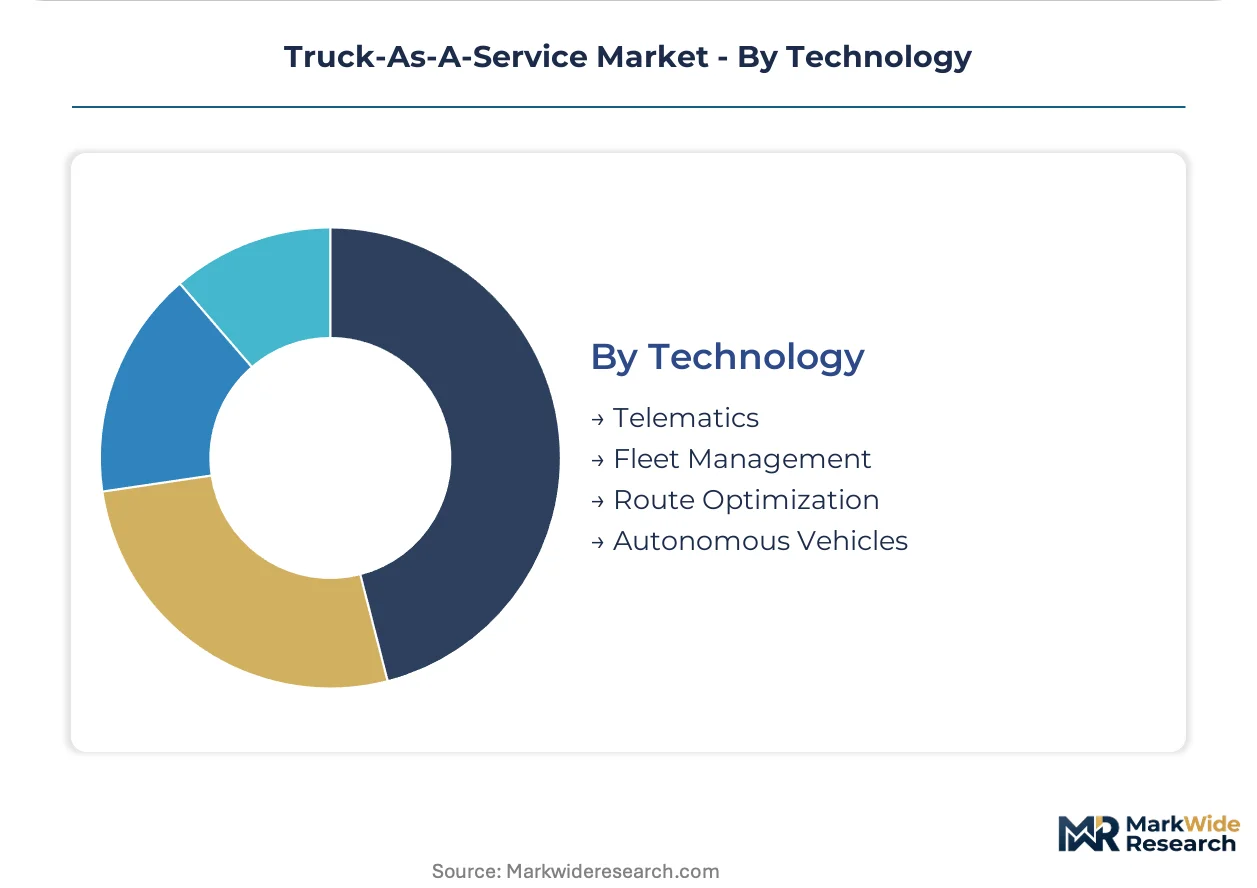
Telematics platforms form the foundational layer enabling predictive maintenance bundling, while autonomous vehicle capabilities differentiate offerings for closed-loop industrial applications.
- Telematics:GPS tracking combined with engine and battery performance monitoring enables real-time fleet visibility. These systems compress the traditional separation between vehicle provision and operational optimization.
- Fleet Management:Centralized dispatch and maintenance scheduling platforms integrate with subscriber ERP systems. Large logistics providers demand API connectivity for unified procurement authority across operating subsidiaries.
- Route Optimization:AI-driven routing algorithms reduce per-mile costs and improve asset utilization. These tools prove most valuable for mixed diesel-electric operations during fleet transition periods.
- Autonomous Vehicles:Self-driving capabilities target closed-loop routes in mining, ports, and industrial campuses where regulatory complexity of open-road deployment is avoided. Einride AB specializes in this segment.
Telematics underpins today's bundled contracts. Autonomous capabilities represent the emerging differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's freight logistics corridor concentrates the highest density of subscription-based electric fleet programs. National regulators across major economies are recalibrating emission standards and subsidy structures that determine contract economics for outsourced commercial vehicle capacity.
Germany
KBA type-approval protocols unlock federal subsidies for leased electric commercial vehicles, compressing ownership tenures among freight operators. The EU Green Deal's CO2 emission standards for heavy-duty vehicles mandate progressive fleet decarbonization by 2030. The Rhine-Ruhr logistics cluster hosts pilot programs where logistics providers bundle vehicle subscriptions with depot-based charging infrastructure.
United States
EPA Phase 3 greenhouse gas standards tighten compliance pathways for regional freight networks operating aging diesel tractors. The IRA's commercial clean vehicle tax credits alter total-cost calculations favoring outsourced electric fleet transitions. California's Central Valley distribution hubs are piloting shorter-term subscription models to defer capital commitment until battery technology matures.
Netherlands
Third-party logistics providers consolidate procurement authority across European distribution hubs seeking continental consistency in telematics standards. The country's national environmental agency enforces strict low-emission zones in urban centers that accelerate electric truck adoption. Rotterdam's port logistics corridor is testing autonomous-capable electric subscriptions for closed-loop container movements.
Sweden
Industrial shippers favor closed-loop route contracts for mining and port logistics where autonomous deployment avoids open-road regulatory complexity. The Swedish Transport Agency coordinates with EU frameworks on automated vehicle testing permits. The Kiruna mining district is piloting self-driving electric truck subscriptions for captive industrial routes.
China
Battery supply concentration in cell manufacturing clusters exposes service providers to input cost volatility while enabling rapid fleet electrification. The Ministry of Industry and Information Technology oversees GB standards for commercial vehicle safety and emission performance. The Yangtze River Delta logistics corridor is scaling pay-per-use arrangements that match vehicle availability to e-commerce demand volatility.
Truck-As-A-Service Market Competitive Environment
Global majors compete with regional champions across integrated service platforms and subscription model sophistication. The market structure consolidates around OEM-backed service divisions and independent fleet technology specialists. Two strategic archetypes dominate: integrated manufacturers bundling leasing with predictive maintenance, and autonomous-capable pure-plays targeting closed-loop industrial routes. Competitive intensity centers on M&A activity to capture telematics capabilities and strategic partnerships to secure charging infrastructure access.
Among European OEMs with captive service arms, Daimler Truck AG anchors the integrated platform tier, while AB Volvo occupies a parallel position in subscription-based regional freight networks. Einride AB exemplifies the autonomous-specialist archetype with its closed-loop industrial focus. These three represent distinct competitive vectors: manufacturer-backed bundling, regional network density, and automation-enabled route economics.
| Leading Market Players |
|---|
| Daimler Truck AG |
| AB Volvo |
| TRATON SE |
| Tata Motors Limited |
| Volta Trucks |
| Einride AB |
| BYD Company Limited |
| Trimble Transportation |
| Fleet Advantage |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal CO2 emission standards are compressing diesel ownership tenures and forcing freight operators toward electric subscriptions, compelling service providers to restructure cost recovery models around battery depreciation schedules and charging infrastructure bundling.
Pricing Analysis
Input-cost pass-through from battery cell manufacturing dominates contract economics, with lithium-ion pack prices feeding directly into monthly subscription rates. Three-tier pricing structure across premium telematics-enabled, standard maintenance-bundled, and economy basic-lease levels differentiates offerings. Pricing pressure stems from residual value uncertainty for electric commercial vehicles, elevating lessor risk premiums. E-commerce logistics providers exhibit highest price sensitivity due to demand volatility, while mining and port operators accept premium rates for autonomous-capable subscriptions.
Supply Chain Analysis
Domestic-content mandates in the EU and US are reshaping sourcing patterns for battery cells and electric drivetrain components. Cell manufacturing concentrates in China, South Korea, and Japan, with European assembly operations drawing from these clusters. Lithium carbonate, nickel sulfate, and semiconductor power modules constitute critical input dependencies. Single-source vulnerability from Chinese cell production exposes providers to geopolitical supply risk. Distribution runs through OEM captive service divisions and independent fleet technology platforms with national coverage networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Truck-As-A-Service market compounds steadily as regulatory mandates convert capital-intensive fleet ownership into recurring subscription revenue. EU Green Deal compliance deadlines and US EPA Phase 3 standards ensure durable demand expansion.
For Market Incumbents: Lock in charging infrastructure partnerships to secure depot electrification access before grid upgrade bottlenecks intensify. Deepen backward integration into predictive maintenance software to capture lifecycle value beyond vehicle provision. Autonomous-capable pure-plays threaten premium segment margins; counter by bundling telematics with route optimization APIs. For New Entrants and Emerging Players: Regional freight networks operating aging diesel tractors represent the most penetrable buyer archetype, particularly in California's Central Valley and Germany's Rhine-Ruhr corridor. Closed-loop industrial routes in mining and port logistics offer white-space deployment without open-road regulatory complexity. Pursue pilot-to-scale contracts with pay-per-use structures that defer capital commitment until technology matures. For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous-capable pure-plays targeting captive industrial routes, where regulatory barriers protect incumbent positions. Long-term viability hinges on telematics platform consolidation and charging infrastructure access. Watch for bidirectional charging contract adoption in Germany as an inflection indicator for vehicle-to-grid monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Depot electrification access secures subscription contract economics against grid upgrade delays. |
| Predictive Maintenance Platform Acquisition | Telematics-enabled AI bundling captures lifecycle revenue beyond vehicle provision. |
| Autonomous Capability Development | Self-driving electric subscriptions unlock closed-loop mining and port logistics premiums. |
| Bidirectional Charging Contract Pilot | Vehicle-to-grid energy resale subsidizes subscription costs for German freight operators. |
| Regional Service Network Expansion | Netherlands-based European distribution hubs demand continental telematics consistency. |
Study Parameters
Coverage spans Germany, the United States, the Netherlands, Sweden, and China, with primary inputs from each market cluster. Fleet procurement managers at third-party logistics providers, OEM service division executives, charging infrastructure developers, and regulatory affairs specialists at commercial vehicle manufacturers contributed structured interviews. Secondary validation drew from KBA type-approval databases, EPA Phase 3 regulatory filings, EU Green Deal implementation documents, and vehicle registration statistics. Bottom-up subscription contract value estimates triangulated against top-down fleet electrification spending projections.
Granularity-level modeling distinguished lease, subscription, pay-per-use, and financing structures across light-duty, heavy-duty, electric, and refrigerated vehicle categories. End-user segmentation captured logistics companies, e-commerce firms, retailers, and manufacturers with distinct procurement authority patterns. Technology integration layers—telematics, fleet management, route optimization, and autonomous capabilities—were modeled separately. CAGRs derived from regression analysis against regulatory compliance timelines and battery cost curves, with electric drivetrain adoption rates and charging infrastructure deployment schedules as key forecast inputs.
Underlying measurement precision varies by segment; electric truck subscription volumes carry tighter precision than autonomous-capable pilot programs. Forecasts reflect assumptions about subsidy program continuity, battery technology maturation, and grid infrastructure investment pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Global Commercial Vehicles Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market