
 Asia Three Wheeler Market | 2026-2036
Asia Three Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Three Wheeler Market Outlook
Modular battery-swappable configurations are decoupling vehicle ownership from energy asset investment, letting fleet operators lease power packs while purchasing bare chassis. Bajaj Auto Ltd leverages its captive casting and forging facilities to sustain cost leadership in internal-combustion powertrains. TVS Motor Company anchors its southern India stronghold through dense service networks and financing tie-ups with rural cooperatives. Mahindra & Mahindra Ltd competes by extending its electric three-wheeler lineup into refrigerated cargo variants for perishable supply chains.
Asia three wheelers are motorized three-wheeled vehicles with gross vehicle weights typically below one tonne, employing single-front or twin-front steering configurations with rear-wheel or all-wheel drive, and serving as low-cost commercial transport for passengers and light freight across dense urban and semi-urban corridors. Electric propulsion is gaining fastest among product types as lithium-iron-phosphate pack costs decline and charging infrastructure penetrates tier-two cities, though petrol variants still dominate rural installation segments where grid reliability remains intermittent. Passenger transport end users face margin compression from ride-hailing app intermediation, while goods delivery operators capture superior utilization rates through e-commerce fulfillment contracts.
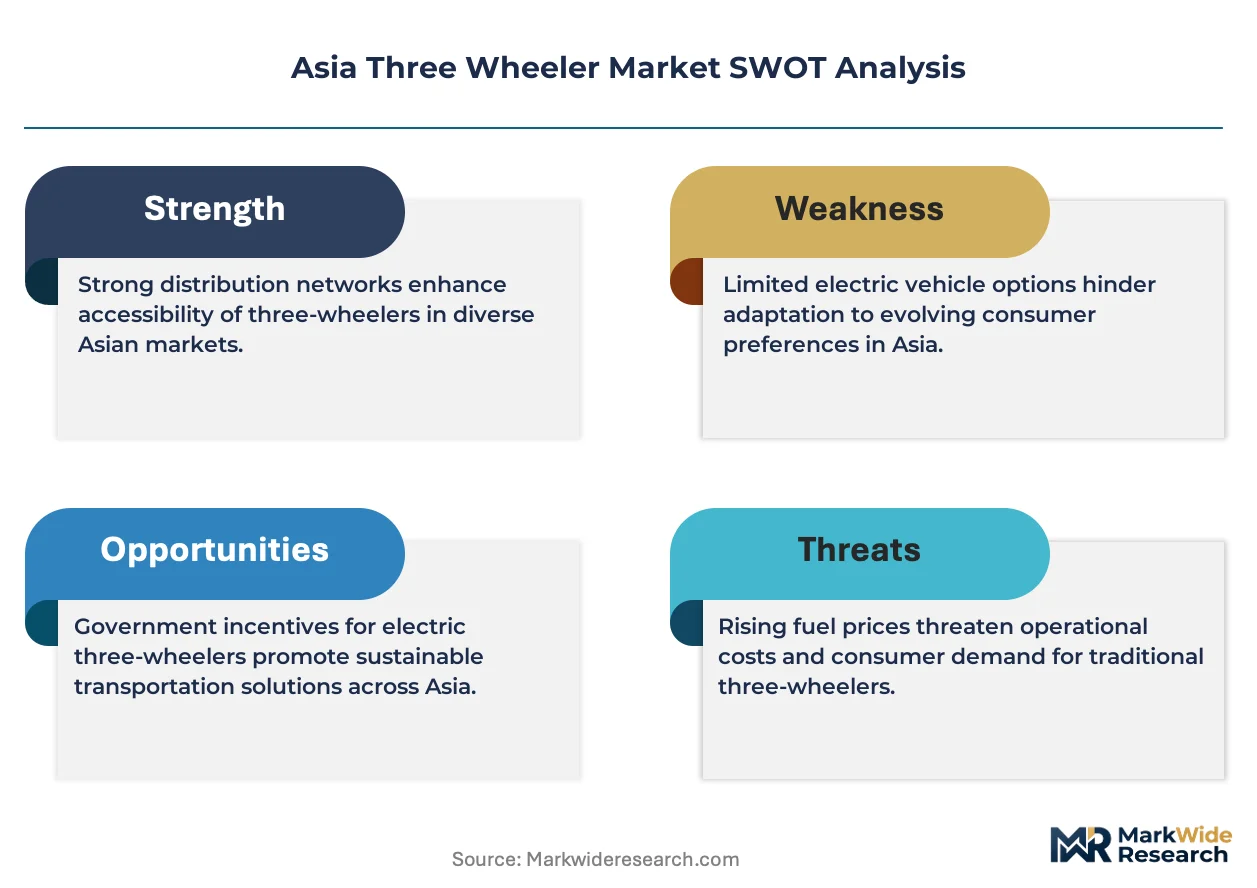
India's CEA and BIS enforce battery safety and performance standards that constrain import pathways for uncertified Chinese cell suppliers, while the PLI scheme redirects capital toward domestic module assembly. Thailand's industrial standards regulator and Indonesia's ministry of industry impose escalating local content requirements that shape regional manufacturing location decisions. Stakeholders must monitor how subsidy phase-out schedules and carbon border adjustment preparations reshape total cost of ownership calculations across the region's fragmented policy landscape.
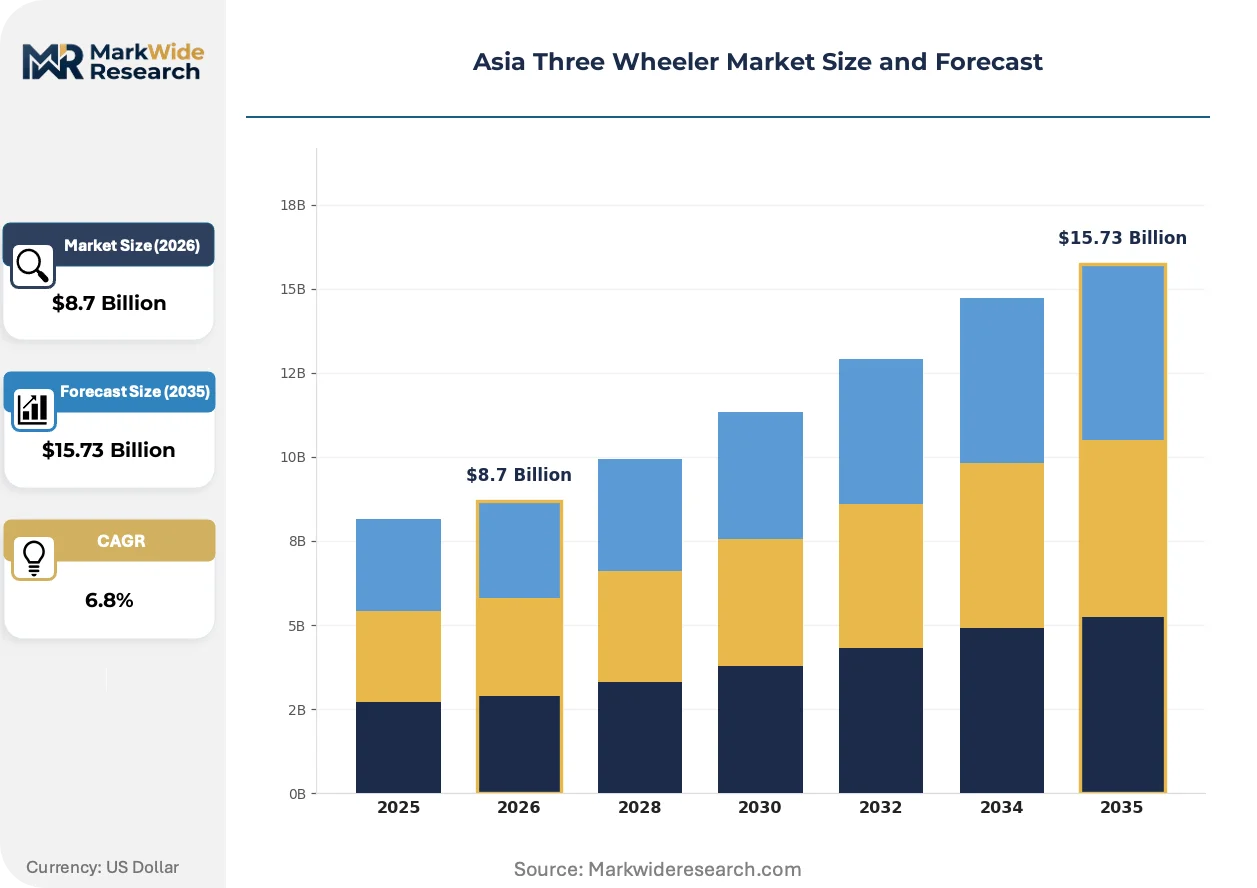
Market Dynamics
Modular battery-swappable architectures are decoupling vehicle ownership from energy asset investment, forcing powertrain suppliers to reposition around energy-as-a-service revenue streams rather than hardware sales cycles.
Growth Catalysts
- India's PLI scheme for automotive manufacturing:The production-linked incentive redirects capital toward domestic lithium-ion module assembly, reducing import dependency for powertrain components and accelerating localized supply chain formation.
- Last-mile e-commerce fulfillment:Dense urban delivery networks across Bangladesh and Vietnam are expanding electric three-wheeler procurement as municipal zero-emission mandates tighten in Dhaka and Ho Chi Minh City.
- Lithium-iron-phosphate chemistry:Declining pack costs and improved thermal stability are displacing lead-acid alternatives in commercial fleet applications where daily utilization rates exceed twelve hours.
Market Restraints
- Grid reliability gaps:Rural installation segments across Indonesia and the Philippines face intermittent electricity access that constrains pure-electric deployment and sustains petrol variant dominance.
- Cell import pathway constraints:India's CEA and BIS battery safety standards block uncertified Chinese suppliers, creating supply bottlenecks during domestic capacity ramp-up phases.
- Four-wheel commercial vehicle substitution:Subsidized electric cargo vans are capturing mid-weight freight segments that previously defaulted to three-wheeler platforms.
Strategic Opportunities
- Refrigerated cargo variants:Cold-chain gaps in India's perishable supply chains create white space for thermally insulated electric three-wheelers with integrated compressor units.
- Battery leasing channels:Energy-as-a-service models let fleet operators lease power packs while purchasing bare chassis, reducing upfront capital barriers for micro-entrepreneurs.
- Thailand's BOI incentive structures:Board of Investment privileges for EV component manufacturing are attracting module assembly investments that could serve ASEAN export markets.
Industry Challenges
- Service technician scarcity:High-voltage powertrain diagnostics and battery management system calibration require skills that rural dealership networks have not yet developed.
- Homologation timeline compression:Indonesia's escalating local content requirements force rapid supplier requalification cycles that strain engineering bandwidth at mid-scale manufacturers.
- Financing infrastructure misalignment:Traditional auto loan products do not accommodate battery-swappable asset structures, requiring new collateral valuation frameworks from rural cooperatives and NBFCs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Three Wheeler Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Petrol, Diesel, Hybrid End User: Passenger Transport, Goods Delivery, Municipal Services, Agriculture Installation: On-Road, Off-Road, Urban, Rural Maintenance Type: Scheduled, Breakdown, Preventive, Emergency |
| Companies Covered | TVS Motor Company, Kinetic Green Energy & Power Solutions Ltd, Bajaj Auto Ltd, Chongqing Zongshen Tricycle Manufacture Co. Ltd, Saera Electric Auto Pvt. Ltd, Mahindra & Mahindra Ltd, Atul Auto Limited, YC Electric Vehicle, Piaggio & C. SpA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Three Wheeler Market Strategic Shifts
Active thermal management and connected fleet telematics are converging to reshape how commercial operators extract value from three-wheeler assets, shifting competitive advantage from manufacturing scale toward energy optimization capabilities.
Lithium-iron-phosphate battery packs with integrated liquid cooling circuits are expanding into high-utilization delivery fleets across India's Gangetic plain states. Temperature-controlled cell environments extend cycle life beyond four thousand charge events, compressing total cost of ownership calculations for operators running double-shift schedules. Swappable configurations enable five-minute energy replenishment without grid dependency, expanding operational radius into semi-urban corridors lacking overnight charging infrastructure.
Indonesia's Ministry of Industry local content regulations are mandating progressive domestic value addition for electric vehicle eligibility certificates. Component suppliers must restructure procurement toward ASEAN-sourced magnet wire, stamped steel, and plastic molding to maintain subsidy access. Thai and Vietnamese assembly operations are responding by deepening tier-two supplier development programs that transfer technical specifications without direct technology licensing.
Fleet operators are consolidating procurement decisions at the holding-company level rather than individual owner-driver level, compressing vendor negotiation cycles and demanding standardized telematics integration. Aggregator platforms in Bangladesh and Sri Lanka are displacing traditional dealership financing by offering vehicle-plus-energy bundled subscriptions with utilization-linked repayment schedules. This concentration is most visible in Dhaka's garment-export logistics corridors where single buyers now contract fifty-plus unit deployments.
Asia Three Wheeler Market Segmentation
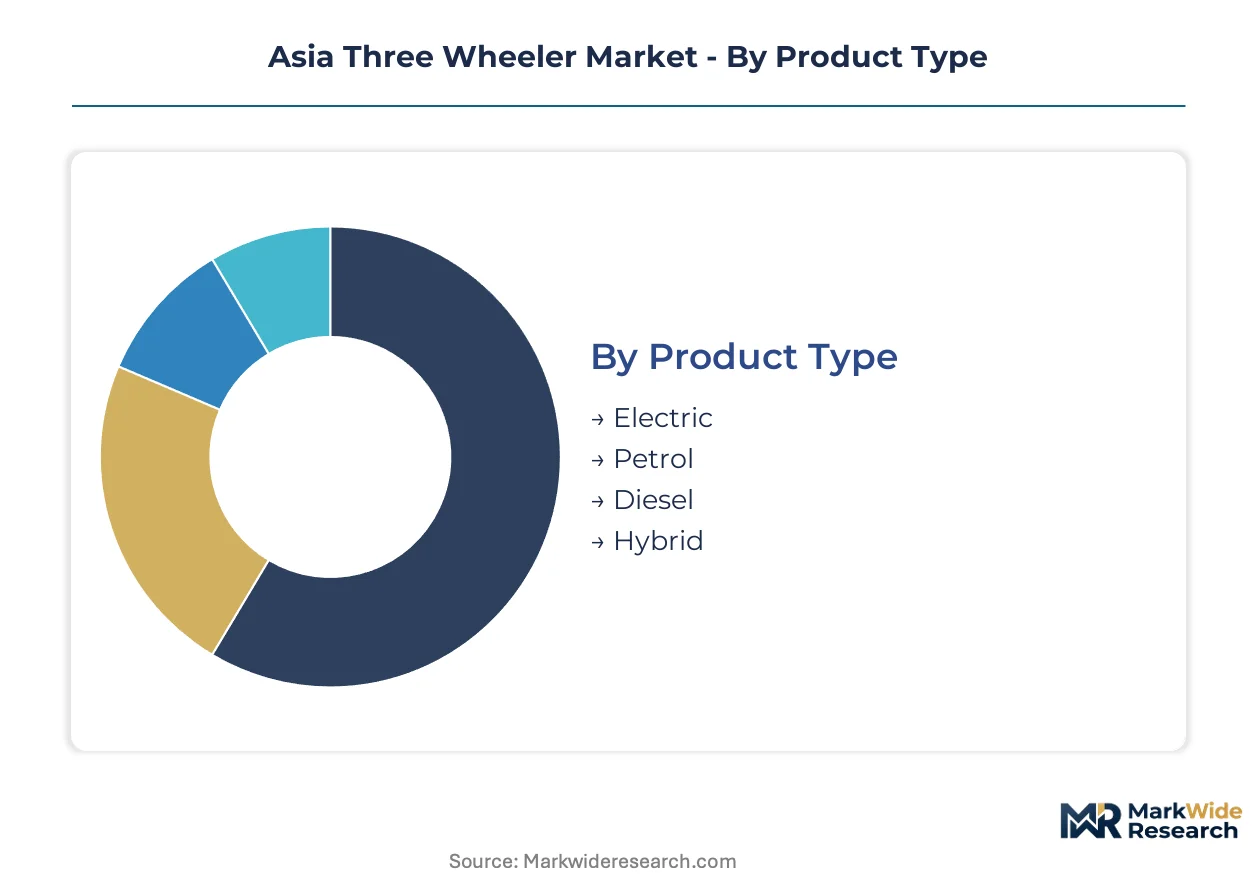
Three-wheeler procurement patterns diverge sharply between fleet operators seeking standardized platforms for asset pooling and owner-drivers demanding customized configurations for specific route economics. Segment boundaries are blurring as battery-swappable architectures let single chassis serve multiple duty cycles through modular energy and cargo attachments.
Product Type:
Standardization dominates mass-market manufacturing while customization concentrates in specialized thermal and range-extended configurations.
- Electric:Lithium-iron-phosphate packs with liquid cooling circuits now penetrate double-shift delivery fleets across Uttar Pradesh and Bihar. Dhaka's municipal zero-emission mandates are accelerating fleet procurement of swappable-battery variants that eliminate overnight charging dependency.
- Petrol:Carbureted and fuel-injected variants retain dominance in rural Indonesian and Philippine installations where grid reliability gaps exceed twelve hours daily. Low first-cost and established service networks sustain penetration among micro-entrepreneurs in tier-three towns.
- Diesel:Torque-dense powertrains serve heavy-load agricultural and construction material transport across semi-urban corridors. CNG conversion kits are displacing pure diesel in Delhi-NCR and Mumbai metropolitan regions under air quality enforcement.
- Hybrid:Range-extended architectures with small displacement gensets address cold-chain applications requiring uninterrupted compressor power. Thermally insulated cargo boxes with integrated auxiliary power units command premium positioning in perishable supply chains.
Most installed capacity flows through Petrol. Expansion is steepest in Electric.
End User:
Volume concentrates in high-utilization commercial operators while margin pools in specialized municipal and cold-chain contracts.
- Passenger Transport:Auto-rickshaw and shared mobility configurations face margin compression from ride-hailing app intermediation across Indian metropolitan clusters. Compressed natural gas and electric variants are capturing regulatory-compliant replacements in Delhi, Mumbai, and Dhaka urban cores.
- Goods Delivery:E-commerce fulfillment networks across Bangladesh and Vietnam are consolidating procurement at holding-company level with standardized telematics integration. Double-shift utilization rates exceeding twelve hours daily justify premium electric powertrain investments through total cost of ownership compression.
- Municipal Services:Waste collection and street-sweeping configurations benefit from dedicated subsidy windows under smart city programs. Battery-electric variants with hydraulic lift mechanisms are penetrating municipal tender specifications in tier-two Indian cities.
- Agriculture:Produce transport and light farm equipment hauling sustains petrol and diesel dominance in grid-constrained rural hinterlands. Low-speed, high-torque configurations serve last-mile connectivity between farms and wholesale mandis.
Goods Delivery commands the deepest fleet standardization. Passenger Transport faces the steepest margin pressure.
Installation:
Regulatory compliance requirements and infrastructure availability create sharp segmentation between formal and informal operating environments.
- On-Road:Homologated configurations with type certification dominate fleet procurement and financing-eligible transactions. India's BIS safety standards and Indonesia's local content mandates shape supplier qualification pathways for road-legal variants.
- Off-Road:Unregulated industrial and construction site applications prioritize durability over emissions compliance. Quarry and mining operations across Vietnam and the Philippines deploy reinforced chassis with higher payload ratings.
- Urban:Congestion-charging zones and zero-emission mandates in Dhaka, Ho Chi Minh City, and Indian metropolitan regions are accelerating electric penetration. Narrow street infrastructure sustains three-wheeler preference over four-wheel alternatives.
- Rural:Intermittent grid access and longer inter-city distances sustain internal combustion dominance. Service network density gaps favor established petrol powertrain platforms with proven field repairability.
Urban installations attract the most policy attention. Rural segments sustain the largest absolute fleet population.
Maintenance Type:
Service revenue models are shifting from transactional repairs toward subscription-based uptime guarantees under fleet management contracts.
- Scheduled:Preventive maintenance intervals tied to utilization hours preserve warranty coverage and residual values. Fleet operators are consolidating service contracts at holding-company level with standardized inspection protocols.
- Breakdown:Unplanned failure response demands rapid parts availability and mobile technician deployment. Rural service networks face scarcity of high-voltage powertrain diagnostics capability.
- Preventive:Predictive algorithms using battery management system telemetry are displacing time-based service schedules. Connected fleet platforms enable remote health monitoring and component replacement before failure.
- Emergency:Accident and collision repair requires specialized frame straightening and safety system recalibration. Insurance-linked service networks are consolidating around approved repair center certifications.
Scheduled maintenance generates the most predictable revenue streams. Preventive service models are gaining share fastest among electric fleet deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three-wheeler manufacturing scaled through India's post-liberalization automotive corridors, with the Gangetic plain emerging as the dominant production and consumption belt for motorized last-mile transport.
India
Fleet electrification and e-commerce fulfillment networks drive procurement across Uttar Pradesh and Bihar. The PLI scheme for automotive manufacturing redirects capital toward domestic lithium-ion module assembly. Pune-Aurangabad industrial corridors host powertrain component clusters serving both domestic demand and Bangladesh export markets.
Bangladesh
Dhaka's municipal zero-emission mandates accelerate electric three-wheeler adoption for garment-export logistics. The country's national transport regulator enforces progressive emission standards that favor battery-electric replacements in urban cores. Chittagong port corridors concentrate refrigerated cargo variant deployments for perishable supply chains.
Indonesia
Rural grid reliability gaps sustain internal combustion dominance across Java and Sumatra. The Ministry of Industry imposes escalating local content requirements that reshape component sourcing decisions. Surabaya industrial zones attract ASEAN-sourced magnet wire and stamped steel suppliers seeking EV eligibility certificates.
Thailand
Board of Investment privileges for EV component manufacturing attract module assembly investments serving regional export markets. The country's industrial standards regulator enforces battery safety protocols that constrain uncertified import pathways. Bangkok metropolitan congestion-charging zones accelerate electric penetration in passenger transport segments.
Vietnam
Ho Chi Minh City's municipal zero-emission mandates tighten procurement criteria for last-mile delivery fleets. Dense urban delivery networks expand electric three-wheeler deployment through standardized telematics integration. Mekong Delta agricultural corridors sustain diesel and petrol variants for produce transport between farms and wholesale mandis.
Asia Three Wheeler Market Competitive Environment
The competitive structure tilts toward integrated domestic manufacturers with captive powertrain production and dense service networks. Consolidation pressures concentrate around three archetypes: legacy internal combustion specialists pivoting toward electric platforms, pure-play electric entrants leveraging battery-swappable architectures, and diversified automotive conglomerates extending commercial vehicle portfolios. Dominant competitive moves include backward integration into cell and motor production, plus strategic financing tie-ups with rural cooperatives and non-banking financial companies.
Among India-based integrated manufacturers, Bajaj Auto Ltd, TVS Motor Company, and Mahindra & Mahindra Ltd occupy positions across the spectrum from cost-optimized internal combustion platforms to refrigerated electric cargo variants. Chongqing Zongshen Tricycle Manufacture Co. Ltd represents Chinese manufacturing scale in the regional supply base. Saera Electric Auto Pvt. Ltd and YC Electric Vehicle exemplify pure-play electric specialists targeting battery-swappable fleet configurations. Atul Auto Limited and Kinetic Green Energy & Power Solutions Ltd sit within the diversified tier serving both passenger and goods transport segments. Piaggio & C. SpA anchors European-origin premium positioning in select urban markets.
| Leading Market Players |
|---|
| TVS Motor Company |
| Kinetic Green Energy & Power Solutions Ltd |
| Bajaj Auto Ltd |
| Chongqing Zongshen Tricycle Manufacture Co. Ltd |
| Saera Electric Auto Pvt. Ltd |
| Mahindra & Mahindra Ltd |
| Atul Auto Limited |
| YC Electric Vehicle |
| Piaggio & C. SpA |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap manufacturers with captive forging and casting facilities anchor supply discipline across India's Pune-Aurangabad industrial corridor, translating upstream control into pricing resilience against lithium-cell cost volatility. Their financing tie-ups with rural cooperatives lock in volume commitments that buffer spot-market fluctuations in steel and aluminum inputs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by powertrain architecture and after-sales bundling intensity. Premium electric variants with liquid-cooled lithium-iron-phosphate packs and telematics integration command positioning above bare chassis configurations sold to battery-leasing fleet operators. Cost compression in economy-tier petrol variants is intensifying as Indonesian and Philippine micro-entrepreneurs prioritize first-cost minimization over total cost of ownership. Goods delivery fleet operators demonstrate lowest price sensitivity due to utilization-linked revenue models, while rural owner-drivers exhibit acute responsiveness to financing rate fluctuations.
Supply Chain Analysis
Indonesia's escalating local content requirements and India's PLI scheme are redirecting procurement toward ASEAN-sourced magnet wire, stamped steel, and domestic lithium-ion module assembly. Manufacturing gravity centers on India, Thailand, and Vietnam, with component feeds from China's cell suppliers constrained by India's CEA and BIS safety certifications. The supply chain rests on lithium carbonate, rare-earth magnets, and cold-rolled steel as critical inputs. Single-source vulnerability concentrates in high-nickel cathode chemistries subject to Indonesian export licensing. Distribution runs through OEM-captive dealership networks in rural hinterlands and direct fleet procurement channels in Dhaka and Ho Chi Minh City urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia three wheeler market functions as a stable compounder underpinned by irreplaceable last-mile logistics utility across dense urban corridors where four-wheel alternatives face congestion constraints.
For Market Incumbents: Deploy battery-swappable platform standardization to defend against pure-play electric entrants leveraging asset-light energy-as-a-service models. Deepen backward integration into domestic cell assembly under India's PLI scheme to reduce exposure to Chinese supplier certification bottlenecks. Capture refrigerated cargo white space through thermally insulated variant development for India's perishable supply chains.
For New Entrants and Emerging Players: Begin with battery-leasing subscription models targeting Bangladesh's garment-export logistics corridors where holding-company procurement consolidation creates fleet-scale entry points. Target municipal service tender specifications in tier-two Indian cities with electric waste-collection configurations benefiting from dedicated smart city subsidy windows. Anchor go-to-market through aggregator platform partnerships offering utilization-linked repayment schedules.
For Investors and Strategic Acquirers: Diversified automotive conglomerates seeking commercial vehicle portfolio extension represent the most active acquirer in this space, particularly those lacking last-mile logistics exposure. Acquisition targets with captive powertrain production and dense rural service networks offer defensive positioning through financing infrastructure control. Monitor Indonesia's local content requirement enforcement timelines as inflection indicators for regional manufacturing location decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Domestic cell procurement under India's PLI scheme reduces import dependency and accelerates localized module assembly capacity. |
| Platform Standardization | Modular chassis architectures enable single production lines to serve multiple duty cycles through swappable energy attachments. |
| Backward Integration | Captive forging and casting facilities translate upstream control into pricing resilience against steel and aluminum volatility. |
| Geographic Manufacturing Footprint | Thailand's BOI privileges attract ASEAN-sourced component clustering for export market eligibility certificate access. |
| Charging Infrastructure Partnership | Five-minute battery swap networks eliminate grid dependency and expand operational radius into semi-urban corridors. |
Study Parameters
Bottom-up fleet operator procurement modeling reconciled against top-down powertrain component production tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service heads, and rural cooperative financing officers combined with secondary validation from vehicle production databases, customs and trade records, IEA energy transition reports, and national regulator certification filings. Triangulation across these sources ensures demand-side fleet deployment patterns align with supply-side manufacturing capacity and component flow data.
Historical trendline analysis of electrification penetration rates and utilization-hour economics across passenger transport, goods delivery, and municipal service segments informs the projection framework. Segmentation dimensions modeled include propulsion architecture, end-use application, installation environment, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated against policy mandate timelines and infrastructure deployment schedules. Forecast inputs incorporate lithium-iron-phosphate pack cost trajectories and municipal zero-emission mandate enforcement intensity across Dhaka, Ho Chi Minh City, and Indian metropolitan regions.
Several conditions sit outside the modeled scope, including unforeseen commodity price shocks in lithium carbonate and rare-earth magnet markets, abrupt subsidy phase-out schedules, and grid reliability improvements in rural Indonesian and Philippine installations that could accelerate electric penetration beyond projected rates. Forecasts reflect assumptions documented in the segmentation and regional analysis sections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Truck-Mounted Road Sweeper Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
United States Vans Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Commercial Vehicle Driveline Support Bearings Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Robotic Haul Trucks Market