
 Global Light Commercial Vehicles Market | 2026-2036
Global Light Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Light Commercial Vehicles Market Foresight
The EU Green Deal is restructuring light commercial vehicle procurement across European logistics corridors. Ford Motor Company leverages its electric Transit platform to anchor fleet contracts in zero-emission zones. Toyota Motor Corporation sustains hybrid dominance in markets where charging infrastructure remains sparse. Stellantis competes through modular battery architectures that span multiple van body styles.
Light commercial vehicles are motor vehicles with a gross vehicle weight rating between 3.5 and 7.5 tonnes, designed for goods transport or specialized commercial services with cab-forward configurations and flat-load floors. Panel vans lead volume in urban last-mile delivery where cargo density and maneuverability command premium positioning. Electric fuel types are gaining fastest in applications with predictable daily routes and depot-based charging. Diesel retains structural share in long-haul courier services and mobile workshops where range flexibility outweighs total cost of ownership advantages from electrification.
The US EPA tailpipe standards and California Air Resources Board mandates are compressing diesel's viable horizon while creating compliance pathways for plug-in hybrids. China's MIIT new energy vehicle quotas and the EU's F-Gas Regulation on refrigerants in thermal management systems are reshaping component sourcing and vehicle certification requirements. Fleet operators must monitor regulatory divergence between jurisdictions to avoid stranded asset risk in multi-country deployment strategies.
Market Dynamics
Powertrain diversification is compressing diesel's structural dominance across urban logistics corridors, with fleet operators rebalancing procurement toward electric platforms as zero-emission zones expand and total cost of ownership equations flip.
Growth Catalysts
- EU Green Deal emissions targets:The framework mandates fleet decarbonization timelines that accelerate van electrification across German and British logistics networks.
- Last-mile delivery density:E-commerce fulfillment networks in India and the United Kingdom are scaling electric van procurement to navigate congestion pricing schemes.
- Depot-based charging infrastructure:Predictable route patterns enable overnight fleet charging, reducing range anxiety for urban parcel operators.
Market Restraints
- Battery mineral supply concentration:Lithium and cobalt processing capacity clusters in limited geographies, creating input volatility for electric van manufacturers.
- Long-haul range limitations:Current battery energy density constrains electric viability for mobile workshop and intercity courier applications.
- F-Gas Regulation compliance costs:The EU's thermal management refrigerant rules add certification overhead to HVAC system sourcing.
Strategic Opportunities
- Modular battery architectures:Platform flexibility spanning multiple van body styles enables Stellantis and competitors to address fragmented vocational demand.
- India's logistics electrification:Underpenetrated last-mile fleets in Indian urban corridors present volume expansion potential for compact panel van suppliers.
- US EPA tailpipe standards:Compression of diesel's viable horizon creates compliance pathways for plug-in hybrid powertrains in California and federal fleet procurement.
Industry Challenges
- Multi-jurisdiction regulatory divergence:Fleet operators deploying across Germany, the United Kingdom, and India must monitor stranded asset risk from mismatched zero-emission zone timelines.
- Charging infrastructure skill gaps:Depot electrification projects require electrical engineering and grid integration capabilities scarce in traditional fleet maintenance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Light Commercial Vehicles Market |
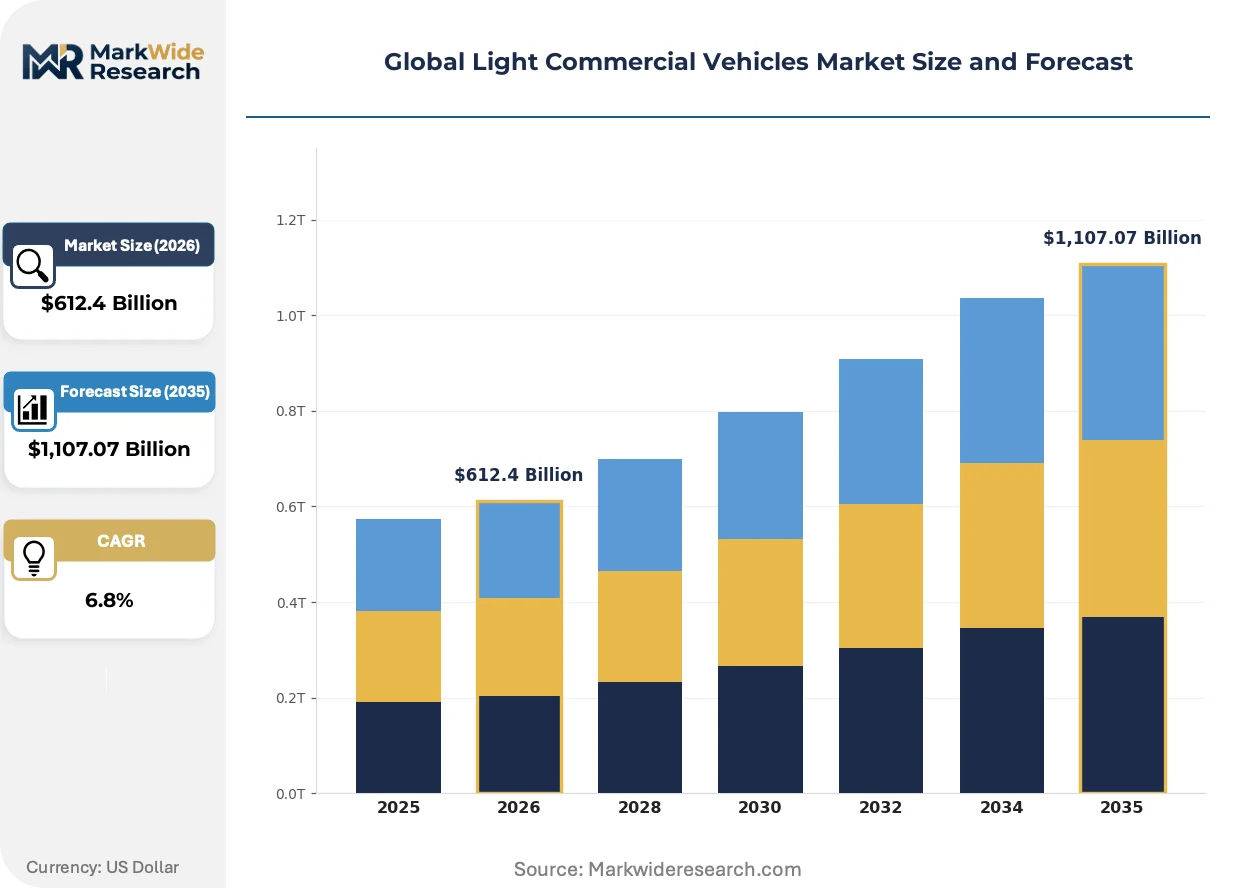
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,107.07 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
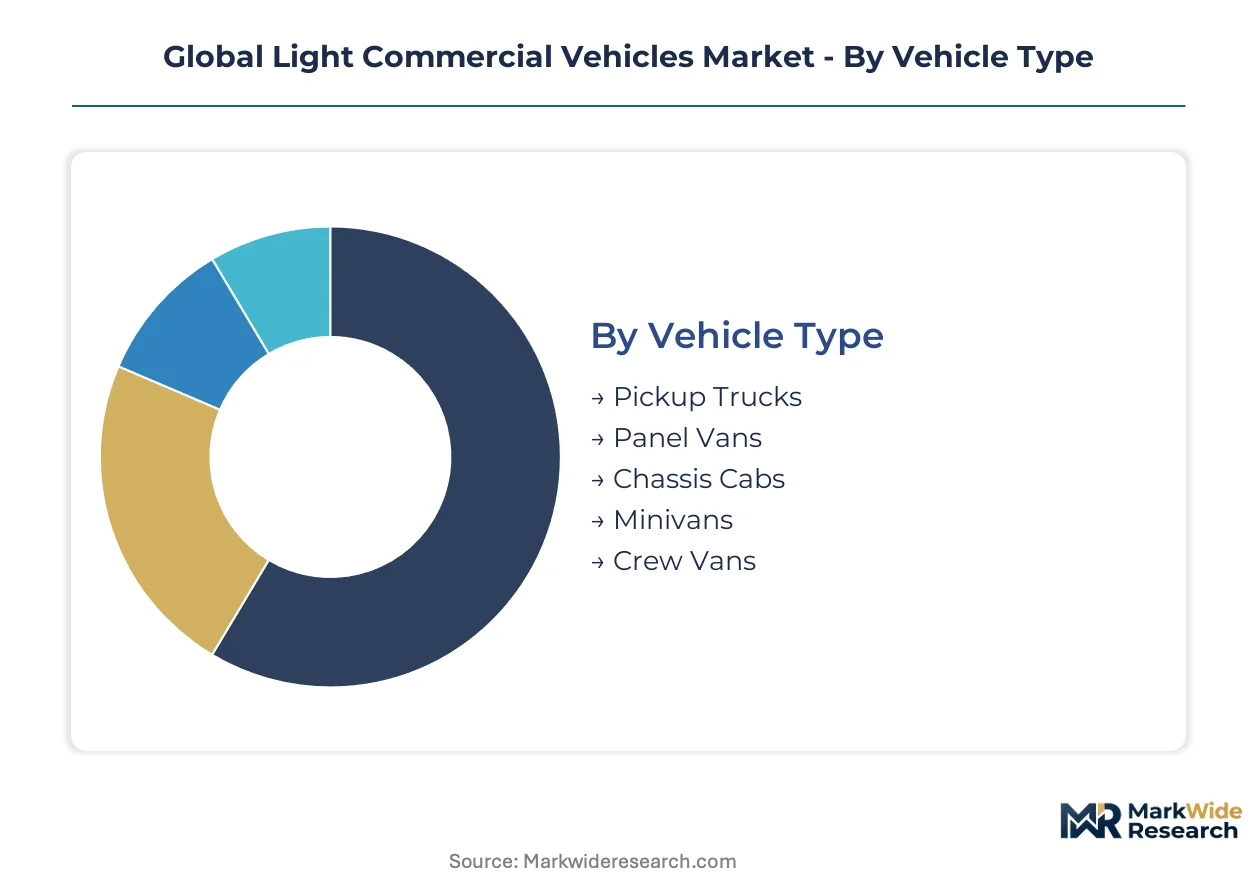
| Segmentation | Vehicle Type: Pickup Trucks, Panel Vans, Chassis Cabs, Minivans, Crew Vans Fuel Type: Diesel, Gasoline, Electric, Hybrid, Compressed Natural Gas, Liquefied Petroleum Gas Application: Last-Mile Delivery, Courier & Express Services, Passenger Transport, Mobile Workshops, Utility Services, Mobile Healthcare End User: Logistics Companies, Government Agencies, Small Businesses, Rental Fleets, Fleet Operators |
| Companies Covered | Ford Motor Company, General Motors Company, Volkswagen AG, Toyota Motor Corporation, Stellantis, Isuzu Motors, Hyundai Motor Company, Daimler Truck Holding AG, Renault Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Light Commercial Vehicles Market Shifts & Advancements
Electrification is restructuring competitive advantage around software-defined vehicle platforms and energy management systems rather than traditional powertrain engineering.
Modular battery pack architectures are consolidating platform economics across multiple van body styles and wheelbase configurations. Fleet buyers in Germany and the United Kingdom now specify battery capacity independent of chassis length, compressing variant complexity for manufacturers. This consolidation is enabling faster model cycle times and shared component sourcing across passenger and commercial vehicle programs.
The EU F-Gas Regulation on refrigerants is reshaping thermal management system supply chains and vehicle certification requirements. Manufacturers must redesign HVAC components to meet phasedown schedules for high-global-warming-potential gases. Panel van segments with intensive climate control needs—pharmaceutical delivery and fresh food logistics—are experiencing the steepest compliance cost adjustments.
Fleet procurement is gravitating toward total-cost-of-ownership contracts that unbundle vehicle acquisition from energy and maintenance services. Third-party fleet management providers in India and the United Kingdom are displacing traditional dealer networks for large-scale van deployments. This shift is most visible among e-commerce fulfillment operators with centralized procurement functions and standardized route profiles.
Global Light Commercial Vehicles Market Segmentation
Light commercial vehicle procurement patterns diverge sharply across vocational applications, with powertrain choices and body configurations mapping directly to route predictability and payload requirements. Fleet operators segment their acquisitions by total cost of ownership horizons rather than upfront sticker price alone.
Vehicle Type:
Capital intensity varies dramatically across body styles, with chassis cabs demanding the highest upfront tooling investment for upfitter integration while panel vans concentrate volume in standardized configurations.
- Panel Vans:Enclosed cargo compartments with flat-load floors optimize urban maneuverability and cargo density. Last-mile delivery fleets in Germany and the United Kingdom prioritize these configurations for zero-emission zone compliance where compact dimensions reduce congestion charges.
- Pickup Trucks:Open-bed designs with reinforced frames support construction and agricultural applications requiring irregular load shapes. Demand concentrates in North American markets where towing capacity and off-road capability command premium positioning against enclosed alternatives.
- Chassis Cabs:Incomplete vehicle platforms require substantial secondary manufacturing investment for body installation.
- Minivans:Passenger-oriented configurations with flexible seating arrangements serve mixed-use small business requirements.
- Crew Vans:Dual-purpose designs combining cargo capacity with additional passenger seating address mobile workforce transport needs.
Panel vans absorb the bulk of installed capacity; electric variants within this category are expanding most quickly as depot charging infrastructure matures.
Fuel Type:
Powertrain selection follows a cost-tier logic, with diesel retaining structural share in long-haul applications while electric platforms capture urban routes with predictable daily distances.
- Electric:Battery-electric powertrains with regenerative braking and depot-based charging protocols. Fleet operators in India and the United Kingdom specify these for last-mile delivery corridors where EU Green Deal timelines accelerate zero-emission zone enforcement and overnight charging eliminates range anxiety.
- Diesel:Compression-ignition engines with established service networks and refueling infrastructure. Mobile workshop operators and intercity courier services in jurisdictions with sparse charging networks maintain procurement preference for range flexibility and rapid refueling.
- Hybrid:Combined internal combustion and electric propulsion systems.
- Gasoline:Spark-ignition engines with lower upfront cost positioning.
- Compressed Natural Gas:Alternative fuel systems with regional infrastructure dependency.
- Liquefied Petroleum Gas:Propane-based propulsion with limited geographic deployment.
Diesel retains the largest installed base; electric powertrains are gaining share fastest where congestion pricing and low-emission zones reshape total cost equations.
Application:
Customer maturity determines specification complexity, with e-commerce fulfillment networks driving standardization while specialized services demand custom upfitting.
- Last-Mile Delivery:Urban parcel distribution with high stop frequency and predictable route patterns. E-commerce operators in Germany and India scale electric van procurement to navigate congestion pricing schemes and meet EU Green Deal emissions timelines.
- Mobile Workshops:On-site service vehicles carrying tools, parts inventory, and specialized equipment. Long-haul range requirements and variable daily distances constrain electric adoption where battery energy density limits payload-range tradeoffs.
- Courier & Express Services:Time-sensitive document and small parcel transport.
- Passenger Transport:Shared mobility and shuttle services with seating priority.
- Utility Services:Infrastructure maintenance and repair operations.
- Mobile Healthcare:Clinical service delivery and diagnostic testing units.
Last-mile delivery commands the greatest procurement volume; mobile healthcare applications are climbing the fastest as decentralized care models expand fleet requirements.
End User:
Procurement scale and centralization separate fleet buyers, with large logistics companies consolidating specifications while small businesses prioritize acquisition flexibility.
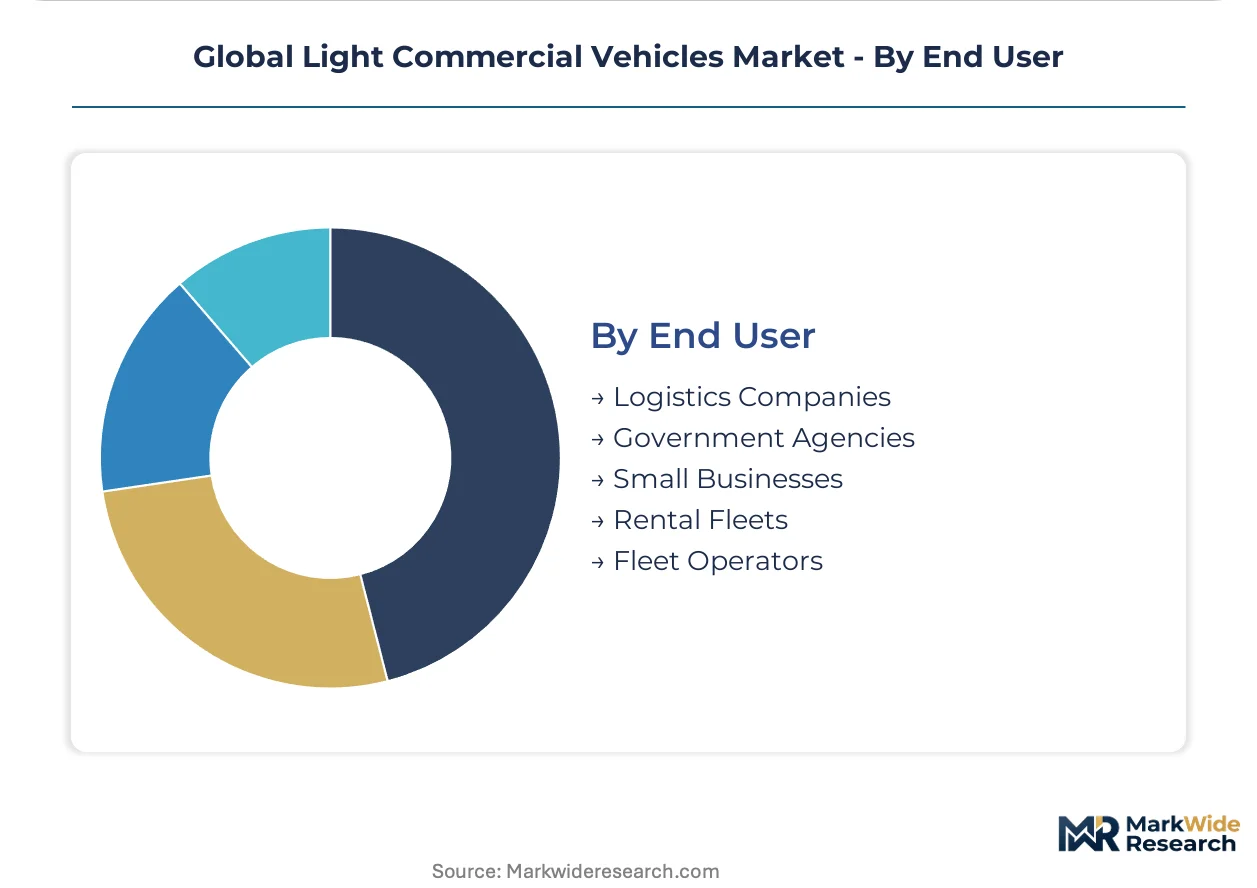
- Logistics Companies:National and regional parcel carriers with centralized procurement functions and standardized route profiles. Third-party fleet management providers in the United Kingdom and India displace traditional dealer networks for these operators through total-cost-of-ownership contracts bundling vehicles, energy, and maintenance.
- Fleet Operators:Dedicated vehicle management companies serving multiple end-use clients. Multi-jurisdiction deployment across Germany, the United Kingdom, and India requires monitoring of stranded asset risk from mismatched zero-emission zone timelines.
- Government Agencies:Public sector procurement with compliance and domestic content requirements.
- Small Businesses:Owner-operator models with fragmented acquisition patterns.
- Rental Fleets:Short-term vehicle access providers with utilization optimization priorities.
Logistics companies absorb the bulk of manufacturer capacity; fleet operators are scaling most rapidly as outsourcing trends consolidate vehicle management functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of light commercial vehicle chassis while Germany and the United States absorb premium electric van volumes. Manufacturing clusters concentrate where battery supply chains intersect with legacy automotive engineering capabilities. Consumption patterns diverge sharply between dense urban corridors favoring compact electrics and sprawling territories where range flexibility commands priority.
Germany
Fleet operators in the Rhine-Ruhr and Stuttgart regions are converting last-mile delivery contracts to electric platforms ahead of municipal zero-emission zone enforcement. The KBA enforces stringent type-approval standards for commercial vehicle powertrain certification. Berlin's logistics corridor now hosts Europe's densest depot-charging infrastructure for compact panel van fleets serving e-commerce fulfillment networks.
United States
Commercial buyers in California and the Pacific Northwest are accelerating electric van procurement to meet CARB fleet mandates and federal EPA tailpipe standards tightening through 2027. The Inflation Reduction Act commercial vehicle tax credits are restructuring total-cost-of-ownership calculations for urban courier operators. Detroit's engineering cluster supplies modular chassis architectures spanning multiple vocational upfit configurations for North American fleet buyers.
China
Domestic logistics operators in the Yangtze River Delta and Pearl River Delta are scaling battery-electric van deployment under MIIT new energy vehicle quota requirements. The dual carbon policy framework compresses diesel's viable horizon in municipal delivery applications. Shenzhen's port-logistics corridor serves as the primary testbed for autonomous electric van integration in high-density freight networks.
India
E-commerce fulfillment networks in Maharashtra and Karnataka are piloting compact electric panel vans for last-mile delivery in Bangalore and Mumbai congestion zones. The PLI scheme for automotive manufacturing is attracting component suppliers to Tamil Nadu's industrial belt. Delhi-NCR's logistics operators face the steepest regulatory pressure from the capital's air quality mandates, accelerating procurement timelines for zero-emission commercial fleets.
United Kingdom
Parcel carriers in the Midlands and Greater London are consolidating electric van specifications around standardized battery capacities to simplify fleet maintenance protocols. The UK government's ZEV mandate for van sales is compressing diesel procurement windows through 2030. Birmingham's logistics hub is emerging as the primary concentration for third-party fleet management providers bundling vehicles, energy, and maintenance services under total-cost-of-ownership contracts.
Global Light Commercial Vehicles Market Competitive Landscape
The competitive structure tilts toward diversified automotive conglomerates with modular platform capabilities spanning passenger and commercial vehicle programs. Tiered positioning separates full-line manufacturers with battery-electric architectures from regional specialists serving vocational niches. Two dominant archetypes occupy the premium tier: legacy OEMs leveraging electric Transit-type platforms for fleet contracts, and hybrid-focused producers sustaining share in charging-constrained markets. Competitive moves concentrate on strategic partnerships for battery supply security and geographic expansion into underpenetrated logistics corridors.
Among diversified automotive groups, Ford Motor Company, Toyota Motor Corporation, and Stellantis represent contrasting strategic positions within the electrification transition. Ford occupies a position anchored by fleet-centric electric van architectures designed for zero-emission zone compliance. Toyota exemplifies hybrid-sustained market presence in jurisdictions where charging infrastructure development lags powertrain diversification timelines. Stellantis sits within the modular-platform archetype, enabling battery capacity specifications independent of chassis configurations to address fragmented vocational demand across European and North American logistics networks.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors Company |
| Volkswagen AG |
| Toyota Motor Corporation |
| Stellantis |
| Isuzu Motors |
| Hyundai Motor Company |
| Daimler Truck Holding AG |
| Renault Group |
| Others |
Supply & Pricing Matrix
Lithium carbonate price benchmarks cascade through light commercial vehicle supply chains, compressing margin structures for battery-electric van manufacturers while amplifying procurement leverage for fleet operators with long-term offtake contracts in Germany and the United Kingdom.
Pricing Analysis
Total-cost-of-ownership contracts now anchor fleet procurement decisions, with pricing stratifying across premium, standard, and economy tiers based on battery capacity specifications and after-sales service bundling. Price differentiation stems from certification grade under EU F-Gas Regulation compliance tiers and volume scale in centralized logistics company orders. Cost compression in standard-tier electric panel vans is intensifying because battery mineral supply volatility feeds through to manufacturer cost structures. Small businesses exhibit highest price sensitivity due to fragmented acquisition patterns and limited access to fleet-scale energy service bundling.
Supply Chain Analysis
Battery cell production rests on Chinese, South Korean, and Japanese cathode and anode material suppliers, with lithium processing concentrated in Australia, Chile, and Argentina. Critical inputs include lithium carbonate, cobalt sulfate, and nickel-manganese-cobalt cathode formulations. Single-source vulnerability in semiconductor power electronics creates bottleneck exposure for electric powertrain controllers. Distribution runs through OEM captive networks in Europe and third-party fleet management providers displacing traditional dealer channels in India and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into battery mineral sourcing and captive charging infrastructure deployment constitutes the decisive competitive race, with upstream control over lithium hydroxide refining emerging as the critical margin lever.
For Market Incumbents: Cement platform standardization advantages by locking in long-term cathode supply agreements with Australian and Chilean lithium producers before quota constraints tighten. Defend against modular-platform challengers by accelerating software-defined vehicle investments that lock fleet customers into proprietary energy management ecosystems. Prioritize certification pre-positioning under EU F-Gas Regulation phasedown schedules to capture pharmaceutical delivery van contracts. For New Entrants and Emerging Players: Solid-state battery prototyping offers a technology-first wedge into mobile workshop segments where incumbent range limitations persist. Target India's underpenetrated last-mile logistics corridors in Maharashtra and Karnataka where charging infrastructure gaps delay established OEM electrification timelines. Pursue asset-light fleet management partnerships rather than manufacturing scale to bypass capital intensity barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal management specialists with EU F-Gas Regulation-ready HVAC architectures in Germany's industrial belt. Five-to-ten-year viability hinges on regulatory compliance capability rather than scale economies alone. Watch MIIT new energy vehicle quota enforcement stringency in China's Yangtze River Delta as the inflection signal for global battery supply constraint severity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term offtake contracts with Chilean lithium producers secure cathode material access for European van assembly. |
| Platform Standardization | Modular chassis architectures spanning multiple wheelbases compress variant complexity for Stellantis and Ford fleet programs. |
| Charging Infrastructure Partnership | Depot electrification joint ventures with grid operators in Birmingham and Berlin reduce fleet operator adoption friction. |
| Software-Defined Vehicle Investment | Over-the-air energy management updates lock logistics companies into recurring revenue service contracts. |
| Geographic Manufacturing Footprint | Tamil Nadu production clusters under India's PLI scheme attract component suppliers for compact electric panel van assembly. |
Research Methodology
Multi-period observation of vehicle registration databases, battery mineral price benchmarks, and municipal zero-emission zone enforcement timelines anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet management provider operations directors, and logistics company centralized procurement heads. Secondary validation drew from KBA type-approval filings, MIIT new energy vehicle quota disclosures, EU F-Gas Regulation implementation schedules, and IHS Markit production data. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Segment-weighting across vehicle type, fuel architecture, application, and end-user concentration shaped the analytical framework, with propulsion technology and battery capacity tiers receiving additional modeling emphasis throughout the projection horizon. CAGRs derived from regression analysis against regulatory enforcement schedules and fleet replacement cycle patterns. Industry-specific forecast inputs included EU Green Deal emissions trajectory assumptions and charging infrastructure deployment curves in German and British logistics corridors.
Several conditions sit outside the modeled scope, including unannounced battery chemistry breakthroughs, abrupt tariff reconfigurations affecting lithium supply chains, and accelerated autonomous vehicle regulatory frameworks. Forecasts embed assumptions regarding sustained mineral price volatility and zero-emission zone expansion timelines. A small set of named triggers warrants ongoing watch: MIIT quota enforcement stringency, F-Gas Regulation refrigerant substitution cost pass-through rates, and Indian PLI scheme disbursement continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Commercial Air Brake Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Europe Vacuum Truck Market