
 Van Market | 2026-2036
Van Market Size, Share, and Industry Trends Forecast 2026-2036
Van Market Analysis
EURO VI emissions certification is redrawing competitive boundaries for diesel and gasoline van manufacturers. Mercedes-Benz leverages its electric Vito and eSprinter platforms to sustain technology leadership in European commercial segments. Ford anchors North American demand through its E-Transit production at the Kansas City Assembly Plant. Volkswagen competes aggressively with the ID. Buzz Cargo, positioning the model as a direct challenger in mid-size electric logistics.
A van is a light commercial vehicle with a fully enclosed cargo or passenger compartment, unibody or body-on-frame construction, and gross vehicle weight ratings typically below 3.5 tonnes, designed for urban freight movement, tradesman transport, or multi-passenger shuttle duty. Cargo van configurations dominate fleet procurement due to superior payload density and standardized interior dimensions that maximize cubic utilization. Electric fuel type variants represent the fastest-expanding segment as battery chemistry improvements reduce total cost of ownership parity thresholds. Compact size classes retain strongholds in dense European and Japanese urban cores where parking constraints and road width limit larger vehicle maneuverability.
EPA greenhouse gas standards for light-duty trucks and the EU Green Deal's 100% CO2 reduction target for new vans by 2035 are forcing accelerated powertrain transitions across both markets. NHTSA crashworthiness protocols and ECE R94/R95 occupant protection regulations add compliance cost layers that favor manufacturers with integrated safety engineering capabilities. Stakeholders must monitor battery raw material supply agreements and charging infrastructure build-out rates as the decisive variables for production allocation and regional market prioritization.
Market Dynamics
Battery-electric powertrains are restructuring van manufacturing economics as EU CO2 standards for commercial vehicles tighten and fleet operators recalculate total cost of ownership around energy and maintenance savings.
Growth Catalysts
- EU Green Deal mandates:The 100% CO2 reduction target for new vans by 2035 is forcing fleet procurement toward zero-emission variants and accelerating charging infrastructure deployment across member states.
- Last-mile logistics densification:E-commerce fulfillment networks in Germany and the United States are expanding dedicated electric van fleets to meet urban delivery windows and municipal low-emission zone requirements.
- Lithium iron phosphate chemistry:Improved thermal stability and lower raw material costs are compressing battery replacement timelines and extending vehicle service life for high-utilization commercial operators.
Market Restraints
- Cobalt and lithium price volatility:Concentrated mining operations in the Democratic Republic of Congo and Chile create input cost instability that ripples through battery pack pricing and fleet financing models.
- Charging infrastructure gaps:Uneven fast-charging coverage in secondary cities and industrial zones limits route flexibility for operators outside major metropolitan corridors.
- Payload-range tradeoffs:Current battery energy density constraints force commercial users to choose between maximum cargo capacity and single-charge range, constraining deployment in long-haul distribution.
Strategic Opportunities
- India commercial vehicle electrification:PLI scheme incentives for advanced chemistry cell manufacturing are opening localized production pathways for cost-competitive electric van platforms serving domestic logistics.
- Vehicle-to-grid integration:Bidirectional charging capabilities allow fleet operators to monetize parked assets as grid stabilization resources, creating new revenue streams beyond freight transport.
- Autonomous last-mile routing:Convergence of lidar perception systems and edge computing is enabling pilot deployments of driverless delivery vans in controlled campus and suburban environments.
Industry Challenges
- Battery technician certification pipelines:High-voltage safety training and diagnostic competency requirements are outpacing vocational program output, creating maintenance bottlenecks for expanding electric fleets.
- Multi-platform software integration:Fleet management systems must reconcile proprietary telematics from diverse OEMs with third-party routing optimization tools, increasing IT complexity and vendor lock-in risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Van Market |
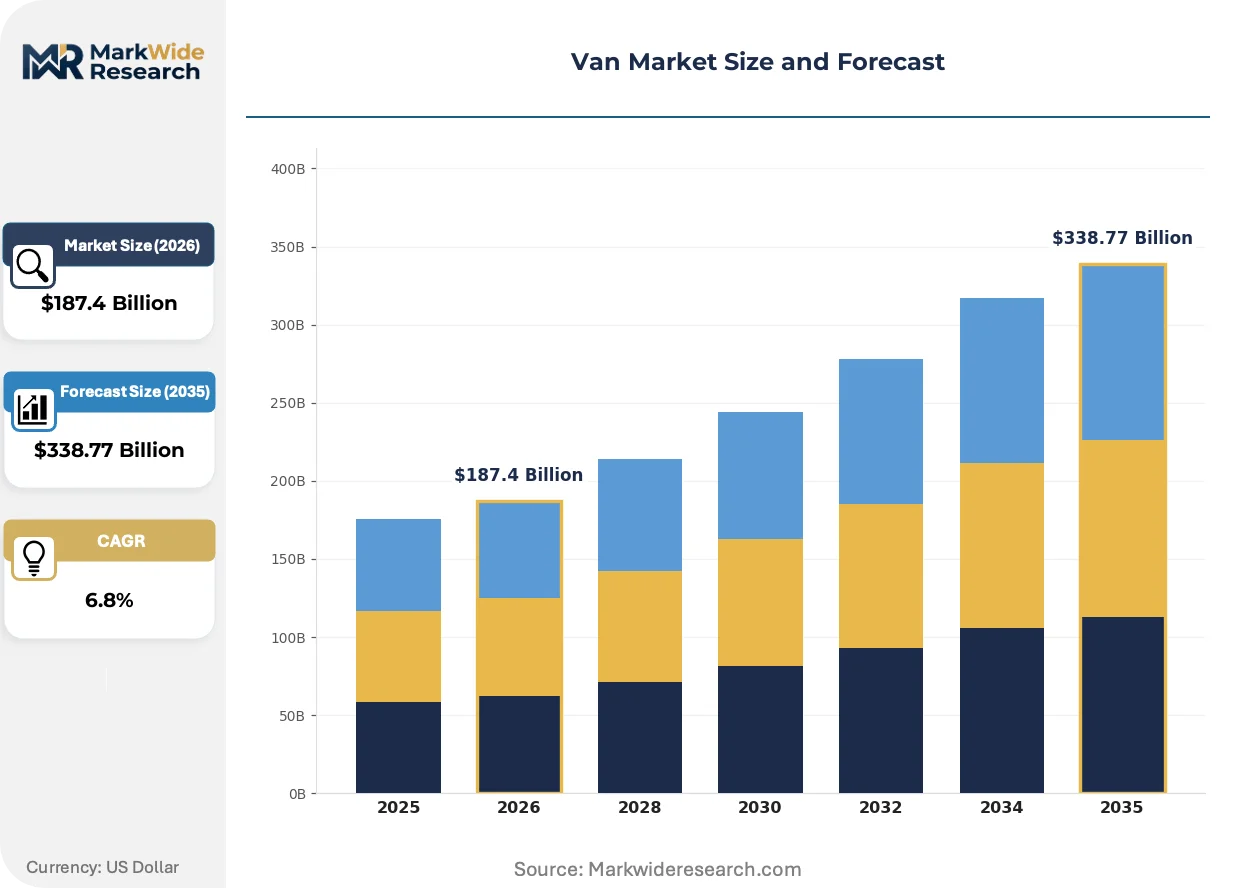
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Cargo Van, Passenger Van, Minivan, Box Van End User: Small Business, Delivery Services, Family, Rentals Fuel Type: Diesel, Gasoline, Electric, Hybrid Size: Compact, Full-Size, Extended, Mid-Size |
| Companies Covered | GMC, Renault, Mercedes-Benz, Volkswagen, Opel, Ford, Ram, Kia, Chevrolet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Van Market Emerging Trajectories
Electrification is converging with digital fleet management to redefine how commercial van assets are specified, financed, and operated across urban logistics networks.
Solid-state battery prototypes are supplanting conventional lithium-ion architectures in pre-production testing programs. German logistics operators are piloting these systems for temperature-sensitive pharmaceutical distribution. The technology is compressing thermal management packaging requirements and enabling denser cabin configurations.
EPA greenhouse gas standards for light-duty trucks are tightening compliance windows for internal combustion van variants. Manufacturers are reallocating engineering resources toward dedicated electric platforms rather than retrofit architectures. North American fleet buyers are accelerating procurement timelines to lock in federal tax credit eligibility.
Subscription-based vehicle access models are fragmenting traditional ownership patterns among small trade contractors. Tiered service bundles covering maintenance, insurance, and charging access are displacing outright purchase in UK and Netherlands markets. Plumbing and electrical trades show highest uptake of this procurement shift.
Van Market Segmentation
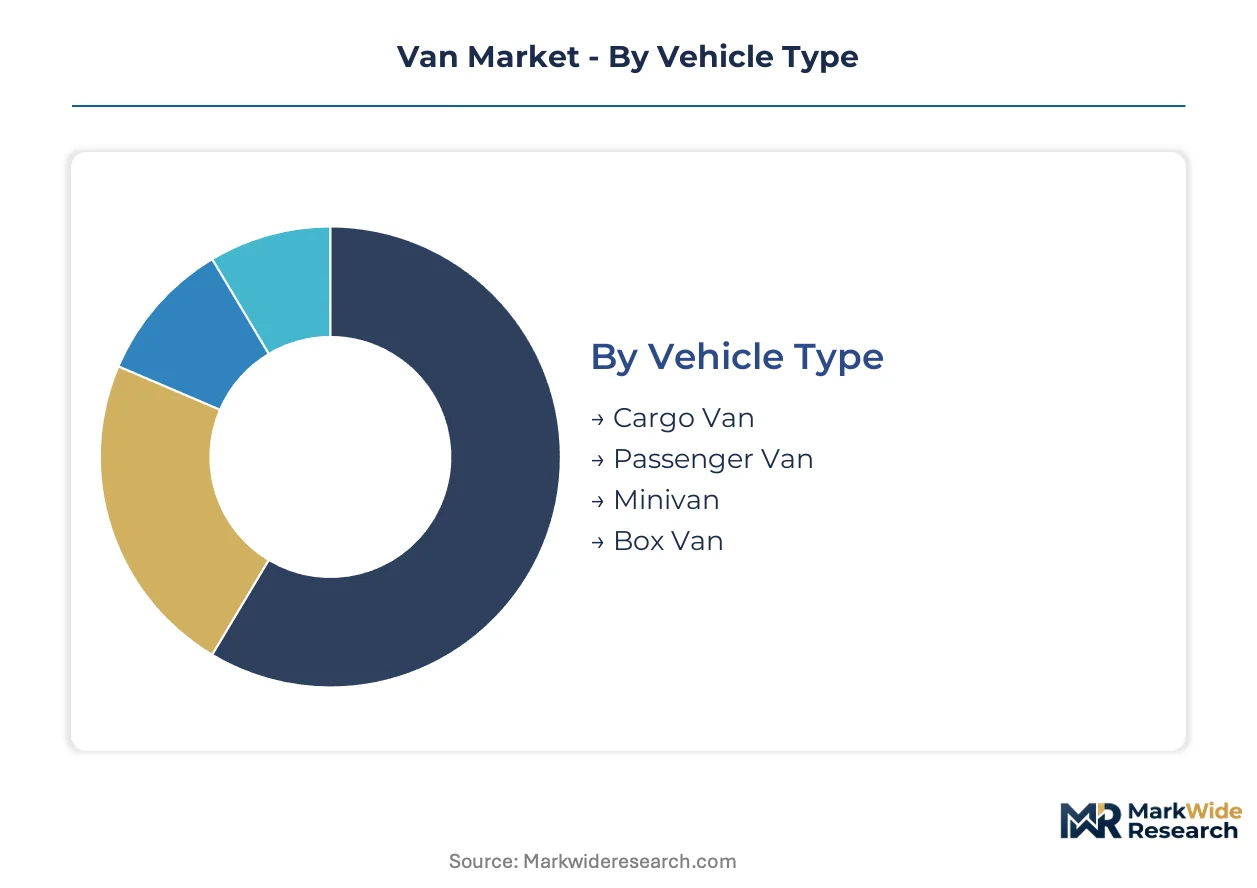
Van market segmentation reveals distinct procurement channels for each configuration. Fleet managers, family buyers, and rental operators source through entirely different commercial pathways with divergent specification priorities.
Vehicle Type:
Cargo vans and passenger variants flow through distinct channel architectures. Fleet leasing companies dominate commercial cargo procurement, while passenger configurations split between retail dealerships and mobility service contracts.
- Cargo Van:Fully enclosed load bay with bulkhead separation optimizes cubic utilization for parcel and equipment transport. German last-mile operators are expanding dedicated electric cargo fleets to comply with municipal low-emission zones in Berlin, Hamburg, and Munich.
- Passenger Van:Multiple row seating configurations accommodate 8-15 occupants with removable or fold-flat seat architectures. Airport shuttle services in the United States and corporate campus transport in the Netherlands are standardizing procurement around wheelchair-accessible passenger variants.
- Minivan:Unibody construction with sliding side doors prioritizes family ingress and third-row accessibility. North American family buyers continue to favor minivans for child-seat accommodation despite SUV cross-shopping pressure.
- Box Van:Detachable cube body mounted on chassis cab permits customized upfitting for specialized freight. Refrigerated box configurations serve pharmaceutical distribution networks requiring temperature-controlled logistics.
By volume, Cargo Van leads. By growth pace, Box Van is climbing the fastest as specialized logistics requirements proliferate.
End User:
Cost tier stratification separates these segments. Small businesses prioritize acquisition price and maintenance predictability. Delivery services optimize around total cost of ownership and uptime guarantees.
- Small Business:Trade contractors and local service providers specify vans for tool transport and mobile workshop functionality. British plumbing and electrical contractors are migrating toward subscription-based vehicle access to preserve working capital.
- Delivery Services:E-commerce fulfillment networks demand standardized interior dimensions for automated sorting compatibility. United States-based parcel carriers are locking in multi-year electric van procurement to secure federal tax credit eligibility.
- Family:Multi-child households prioritize safety ratings and entertainment system integration. Sliding door configurations retain preference in suburban Japanese markets where narrow residential streets constrain parking.
- Rentals:Daily and weekly rate optimization drives specification toward reliability and rapid turnaround capability. European airport rental fleets are accelerating electric van introductions to meet corporate sustainability procurement requirements.
By fleet size, Delivery Services dominates. By margin contribution, Family is gaining share fastest as premium feature uptake increases.
Fuel Type:
Application requirements dictate fuel selection across operating environments. Urban stop-and-go routes favor electric regeneration, while extended highway duty retains combustion advantage.
- Diesel:Compression ignition architecture delivers torque density for heavy payload and towing applications. German KBA emissions certification requirements are compressing diesel van residual values and accelerating fleet transition timelines.
- Gasoline:Spark ignition systems reduce upfront acquisition cost and cold-start complexity for moderate-duty cycles. North American small business buyers continue to favor gasoline powertrains where daily mileage remains below electric range thresholds.
- Electric:Battery-electric powertrains eliminate tailpipe emissions and reduce per-mile energy expenditure. EU Green Deal mandates are forcing accelerated electric van adoption as member states implement urban access restrictions for combustion vehicles.
- Hybrid:Dual powertrain architecture bridges range anxiety and regeneration efficiency for variable route profiles. Japanese commercial operators are piloting hybrid vans for rural delivery routes where charging infrastructure remains sparse.
By installed base, Diesel leads. By production pipeline allocation, Electric is expanding most quickly.
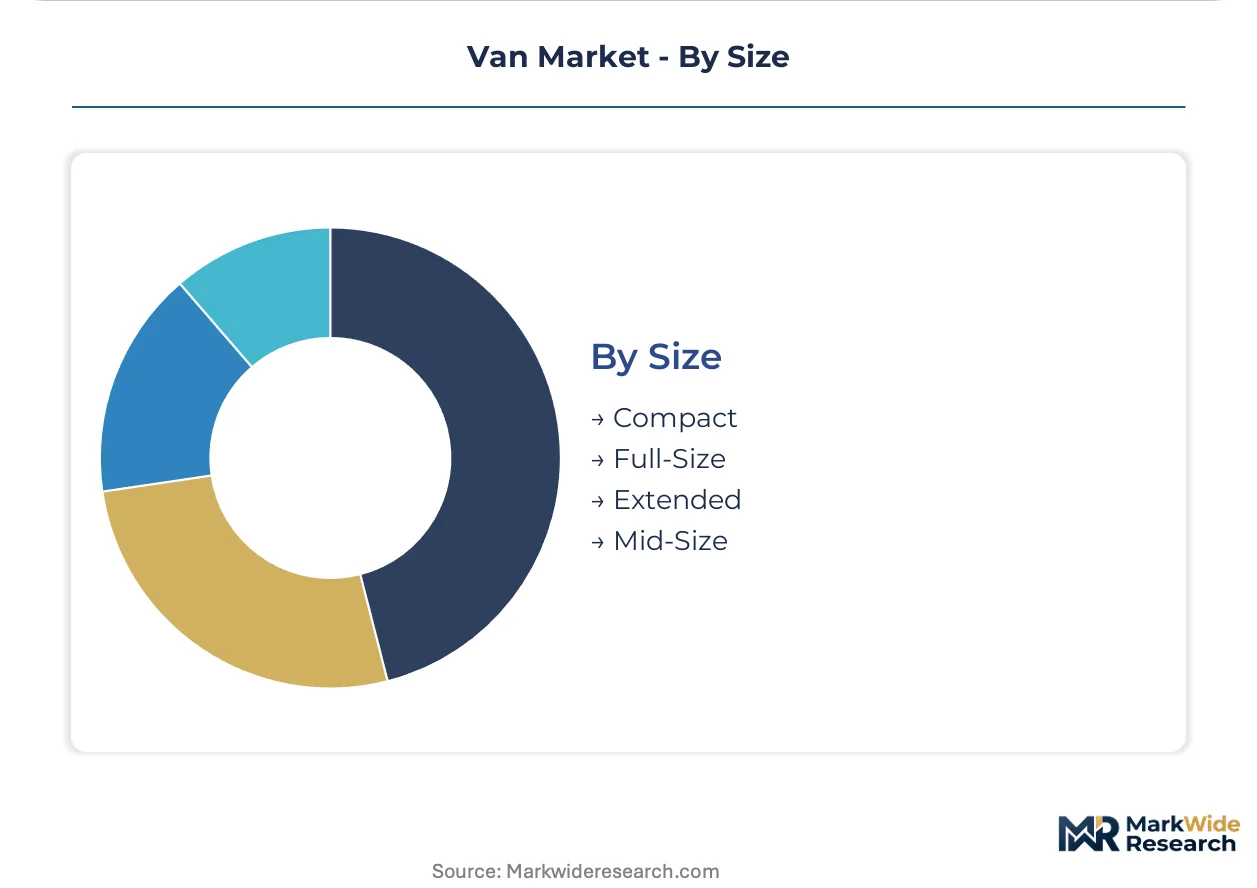
Size:
Geography constrains size selection. Dense urban cores with parking scarcity favor compact dimensions, while suburban and interurban routes permit larger configurations.
- Compact:Sub-4.5 meter length enables maneuverability in narrow European streets and multi-story parking structures. Amsterdam and Tokyo delivery fleets specify compact electric vans for canal-side and alley-access routes.
- Full-Size:Maximum cargo volume within standard driving license categories optimizes payload for long-haul distribution. United States interstate corridor operators favor full-size configurations for hub-and-spoke freight consolidation.
- Extended:Stretched wheelbase variants accommodate specialized upfitting without exceeding weight thresholds. British refrigerated couriers specify extended chassis for dual-temperature pharmaceutical transport.
- Mid-Size:Balanced footprint bridges urban maneuverability and highway stability for mixed-duty operators. German mid-size van registrations are climbing as regional logistics providers consolidate vehicle types.
By registration volume, Full-Size leads. By urban market penetration rate, Compact is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal tax credits and municipal low-emission zones are accelerating electric van procurement across major economies. Fleet operators in Germany and the United States are expanding dedicated zero-emission logistics networks. Manufacturing clusters in Detroit, Stuttgart, and Shanghai are reallocating capacity toward battery-electric platforms.
United States
E-commerce fulfillment networks in Chicago and Dallas are locking in multi-year electric van contracts to secure IRA tax credit eligibility. EPA greenhouse gas standards for light-duty trucks are compressing compliance windows for combustion variants. Ford's Kansas City Assembly Plant anchors North American E-Transit production for parcel carrier fleets.
Germany
Last-mile operators in Berlin, Hamburg, and Munich are expanding dedicated electric cargo fleets to comply with municipal low-emission zone requirements. KBA emissions certification protocols are accelerating diesel van residual value compression. Mercedes-Benz leverages its electric Vito and eSprinter platforms from Stuttgart manufacturing clusters.
China
Urban logistics providers in Shanghai and Shenzhen are piloting solid-state battery prototypes for temperature-sensitive pharmaceutical distribution. MIIT new energy vehicle mandates are driving battery chemistry improvements across domestic manufacturing. BYD and local OEMs dominate compact electric van production for dense urban cores.
India
Domestic logistics operators in Maharashtra and Gujarat are accessing PLI scheme incentives for advanced chemistry cell manufacturing. Central government commercial vehicle electrification targets are opening localized production pathways. Tata Motors and Mahindra are scaling electric van platforms from Pune and Chennai assembly facilities.
United Kingdom
Trade contractors in London and Birmingham are migrating toward subscription-based vehicle access models to preserve working capital. Corporate sustainability procurement requirements are accelerating electric van introductions at airport rental fleets. Vauxhall and Ford compete for fleet leasing contracts through UK commercial vehicle channels.
Van Market Vendor Landscape
Player mix skews toward integrated automotive conglomerates with dedicated commercial vehicle divisions. Market structure concentrates around three to four full-line manufacturers controlling European and North American volume. Strategic archetypes include legacy OEM platform diversifiers, electric-native challengers, and commercial fleet specialists. Competitive moves center on dedicated electric platform launches and strategic charging infrastructure partnerships.
Among German-based manufacturers, Mercedes-Benz and Volkswagen exemplify the platform diversification archetype, each fielding multiple electric van nameplates across size classes. Ford anchors the North American competitive set through its E-Transit production commitment. Renault represents the European volume-focused specialist, competing aggressively in mid-size electric logistics segments.
| Leading Market Players |
|---|
| GMC |
| Renault |
| Mercedes-Benz |
| Volkswagen |
| Opel |
| Ford |
| Ram |
| Kia |
| Chevrolet |
| Others |
Supply Flow & Price Mechanics
Lithium iron phosphate chemistry displacing cobalt-dependent formulations is compressing battery pack costs while shifting procurement gravity toward Chinese cathode producers and Chilean lithium brine operations. This substitution dynamic simultaneously reduces exposure to Democratic Republic of Congo mining concentration and creates new price volatility transmission channels through South American supply corridors.
Pricing Analysis
Certification level creates the primary spread between EU Green Deal-compliant electric variants and legacy combustion models still clearing EPA or KBA emissions protocols. Three-tier pricing structure across premium battery-electric, standard hybrid, and economy combustion tiers reflects divergent total cost of ownership calculations among fleet operators. Cost compression in the combustion tier is intensifying because residual value deterioration accelerates as municipal low-emission zones expand. Small business trade contractors exhibit highest price sensitivity, while delivery services prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Shenzhen ports through Rotterdam and Long Beach corridors constrain inventory positioning for European and North American assembly plants. Battery cell production concentrates in China, South Korea, and Japan, with cathode active material drawing from Chilean lithium and Indonesian nickel processing. Single-source vulnerability in high-voltage semiconductor components creates bottlenecks for power inverter assembly. Distribution runs through OEM captive financing arms and fleet leasing companies that bundle charging infrastructure with vehicle procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based vehicle access models are expanding faster than hardware sales as British and Dutch trade contractors prioritize working capital preservation over asset ownership. This service-attach layer creates recurring revenue pools that reshape competitive economics for fleet-focused manufacturers.
For Market Incumbents: Compound platform standardization advantages by extending electric Vito and eSprinter architectures across multiple size classes to amortize battery supply agreements. Defend against electric-native challengers through backward integration into charging infrastructure partnerships that lock in fleet operator switching costs. Prioritize certification investment in EU CO2 compliance pathways that preserve residual value positioning.
For New Entrants and Emerging Players: Differentiate on vehicle-to-grid integration capabilities that monetize parked fleet assets as grid stabilization resources. White-space targets include refrigerated pharmaceutical distribution in Germany and corporate campus shuttle services in the Netherlands. The most penetrable segment is compact electric logistics for dense European urban cores where parking constraints limit incumbent full-size dominance.
For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors manufacturers with captive battery supply agreements and integrated telematics stacks. Long-term viability hinges on software-defined vehicle architectures that enable over-the-air feature monetization. The acquisition target archetype is mid-size electric van specialists with established fleet leasing relationships. The signal to watch is charging infrastructure build-out rates in secondary cities as the decisive variable for regional market prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium iron phosphate cell allocation from CATL or BYD for high-utilization fleet contracts. |
| Charging Infrastructure Partnership | Integrates depot fast-ching with Shell Recharge or Ionity networks to reduce operator range anxiety. |
| Software-Defined Vehicle Investment | Enables telematics-based usage pricing and predictive maintenance revenue streams beyond hardware sales. |
| Platform Standardization | Extends Mercedes-Benz eSprinter skateboard architecture across compact and mid-size variants to reduce engineering duplication. |
| Geographic Manufacturing Footprint | Localizes Ford E-Transit assembly at Kansas City to preserve IRA tax credit eligibility for domestic fleet buyers. |
Methodological Framework
A standing panel of fleet procurement managers, OEM platform engineers, battery supply chain specialists, and municipal transport planners provided ongoing calibration throughout the research process. Primary interviews with Tier 1 supplier procurement teams and aftermarket service heads were cross-validated against secondary sources including EPA regulatory filings, EU Green Deal implementation documents, KBA registration databases, and IHS Markit vehicle production data. Bottom-up demand modeling from fleet operator surveys was reconciled with top-down market sizing through triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with electric van adoption curves calibrated against charging infrastructure deployment trajectories and battery cost reduction pathways.
The analysis sits within stated boundaries; outcomes outside sustained lithium price stability and charging network build-out assumptions would require recalibration. Forecasts reflect documented assumptions regarding EU CO2 mandate enforcement timelines and IRA tax credit continuity. Battery raw material supply disruptions or tariff regime shifts represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe LCV Rental Market
Commercial Vehicles
Global Light Commercial Vehicles Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Peru Commercial Vehicle Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Asia Three Wheeler Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Gas Powered Commercial Vehicle Market
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Truck-Mounted Road Sweeper Market