
 Cryogenic Road Tankers Market | 2026-2036
Cryogenic Road Tankers Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Road Tankers Market Insights
A capital-intensity divergence between vacuum-insulation specialists and conventional tanker assemblers is redrawing competitive boundaries in cryogenic road transport. Chart Industries leverages its integrated cold-box engineering to anchor North American hydrogen logistics. INOX India Limited sustains cost leadership through captive stainless-steel fabrication and domestic vessel certification. Nikkiso competes in advanced pressure-control systems for liquid helium and LNG trailers.
Cryogenic road tankers are double-walled vacuum-insulated vessels designed to transport liquefied gases at temperatures below minus 150 degrees Celsius, typically constructed with austenitic stainless steel inner shells and carbon steel outer jackets with multi-layer insulation. Their primary purpose is to maintain cryogenic fluid integrity during overland distribution of industrial gases, LNG, and liquid hydrogen. Vacuum insulated tank trailers command the dominant product position due to superior hold-time performance on long-haul routes. The medical sector represents the fastest-growing end-user channel as hospital networks and biobanks expand liquid nitrogen distribution for cryopreservation. Advanced insulation technology is displacing conventional foam systems where boil-off rate thresholds are tightening.
The US DOT regulates cryogenic transport vessel construction through 49 CFR specifications, while the EU enforces ADR and RID frameworks governing hazardous goods movement across member states. China's SAMR and GB standards mandate pressure vessel certifications that foreign manufacturers must navigate for market access. Stakeholders must monitor evolving hydrogen purity requirements and cross-border alignment of cryogenic safety protocols to secure positioning in emerging clean fuel corridors.
Market Dynamics
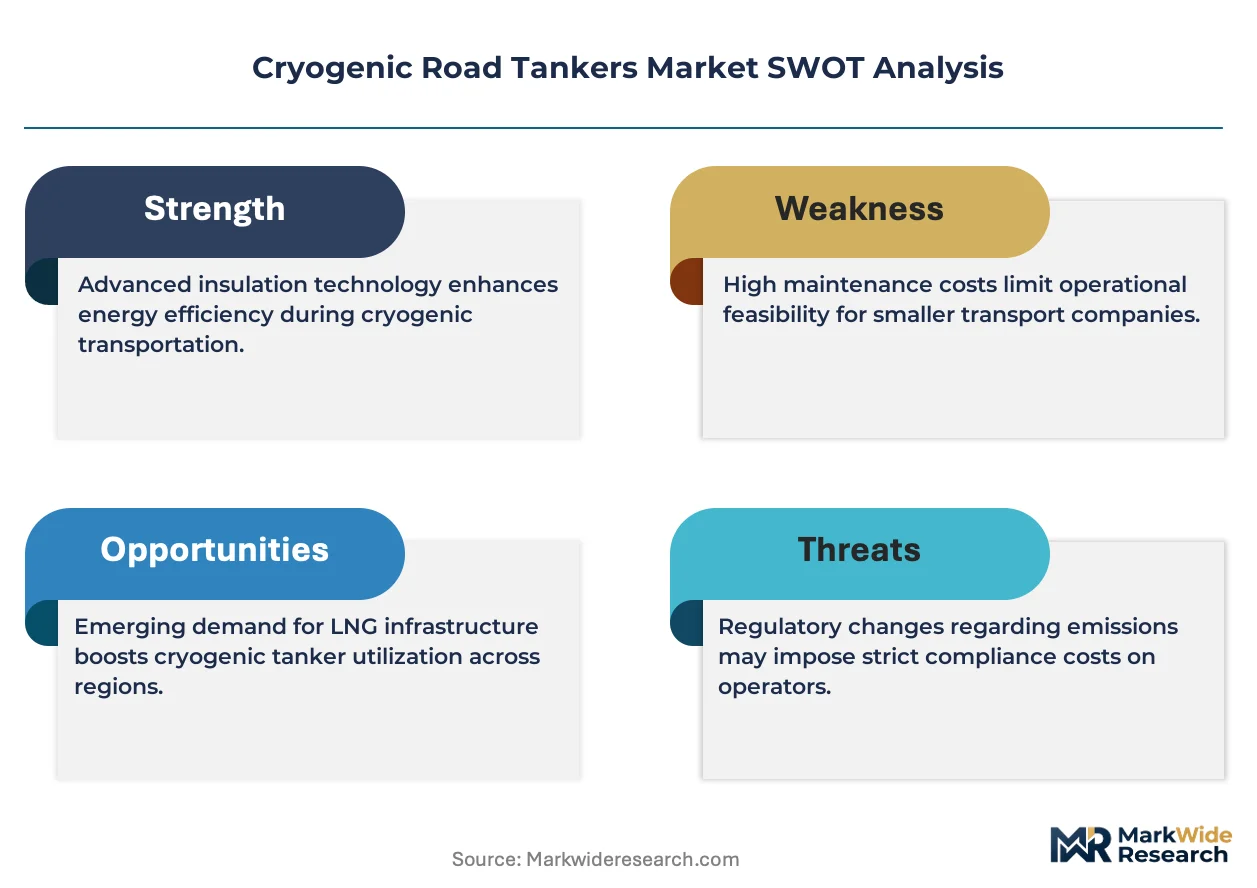
Fleet operators face mounting pressure from thermal-performance mandates that force premature retirement of foam-insulated trailers before standard depreciation cycles conclude.
Growth Catalysts
- Liquid hydrogen corridors:Germany, China, and the United States are deploying dedicated refueling networks that require purpose-built tankers with extended hold times.
- 49 CFR Part 178:The US DOT specification for portable tanks tightens boil-off thresholds, compelling fleet-wide upgrades across North American industrial gas distributors.
- Cryopreservation logistics:Hospital networks and biobanks are expanding liquid nitrogen distribution chains, creating dedicated cold-chain requirements for medical-grade tankers.
Market Restraints
- Austenitic stainless steel concentration:Japanese and German mills control premium-grade 304L/316L supply, exposing fabricators to nickel price volatility and extended lead times.
- Multi-layer insulation complexity:Vacuum-powder and perlite systems require cleanroom assembly conditions that limit production scaling.
- ADR certification timelines:European hazardous goods frameworks impose 18-24 month approval windows for novel vessel designs, freezing product development cycles.
Strategic Opportunities
- India hydrogen hubs:The country's National Hydrogen Mission creates demand for liquid hydrogen trailers connecting coastal import terminals to inland industrial zones.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases accelerate LNG adoption as a transport fuel, expanding cryogenic tanker deployment for bunkering logistics.
- Telematics-integrated insulation monitoring:Real-time boil-off sensing combined with predictive maintenance contracts creates recurring revenue streams for fleet operators.
Industry Challenges
- Vacuum technician scarcity:Specialized welding and leak-detection skills for double-walled vessel fabrication outpace vocational training output in Germany and the United States.
- Cross-border protocol misalignment:Divergent pressure-testing standards between US DOT 49 CFR and EU ADR create duplication costs for manufacturers serving transatlantic markets.
- Legacy fleet stranding risk:Existing foam-insulated tankers face accelerated obsolescence as thermal-performance baselines tighten, compressing residual value recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Road Tankers Market |
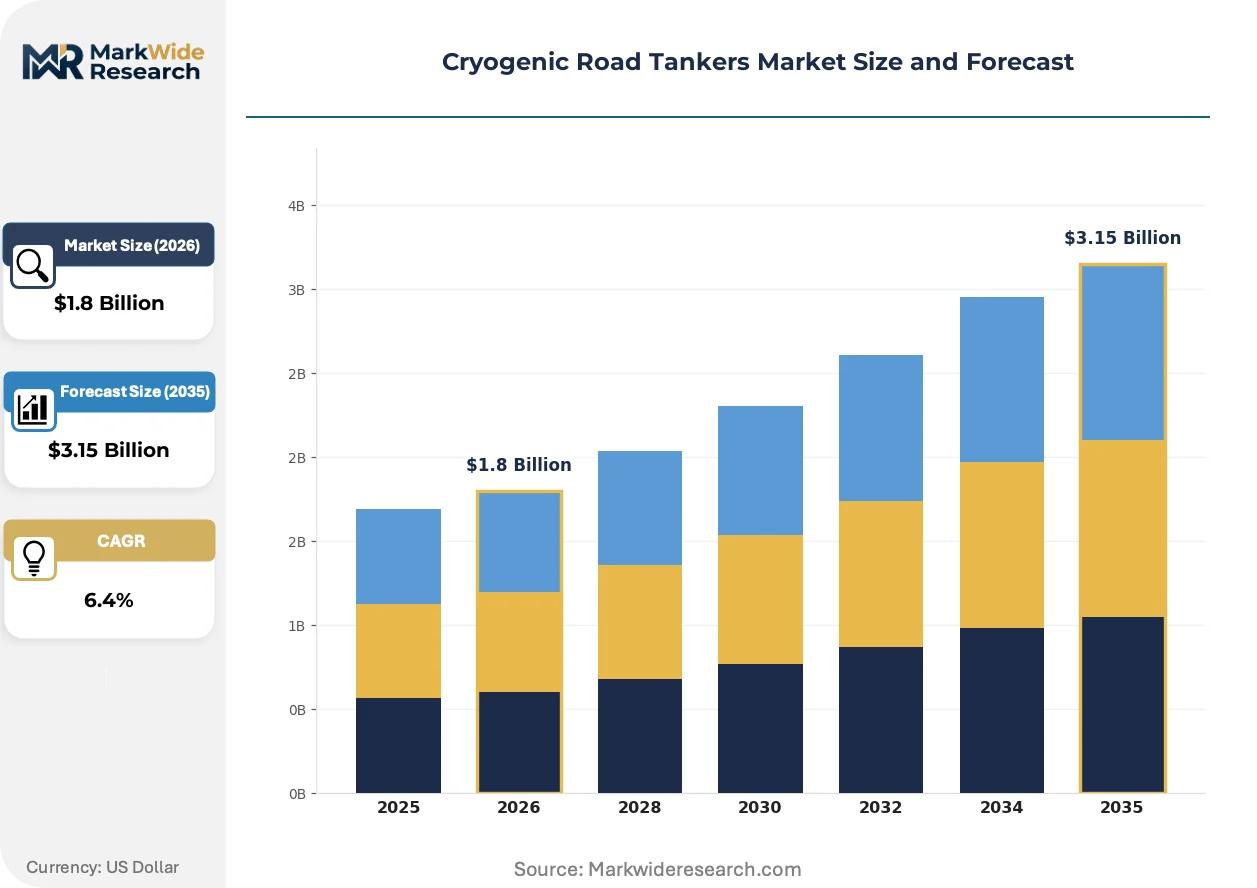
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Insulated, Cryogenic Liquid Cylinder, Tank Trailer, ISO Tank End User: Industrial Gas Suppliers, Chemical Manufacturers, Food & Beverage Industry, Medical Sector Technology: Conventional, Advanced Insulation, Pressure Control, Control System Size: Small Capacity, Medium Capacity, Large Capacity, Customized Solutions |
| Companies Covered | Chart VRV, INOX CVA, Cryogas Equipment Private Limited, CRYOFAB, Nikkiso, Chart Industries, INOX India Limited, Suretank Group, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Road Tankers Market Trends and Innovations
Active thermal-management systems and predictive logistics platforms are compressing operational margins for conventional tanker operators while opening service-based revenue models.
Multi-layer vacuum super-insulation is miniaturizing hold-time performance into lighter-weight vessel geometries. LNG bunkering operators in Rotterdam and Singapore are adopting these systems to maximize payload on weight-restricted road corridors. The technology is miniaturizing the gap between trailer capacity and chassis gross vehicle weight limits, enabling 15-20% volume gains on standard European tractor configurations.
The EU F-Gas Regulation mandates progressive reduction of fluorinated greenhouse gas emissions through 2030. Industrial gas distributors must transition cold-chain logistics away from conventional refrigerants toward cryogenic alternatives. Liquid nitrogen transport contracts are accelerating fastest in pharmaceutical corridors connecting Swissmedic-regulated manufacturing sites to Benelux distribution hubs.
Industrial gas procurement is consolidating under long-term hydrogen supply agreements that bundle tanker provision with molecule delivery. Major chemical processors in the US Gulf Coast and Germany's Rhineland are shifting from equipment ownership to full-service logistics contracts. This restructuring concentrates fleet purchasing authority with fewer buyers, intensifying price negotiation leverage and compressing vendor margins across premium and standard equipment tiers.
Cryogenic Road Tankers Market Segmentation
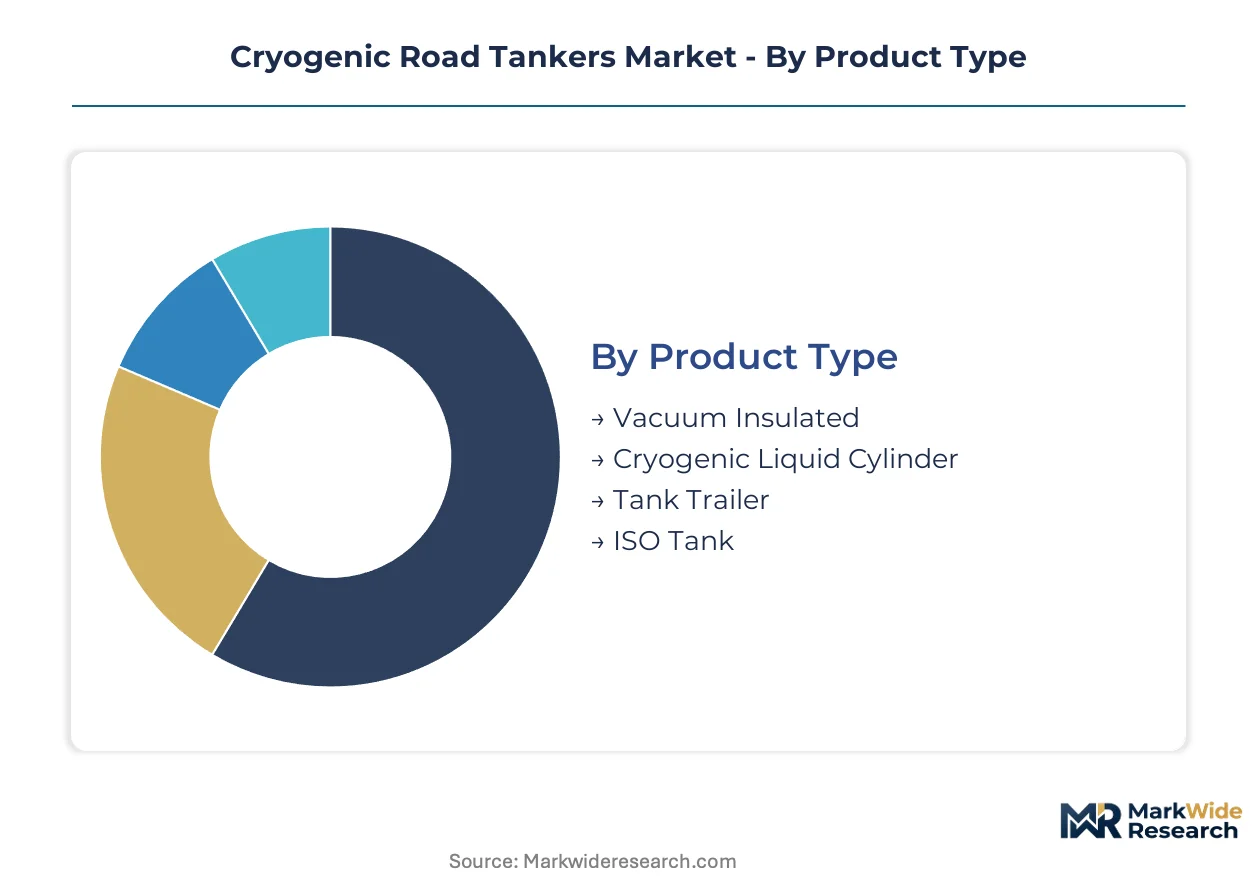
Cryogenic road tanker procurement follows distinct technical and commercial pathways. Regulatory pressure on thermal performance and end-use purity requirements fragment purchasing criteria across vessel categories.
Product Type:
US DOT 49 CFR Part 178 and EU ADR specifications diverge on allowable boil-off thresholds, creating certification-driven procurement preferences.
- Vacuum Insulated:Double-walled vessels with multi-layer insulation achieve hold times exceeding 45 days for liquid hydrogen and LNG. German industrial gas distributors specify these for Rhineland hydrogen corridor routes where thermal performance mandates are strictest.
- Cryogenic Liquid Cylinder:Modular dewar systems serve medical and laboratory distribution with capacities below 500 liters. Swiss hospital networks expanding liquid nitrogen cold chains favor these for last-mile flexibility.
- Tank Trailer:Chassis-mounted vessels dominate overland bulk transport for industrial gas majors. US Gulf Coast chemical processors deploy these for high-volume oxygen and argon distribution.
- ISO Tank:Intermodal containers enable rail-sea-road transfer without cargo handling. Rotterdam LNG bunkering operators specify these for multimodal supply to North Sea ports.
Established volume favors vacuum insulated configurations; emerging adoption favors ISO tank formats for hydrogen export corridors.
End User:
Customer concentration and contract duration reshape fleet ownership models across buyer categories.
- Industrial Gas Suppliers:Linde, Air Liquide, and Air Products operate captive fleets exceeding 10,000 units globally. Their procurement concentrates on 20-year service agreements with embedded maintenance protocols.
- Chemical Manufacturers:US Gulf Coast and German Ruhr Valley processors are shifting from equipment ownership to full-service logistics contracts. This restructuring concentrates purchasing authority with fewer buyers.
- Food & Beverage Industry:Carbon dioxide transport for beverage carbonation drives demand for medium-capacity trailers. European bottlers face EU F-Gas Regulation compliance costs accelerating fleet turnover.
- Medical Sector:Hospital networks and biobanks expanding cryopreservation logistics represent the steepest expansion trajectory. Liquid nitrogen distribution for cell therapy cold chains demands medical-grade certification.
Long-tenure contracts dominate industrial gas supplier procurement; spot-market flexibility defines food and beverage purchasing patterns.
Technology:
Margin compression in conventional systems funds R&D migration toward active thermal management.
- Conventional:Foam-insulated vessels with passive thermal protection face accelerated obsolescence. US DOT boil-off threshold tightening forces premature retirement before standard depreciation cycles conclude.
- Advanced Insulation:Vacuum-powder and perlite systems with multi-layer radiation shields reduce boil-off rates. Cleanroom assembly requirements limit production scaling to specialized fabricators.
- Pressure Control:Automated venting and re-liquefaction systems extend hold times on extended routes. Liquid helium transporters specify these for ultra-low temperature integrity.
- Control System:Telematics-integrated monitoring enables predictive maintenance and real-time boil-off sensing. Fleet operators monetize these through recurring service contracts.
Asset-heavy ownership favors conventional technology; performance-guaranteed service contracts favor control system integration.
Size:
Chassis weight limits and road corridor regulations constrain capacity selection across geographies.
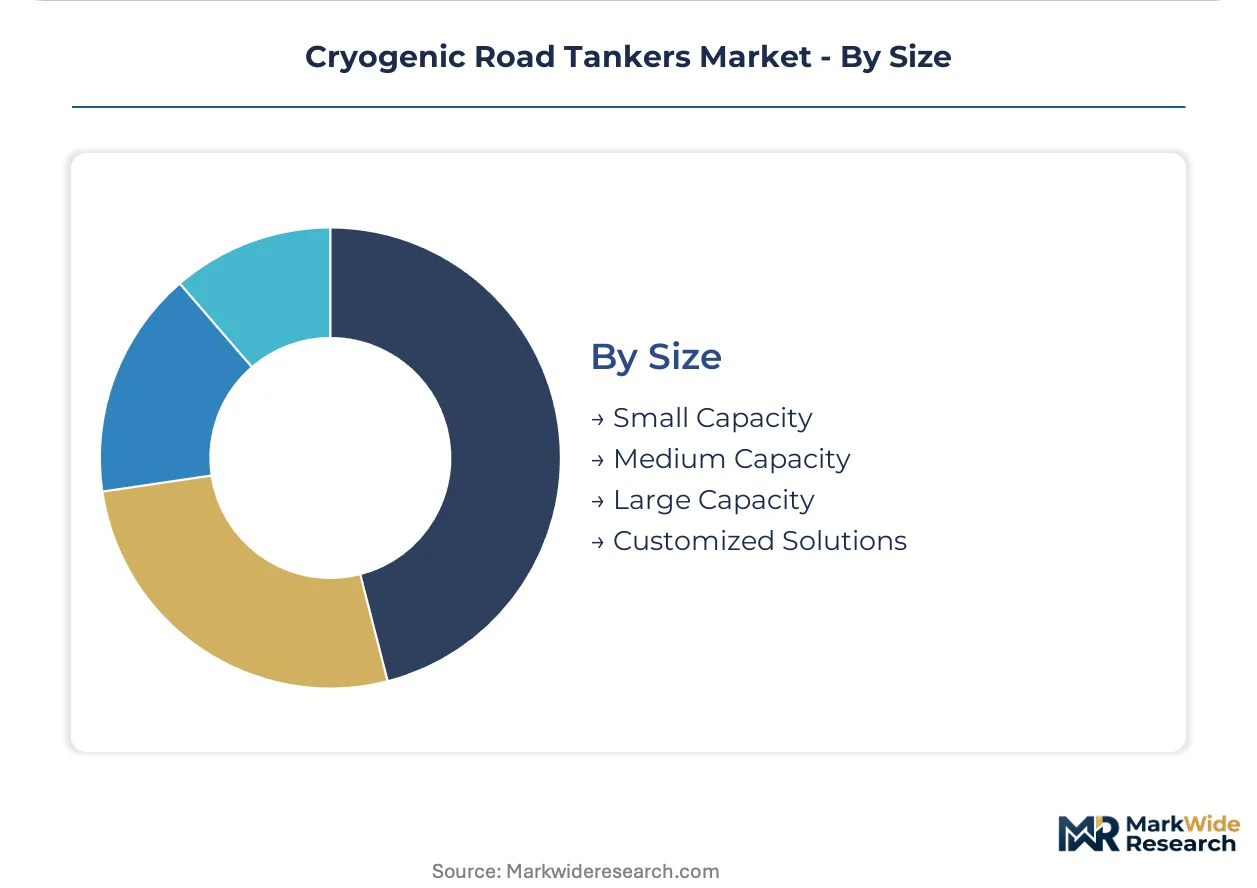
- Small Capacity:Units below 10,000 liters serve urban medical distribution and specialty gas delivery. Tokyo and Singapore hydrogen refueling stations specify these for space-constrained sites.
- Medium Capacity:10,000-30,000 liter vessels balance payload efficiency with route flexibility. Indian National Hydrogen Mission corridors connecting coastal terminals to inland zones favor this format.
- Large Capacity:Exceeding 30,000 liters, these maximize economies on dedicated industrial gas pipelines. German autobahn weight restrictions limit deployment despite thermal efficiency gains.
- Customized Solutions:Purpose-built vessels for liquid hydrogen or helium with extended hold times command premium pricing. NASA and ESA spaceport logistics drive specification innovation.
Standardized fleet economics favor medium capacity; mission-critical applications favor customized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premiums over United States spot markets due to stricter ADR thermal-performance mandates. Chinese fabricators undercut both on standardized vacuum-insulated trailers for domestic hydrogen corridors. Indian procurement concentrates on medium-capacity vessels connecting coastal import terminals to inland industrial zones.
United States
Gulf Coast chemical processors and hydrogen hub developers drive procurement of large-capacity tank trailers. US DOT 49 CFR Part 178 specifications tighten boil-off thresholds, compelling fleet-wide upgrades among industrial gas distributors. Houston and Louisiana corridor operators deploy purpose-built vessels for liquid hydrogen distribution to Texas and California refueling networks.
Germany
Rhineland hydrogen corridor investments and autobahn weight restrictions shape demand for vacuum-insulated configurations with extended hold times. ADR frameworks impose 18-24 month certification windows for novel vessel designs, freezing product development cycles. Ruhr Valley chemical processors shift from equipment ownership to full-service logistics contracts, concentrating purchasing authority.
China
National hydrogen mission targets and coastal LNG import expansion sustain fleet renewal programs. SAMR and GB standards mandate pressure vessel certifications that foreign manufacturers must navigate for market access. Yangtze River Delta and Pearl River Delta industrial clusters deploy medium-capacity trailers connecting coastal terminals to inland manufacturing zones.
India
National Hydrogen Mission creates demand for liquid hydrogen trailers connecting coastal import terminals to inland industrial zones. BIS certification requirements and domestic vessel standards favor local fabricators with captive stainless-steel supply chains. Gujarat and Maharashtra hydrogen hub developers specify medium-capacity vessels for corridor routes to Delhi-NCR industrial zones.
Japan
Liquid helium transport for semiconductor manufacturing and spaceport logistics drives specification innovation in ultra-low temperature integrity. METI industrial policy supports hydrogen supply chain investments, including cryogenic distribution infrastructure. Kyushu and Chubu regional operators adopt advanced pressure-control systems for specialty gas distribution to Tokyo-Osaka manufacturing belts.
Cryogenic Road Tankers Market Competitive Landscape
Concentration sits with integrated industrial gas suppliers and specialized vacuum-insulation fabricators. The vendor base spans captive fleet operators, independent tanker assemblers, and component specialists for multi-layer insulation systems. Two strategic archetypes dominate: stainless-steel fabricators with captive metallurgical supply, and cryogenic engineering houses with integrated cold-box capabilities. Competitive moves center on backward integration into specialty steel supply and geographic expansion through local certification partnerships.
Within the integrated engineering tier, Chart Industries and Chart VRV exemplify cold-box-to-tanker vertical capabilities. INOX India Limited and INOX CVA occupy positions among stainless-steel fabricators with domestic certification advantages. Nikkiso sits within the pressure-control specialist archetype for ultra-low temperature applications.
| Leading Market Players |
|---|
| Chart VRV |
| INOX CVA |
| Cryogas Equipment Private Limited |
| CRYOFAB |
| Nikkiso |
| Chart Industries |
| INOX India Limited |
| Suretank Group |
| Linde plc |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese and German specialty steel mills sits above 85 percent, anchoring austenitic stainless steel price floors and compressing margins for vacuum-insulation fabricators competing on thermal performance. This scale concentration forces smaller assemblers to absorb nickel volatility or surrender market share to integrated producers with captive metallurgical supply.
Pricing Analysis
Configured-to-order pricing for liquid hydrogen trailers with extended hold times commands 40-60 percent premiums over standard vacuum-insulated units for industrial gas distribution. Pricing stratifies across certification tiers, with ADR-compliant vessels for German hydrogen corridors fetching premiums above US DOT-certified equivalents. Cost compression in standard foam-insulated segments is intensifying as fleet operators accelerate premature retirement of non-compliant trailers. Chemical manufacturers shifting to full-service logistics contracts exhibit lowest price sensitivity, while independent fleet operators in food and beverage carbonation remain most exposed to spot-market volatility.
Supply Chain Analysis
Nickel alloy supply from Japanese and German mills creates a single-source vulnerability for 304L/316L austenitic stainless steel, with no qualified alternative suppliers for cryogenic-grade material. Multi-layer insulation systems draw from perlite mining in Greece and Turkey, radiation shield manufacturing in the United States, and cleanroom assembly capacity concentrated in Germany and India. Tariff exposure on Chinese stainless steel inputs threatens cost structures for Indian fabricators serving domestic hydrogen corridors. Distribution runs through industrial gas majors operating captive fleets exceeding 10,000 units, with aftermarket service networks controlled by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid hydrogen corridor deployment sits at sub-15 percent penetration of projected infrastructure needs, creating substantial runway for equipment providers as refueling networks mature. Early-mover positioning in medical-grade cryopreservation logistics offers additional expansion vectors as cell therapy cold chains proliferate.
For Market Incumbents: Fortify backward integration into specialty steel supply to hedge nickel price volatility and secure allocation during mill capacity constraints. Expand cleanroom assembly footprint in India to capture National Hydrogen Mission procurement while ADR certification timelines freeze European product development cycles. Pressure from Chinese fabricators undercutting standardized trailers demands differentiation through active thermal-management system integration. For New Entrants and Emerging Players: BIS certification fast-track partnerships with Gujarat and Maharashtra hydrogen hub developers offer the most penetrable entry vector for domestic market access. Target medium-capacity vessel segments where incumbent concentration is lowest and procurement authority is fragmenting among state-level industrial zone operators. Pursue telematics-integrated service contracts as the primary go-to-market angle, monetizing predictive maintenance rather than equipment margin alone. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vacuum-insulation specialists with demonstrated cleanroom scaling capability over conventional tanker assemblers facing asset stranding. Long-term viability across the analysis window rests on hydrogen purity specification evolution and cross-border regulatory alignment. Monitor ADR-US DOT protocol convergence negotiations as the critical inflection signal for transatlantic market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive 304L/316L supply hedges nickel volatility and secures mill allocation priority. |
| Cleanroom Assembly Expansion | Indian capacity addition captures National Hydrogen Mission procurement windows. |
| Telematics-Integrated Service Contracts | Recurring revenue monetization shifts value capture from equipment to operational performance. |
| ADR Certification Investment | European hazardous goods compliance unlocks Rhineland hydrogen corridor premium pricing. |
| Medical-Grade Certification Pathway | Swissmedic-aligned liquid nitrogen protocols access pharmaceutical cold-chain expansion. |
Research Methodology
Desk research of customs trade data, pressure vessel certification registries, and industrial gas fleet disclosure filings preceded structured interviews with procurement directors at Linde and Air Liquide, maintenance heads at US Gulf Coast chemical processors, and certification engineers at German TÜV bodies. Primary fieldwork with vacuum-insulation fabricators in India and component suppliers for multi-layer radiation shields validated secondary estimates. Bottom-up unit economics for trailer configurations were triangulated against top-down hydrogen infrastructure investment pipelines.
Variance decomposition across insulation technology tiers, vessel capacity formats, and end-user contract structures informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-user industry, technology tier, and regional regulatory cluster. CAGRs were derived from infrastructure deployment timelines and fleet replacement cycles rather than extrapolated historical trends. Forecast inputs incorporated SAMR certification timelines for foreign market access and EU F-Gas Regulation phase-down schedules for LNG bunkering demand.
Decision-makers should treat outputs as directional under assumptions of sustained hydrogen hub investment and stable nickel alloy supply; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as ADR-US DOT protocol alignment and Chinese domestic content requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Europe Van Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
Spain Light Commercial Vehicles Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Europe Light Commercial Vehicle (LCV) Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market