
 Freight Trucking Market | 2026-2036
Freight Trucking Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Trucking Market Analysis
The EPA Phase 3 greenhouse gas standards for heavy-duty vehicles is rebalancing capital allocation across fleet operators and OEMs. United Parcel Service leverages its alternative fuel investments to preempt compliance thresholds. J.B. Hunt Transport Services anchors intermodal expansion through rail-highway integration. FedEx Corporation differentiates via dense last-mile network density in metropolitan corridors.
Freight trucking encompasses the motorized transport of goods using heavy-duty vehicles with gross vehicle weight ratings exceeding 10,000 pounds, powered by diesel, natural gas, battery-electric, or hydrogen fuel cell powertrains. The sector moves raw materials, intermediate components, and finished products between manufacturing plants, distribution centers, retail locations, and end consumers. Full truckload services dominate revenue pools due to contract stability and route efficiency, while refrigerated trucks command premium pricing from pharmaceutical and perishable food shippers. Less than truckload networks face margin compression from e-commerce fulfillment demands for speed and visibility.
The EPA, NHTSA, and DOT collectively shape vehicle emissions thresholds, driver hours-of-service limits, and highway weight restrictions that dictate fleet renewal cycles and operational economics. California's Advanced Clean Trucks regulation extends compliance pressure beyond federal baselines, forcing multi-state operators to standardize zero-emission assets. Stakeholders must monitor powertrain technology cost curves and charging infrastructure deployment to time diesel-to-electric transitions without stranding mid-life assets.
Market Dynamics
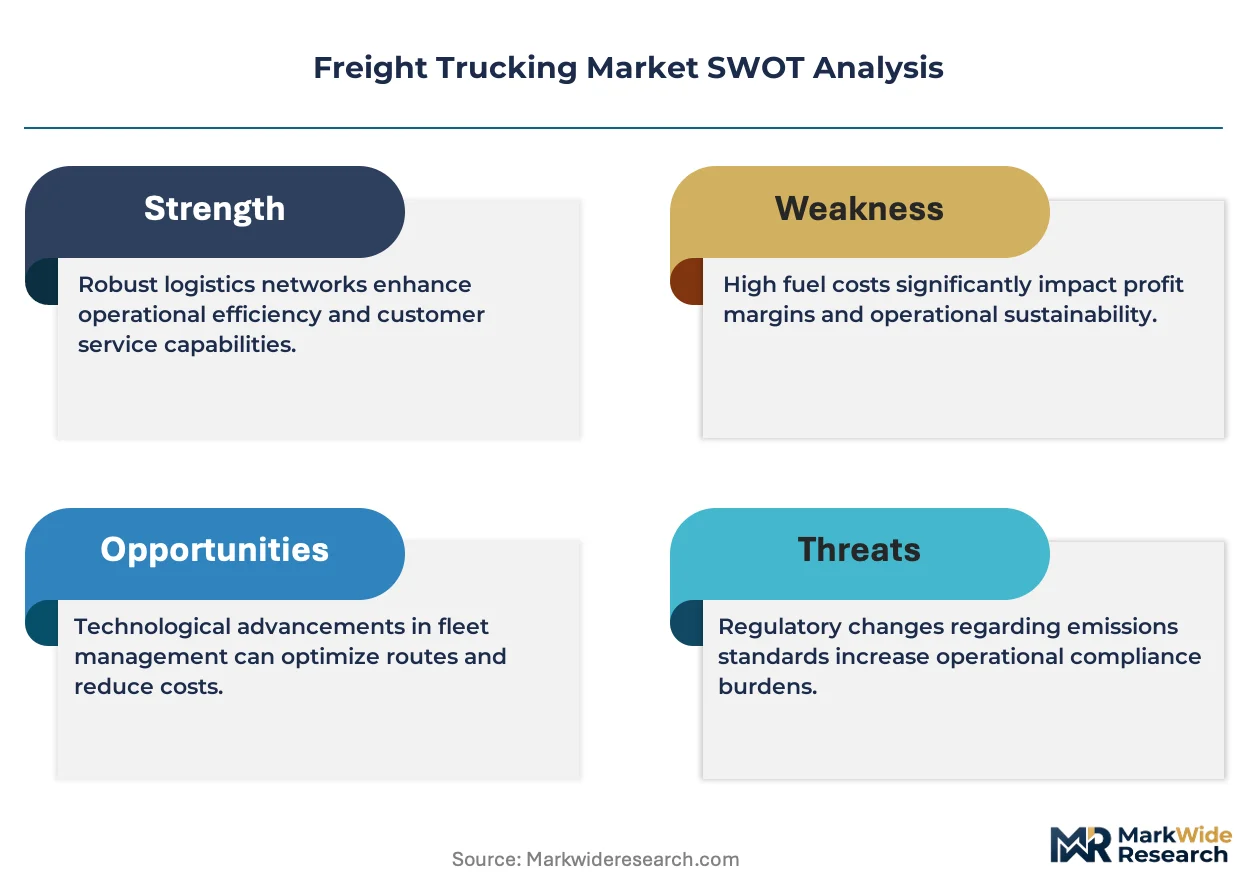
EPA Phase 3 greenhouse gas standards are compressing diesel powertrain procurement timelines while battery-electric and hydrogen fuel cell alternatives mature. Fleet operators face stranded asset risk on mid-life diesel tractors as compliance thresholds tighten through 2035.
Growth Catalysts
- Manufacturing Reshoring:Southeastern United States industrial corridors are generating dedicated contract freight demand as automotive and electronics suppliers relocate production from Asia.
- California Advanced Clean Trucks:The state's zero-emission vehicle mandate is forcing multi-state operators to standardize electric assets across national networks, accelerating fleet turnover.
- Pharmaceutical Cold Chain:Temperature-controlled biologics distribution is expanding dedicated refrigerated fleet partnerships with validated thermal monitoring systems.
Market Restraints
- Lithium-Ion Battery Cost Volatility:Cathode material price swings constrain electric truck total cost of ownership calculations against diesel baselines.
- Charging Infrastructure Gaps:Highway corridor electrification lags fleet deployment schedules, particularly along rural interstate segments.
- Driver Hours-of-Service Limits:Federal Motor Carrier Safety Administration regulations cap utilization rates on long-haul routes regardless of autonomous technology readiness.
Strategic Opportunities
- Intermodal Rail Integration:Highway-to-rail container transfers offer fuel cost arbitrage on corridors exceeding 500 miles between major distribution hubs.
- Last-Mile Electrification:Urban freight zones with congestion pricing are creating captive demand for battery-electric step vans and medium-duty delivery vehicles.
- Hydrogen Fuel Cell Corridor Development:California and Texas are piloting heavy-duty hydrogen infrastructure partnerships with industrial chemical producers.
Industry Challenges
- Technician Skill Shortage:High-voltage electric powertrain diagnostics require certification programs that outpace vocational training pipeline capacity.
- Depreciation Schedule Compression:Regulatory uncertainty around residual diesel asset values is distorting fleet financing and lease structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Trucking Market |
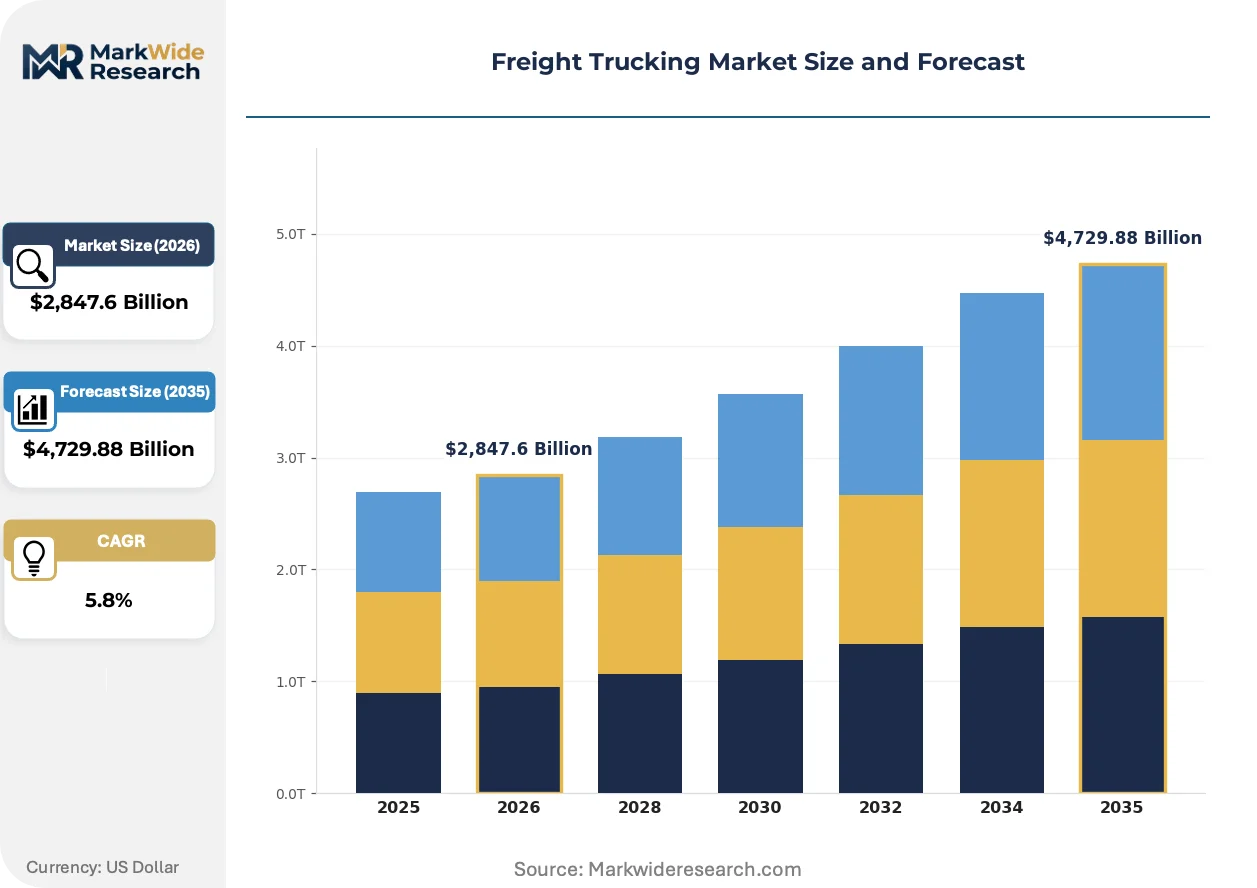
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,729.88 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truckload, Less Than Truckload, Expedited Freight, Intermodal Shipping End User: Manufacturing, Retail, Construction, Agriculture Vehicle Type: Flatbed Trucks, Refrigerated Trucks, Tanker Trucks, Dry Van Trucks Distribution Channel: Direct Shipping, Third-Party Logistics, Freight Brokers, E-commerce Fulfillment |
| Companies Covered | United Parcel Service, FedEx Corporation, J.B. Hunt Transport Services, Knight-Swift Transportation, Schneider National, Old Dominion Freight Line, TFI International, XPO Logistics, Estes Express Lines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Trucking Market Emerging Trajectories
Powertrain electrification is converging with autonomous convoy systems to reshape fleet economics. Regulatory pressure on emissions is accelerating technology substitution timelines beyond historical replacement cycles.
Platooning automation is absorbing driver labor costs on dedicated freight corridors. Major shippers in consumer packaged goods are piloting truck-following systems on Texas and Arizona interstate segments. This technology is absorbing wage inflation pressure while compressing fuel consumption through aerodynamic drafting.
EPA Phase 3 standards are mandating 40% emissions reduction from 2021 baselines for heavy-duty vehicles. Engine manufacturers are diverting R&D expenditure from diesel efficiency improvements toward zero-emission platform development. Long-haul fleet operators are responding by shortening tractor trade cycles to avoid compliance penalties on older assets.
Shippers are consolidating freight procurement through digital brokerage platforms that disintermediate traditional asset-based carriers. Consumer electronics and retail verticals are migrating volume to algorithmic freight matching services. This pattern concentrates most visibly in California and Northeast corridor markets where real-time visibility commands premium pricing.
Freight Trucking Market Segmentation
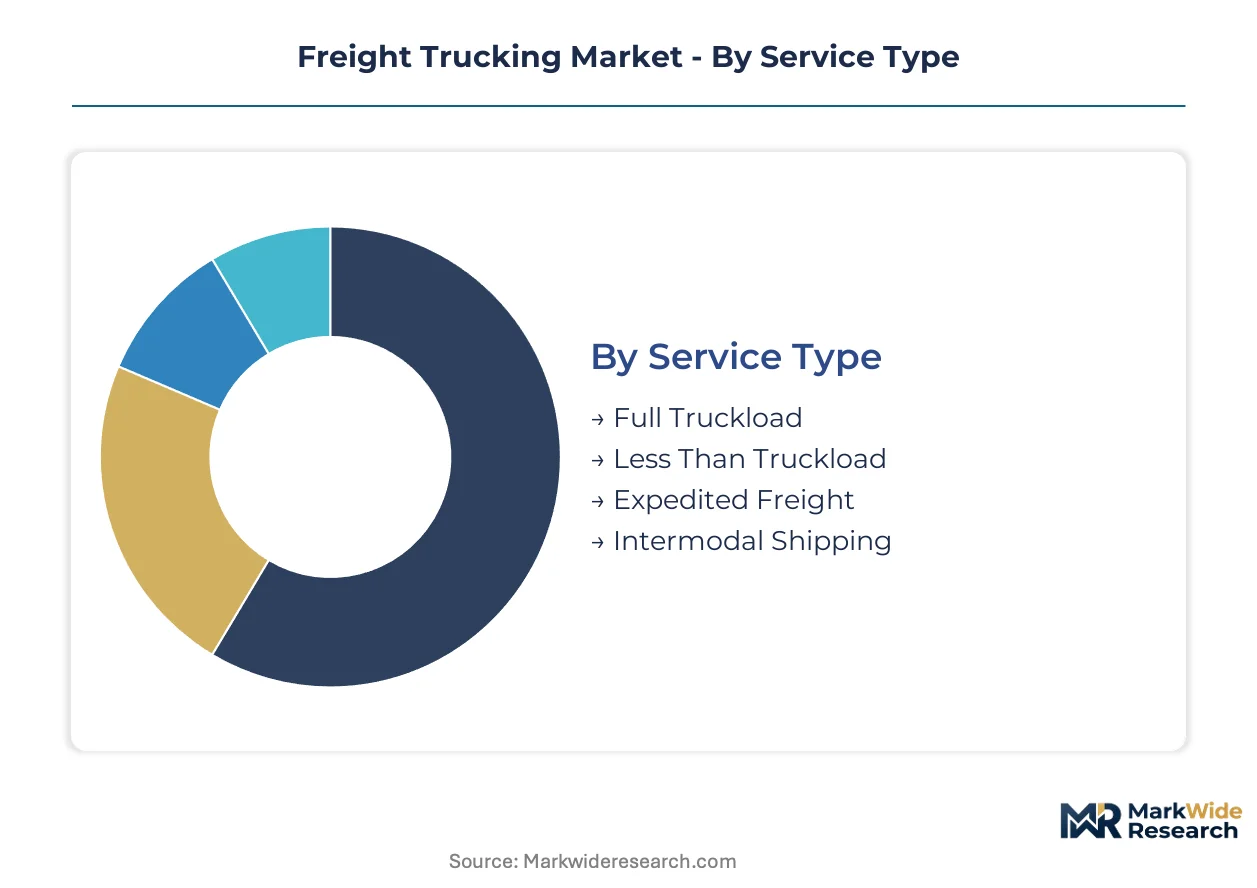
Service configuration dictates capital intensity and contract structure across fleet operators. Shippers select modes based on cargo density, time sensitivity, and route predictability rather than price alone. Vehicle specification and channel access determine margin capture in a market where fuel and labor costs dominate economics.
Service Type:
Shippers prioritize asset utilization rates and contract stability when selecting service tiers, with route density and backhaul economics driving procurement decisions.
- Full Truckload:Dedicated tractor-trailer units move single-shipper cargo from origin to destination without intermediate handling. Contract freight from automotive and electronics manufacturers in the southeastern United States anchors volume, with manufacturers reshoring production from Asia generating dedicated lane demand.
- Less Than Truckload:Consolidated shipments from multiple shippers share trailer capacity through hub-and-spoke terminal networks. E-commerce fulfillment demands for speed and visibility are compressing margins as shippers require real-time tracking and expedited delivery windows.
- Expedited Freight:Time-definite delivery with dedicated drivers and minimal stops for critical inventory replenishment. Pharmaceutical and aerospace shippers in California and Texas corridors generate premium pricing for guaranteed transit times.
- Intermodal Shipping:Containerized cargo transfers between highway and rail modes for long-haul cost arbitrage. Rail-highway integration on corridors exceeding 500 miles offers fuel savings that J.B. Hunt and similar operators leverage for contract competitiveness.
Full Truckload leads on scale; Expedited Freight leads on momentum.
End User:
Vertical-specific cargo characteristics determine equipment requirements and pricing power across customer segments.
- Manufacturing:Raw material inbound and finished goods outbound movements with scheduled delivery windows. Automotive suppliers relocating to Alabama, Tennessee, and South Carolina are expanding dedicated fleet partnerships for just-in-time component delivery.
- Retail:Seasonal volume surges and distribution center replenishment with high trailer turn requirements. Big-box retailers in California and Northeast corridors are consolidating procurement through digital brokerage platforms that disintermediate asset-based carriers.
- Construction:Heavy equipment, aggregates, and building materials transport with specialized flatbed and lowboy configurations. Infrastructure spending in Texas and Florida is expanding demand for overweight permit loads and specialized rigging.
- Agriculture:Seasonal harvest movements and temperature-sensitive produce distribution with harvest-window urgency. California Central Valley operators face California Air Resources Board compliance pressure on diesel refrigeration units.
Manufacturing commands contract stability; Retail is gaining share fastest.
Vehicle Type:
Equipment specialization creates pricing tiers based on cargo protection requirements and regulatory compliance costs.
- Refrigerated Trucks:Insulated trailers with integrated refrigeration units maintain controlled temperatures for perishables and pharmaceuticals. Temperature-controlled biologics distribution is expanding dedicated fleet partnerships with validated thermal monitoring systems that FDA regulations mandate.
- Dry Van Trucks:Enclosed box trailers for general freight without environmental controls. Consumer packaged goods and electronics shippers dominate volume, with EPA Phase 3 standards accelerating turnover toward aerodynamic designs.
- Flatbed Trucks:Open-deck configurations for oversized, irregular, or weather-resistant cargo. Construction and energy sector demand in Texas and North Dakota requires specialized securing equipment and pilot car coordination.
- Tanker Trucks:Cylindrical vessels for liquid bulk commodities including chemicals, food-grade products, and petroleum derivatives. Chemical producers in Texas and Louisiana are piloting hydrogen fuel cell corridor partnerships for zero-emission tanker operations.
Dry Van leads on scale; Refrigerated Trucks lead on momentum.
Distribution Channel:
Channel selection reflects shipper sophistication, volume scale, and tolerance for coordination overhead versus cost savings.
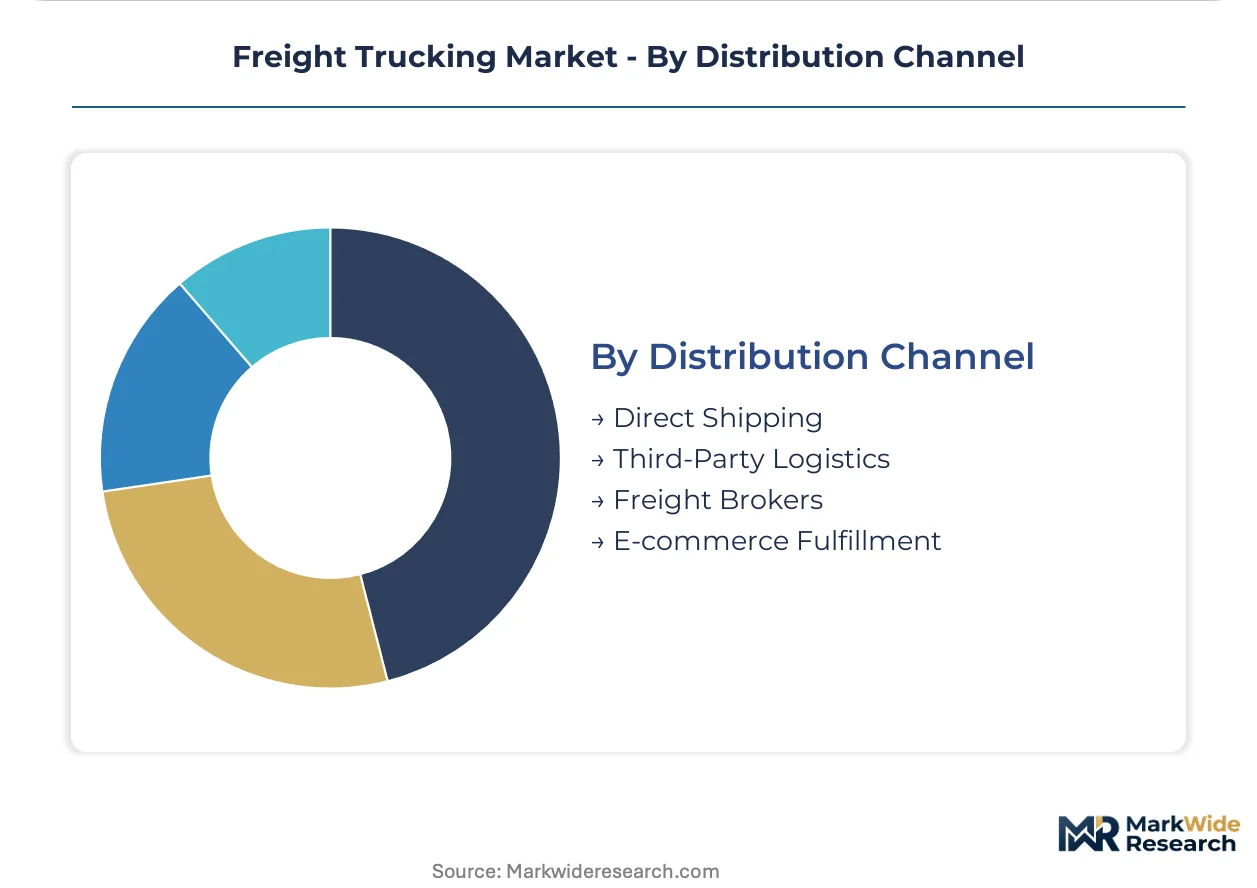
- Third-Party Logistics:Integrated transportation management with warehousing and inventory control bundled. Large shippers in consumer electronics are outsourcing fleet operations to 3PLs with dedicated contract carriage capabilities.
- Freight Brokers:Non-asset intermediaries matching shipper loads with available carrier capacity through digital platforms. Algorithmic freight matching services are concentrating volume in California and Northeast corridor markets where real-time visibility commands premium pricing.
- Direct Shipping:Shipper-operated private fleets with captive equipment and driver employment. Major retailers with predictable volume patterns are expanding private fleet capacity to control service levels and driver retention.
- E-commerce Fulfillment:Last-mile and middle-mile integration with warehouse automation and returns processing. Urban freight zones with congestion pricing are creating captive demand for battery-electric step vans and medium-duty delivery vehicles.
Third-Party Logistics leads on scale; E-commerce Fulfillment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver labor pools and logistics infrastructure density anchor freight trucking demand across distinct industrial corridors. Fleet operators concentrate where manufacturing reshoring, port throughput, and regulatory compliance create sustained contract volume.
United States
Manufacturing reshoring in Alabama, Tennessee, and South Carolina generates dedicated automotive component freight demand. EPA Phase 3 greenhouse gas standards compress diesel procurement timelines while accelerating zero-emission fleet turnover. The Dallas-Fort Worth metroplex anchors intermodal rail-highway integration with expanded inland port facilities.
Germany
Automotive OEM supply chains and chemical industry logistics sustain heavy-duty freight volumes across the Rhine-Ruhr corridor. EU Green Deal emissions targets and Germany's national hydrogen strategy reshape powertrain procurement toward fuel cell alternatives. The Stuttgart industrial region concentrates refrigerated pharmaceutical distribution with validated cold chain infrastructure.
China
E-commerce fulfillment networks and manufacturing export corridors drive medium and heavy-duty fleet expansion. MIIT new energy vehicle mandates and dual carbon goals accelerate battery-electric truck deployment in port cities. The Yangtze River Delta manufacturing cluster generates dedicated container drayage demand with multimodal connectivity.
India
Fast-moving consumer goods distribution and agricultural produce movement sustain fragmented fleet demand across state boundaries. BIS fuel efficiency standards and state-level electric vehicle policies create compliance complexity for national operators. The Delhi-Mumbai Industrial Corridor concentrates contract logistics with dedicated freight infrastructure investment.
Mexico
Nearshoring manufacturing relocation and cross-border trade with the United States expand dedicated lane demand. Mexican federal emissions standards and NOM-044 environmental regulations align with US EPA thresholds for cross-border fleet compatibility. The Nuevo León-Monterrey industrial hub anchors automotive supplier logistics with direct highway-rail connectivity.
Freight Trucking Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across service tiers, creating a bifurcated structure where scale advantages clash with operational agility. Asset-heavy operators with captive equipment dominate contract freight while digital platforms disintermediate spot market transactions. Strategic archetypes include integrated parcel-logistics conglomerates, dedicated contract carriers with specialized equipment, and technology-enabled brokerage platforms. Competitive moves concentrate on intermodal rail partnerships for long-haul cost arbitrage and last-mile electrification for urban compliance.
Within the integrated logistics tier, United Parcel Service and FedEx Corporation exemplify diversification across parcel, freight, and supply chain services. J.B. Hunt Transport Services occupies a position as a dedicated contract carrier with intermodal rail integration capabilities. These three operators represent distinct strategic postures: conglomerate breadth, integrated network density, and modal flexibility specialization respectively.
| Leading Market Players |
|---|
| United Parcel Service |
| FedEx Corporation |
| J.B. Hunt Transport Services |
| Knight-Swift Transportation |
| Schneider National |
| Old Dominion Freight Line |
| TFI International |
| XPO Logistics |
| Estes Express Lines |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap operators anchor contract pricing discipline through long-term shipper relationships that resist digital brokerage erosion. Their captive driver pools and equipment financing structures insulate rate negotiations from spot market volatility while concentrating procurement leverage with OEMs in the southeastern United States.
Pricing Analysis
Bundled full-truckload contracts with dedicated equipment and guaranteed capacity command rate premiums over unbundled spot market transactions. Price differentiation separates fuel-surcharge-adjusted contract tiers from all-in spot pricing, with refrigerated pharmaceutical lanes showing the widest spreads. Cost compression in dry van spot markets is intensifying because digital freight matching platforms aggregate shipper leverage. Small fleet operators exhibit highest price sensitivity, while pharmaceutical shippers accept premium rates for validated cold chain compliance.
Supply Chain Analysis
Diesel powertrain production rests on integrated engine manufacturing in the United States, Mexico, and Germany. Battery-electric alternatives draw from lithium cell suppliers in South Korea, Japan, and China, with cathode material processing concentrated in Chinese chemical complexes. Single-source vulnerability in semiconductor-based telematics and engine control modules creates fleet procurement risk. Distribution runs through OEM dealer networks for new equipment and independent auction channels for secondary tractor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in refrigerated pharmaceutical logistics and intermodal rail-highway integration, where fuel cost arbitrage and compliance premiums offset driver wage inflation.
For Market Incumbents: Extend intermodal rail partnerships beyond 500-mile corridors to capture fuel cost arbitrage against pure highway competitors. Consolidate maintenance capabilities in-house to offset technician skill shortages that threaten fleet uptime guarantees. Vertical integration into charging infrastructure partnerships in California and Texas corridors defends against stranded diesel asset risk under EPA Phase 3 thresholds. For New Entrants and Emerging Players: California Advanced Clean Trucks regulation opens a window for battery-electric fleet specialists to capture compliance-mandated shipper demand. Target urban last-mile delivery zones with congestion pricing regimes where captive demand for electric step vans concentrates. White space exists in hydrogen fuel cell corridor development partnerships with industrial chemical producers in Texas. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light digital brokerage platforms facing margin compression from shipper consolidation. Long-term viability favors operators with intermodal rail integration capabilities and refrigerated pharmaceutical certifications. Watch EPA Phase 3 enforcement acceleration as the inflection signal for zero-emission fleet turnover timing.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Rail Partnership Expansion | J.B. Hunt's rail-highway integration model demonstrates fuel cost arbitrage capture on long-haul corridors. |
| Battery-Electric Fleet Deployment | United Parcel Service leverages alternative fuel investments to preempt EPA Phase 3 compliance thresholds. |
| Hydrogen Fuel Cell Corridor Development | California and Texas pilot partnerships with industrial chemical producers for zero-emission heavy-duty operations. |
| Refrigerated Pharmaceutical Certification | FDA-mandated thermal monitoring systems expand dedicated fleet partnerships with biologics distributors. |
| Digital Freight Matching Platform Integration | Algorithmic brokerage services concentrate volume in California and Northeast corridor markets. |
Methodological Framework
Bottom-up fleet operator modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with fleet procurement directors, terminal operations managers, driver workforce specialists, and shipper logistics coordinators combined with secondary validation from EPA regulatory filings, FMCSA enforcement data, ATA economic reports, and SEC 10-K disclosures. Triangulation across these sources ensures demand-side contract volume estimates align with supply-side equipment production and powertrain technology deployment schedules.
Historical trendline analysis of fleet turnover rates, fuel cost pass-through coefficients, and regulatory compliance cost absorption patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include service type configuration, vehicle powertrain architecture, end-use industry vertical, and regional regulatory cluster. CAGRs derive from equipment replacement cycle compression under EPA Phase 3 standards and manufacturing reshoring freight demand elasticity in southeastern corridor states.
Revisions become necessary when EPA enforcement acceleration, lithium-ion battery cost volatility, or autonomous technology readiness timelines materialize differently than modeled assumptions. Forecasts reflect documented expectations regarding powertrain technology cost curves and charging infrastructure deployment pace. A small set of named triggers—regulatory enforcement intensity, cathode material price swings, and driver labor supply constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Refrigerated Truck Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Van Market
Commercial Vehicles
US Semi-Trailer Dealership Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Global Commercial Vehicle Remote Diagnostics Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Southeast Asia Box Truck Market
Commercial Vehicles
Refrigerated Vans Market