
 Global Timber Trailer Market | 2026-2036
Global Timber Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Timber Trailer Market Outlook
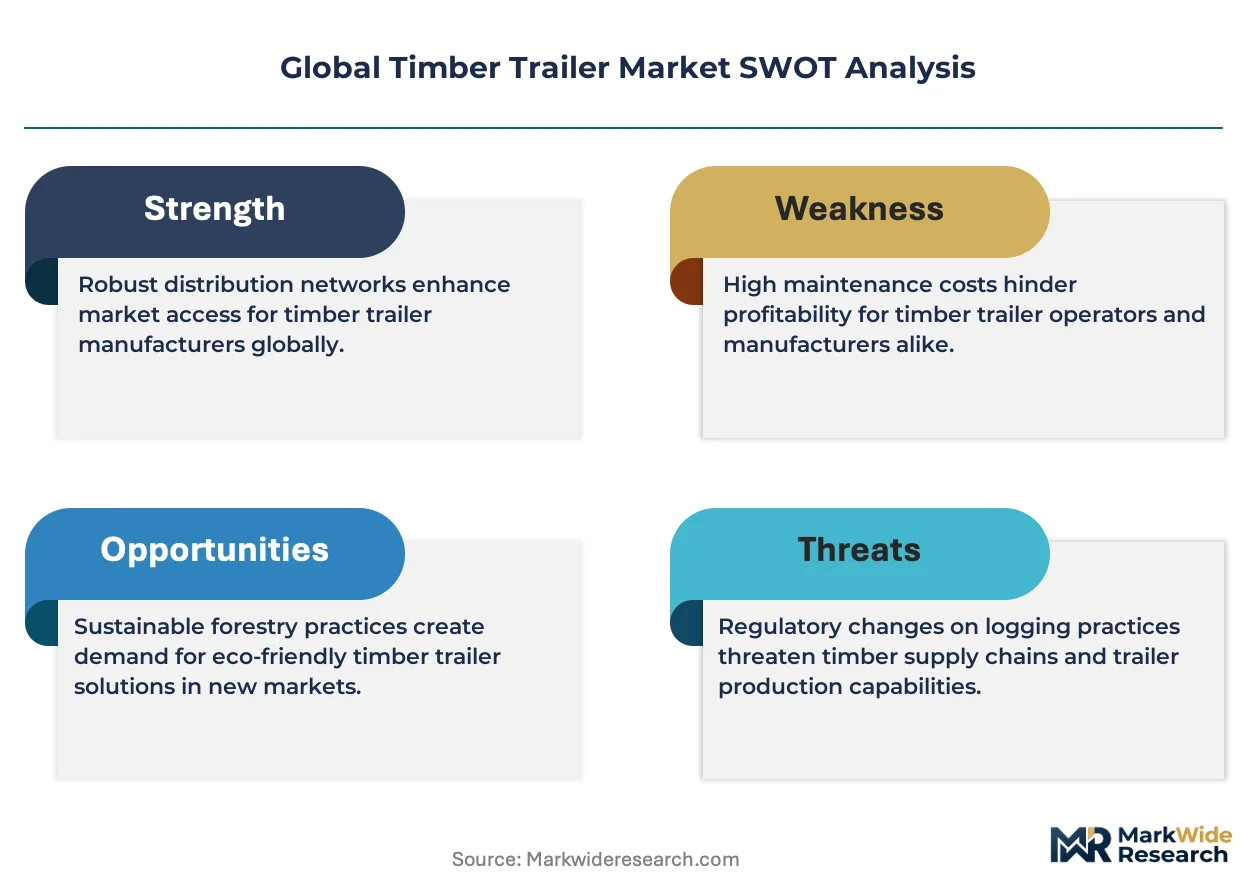
Heavy-duty load rating upgrades across premium timber trailer specifications is unwinding competitive dynamics among established manufacturers. KRONE leverages captive axle production to sustain margin control across Nordic distribution channels. Palms anchors its position through specialized grapple-loader integration for steep-terrain forestry applications in the Baltics. Igland competes on steel-grade customization for extended-reach logging roads in Norway and Finland.
A timber trailer is a purpose-built road transport unit engineered to haul felled logs, typically featuring reinforced steel or aluminum chassis members, hydraulic grapple systems, and rated load capacities exceeding 40 tonnes for off-road extraction routes. Its primary industrial function is bridging the gap between forest harvest sites and mill processing facilities under variable terrain and weather conditions. Flatbed configurations dominate volume shipments across European forestry applications where rapid loading cycles justify premium positioning. Drop deck variants are gaining traction in North American hauling corridors where height-restricted tunnel networks demand lower center-of-gravity designs. Composite material adoption remains nascent but concentrates margin pools among specialty builders serving corrosion-sensitive coastal logging zones in British Columbia and New Zealand.
EU F-Gas Regulation compliance costs are redirecting R&D budgets toward lighter chassis architectures that reduce tractor emissions during laden transport cycles. Sweden's national transport agency enforces periodic brake-system certification that filters out non-compliant imports from Eastern European assemblers. US OSHA logging standards mandate rollover protection structures that reshape trailer-sideguard specifications for cross-border Canadian operators. Stakeholders must monitor diverging weight-per-axle limits between German federal states and Austrian alpine provinces as these determine viable product configurations for Central European fleet renewals.
Market Dynamics
EU F-Gas Regulation enforcement is compressing tractor-trailer weight margins and forcing aluminum chassis adoption across Nordic biomass supply chains. This regulatory pressure cascades through axle ratings, grapple-loader integration requirements, and periodic brake certification protocols.
Growth Catalysts
- Biomass energy quotas:Finland and Sweden have expanded sustainable logging allocations to feed district heating networks. Trailer fleets require higher load-cycle frequency to meet pellet mill intake schedules.
- REACH-compliant aluminum alloys:Lighter chassis materials reduce tractor emissions during laden transport. Swedish transport agencies certify these configurations for extended-reach forest roads.
- Mechanized harvesting expansion:European contractors are replacing manual felling with processor-forwarder systems. Trailer specifications now prioritize hydraulic grapple compatibility over pure payload volume.
Market Restraints
- Steel-grade input volatility:High-tensile chassis steel prices fluctuate with scrap metal arbitrage. Norwegian and Finnish assemblers face margin compression on extended-reach logging road specifications.
- Axle supply concentration:Captive production of heavy-duty axles concentrates among three Nordic component suppliers. Eastern European trailer builders face certification barriers entering Swedish distribution channels.
- Height-restricted tunnel networks:Drop deck variants achieve lower center-of-gravity designs but sacrifice grapple reach. North American operators substitute flatbed configurations where overhead clearance permits.
Strategic Opportunities
- New Zealand coastal corrosion zones:Composite material adoption remains nascent but commands premium positioning. Specialty builders target salt-air degradation in British Columbia and South Island logging operations.
- CSRD disclosure requirements:EU corporate sustainability reporting mandates lifecycle emissions tracking. Trailer-as-a-service models emerge for contractors seeking asset-light fleet renewal.
- Telematics-integrated maintenance:Predictive brake-wear monitoring converges with axle load sensors. Finnish fleet operators pilot subscription-based uptime guarantees.
Industry Challenges
- Hydraulic grapple technician scarcity:Steep-terrain forestry applications require specialized repair skills. Baltic contractors compete for certified service personnel against mining equipment sectors.
- Multi-jurisdiction brake certification:German federal states enforce diverging weight-per-axle limits. Austrian alpine provinces maintain stricter gradient-descent protocols. Cross-border fleet standardization demands redundant compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Timber Trailer Market |
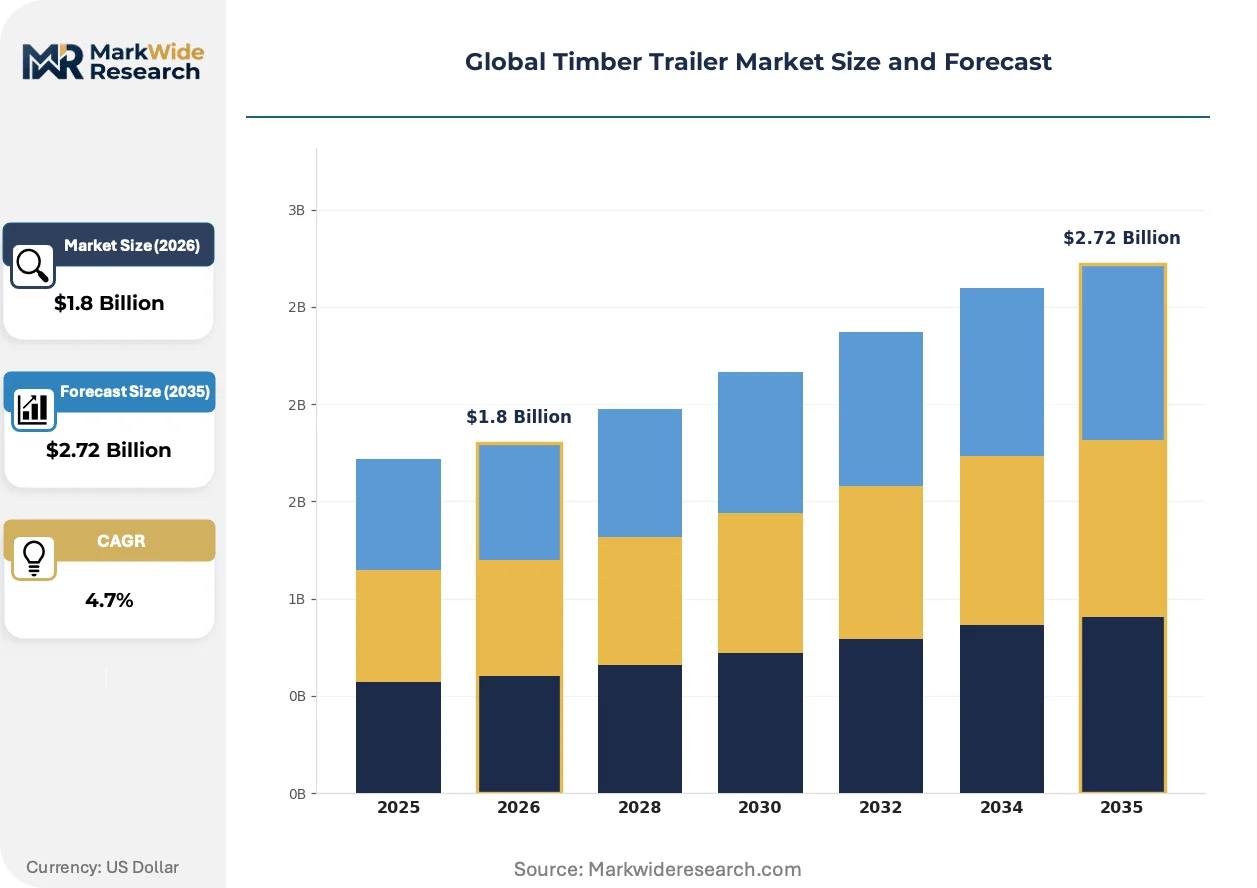
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Enclosed, Drop Deck, Lowboy Material: Aluminum, Steel, Composite, Wood Application: Forestry, Agriculture, Construction, Hauling Vehicle Compatibility: Light Duty Trucks, Heavy Duty Trucks, Trailers, Tractors |
| Companies Covered | Igland, RABAUD, East Manufacturing Company, Trail King Industries, Fors MW, Palms, Fahrzeugwerk Bernard KRONE GmbH & Co. KG, Doepker Industries Limited, Fontaine Commercial Trailer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Timber Trailer Market Strategic Shifts
Active materials substitution and predictive connectivity are compressing traditional specification boundaries. Trailer design now integrates emissions accounting, terrain adaptability, and uptime contracting into unified platform decisions.
Aluminum-intensive chassis architectures are displacing conventional steel construction in EU-regulated biomass corridors. Swedish and Finnish contractors specify these configurations to maintain tractor fuel efficiency under laden cycle conditions. The shift compresses raw material supplier margins while elevating captive aluminum processors.
EU F-Gas Regulation phase-down schedules mandate refrigerant containment in ancillary hydraulic cooling systems. Trailer manufacturers redirect engineering resources toward passive thermal management. Nordic assemblers prioritize Swedish transport agency brake-certification compatibility over southern European payload optimization.
Outcome-based fleet contracting now bundles trailer availability with grapple-loader uptime guarantees. Finnish biomass haulers substitute capital expenditure with per-ton-kilometer service agreements. This procurement restructuring concentrates vendor relationships among vertically integrated Nordic equipment providers.
Global Timber Trailer Market Segmentation
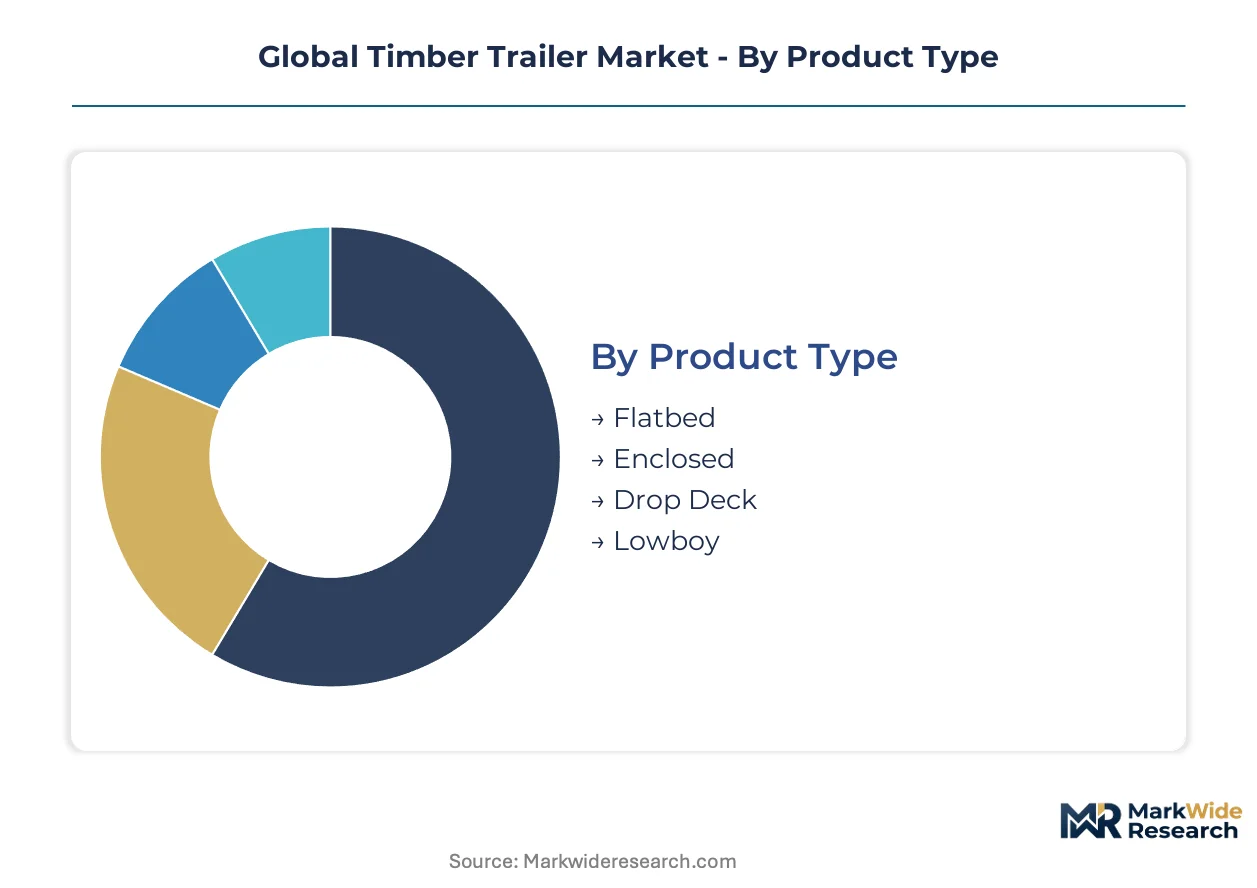
Timber trailer specifications fragment across payload geometry, chassis metallurgy, and tractor coupling standards. Each dimension carries distinct regulatory weight and procurement logic that reshapes vendor positioning across biomass supply chains.
Product Type:
Substitution pressure from mechanized forwarder systems is compressing demand for pure transport configurations while elevating integrated grapple-loader designs.
- Flatbed:Open-deck construction with reinforced side stanchions permits rapid top-loading of processed logs via crane or loader. Finnish pellet mill contractors prioritize these configurations for high-frequency intake cycles at district heating facilities.
- Drop Deck:Lower deck height achieves center-of-gravity reduction for height-restricted tunnel networks. North American operators in British Columbia and Pacific Northwest corridors specify these for mountain pass compliance despite sacrificed grapple reach.
- Enclosed:Weather-protected cargo compartments serve specialized chip and bark transport. Swedish biomass haulers deploy these for moisture-sensitive feedstock deliveries to combined heat and power plants.
- Lowboy:Ultra-low deck height accommodates heavy processor-forwarder equipment transport between harvest sites. Norwegian contractors specify these for machinery relocation across extended-reach logging roads.
Flatbed configurations anchor the volume base while drop deck variants gain share at the steepest rate.
Material:
Cost tier stratification separates premium lightweight alloys from commodity steel grades, with corrosion-resistant composites commanding niche positioning.
- Aluminum:REACH-compliant alloys reduce tractor fuel consumption under laden transport cycles. Swedish transport agency certification programs favor these configurations for extended-reach forest road access.
- Steel:High-tensile chassis members withstand abrasive loading conditions and field repair accessibility. Finnish and Norwegian assemblers source specialized grades for extended-reach logging specifications.
- Composite:Fiber-reinforced polymer construction resists salt-air degradation. Specialty builders target coastal logging zones in British Columbia and New Zealand South Island operations.
- Wood:Traditional plank decking persists in low-intensity Baltic operations. Estonian and Latvian contractors specify these for cost-sensitive short-haul routes.
Steel grades dominate installed fleet value while aluminum-intensive architectures climb the fastest.
Application:
Volume concentration in mechanized harvesting is displacing manual felling support equipment while construction logistics demands divergent payload specifications.
- Forestry:Purpose-built units integrate hydraulic grapple systems and reinforced chassis for log extraction. Biomass energy quotas in Finland and Sweden are expanding fleet renewal schedules.
- Agriculture:Dual-use configurations handle silage, straw, and short-wood biomass. German and Austrian contractors specify these for diversified farm-to-plant operations.
- Construction:Heavy timber beam transport for prefabricated building modules. Norwegian and Swedish builders deploy these for cross-laminated timber project logistics.
- Hauling:General freight adaptation for non-forestry payload versatility. Eastern European operators favor these for seasonal equipment utilization.
Forestry applications anchor the volume base while construction logistics gains share at the steepest rate.
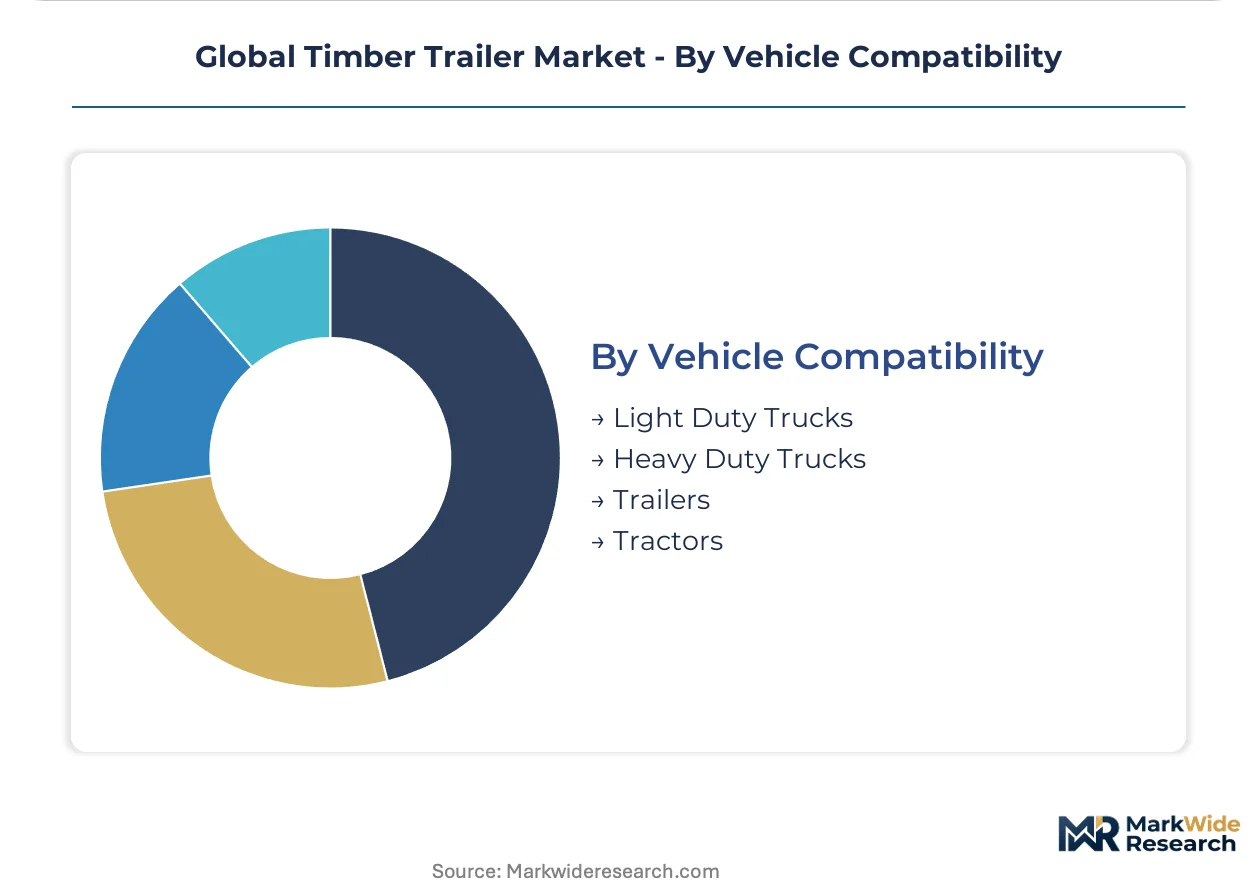
Vehicle Compatibility:
Supply concentration in heavy-duty axle production is filtering fleet standardization toward tractor-trailer configurations over light truck adaptation.
- Heavy Duty Trucks:Three-axle and four-axle tractor units rated for 40+ tonne gross combinations. Nordic biomass haulers standardize on these for pellet mill intake schedules.
- Tractors:Agricultural power units with PTO-driven hydraulic systems for grapple operation. Finnish contractors deploy these for steep-terrain forwarding where road tractors cannot access.
- Light Duty Trucks:Two-axle configurations for farm-scale and short-wood operations. Baltic private woodland owners specify these for sub-10 tonne payload efficiency.
- Trailers:Non-powered towed units for specialized forwarding or dolly applications. Swedish logging cooperatives use these for flexible fleet scaling.
Heavy duty truck compatibility anchors the volume base while tractor-coupled configurations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor Nordic suppliers shipping aluminum-intensive configurations to Central European biomass operators while North American producers concentrate on drop-deck variants for tunnel-restricted corridors.
Sweden
Biomass energy quotas from district heating networks drive fleet renewal schedules across Götaland and Svealand forestry cooperatives. The Swedish Transport Agency enforces periodic brake-system certification that filters non-compliant Eastern European imports. Värmland and Västerbotten counties concentrate mechanized harvesting contractor headquarters where aluminum chassis adoption accelerates.
Finland
Pellet mill intake schedules demand higher load-cycle frequency from trailer fleets serving combined heat and power plants. REACH-compliant aluminum alloys receive preferential certification for extended-reach forest road access. Kainuu and North Karelia regions anchor grapple-loader integration manufacturing clusters serving steep-terrain applications.
Norway
Extended-reach logging road specifications sustain demand for steel-grade customization among coastal and inland contractors. National transport regulators align with Swedish brake-certification protocols to enable cross-border fleet standardization. Trøndelag and Innlandet counties host machinery relocation corridors where lowboy configurations transport processor-forwarder equipment.
Germany
Diverging weight-per-axle limits across federal states reshape viable product configurations for Central European fleet renewals. KBA vehicle certification requirements filter trailer imports against gradient-descent safety protocols. Bavarian and Baden-Württemberg alpine provinces maintain stricter protocols than northern federal states, fragmenting procurement standardization.
Canada
US OSHA logging standards mandate rollover protection structures that reshape trailer-sideguard specifications for cross-border operators. British Columbia coastal logging zones command corrosion-resistant composite material premiums from specialty builders. Pacific Northwest mountain pass corridors drive drop-deck variant adoption where height-restricted tunnel networks dominate routing.
Global Timber Trailer Market Competitive Environment
Concentration sits with Nordic captive-axle producers and specialized grapple-integrators rather than diversified trailer generalists. Three structural archetypes define competitive positioning: vertically integrated chassis-axle manufacturers, steep-terrain grapple specialists, and regional steel-grade customizers. Strategic moves center on aluminum alloy supply chain control and predictive maintenance service bundling rather than pure capacity expansion.
Among Nordic equipment providers, Igland and Palms exemplify divergent specialization archetypes within the same geography, while Fahrzeugwerk Bernard KRONE GmbH & Co. KG anchors the integrated manufacturer tier. KRONE occupies a position defined by captive production of heavy-duty axles that sustain margin control across distribution channels. Palms represents the steep-terrain specialist vector through grapple-loader integration expertise. Igland sits within the steel-grade customization segment serving extended-reach logging road specifications in Norway and Finland.
| Leading Market Players |
|---|
| Igland |
| RABAUD |
| East Manufacturing Company |
| Trail King Industries |
| Fors MW |
| Palms |
| Fahrzeugwerk Bernard KRONE GmbH & Co. KG |
| Doepker Industries Limited |
| Fontaine Commercial Trailer |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Nordic biomass haulers and aluminum processors lock in chassis supply access while freezing input cost visibility across multi-year fleet renewal cycles. Finnish pellet mill contractors leverage these arrangements to secure REACH-compliant alloy allocations ahead of Swedish transport agency certification deadlines.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels in the timber trailer market. Premium tiers bundle Swedish brake-certification compliance with grapple-loader integration, while economy configurations serve Baltic short-haul operators with simplified steel chassis. Cost compression in standard-grade steel is intensifying because scrap metal arbitrage disrupts Nordic assembler margins. Eastern European fleet buyers exhibit highest price sensitivity, whereas Swedish district heating contractors prioritize certification-grade premiums.
Supply Chain Analysis
Inventory cycles for heavy-duty axles stretch 16-20 weeks, forcing Nordic manufacturers to pre-position captive production capacity ahead of seasonal harvesting demand. Supply concentrates in Finland, Sweden, and Germany, with high-tensile steel and REACH-compliant aluminum alloys as critical inputs. Single-source vulnerability runs through three Nordic axle suppliers that control certification-compatible output. Distribution runs through forestry equipment dealer networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-integrated uptime contracting is reconstituting timber trailer procurement as a platform economy where predictive maintenance algorithms and per-ton-kilometer service agreements replace asset ownership. Interoperability between grapple-loader hydraulic systems and fleet management software stacks is becoming the decisive ecosystem battleground.
For Market Incumbents: Compound defensive moats around captive axle production and Swedish brake-certification compatibility to repel Eastern European price competition. Deepen backward integration into aluminum alloy supply through long-term offtake with Nordic smelters. Prioritize predictive maintenance R&D to anchor subscription-based fleet contracts against emerging trailer-as-a-service entrants. For New Entrants and Emerging Players: Differentiate on composite material expertise for British Columbia and New Zealand coastal corrosion zones where specialty builders command premium positioning. Target Baltic steep-terrain contractors underserved by incumbent grapple-technician networks. Pursue white-label manufacturing partnerships with Estonian and Latvian assemblers lacking Swedish certification access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated chassis-axle manufacturers over pure-play trailer assemblers. Five-to-ten year viability hinges on aluminum supply chain control and telematics platform ownership. Acquisition targets should display captive component production plus Swedish transport agency certification lineage. Monitor Finnish fleet operator adoption of per-ton-kilometer contracts as inflection signal for asset-light model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Alloy Supply | Captive REACH-compliant material access secures Swedish transport agency certification pipelines against scrap volatility. |
| Predictive Maintenance Platform Development | Telematics-integrated brake-wear monitoring enables Finnish fleet operators to pilot subscription uptime guarantees. |
| Composite Material Manufacturing Scale-Up | Fiber-reinforced polymer capacity targets salt-air degradation premiums in British Columbia coastal logging zones. |
| Swedish Brake-Certification Compliance Investment | Swedish Transport Agency alignment filters non-compliant Eastern European imports from Nordic distribution channels. |
| Trailer-as-a-Service Model Launch | Per-ton-kilometer contracting addresses EU CSRD disclosure requirements for biomass haulers seeking asset-light renewal. |
Study Parameters
Desk research of customs trade databases, EU regulatory filings, and forestry equipment registration records preceded structured interviews with Nordic trailer procurement managers, Swedish transport agency certification officers, Finnish biomass hauler fleet directors, and aluminum alloy procurement leads. Primary fieldwork validated chassis metallurgy trends and grapple-loader integration specifications against secondary trade flow analysis. Bottom-up unit economics triangulated with top-down sector expenditure estimates.
Variance decomposition across product type, chassis material, application end-use, and vehicle compatibility dimensions shaped the analytical framework over the projection horizon. CAGRs derived from modeled replacement cycles and mechanized harvesting penetration curves. Industry-specific inputs incorporated Swedish brake-certification compliance rates and Finnish pellet mill intake schedule intensities.
Material uncertainties — steel-grade price volatility, EU F-Gas Regulation phase-down acceleration, and hydraulic grapple technician availability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomass energy quota expansion and Nordic fleet renewal timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Three-Wheeler Market
Commercial Vehicles
Freight Trucking Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Malaysia Box Truck Market
Commercial Vehicles
Commercial Vehicle (CV) Active Power Steering Market
Commercial Vehicles
India Commercial Vehicle (CV) Market
Commercial Vehicles
Mining Truck Market
Commercial Vehicles
North America Van Market
Commercial Vehicles
United States Commercial Vehicles Market
Commercial Vehicles
Europe Vacuum Truck Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Commercial Vehicle Transmission Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Flatbed Semi-Trailer Market