
 Global Chip Scale Package (CSP) LED Market | 2026-2036
Global Chip Scale Package (CSP) LED Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chip Scale Package (CSP) LED Market Intelligence
The emergence of fab-lite and asset-light manufacturing strategies is fragmenting the supplier base by lowering capital entry barriers. Established players like OSRAM Opto Semiconductors leverage extensive R&D capabilities for high-performance automotive applications. In contrast, Samsung Electronics dominates display backlighting through its massive manufacturing scale and vertical integration into consumer devices. Nichia Corporation specializes in high-CRI white LED technologies for premium lighting segments.
Chip Scale Package (CSP) LEDs are semiconductor light-emitting diodes packaged to be the same size or no more than 20% larger than the chip itself. This direct-mount, lens-free architecture enables extreme miniaturization and high lumen density for modern electronics and lighting systems. While display backlighting in consumer electronics remains a foundational application, automotive lighting represents the fastest-growing opportunity. Flip chip designs and high-efficacy white LEDs are the dominant product types, commanding significant volume.
Product design must comply with a matrix of international standards, including the EU's RoHS directive on hazardous substances. Energy efficiency programs like the US EPA's ENERGY STAR and China's GB standards for lighting products directly influence component selection. Navigating the thermal management challenges associated with higher power densities is the critical engineering decision for next-generation product development.
Market Dynamics
The market's central dynamic is the bifurcation of its supply base. One segment, driven by automotive demands, invests heavily in R&D for high-reliability, high-performance components. The other segment, serving consumer electronics, competes on massive scale and cost efficiency, a split accelerated by fab-lite manufacturing models.
Growth Catalysts
- Flip Chip Architecture:The adoption of flip chip designs, which offer superior thermal performance and a smaller form factor, enables higher power densities. This is critical for advanced automotive headlighting systems and compact consumer electronics.
- Energy Efficiency Mandates:Regulations like the EU's energy efficiency directives and the US EPA's ENERGY STAR program compel luminaire manufacturers to adopt higher-efficacy light sources, directly benefiting the performance characteristics of CSP LEDs.
- Automotive Sector Demand:The automotive industry's shift toward adaptive driving beam (ADB) systems and signature lighting designs requires compact, powerful, and individually addressable light sources, a key strength of CSP LED technology.
Market Restraints
- Thermal Management Complexity:The high lumen density of CSP LEDs generates significant localized heat. Inadequate thermal dissipation engineering can lead to color shifting, reduced lifespan, and catastrophic failure, acting as a barrier to adoption in thermally constrained designs.
- Phosphor Material Costs:Achieving high Color Rendering Index (CRI) in white LEDs depends on sophisticated and often costly phosphor materials. This price premium limits the use of high-quality CSP LEDs in cost-sensitive general lighting and consumer applications.
- MicroLED Substitution Risk:In high-resolution direct-view display applications, emerging MicroLED technology presents a long-term substitution threat, offering potentially higher brightness, efficiency, and lifetime compared to current LED-based backlighting solutions.
Strategic Opportunities
- Horticultural Lighting:The expansion of controlled environment agriculture creates an opportunity for CSP LEDs tailored to specific spectral outputs. These can optimize plant growth, increasing crop yields and quality in vertical farms and greenhouses.
- Sensor Integration:Combining CSP LEDs with miniaturized photodetectors and microcontrollers on a single substrate enables the creation of smart lighting nodes. These integrated modules can support presence detection, ambient light sensing, and networked controls for IoT applications.
- UVC Disinfection Systems:The development of CSP LEDs that emit in the UVC spectrum opens new markets in surface, air, and water disinfection. Their compact size allows for integration into consumer appliances, HVAC systems, and portable sanitizing devices.
Industry Challenges
- White Light IP Licensing:A dense patent landscape controlled by established incumbents surrounds the core technologies for converting blue LED light into white light via phosphors. This creates substantial licensing costs and legal risks for new market entrants. *Lack of Standardization: The absence of standardized package footprints and thermal interface specifications among different CSP LED manufacturers complicates luminaire design. This forces OEMs into costly redesigns when second-sourcing components or upgrading products.
- RoHS Compliance Overhead:Adhering to the EU's RoHS directive and similar global regulations on hazardous substances requires rigorous supply chain tracking and material testing. This adds significant administrative and compliance costs, particularly for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chip Scale Package (CSP) LED Market |
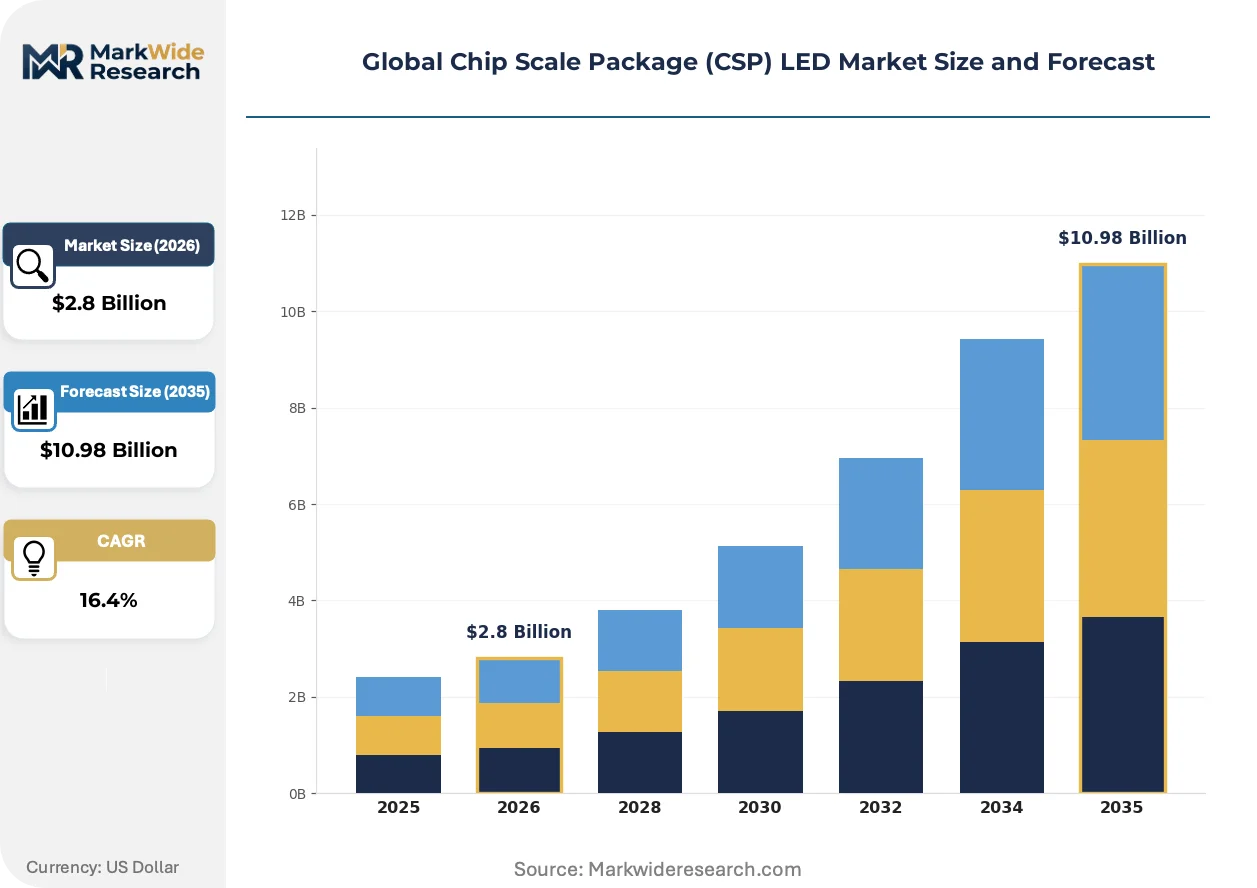
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top Emission, Side Emission, Flip Chip, White LED, RGB LED Technology: Solder Bumping, Wire Bonding, Flip Chip Assembly, Tape Automated Bonding, Laser Direct Structuring Application: Display Backlighting, Automotive Lighting, Consumer Electronics, Wearable Devices, Signage End User Industry: Electronic Manufacturing, Consumer Goods, Transportation Equipment, Telecommunications, Lighting Solutions |
| Companies Covered | OSRAM Opto Semiconductors, LG Innotek, Samsung Electronics, Genesis Photonics, Cree LED, Nichia Corporation, Seoul Semiconductor, EPISTAR, Lumileds Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chip Scale Package (CSP) LED Market Strategic Shifts & Innovations
Product design is shifting from treating illumination as a separate component to integrating light directly into materials and surfaces. This evolution is driven by the extreme power density and small form factor of CSP technology, making light a more fundamental design element.
Miniaturization beyond the chip-scale concept is leading to dot-LEDs and pixelated light sources that are barely visible when inactive. Automotive and consumer electronics designers are rapidly adopting these for dynamic signaling and micro-displays. This granular control over individual light points is digitizing surfaces, transforming static panels into interactive, information-rich displays and creating new user interface paradigms.
New federal rules in the United States now permit adaptive driving beam (ADB) headlamp systems, aligning with standards already common in Europe and Asia. This policy change creates a substantial new addressable market for high-resolution matrix headlamps. Automotive lighting suppliers are consequently prioritizing the development of multi-pixel CSP LED arrays to capture this opportunity in the US market.
Automotive OEMs are increasingly bypassing Tier-1 lighting system suppliers to engage directly with LED manufacturers for custom module development. This disintermediation compresses design cycles and gives carmakers greater control over signature lighting elements that define brand identity. This trend is most pronounced in the premium electric vehicle segment, where unique and dynamic lighting is a key differentiator.
Global Chip Scale Package (CSP) LED Market Segmentation
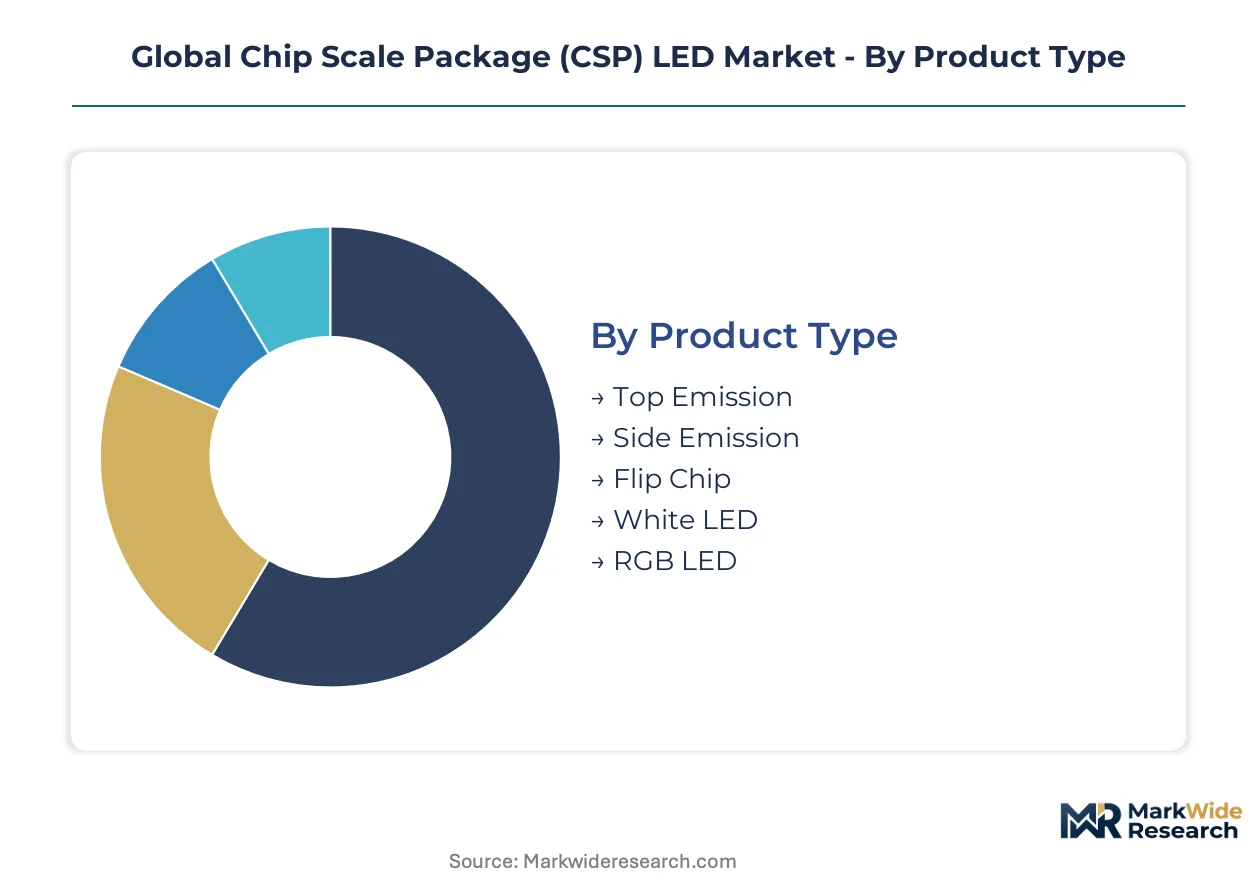
The Global Chip Scale Package (CSP) LED Market segmentation highlights distinct value propositions and technical requirements across diverse applications. This analysis reveals how different product architectures and manufacturing processes cater to varied end-use demands. Understanding these distinctions is crucial for identifying market opportunities and navigating competitive landscapes.
Product Type:
The intensity of after-sales service and technical support varies significantly across CSP LED product types, reflecting their complexity and application criticality.
- Flip Chip:These LEDs feature direct electrical contact to the substrate, eliminating wire bonds and enabling superior thermal performance. Demand concentrates in automotive headlighting systems, driven by requirements for higher power density and reliability.
- White LED:These diodes typically use a blue LED chip coated with phosphor to produce white light, crucial for general illumination and display backlighting. Demand is high in consumer electronics and premium lighting segments due to efficiency and color quality.
- Top Emission:Light exits primarily from the top surface of the chip, a traditional configuration for many standard LED applications.
- Side Emission:Light is directed horizontally from the chip's edges, often used for edge-lit display backlights or specific optical designs.
- RGB LED:These combine red, green, and blue emitters on a single package to create a full spectrum of colors, essential for dynamic signage and display technologies.
White LED holds the largest share; momentum sits with Flip Chip.
Technology:
Cost tier differentiation significantly influences technology choices, with high-volume applications favoring economical processes and specialized uses demanding advanced, often pricier, methods.
- Flip Chip Assembly:This advanced packaging technique involves inverting the LED chip and directly bonding it to the substrate, eliminating wire bonds. Demand is high in high-power applications like automotive lighting, where thermal management is critical.
- Solder Bumping:This method uses microscopic solder balls to create electrical and mechanical connections between the chip and the substrate, offering robust electrical contact. It is widely used in consumer electronics for its cost-effectiveness and reliability in mass production.
- Wire Bonding:Fine wires connect the LED chip's electrical pads to the package leads, a traditional and versatile packaging method.
- Tape Automated Bonding:This process mounts semiconductor devices onto a flexible circuit board, enabling high-density, fine-pitch interconnections.
- Laser Direct Structuring:Lasers create conductive patterns directly on plastic parts, allowing for highly integrated and miniaturized circuit designs.
Flip Chip Assembly represents the fastest-growing trajectory.
Application:
Volume requirements dictate the scale of manufacturing and supply chain configurations for CSP LED applications.
- Automotive Lighting:CSP LEDs provide compact, high-brightness illumination for headlamps, adaptive driving beam systems, and signature lighting elements. Demand accelerates with the shift towards advanced vehicle lighting designs and electric vehicle proliferation.
- Display Backlighting:These LEDs illuminate LCD panels in televisions, smartphones, and monitors, providing uniform brightness and color accuracy. Samsung Electronics utilizes this segment through its massive manufacturing scale and vertical integration into consumer devices.
- Consumer Electronics:CSP LEDs are integral to compact devices like cameras, flashlights, and portable projectors due to their small footprint and efficiency.
- Wearable Devices:Their miniaturization and low power consumption make CSP LEDs ideal for smartwatches, fitness trackers, and augmented reality glasses.
- Signage:High-brightness CSP LEDs enable vibrant and energy-efficient outdoor and indoor digital displays and billboards.
Automotive Lighting is expanding most quickly, while Display Backlighting maintains significant volume.
End User Industry:
Supply concentration within end-user industries determines the purchasing power and technical specifications demanded from CSP LED manufacturers.
- Transportation Equipment:This industry integrates CSP LEDs into automotive headlamps, interior lighting, and signaling systems, prioritizing reliability and performance. The shift to adaptive driving beam systems in the US creates a substantial new market for high-resolution matrix headlamps.
- Electronic Manufacturing:Manufacturers of diverse electronic devices utilize CSP LEDs for backlighting, indicators, and compact illumination needs. Demand is concentrated within the consumer electronics supply chains of South Korea and Taiwan, driving high-volume production.
- Consumer Goods:CSP LEDs are incorporated into household appliances, personal care devices, and smart home products for illumination and indicator functions.
- Telecommunications:These LEDs find use in fiber optic communication systems, network equipment indicators, and compact data transmission applications.
- Lighting Solutions:This segment includes general illumination products, architectural lighting, and specialized luminaires, valuing high efficacy and compact form factors.
Transportation Equipment shows the steepest expansion trajectory, with Electronic Manufacturing representing the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for CSP LEDs exhibits a significant asymmetry, with established manufacturers in Japan and Germany often commanding premiums for high-performance automotive components. In contrast, the high-volume consumer electronics supply chains in South Korea and China prioritize cost efficiency, driving intense competition. This bifurcation influences regional investment and manufacturing strategies.
United States
Demand for CSP LEDs in the United States accelerates due to new federal rules permitting adaptive driving beam (ADB) headlamp systems. The US EPA's ENERGY STAR program also pushes for higher-efficacy light sources. Automotive lighting suppliers in Michigan rapidly develop multi-pixel CSP LED arrays for this new market opportunity.
Germany
German automotive manufacturers drive demand for high-reliability CSP LEDs, particularly for premium vehicle lighting and advanced driver-assistance systems. The EU's RoHS directive influences material selection. Munich's automotive technology clusters focus on integrating compact, powerful CSP LEDs into next-generation vehicle platforms.
South Korea
South Korea's consumer electronics industry fuels massive demand for CSP LEDs in display backlighting and compact portable devices. The Ministry of Trade, Industry and Energy supports R&D into advanced semiconductor packaging. Major electronics manufacturers in Seoul and Gyeonggi Province integrate these components into smartphones and high-resolution displays.
China
China's vast manufacturing base and domestic automotive market generate substantial volume requirements for CSP LEDs. GB standards for lighting products encourage energy-efficient designs, benefiting CSP LED adoption. Shenzhen's electronics manufacturing hubs are critical for the high-volume production and assembly of CSP LED modules.
Japan
Japanese manufacturers prioritize high-CRI white LED technologies and precision optical components for premium lighting and specialized industrial applications. METI initiatives support innovation in advanced materials. Companies in the Kanto region lead in developing miniaturized, high-efficacy CSP LEDs for sophisticated optical systems.
Global Chip Scale Package (CSP) LED Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying foundational CSP LED technology. The market exhibits a bifurcated structure, with high-performance, R&D-intensive players serving automotive demands and mass-scale manufacturers dominating consumer electronics. Strategic archetypes include innovation-driven specialists, vertically integrated consumer electronics giants, and broad-portfolio lighting solution providers. Companies pursue strategic partnerships for technology co-development and expand manufacturing capacity to achieve economies of scale.
On the premium-tier vector, OSRAM Opto Semiconductors exemplifies a focus on extensive R&D capabilities for high-performance automotive applications, emphasizing reliability and longevity. Samsung Electronics, a South Korean conglomerate, occupies a position at the scale-driven end, leveraging massive manufacturing capabilities and captive supply into consumer devices, particularly for display backlighting. Nichia Corporation, a Japanese specialist, anchors the high-CRI white LED segment, catering to premium lighting applications where color quality and efficiency are paramount. These players collectively shape the market's technological trajectory and volume dynamics.
| Leading Market Players |
|---|
| OSRAM Opto Semiconductors |
| LG Innotek |
| Samsung Electronics |
| Genesis Photonics |
| Cree LED |
| Nichia Corporation |
| Seoul Semiconductor |
| EPISTAR |
| Lumileds Holding B.V. |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost dynamics directly influence CSP LED supply concentration and downstream price differentiation across consumer electronics and automotive lighting. This market's structure reflects a constant tension between high-volume, cost-optimized production and specialized, performance-driven manufacturing requirements for advanced applications.
Pricing Analysis
Configured-to-order pricing for specialized automotive CSP LEDs contrasts sharply with standard pricing for high-volume consumer electronics components. The dominant pricing model combines long-term contract-based offtake for automotive applications with per-unit transactional sales for display backlighting. Price differentiation stems from quality grade, customization level, and volume scale. Pricing softness runs through the consumer electronics segment due to intense competition, while automotive OEMs show lower price sensitivity for high-reliability components.
Supply Chain Analysis
Export control regimes impacting semiconductor manufacturing equipment limit the free flow of advanced CSP LED production capabilities. Geographic supply concentration centers on South Korea, Taiwan, and China for high-volume production, with Japan specializing in premium materials. The industry draws from specialized raw materials like gallium nitride wafers and advanced phosphor materials. Single-source vulnerability for these critical inputs presents a structural risk; distribution runs primarily through direct sales channels to major electronic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CSP LED market presents a significant service-attach opportunity, particularly as software and firmware for adaptive lighting systems expand faster than the underlying hardware. These integrated control systems offer recurring revenue streams and enhanced functional value.
For Market Incumbents: Entrench market share by aggressively investing in advanced R&D for high-performance automotive applications, particularly adaptive driving beam systems. Expand manufacturing capacity in regions adhering to strict regulatory standards like the EU's RoHS directive. This defends against MicroLED substitution risk in display backlighting and fragmentation from fab-lite models. Certification investment in automotive-grade components strengthens their competitive positioning.
For New Entrants and Emerging Players: Establish a beachhead in niche, high-growth segments like horticultural lighting and UVC disinfection systems, which require specialized spectral outputs. The most penetrable segment for new entrants involves industrial applications demanding specific functionalities over sheer volume. A viable go-to-market angle involves offering integrated smart lighting nodes, combining CSP LEDs with miniaturized photodetectors for IoT applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to divest non-core but technologically advanced LED divisions. The long-term viability of high-performance, compact illumination solutions remains strong. Acquisition targets should be specialized component manufacturers possessing robust intellectual property in unique phosphor formulations or advanced flip chip assembly. A critical signal to watch is the acceleration of adaptive driving beam system adoption in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Multi-Pixel Array R&D | Accelerates development of high-resolution matrix headlamps for the US automotive market. |
| Secure Phosphor Material Supply Agreements | Mitigates cost volatility and ensures stable production of high-CRI white LEDs. |
| Expand Fab-Lite Manufacturing Partnerships | Lowers capital entry barriers and fragments the supplier base for consumer electronics. |
| Develop UVC Disinfection CSP LED Products | Opens new markets in surface and air sanitization for consumer appliances. |
| Standardize Package Footprints with OEMs | Reduces redesign costs for luminaire manufacturers and promotes component second-sourcing. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholders included automotive OEM engineers, consumer electronics procurement managers, LED product developers, and lighting system integrators. Secondary data sources comprised EU RoHS directives, US EPA ENERGY STAR program documentation, China GB standards, and relevant company filings. This approach utilized both bottom-up and top-down triangulation for robust data validation.
The calibration approach involved iterative adjustments of market models against historical performance and expert consensus across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional market. Compound annual growth rates were derived through regression analysis and market share projections. Key industry-specific inputs included automotive production forecasts and consumer electronics shipment volumes.
Stress conditions across geopolitical trade tensions and rapid MicroLED market penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning technological evolution and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Smart LED Indoor Signage Market
LED
Middle East LED Lights Market
LED
LED Lighting Controllers Market
LED
Outdoor LED Display Market
LED
China Outdoor LED Lighting Market
LED
LED Tester Market
LED
High-Brightness LED Market
LED
Russia LED Market
LED
North America Outdoor LED Lighting Market
LED
France Indoor LED Lighting Market
LED
Linear LED Strip Fixture Market
LED
Gan Substrate Market
LED
Biometrics Infrared LED Market
LED
Bi-Color LED Ring Light Market
LED
Middle East LED Lighting Market
LED
Japan Outdoor LED Lighting Market