
 Gan Substrate Market | 2026-2036
Gan Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Gan Substrate Market Analysis
Market Context
Project finance for mega-fabs and equipment leasing programs is reshaping capital deployment in GaN substrate manufacturing. Kyocera Corporation leverages its ceramic materials heritage to sustain captive wafer supply for internal device production. Mitsubishi Chemical Corporation anchors Japanese supply security through vertical integration from raw gallium to polished substrates. SOITEC competes with its proprietary Smart Cut technology, enabling thinner GaN layers with reduced defect density.
Technical Definition and Segments
A GaN substrate is a single-crystal gallium nitride wafer, typically grown by hydride vapor phase epitaxy or ammonothermal methods, serving as the lattice-matched foundation for high-electron-mobility transistors and blue or UV optoelectronic devices. GaN-on-SiC dominates RF military and radar applications where thermal conductivity exceeds 400 W/mK, while GaN-on-Si captures cost-sensitive power electronics as silicon foundries retrofit existing 200mm lines. MOCVD equipment utilization rates and quantum dot integration complexity are concentrating margin pools in heteroepitaxy technology segments.
Regulatory Frame
REACH in Europe and RoHS directives restrict hazardous substances in semiconductor packaging, forcing substrate suppliers to certify lead-free metallization schemes. Japan's METI sets energy efficiency benchmarks that favor GaN power devices over silicon alternatives in data center power supplies. Stakeholders must monitor how EPA per- and polyfluoroalkyl substance rules affect wet etching chemistries and whether China's GB standards diverge from IEC thermal cycling test protocols.
Market Dynamics
Automotive electrification is compressing qualification cycles for GaN-on-SiC substrates as Tier 1 suppliers demand automotive-grade defect densities below 10⁴ cm⁻² for traction inverter modules. This demand pull is restructuring supply relationships between substrate manufacturers and power semiconductor foundries.
Growth Catalysts
- China's dual carbon goals:Beijing's MEE efficiency mandates are forcing data center operators to replace silicon power supplies with GaN-based alternatives, tightening substrate purity requirements to 6N gallium feedstock standards.
- Defense procurement:Phased array radar modernization programs across NATO member states are locking in multi-year GaN-on-SiC substrate offtake agreements for X-band and Ku-band applications.
- Silicon foundry retrofitting:200mm silicon lines in Taiwan and Japan are converting MOCVD capacity to GaN heteroepitaxy, expanding addressable substrate volumes without greenfield fab construction.
Market Restraints
- Ammonothermal growth bottleneck:Bulk GaN crystal yield rates below 30% constrain native substrate availability, forcing RF device makers to accept higher-cost hydride vapor phase epitaxy wafers.
- Silicon carbide substrate oligopoly:Wolfspeed, Coherent, and SK Siltron control 85% of semi-insulating SiC blank supply, creating chokepoint risk for GaN-on-SiC device manufacturers.
- REACH substance restrictions:ECHA's evolving candidate list for Substances of Very High Concern threatens wet etching chemistries using hexavalent chromium in European polishing operations.
Strategic Opportunities
- Indian PLI scheme for semiconductors:New Delhi's production-linked incentive program offers 50% capex reimbursement for compound semiconductor fabs, creating first-mover substrate demand in a greenfield market.
- UV-C LED sterilization:Post-pandemic water and air purification infrastructure in Southeast Asia is opening ammonothermal GaN substrate demand for 275nm emitters outside traditional lighting applications.
- Smart Cut layer transfer:SOITEC's engineered substrate technology enables 200mm GaN-on-Si wafers with thermal performance approaching native substrates, unlocking cost-sensitive industrial motor drive segments.
Industry Challenges
- Crystallographer talent scarcity:Ammonothermal growth expertise resides with fewer than 200 specialists globally, concentrated at Mitsubishi Chemical and a handful of academic labs in Poland and Japan.
- Automotive qualification timelines:AEC-Q100 stress testing requires 18-24 months for substrate-level certification, misaligning with EV platform development cycles compressed to 36 months.
- Defect metrology standardization:Absence of unified IEC protocols for threading dislocation density measurement creates disputes between substrate suppliers and epi-house customers over acceptance criteria.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gan Substrate Market |
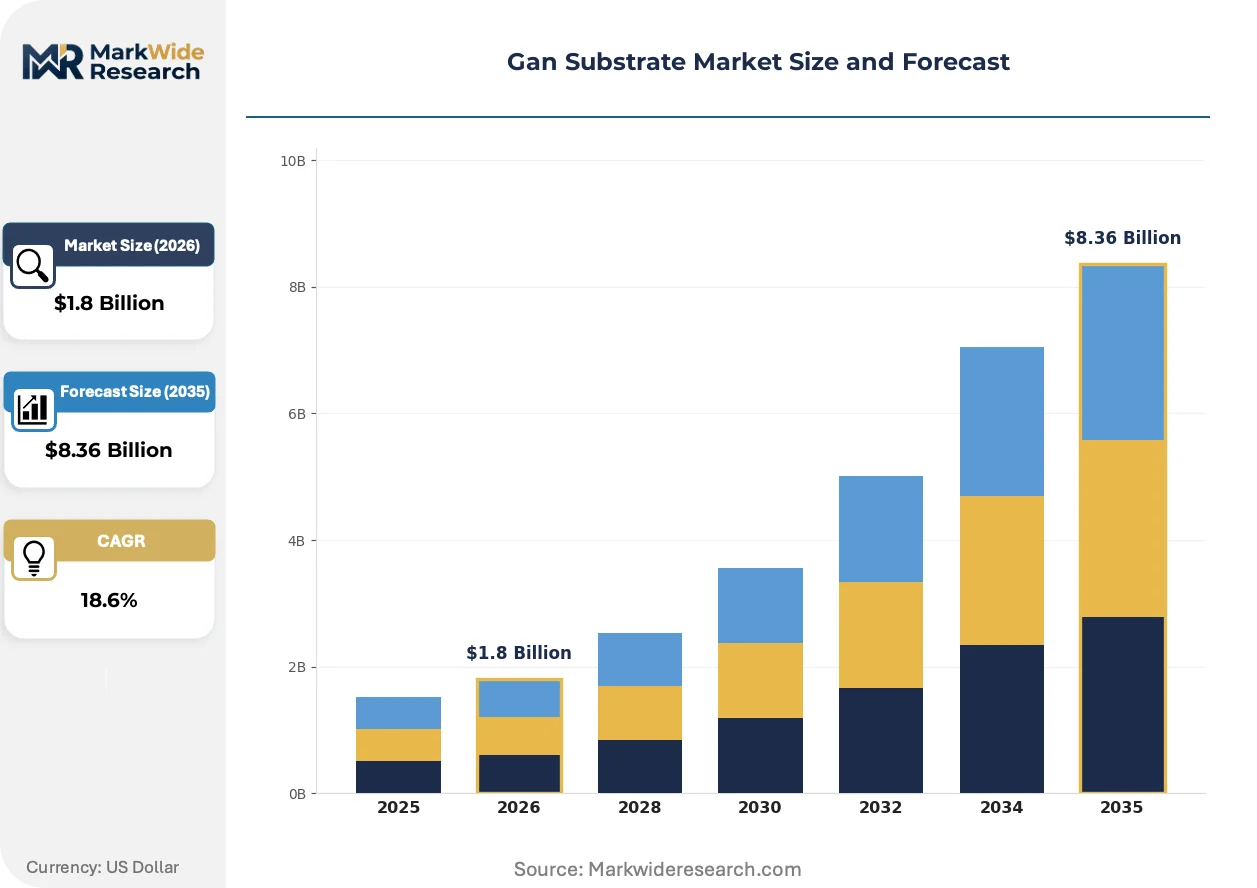
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaN-on-Si, GaN-on-Sapphire, GaN-on-SiC, GaN-on-Diamond Application: Power Electronics, RF Devices, Optoelectronics, Automotive Applications End User: Consumer Electronics, Telecommunications, Industrial Automation, Aerospace Technology: Heteroepitaxy, MOCVD, VPE, Quantum Dots |
| Companies Covered | Kyma Technologies, Inc., Kyocera Corporation, Mitsubishi Chemical Corporation, MTI Corporation, NGK Insulators, Ltd., Shin-Etsu Chemical Co., Ltd., SOITEC, Sumitomo Chemical Co., Ltd., Toyoda Gosei Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gan Substrate Market Emerging Trajectories
Wafer-level integration techniques are collapsing the traditional separation between substrate manufacturing and device fabrication, enabling thinner active layers with engineered strain profiles. This convergence is redrawing competitive boundaries between materials suppliers and foundry operators.
Ammonothermal bulk GaN growth is rendering obsolete hydride vapor phase epitaxy for native substrates in laser diode applications. Osram and Nichia are qualifying ammonothermal material for 450nm blue lasers in automotive headlamps. The technology is rendering obsolete thick HVPE templates that required 400-micron removal through grinding and polishing.
Japan's METI has established power electronics efficiency benchmarks that favor GaN devices over silicon IGBTs in data center power supplies above 3kW. This regulatory pressure is forcing Japanese substrate makers to prioritize 6-inch GaN-on-Si development over 4-inch legacy formats. Domestic server manufacturers are now specifying 98.5% conversion efficiency as minimum procurement threshold.
Automotive Tier 1 suppliers are consolidating substrate procurement through direct long-term agreements with Japanese and Korean manufacturers, bypassing traditional distributor channels. Bosch and Denso are negotiating 5-year offtake contracts with Mitsubishi Chemical and SK Siltron. This consolidation is most visible in Germany and Japan, where power module assemblers seek supply security for 800V EV architectures.
Gan Substrate Market Segmentation
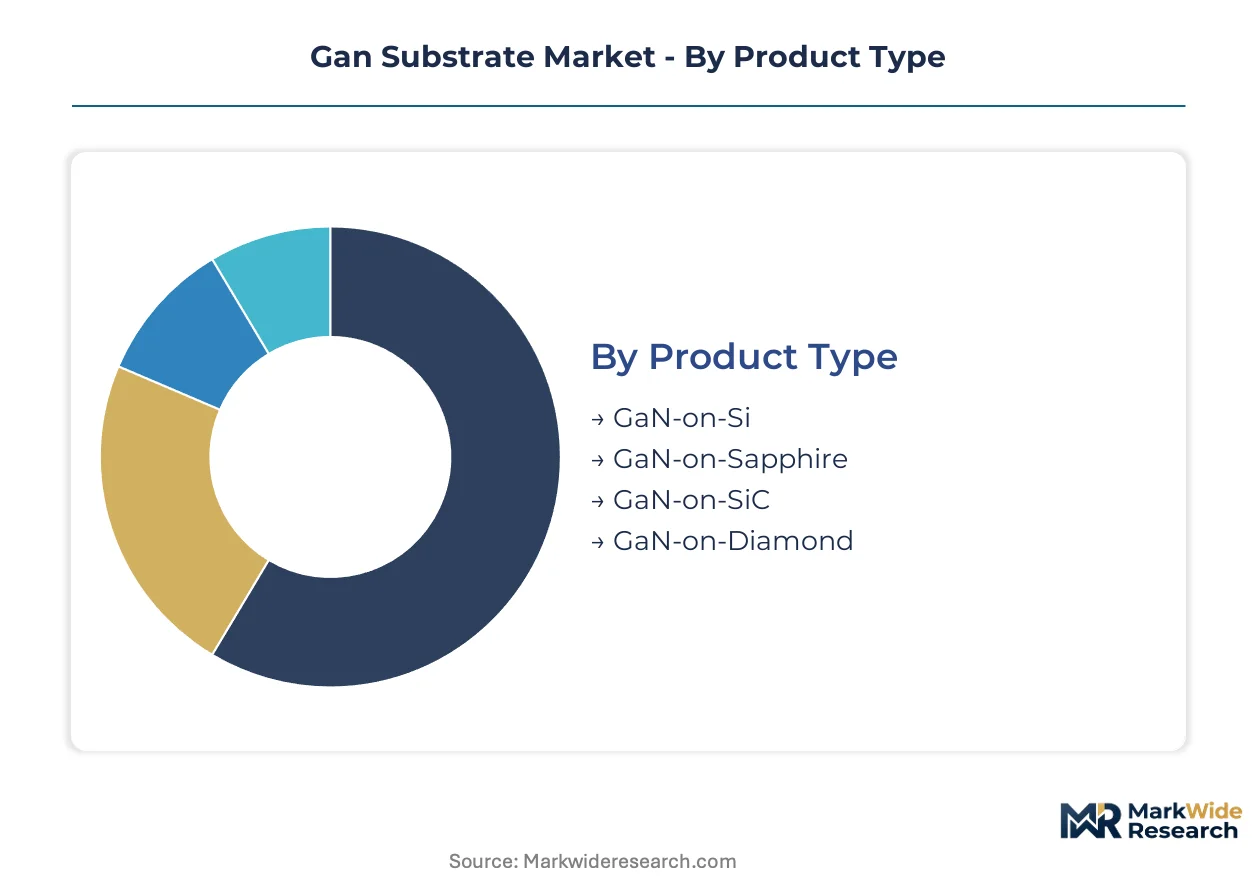
GaN substrate segmentation reveals divergent technical requirements across power, RF, and optical applications. Each product type demands distinct thermal management, defect density tolerances, and epitaxy compatibility. Understanding these boundaries prevents misallocation of capital between high-volume silicon-based platforms and premium native substrates.
Product Type:
After-sales service intensity varies sharply across substrate platforms, with native GaN requiring crystallographer support while heteroepitaxy relies on foundry partnerships.
- GaN-on-SiC:Combines gallium nitride epitaxy with silicon carbide substrates exceeding 400 W/mK thermal conductivity. Defense procurement across NATO member states concentrates demand for X-band radar modules, where Wolfspeed and Coherent control 85% of semi-insulating SiC blank supply. Device makers face chokepoint risk during phased array modernization programs.
- GaN-on-Si:Deposits nitride layers onto standard 200mm silicon wafers, enabling retrofit of existing foundry lines. Taiwan and Japan-based silicon foundries are converting MOCVD capacity to capture cost-sensitive power electronics without greenfield construction. Conversion efficiency mandates from Japan's METI favor this platform for data center supplies above 3kW.
- GaN-on-Sapphire:Leverages established LED infrastructure with limited thermal performance. LED backlighting and display applications in East Asian manufacturing clusters sustain residual demand despite inferior heat dissipation for power devices.
- GaN-on-Diamond:Experimental platform exploiting synthetic diamond's exceptional thermal conductivity. Research programs at selected Japanese national labs explore this architecture for next-generation radar transmitters where heat flux exceeds conventional materials.
GaN-on-SiC holds the largest share; momentum sits with GaN-on-Si.
Application:
Application segmentation tracks directly to thermal cycling requirements and qualification timelines, with automotive imposing the most severe certification burdens.
- Power Electronics:Dominates commercial volume through server power supplies, EV charging infrastructure, and grid-tied inverters. China's MEE efficiency mandates are forcing data center operators to replace silicon power supplies, tightening substrate purity to 6N gallium feedstock standards. Bosch and Denso negotiate multi-year offtake agreements for 800V traction inverters.
- RF Devices:Military radar and telecommunications base stations drive specifications for semi-insulating substrates with resistivity above 10⁶ ohm-cm. Phased array programs across NATO member states lock in long-term GaN-on-SiC substrate commitments for X-band and Ku-band frequencies.
- Optoelectronics:Blue and UV emitters for automotive headlamps and sterilization equipment. Osram and Nichia qualify ammonothermal material for 450nm blue lasers, displacing thick HVPE templates that required 400-micron removal through grinding.
- Automotive Applications:Traction inverters, onboard chargers, and DC-DC converters subject substrates to AEC-Q100 stress testing requiring 18-24 months for certification. This timeline misaligns with EV platform development cycles compressed to 36 months, creating supply planning friction.
Power Electronics captures the dominant revenue position; Automotive Applications climb the fastest.
End User:
End user concentration determines pricing leverage, with aerospace and telecommunications demanding dedicated supply security while consumer electronics prioritizes cost scaling.
- Telecommunications:5G macro base stations and small cell deployments require high-linearity power amplifiers. Network equipment manufacturers in Japan and South Korea specify defect densities below 10⁴ cm⁻² for millimeter-wave frequencies.
- Industrial Automation:Motor drives and robotics power supplies favor GaN-on-Si for cost-sensitive integration. SOITEC's Smart Cut technology enables 200mm wafers with thermal performance approaching native substrates for this segment.
- Consumer Electronics:Smartphone chargers and laptop adapters represent high-volume, low-margin applications where silicon foundry economics dominate substrate selection.
- Aerospace:Satellite communications and electronic warfare systems impose radiation hardness requirements. Procurement flows through defense contractors with multi-year qualification protocols and captive metallization specifications.
Telecommunications maintains the largest installed base; Industrial Automation gains share fastest.
Technology:
Technology segmentation reflects the fundamental tension between heteroepitaxy scalability and native substrate performance, with equipment utilization rates concentrating margin pools.
- Heteroepitaxy:Deposition of GaN on lattice-mismatched substrates including silicon, SiC, and sapphire. This approach dominates commercial production through existing MOCVD infrastructure, though threading dislocation densities exceed 10⁸ cm⁻² on silicon.
- MOCVD:Metal-organic chemical vapor deposition remains the workhorse process for LED and power device manufacturing. Equipment utilization rates at Taiwan and Japan foundries determine effective substrate demand elasticity.
- VPE:Vapor phase epitaxy produces thick GaN templates for laser diode applications, though ammonothermal bulk growth is rendering this approach obsolete for native substrates. Osram and Nichia have shifted qualification programs accordingly.
- Quantum Dots:Nanostructure integration for single-photon sources and advanced optoelectronics. Complexity of dot uniformity and positioning constrains this technology to laboratory and specialty communication applications.
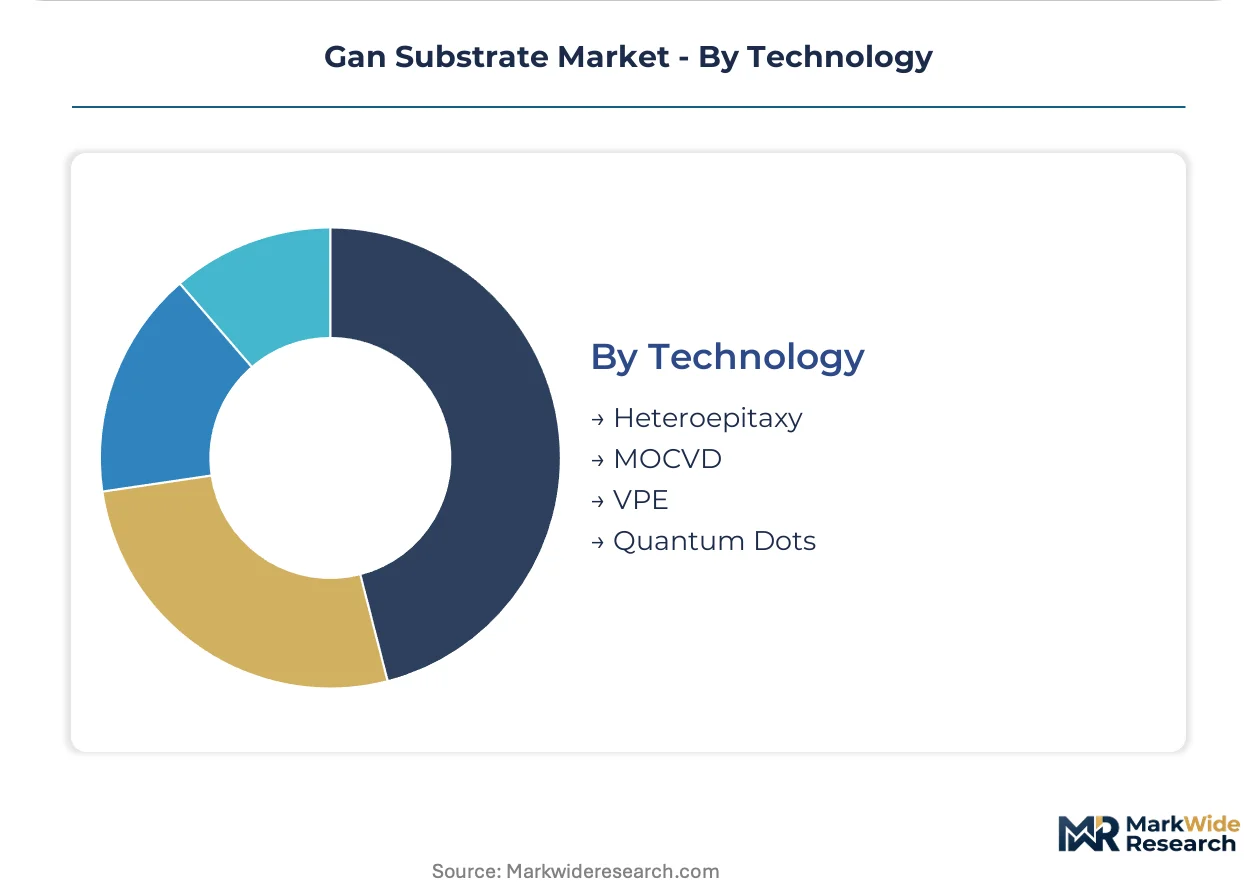
Heteroepitaxy commands the largest share; MOCVD expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and Korean manufacturing corridors while Chinese producers compete on volume scale. Substrate qualification timelines and automotive-grade certification requirements create regional arbitrage opportunities. East Asian foundry clusters dominate effective supply capacity.
Japan
Domestic data center operators drive GaN-on-Si substrate demand under METI efficiency benchmarks mandating conversion efficiency above 98.5% for supplies exceeding 3kW. Japan's national energy efficiency program accelerates silicon foundry conversion to GaN heteroepitaxy. Tokyo-Osaka industrial corridor hosts Mitsubishi Chemical and Shin-Etsu Chemical captive wafer operations serving internal device production.
China
Beijing's dual carbon goals and MEE efficiency mandates force data center operators to replace silicon power supplies with GaN-based alternatives. National gallium purity standards tighten to 6N feedstock specifications under environmental ministry directives. Yangtze River Delta manufacturing clusters concentrate substrate polishing and epitaxy house operations for domestic power module assemblers.
South Korea
SK Siltron anchors semi-insulating SiC blank supply for GaN-on-SiC RF device manufacturers serving defense and telecommunications sectors. National semiconductor self-sufficiency programs prioritize compound substrate capacity expansion. Seoul-Incheon metropolitan area concentrates power electronics foundries converting 200mm silicon lines to GaN heteroepitaxy.
United States
Department of Defense phased array radar modernization programs lock in multi-year GaN-on-SiC substrate offtake agreements for X-band and Ku-band applications. EPA per- and polyfluoroalkyl substance rules scrutinize wet etching chemistries in substrate polishing operations. Research Triangle Park and Silicon Valley host specialty substrate development programs for next-generation RF transmitters.
Germany
Bosch and continental Tier 1 suppliers negotiate direct long-term substrate agreements with Asian manufacturers for 800V EV traction inverters. KBA automotive certification requirements align with AEC-Q100 stress testing protocols for substrate-level qualification. Bavaria's automotive electronics corridor concentrates power module assembly operations demanding automotive-grade defect densities below 10⁴ cm⁻².
Gan Substrate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where crystallographer expertise and materials heritage create defensive moats. The vendor base separates between captive producers serving internal device fabrication and merchant substrate suppliers. Three archetypes dominate: diversified chemical conglomerates with gallium refining capabilities, precision ceramics manufacturers leveraging substrate-adjacent materials science, and engineered substrate specialists with layer-transfer intellectual property. Competitive moves concentrate on backward integration into high-purity gallium feedstock and strategic partnerships with automotive Tier 1 suppliers.
Among Japanese chemical conglomerates, Mitsubishi Chemical Corporation and Shin-Etsu Chemical Co., Ltd. exemplify the captive-production archetype, leveraging in-house gallium refining and ceramic processing heritage to secure internal wafer supply. SOITEC represents the engineered substrate specialist tier, occupying a position defined by proprietary layer-transfer technology enabling thinner GaN structures. Kyocera Corporation anchors the precision ceramics vector, drawing on decades of materials science integration to sustain substrate manufacturing capabilities.
| Leading Market Players |
|---|
| Kyma Technologies, Inc. |
| Kyocera Corporation |
| Mitsubishi Chemical Corporation |
| MTI Corporation |
| NGK Insulators, Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| SOITEC |
| Sumitomo Chemical Co., Ltd. |
| Toyoda Gosei Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Semi-insulating SiC blank concentration in Wolfspeed, Coherent, and SK Siltron hands feeds directly into margin capture at the GaN epitaxy tier, where device makers absorb chokepoint premiums or accept heteroepitaxy trade-offs. This upstream oligopoly shapes how pricing power distributes between substrate suppliers and foundry customers across defense and automotive procurement channels.
Pricing Analysis
Configured-to-order ammonothermal GaN substrates command spreads exceeding standard HVPE template pricing by multiples reflecting crystallographer scarcity and yield rates below 30%. Pricing stratifies across automotive-grade AEC-Q100 certified supply, industrial-standard material, and research-grade volumes with relaxed defect specifications. Cost compression in GaN-on-Si runs through foundry utilization competition as Taiwan and Japan-based silicon lines convert MOCVD capacity. Consumer electronics charger applications exhibit highest price sensitivity, while aerospace radar programs show lowest elasticity due to qualification lock-in and radiation hardness requirements.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk as gallium refining concentrates in Chinese Yangtze River Delta clusters while polishing and epitaxy operations span Japanese Tokyo-Osaka and Korean Seoul-Incheon corridors. Raw material dependencies center on 6N purity gallium feedstock, high-purity ammonia for ammonothermal growth, and semi-insulating SiC blanks from Wolfspeed and Coherent. Single-source vulnerability persists at the SiC substrate tier where three suppliers control 85% of semi-insulating blank supply. Distribution runs through direct long-term offtake agreements with automotive Tier 1 suppliers, bypassing traditional distributor channels for qualified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crystallographer technical support and epitaxy house partnership programs expand faster than native substrate hardware sales, creating service-attach opportunities for substrate manufacturers seeking recurring revenue beyond wafer transactions. This after-sales layer offers margin defense as yield improvements compress unit economics.
For Market Incumbents: Insulate ammonothermal growth expertise through captive training pipelines and exclusive academic lab partnerships in Poland and Japan, where fewer than 200 specialists globally concentrate. Threat from silicon foundry retrofitting demands counter-investment in 6-inch GaN-on-Si qualification to capture data center power supply volume under METI efficiency mandates. Priority lever sits in backward integration into 6N gallium refining to secure feedstock purity standards tightening under China's MEE directives. For New Entrants and Emerging Players: Build out ammonothermal capacity targeting UV-C LED sterilization applications in Southeast Asia water and air purification infrastructure, where 275nm emitter demand opens outside traditional lighting procurement channels. Most penetrable geography centers on India's PLI scheme for compound semiconductors, offering 50% capex reimbursement for greenfield fabs. Go-to-market angle emphasizes crystallographer technical support bundled with substrate supply, addressing talent scarcity that constrains incumbent expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ammonothermal bulk growth as equipment scale-up and yield engineering demands intensify. Long-term viability over the 5-10 year window favors engineered substrate specialists with layer-transfer intellectual property over pure-play crystal growers exposed to yield volatility. Acquisition target archetype combines Smart Cut technology platforms with established automotive qualification relationships. Signal to watch is AEC-Q100 certification timeline compression as EV platform cycles accelerate toward 36-month development windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 6N Gallium Refining | Mitsubishi Chemical and Shin-Etsu Chemical secure feedstock purity against China's MEE tightening standards. |
| Ammonothermal Capacity Expansion | Osram and Nichia qualification programs for 450nm blue lasers displace obsolete HVPE template supply. |
| Smart Cut Layer Transfer Technology Deployment | SOITEC enables 200mm GaN-on-Si wafers with thermal performance approaching native substrates for industrial motor drives. |
| Direct Long-Term Offtake Agreements | Bosch and Denso bypass distributor channels to secure supply security for 800V EV traction inverter architectures. |
| Crystallographer Technical Support Programs | Native substrate suppliers bundle expertise services addressing global specialist scarcity concentrated in Polish and Japanese academic labs. |
Methodological Framework
Desk research of SEC semiconductor equipment filings, Japanese METI energy efficiency reports, and Chinese MEE environmental directives preceded structured interviews with MOCVD equipment engineers, GaN device foundry procurement managers, automotive Tier 1 power module designers, and ammonothermal growth crystallographers. Primary fieldwork combined with secondary validation across trade customs data, compound semiconductor industry association reports, and national laboratory research disclosures. Bottom-up wafer demand modeling triangulated against top-down power electronics market sizing.
Assumptions around ammonothermal yield improvement trajectories, silicon foundry conversion timelines, and automotive qualification compression held fixed across scenarios, while GaN-on-SiC versus GaN-on-Si technology mix and regional regulatory stringency varied. Segmentation dimensions spanned product type, application, end user, and technology platform, with additional granularity on thermal conductivity requirements and defect density thresholds. CAGRs derived from installed base replacement cycles and new application penetration curves, incorporating MOCVD equipment utilization rates and data center power supply efficiency mandates as demand elasticity inputs.
Practitioners should monitor ammonothermal yield breakthroughs, SiC substrate supply allocation shifts, and AEC-Q100 timeline compression for early signals warranting forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Downlight Market
LED
Indonesia LED Market
LED
China Indoor LED Lighting Market
LED
High-Brightness LED Market
LED
LED Panel Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Surface Mount PLCC Leds Market
LED
Saudi Arabia LED Lights Market
LED
LED Display Control Card Market
LED
Germany Outdoor LED Lighting Market
LED
LED Modular Display Market
LED
Mexico LED Lighting Market
LED
Bluetooth LED Bulb Market
LED
North America Outdoor LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
LED Control Unit Market