
 North America Outdoor LED Lighting Market | 2026-2036
North America Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Outdoor LED Lighting Market Analytics
Aluminum die-cast housings is pivoting toward thermally conductive polymer composites in outdoor LED luminaire manufacturing, reducing weight and corrosion susceptibility while maintaining heat dissipation performance. Cree LED leverages its SiC substrate expertise to sustain premium positioning in high-lumen street and roadway applications. Signify Holding anchors its North American presence through extensive municipal retrofit partnerships, while Acuity Brands competes across commercial and industrial outdoor portfolios with broad distribution control.
North America Outdoor LED Lighting comprises solid-state luminaires engineered with efficacy ratings exceeding 130 lumens per watt, utilizing phosphor-converted white LEDs mounted on metal-core PCBs within IP65+ rated enclosures for weather resilience in exterior environments. Street Lights and Floodlights occupy the dominant volume positions, with Street Lights benefiting from federal infrastructure funding cycles and Floodlights capturing margin pools in sports and security installations. Smart Lighting technology leads growth velocity as networked controls and adaptive dimming protocols displace traditional photocell operation in Parks and Parking Lots applications.
The U.S. Department of Energy enforces minimum efficacy standards through ENERGY STAR and DLC qualification requirements, while Canada's NRCan administers comparable performance benchmarks that gate utility rebate eligibility and procurement specifications. Municipal end users in California face additional Title 24 building code constraints on outdoor power density, and Ontario's Save on Energy program shapes retrofit economics through prescriptive incentive structures. Stakeholders must monitor evolving connected lighting cybersecurity standards and grid-interoperability mandates that will determine next-generation product certification pathways.
Market Dynamics
Federal infrastructure funding cycles are compressing municipal procurement timelines while utility rebate programs reshape retrofit economics across U.S. and Canadian jurisdictions.
Growth Catalysts
- Utility Rebate Programs:Ontario's Save on Energy program and comparable U.S. utility incentives accelerate payback periods for municipal LED conversions.
- Smart City Infrastructure:Networked lighting controls with adaptive dimming protocols are expanding addressable market in parking and park applications.
- Thermally Conductive Polymers:Aluminum replacement in luminaire housings reduces weight and corrosion susceptibility while maintaining thermal performance.
Market Restraints
- Silicon Carbide Substrate Concentration:Premium high-lumen applications depend on limited SiC supply sources concentrated among specialized substrate manufacturers.
- Photocell Legacy Infrastructure:Existing photocell-based control systems create technical friction for smart lighting retrofits requiring full luminaire replacement.
- California Title 24 Compliance Costs:Outdoor power density constraints add engineering overhead and certification expense for products targeting that state.
Strategic Opportunities
- Canadian Municipal Expansion:Ontario and British Columbia infrastructure programs remain underpenetrated relative to U.S. state-level deployment rates.
- Cybersecurity Certification Pathways:Emerging connected lighting security standards create first-mover positioning for compliant product portfolios.
- Sports Installation Floodlighting:High-margin athletic field and arena applications represent underserved vertical with specialized optical requirements.
Industry Challenges
- Grid-Interoperability Engineering:Utility demand-response integration requires specialized firmware development and regional protocol adaptation.
- Metal-Core PCB Sourcing:Thermal management substrate supply faces lead time volatility from electronics industry demand competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Outdoor LED Lighting Market |
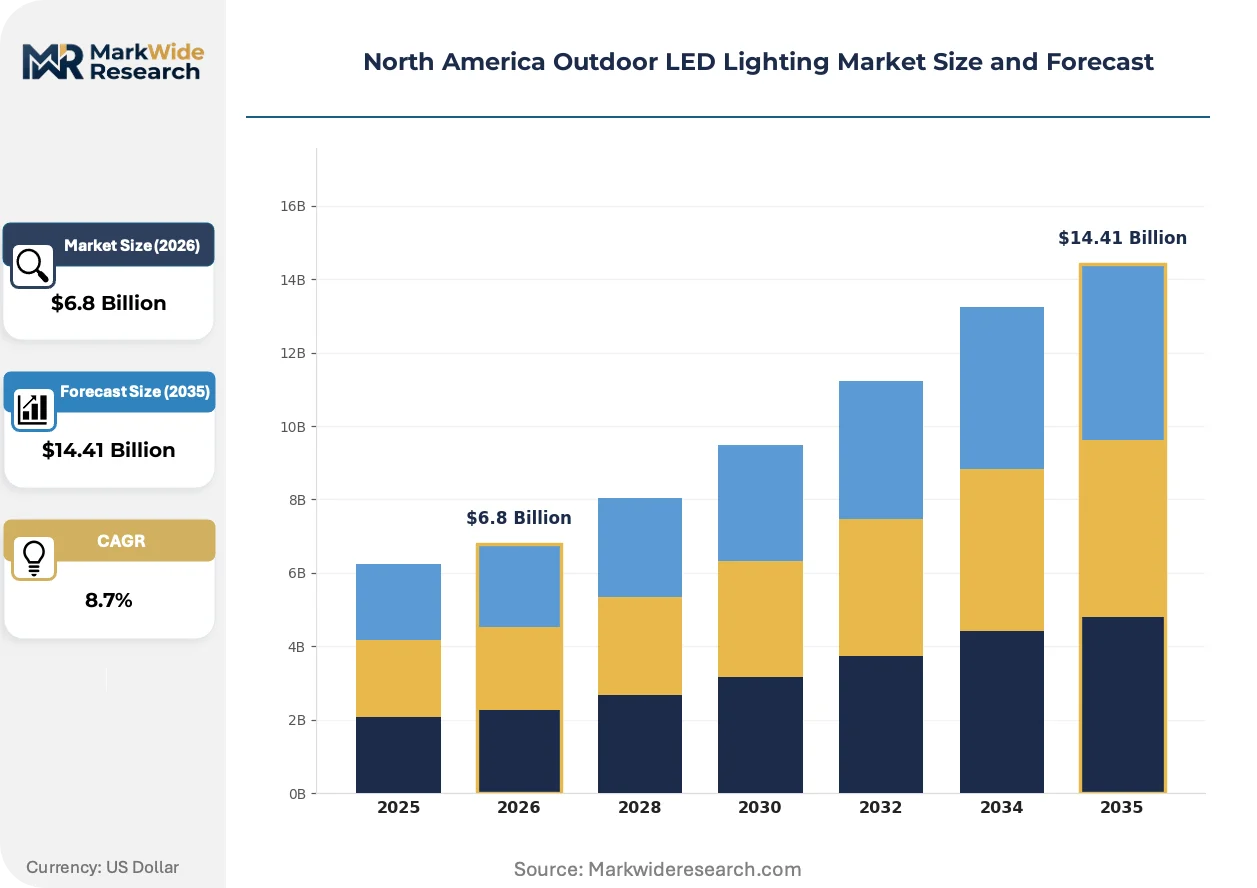
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floodlights, Street Lights, Garden Lights, Wall Pack Lights Application: Parks, Roadways, Parking Lots, Commercial Spaces Technology: Smart Lighting, Solar Powered, Traditional, Motion Sensor End User: Municipal, Residential, Commercial, Industrial |
| Companies Covered | Dialight, Cree LED, Acuity Brands, Feit Electric Company, LEDVANCE, Signify Holding, Panasonic Holdings Corporation, EGLO Leuchten, Current Lighting Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Outdoor LED Lighting Market Evolving Landscape
Product architecture and control intelligence are converging to redefine how outdoor lighting systems are specified, deployed, and monetized across municipal and commercial verticals.
Adaptive dimming protocols with embedded sensor networks are modularizing street lighting infrastructure into software-addressable assets. Municipal buyers in Texas and California are specifying these systems for new corridor deployments. The shift compresses traditional luminaire-only procurement into integrated hardware-software contracts with recurring service components.
The U.S. Department of Energy's ENERGY STAR and DLC qualification requirements are tightening minimum efficacy thresholds for utility rebate eligibility. Manufacturers must redesign optical engines and driver electronics to maintain certification status. Street lighting portfolios face the steepest compliance burden given their volume exposure to federal and state procurement mandates.
Municipal procurement offices are consolidating vendor relationships around full-service retrofit partners who assume installation and maintenance liability. Traditional distributor channels face margin compression as direct manufacturer-municipal contracts displace multi-tier supply arrangements. California's municipal buying cooperatives exemplify this concentration most visibly, with pooled purchasing vehicles reducing supplier count per retrofit program.
North America Outdoor LED Lighting Market Segmentation
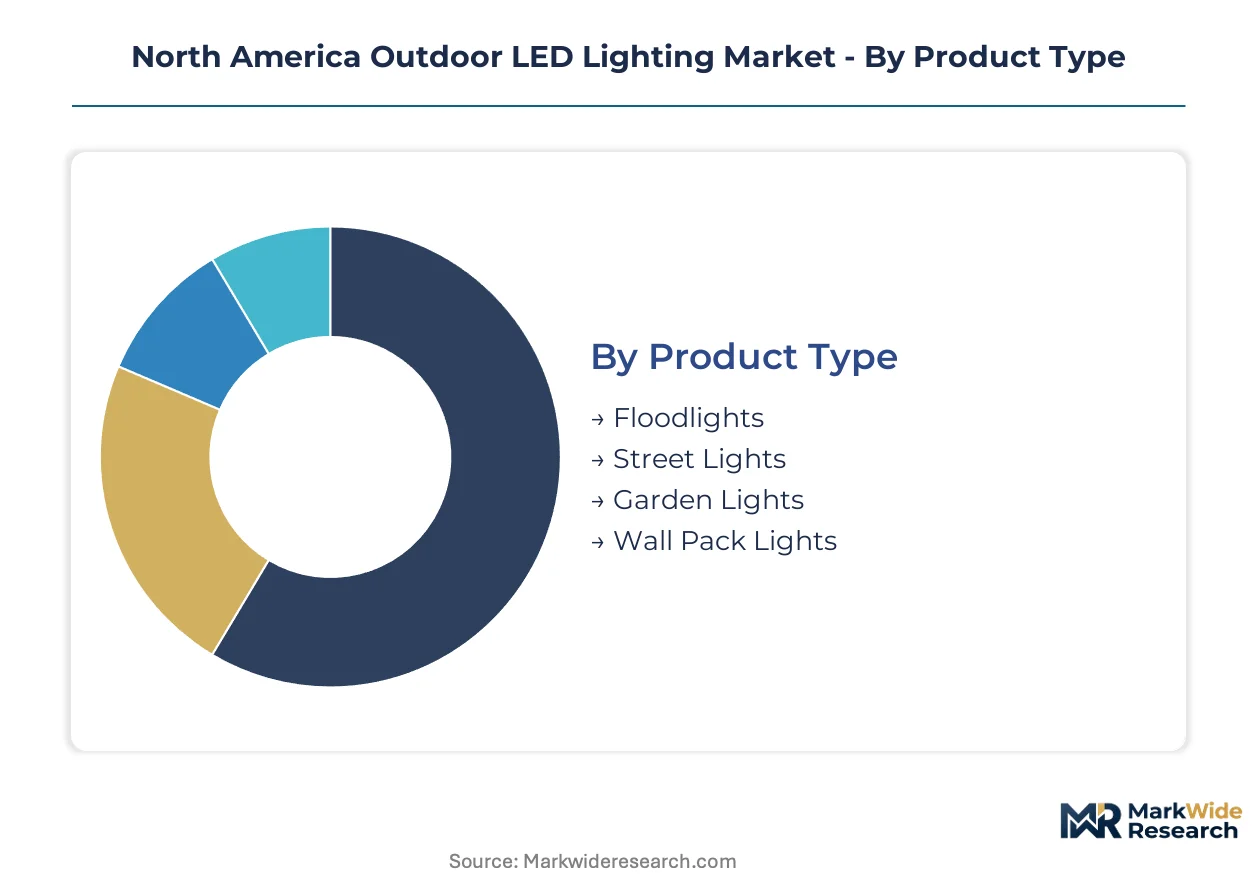
Segmentation in outdoor LED lighting reveals how procurement specifications diverge across infrastructure maturity, regulatory pressure, and operational complexity. Understanding these divides exposes where margin pools concentrate and which technology transitions command premium positioning.
Product Type:
Standardization dominates high-volume municipal contracts while customization persists in specialized architectural and security applications.
- Street Lights:Engineered for 130+ lumens per watt efficacy with IP65-rated die-cast aluminum or polymer composite housings. Municipal retrofit programs in California and Texas concentrate procurement volume here, driven by federal infrastructure funding cycles and utility rebate eligibility thresholds.
- Floodlights:High-lumen output fixtures utilizing precision optics for beam control across asymmetric and symmetric distributions. Sports installations and perimeter security in Ontario and British Columbia drive demand, where specialized optical requirements sustain margin premiums against commodity alternatives.
- Garden Lights:Lower-wattage decorative luminaires emphasizing aesthetic integration over raw efficacy.
- Wall Pack Lights:Compact egress and facade illumination with cutoff optics for dark-sky compliance.
Leading the category by volume: Street Lights. Growing fastest: Floodlights.
Application:
Cost tiers separate mission-critical infrastructure from discretionary commercial upgrades, with each tier carrying distinct procurement authority and replacement cycles.
- Roadways:Continuous-operation lighting with adaptive dimming protocols and networked controls. State DOT specifications and municipal street lighting authorities in Texas and California dominate demand, where ENERGY STAR and DLC certification gates utility rebate access.
- Parking Lots:Security-driven illumination with motion-responsive operation and photocell legacy integration challenges. Commercial property managers and retail chains across the U.S. Midwest drive retrofit economics, balancing liability exposure against energy cost reduction.
- Parks:Mixed-use recreational lighting with wildlife-sensitive spectral output and vandal-resistant construction.
- Commercial Spaces:Brand-forward facade and landscape illumination with shorter payback horizon requirements.
Expanding most quickly: Parking Lots. Anchoring procurement volume: Roadways.
Technology:
Customer type stratification separates early-adopter municipalities with capital planning capacity from price-sensitive residential buyers deferring premium technology.
- Smart Lighting:Networked luminaires with embedded sensors, adaptive dimming protocols, and grid-interoperability firmware. Municipal buyers in California corridor deployments and Texas smart city initiatives concentrate demand, where software-addressable infrastructure enables recurring service revenue models.
- Traditional:Standalone photocell-operated fixtures with fixed output profiles and minimal control intelligence. Legacy infrastructure replacement in underfunded municipal jurisdictions sustains volume, particularly where full luminaire replacement creates technical friction for smart retrofits.
- Solar Powered:Off-grid autonomous operation with integrated photovoltaic and battery storage.
- Motion Sensor:Occupancy-responsive activation for security and energy management in perimeter applications.
Climbing the fastest: Smart Lighting. Still commanding baseline volume: Traditional.
End User:
Maturity gradients separate established municipal procurement channels from emerging residential adoption, with supply concentration favoring institutional buyers.
- Municipal:Large-scale retrofit and new corridor deployment with consolidated vendor relationships and cooperative purchasing vehicles. California municipal buying cooperatives exemplify procurement concentration, where full-service partners assume installation and maintenance liability.
- Commercial:Property owner and facility manager specification with shorter decision cycles and brand-sensitive optical requirements. Retail chains and logistics parks across Ontario and the U.S. Sun Belt drive demand, where energy cost reduction aligns with corporate sustainability commitments.
- Industrial:High-bay and perimeter security with extreme environment durability requirements.
- Residential:Homeowner-driven landscape and security with price-sensitive specification and minimal technical integration.
Gaining share fastest: Commercial. Retaining procurement scale leadership: Municipal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in California, Texas, and Ontario where infrastructure modernization programs drive procurement volume. Municipal retrofit timelines compress as federal funding cycles accelerate project approvals. Utility rebate structures in these jurisdictions reshape payback calculations for LED conversions.
United States
Federal infrastructure funding and state-level efficiency mandates drive municipal procurement across California, Texas, and the Midwest. The U.S. Department of Energy enforces ENERGY STAR and DLC qualification requirements that gate utility rebate access. California's Title 24 building code imposes outdoor power density constraints that add engineering overhead for luminaire manufacturers targeting that market.
Canada
Ontario's Save on Energy program and British Columbia infrastructure initiatives sustain retrofit momentum in Canadian municipalities. Natural Resources Canada administers performance benchmarks comparable to U.S. standards that determine procurement specifications. Toronto and Vancouver anchor demand concentration where prescriptive incentive structures shape project economics.
Mexico
Municipal modernization in Mexico City and northern border states creates emerging demand for street and roadway illumination. The country's national energy efficiency regulator implements performance standards that increasingly align with North American certification frameworks. Monterrey and Guadalajara industrial corridors drive commercial outdoor lighting specifications.
North America Outdoor LED Lighting Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek integrated hardware-software positioning. The vendor base stratifies across three tiers: multinational lighting conglomerates with municipal retrofit expertise, mid-scale specialists in thermal management and optical engineering, and regional distributors facing margin compression from direct manufacturer contracts. Two archetypes prevail: full-service retrofit partners assuming installation liability, and component-integrated platform providers monetizing recurring service revenue. M&A activity and technology licensing agreements represent the dominant competitive vectors as firms acquire sensor networking and adaptive control capabilities.
Within the multinational tier, Signify Holding and Acuity Brands occupy positions exemplifying divergent strategic emphases—Signify through extensive municipal partnership networks, Acuity across commercial and industrial portfolios with distribution breadth. Cree LED represents the specialized substrate and high-lumen engineering archetype, leveraging materials expertise for premium roadway applications. These three anchors illustrate how competitive positioning fragments across service integration, channel control, and component specialization.
| Leading Market Players |
|---|
| Dialight |
| Cree LED |
| Acuity Brands |
| Feit Electric Company |
| LEDVANCE |
| Signify Holding |
| Panasonic Holdings Corporation |
| EGLO Leuchten |
| Current Lighting Solutions |
| Others |
Value Network & Pricing Analysis
Municipal procurement offices in California and Texas concentrate buying power through cooperative purchasing vehicles, locking in contract-based long-term offtake pricing that favors full-service retrofit partners over component suppliers. This buyer consolidation feeds back into supply chain restructuring as manufacturers absorb installation liability to secure multi-year municipal agreements.
Pricing Analysis
Volume concentrates in standardized street luminaires where ENERGY STAR and DLC certification gates utility rebate access, while margin pools persist in floodlighting for sports installations where specialized optical engineering sustains premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates SiC-substrate high-lumen systems from commodity alternatives, with California Title 24 compliance costs adding engineering overhead that compresses margins in the standard tier. Price differentiation rests on certification level and after-sales service bundling. Cost compression in the economy tier is intensifying because municipal buyers are consolidating vendor relationships around fewer full-service partners.
Supply Chain Analysis
ENERGY STAR and DLC qualification requirements gate component eligibility, with metal-core PCB sourcing drawing from Taiwan, South Korea, and domestic U.S. fabrication facilities where electronics industry demand competition creates lead time volatility. Thermally conductive polymer composites and SiC substrates anchor raw material dependencies, while phosphor-converted white LEDs and driver electronics feed from concentrated Asian semiconductor supply bases. Single-source vulnerability in specialized SiC substrate manufacturing presents structural risk. Distribution runs through direct manufacturer-municipal contracts that displace traditional multi-tier distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Outdoor LED Lighting Market sits in a technology-transition phase as networked controls with adaptive dimming protocols displace legacy photocell infrastructure across municipal and commercial verticals.
For Market Incumbents: Cement municipal retrofit partnerships in Ontario and British Columbia where infrastructure programs remain underpenetrated relative to U.S. deployment rates. Acquire sensor networking and grid-interoperability firmware capabilities through technology licensing agreements to defend against smart lighting platform entrants. Prioritize backward integration into thermally conductive polymer housing production to reduce weight and corrosion susceptibility while capturing margin from aluminum replacement.
For New Entrants and Emerging Players: Enter via sports installation floodlighting where specialized optical requirements create white-space opportunity underserved by commodity-focused incumbents. Target Canadian municipal expansion corridors in Toronto and Vancouver where prescriptive incentive structures reshape retrofit economics. Pursue cybersecurity certification pathways for connected lighting as emerging standards create first-mover positioning against legacy portfolios lacking firmware security architecture.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale thermal management specialists in U.S. Sun Belt manufacturing corridors where metal-core PCB fabrication faces electronics industry demand competition. Long-term viability hinges on software-addressable infrastructure monetization through recurring service revenue models rather than transactional luminaire sales. Watch grid-interoperability mandate adoption as the inflection signal determining next-generation product certification pathways and capital allocation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Platform Integration | Adaptive dimming protocols in Texas corridor deployments enable recurring service revenue models. |
| Backward Integration into Polymer Housings | In-house production of thermally conductive composites reduces weight and corrosion susceptibility. |
| Cybersecurity Certification Investment | Connected lighting security standards in California create compliant product portfolio differentiation. |
| Canadian Municipal Partnership Expansion | Ontario Save on Energy program incentives reshape retrofit economics for underpenetrated jurisdictions. |
| SiC Substrate Supply Agreement | Long-term supply anchoring with specialized manufacturers mitigates single-source vulnerability risk. |
Research Methodology
Multi-period observation of municipal procurement timelines, utility rebate program structures, and luminaire cost curves anchored the trend analysis, supplemented by interviews with municipal street lighting authorities, commercial property facility managers, LED driver electronics engineers, and thermal management substrate suppliers. Secondary validation drew from U.S. Department of Energy ENERGY STAR databases, DLC qualified products lists, Natural Resources Canada performance benchmark publications, and federal infrastructure funding disbursement records. Bottom-up luminaire shipment estimates triangulated against top-down energy consumption projections and utility incentive redemption data.
Input-output matrices mapped product type, application, technology, and end user segmentation dimensions across the projection horizon, with CAGRs derived from regression analysis of historical efficacy improvement rates and infrastructure funding cycle patterns. Modeled variables included federal and state procurement mandate adoption curves, SiC substrate supply elasticity, and smart lighting control penetration rates in parking and park applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under discontinuities in federal infrastructure funding authorization or SiC substrate supply disruptions. Forecasts reflect assumptions about municipal budget continuity, utility rebate program stability, and connected lighting cybersecurity standard adoption timelines. A model refresh is warranted upon material change in ENERGY STAR or DLC qualification threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Programmable LED Drivers Market
LED
Japan Indoor LED Lighting Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
Gan Micro LED Market
LED
LED Panel Light Drivers Market
LED
US Outdoor LED Lighting Market
LED
Germany Outdoor LED Lighting Market
LED
LED Modules and Light Engines Market
LED
GCC LED Lighting Market
LED
Micro LED Display Market
LED
Monochrome Outdoor LED Display Market
LED
Middle East and Africa Indoor LED Lighting Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
Japan LED Market
LED
Surface Mount PLCC Leds Market
LED
LED Light Bar Market