
 Smart LED Indoor Signage Market | 2026-2036
Smart LED Indoor Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Smart LED Indoor Signage Market Intelligence
Aftermarket service revenue is reconfiguring margin pools across the Smart LED Indoor Signage value chain. Samsung Electronics leverages its semiconductor fabrication depth to control captive supply of MicroLED backplanes. LG Electronics anchors its position through vertical integration into OLED deposition equipment. Leyard Optoelectronic specializes in narrow pixel pitch assemblies for command-center deployments.
Smart LED Indoor Signage comprises emissive display systems utilizing semiconductor light-emitting diodes arranged in matrix configurations with pixel pitches ranging below 1.0mm for fine-pitch indoor applications, engineered for continuous operation exceeding 50,000 hours in climate-controlled environments. These systems serve commercial communication, wayfinding, and brand immersion functions across enclosed public and private spaces. Transparent LED dominates museum and corporate lobby installations where architectural integration preserves sightlines. MicroLED technology leads R&D allocation due to superior luminance efficiency and elimination of organic degradation mechanisms. RGB LED sustains volume leadership in shopping complexes where cost-per-lumen thresholds govern procurement decisions.
The EU Green Deal and F-Gas Regulation compel display manufacturers to eliminate fluorinated greenhouse gases from cooling systems and demonstrate lifecycle carbon footprints for public-sector tenders. The EPA Energy Star program and FCC Part 15 emissions standards shape product compliance costs for North American market access. Stakeholders must monitor regulatory convergence on right-to-repair mandates and modular design requirements that threaten proprietary service revenue streams while opening aftermarket competition.
Market Dynamics
Energy efficiency mandates and semiconductor supply concentration are restructuring procurement priorities across the Smart LED Indoor Signage value chain. Buyers now weight lifecycle carbon metrics alongside pixel density specifications in tender evaluations.
Growth Catalysts
- F-Gas Regulation:The EU Green Deal's fluorinated gas phase-out accelerates replacement of legacy cooling-dependent display systems in German public-sector installations.
- Command-center deployments:Narrow pixel pitch assemblies below 0.9mm penetrate security operations and traffic management facilities requiring 24/7 readability.
- Transparent LED:Architectural integration preserves sightlines in South Korean corporate lobbies and museum atriums, unlocking premium positioning.
Market Restraints
- Gallium substrate costs:MicroLED epitaxy relies on sapphire and silicon carbide wafers where supply concentrates among Japanese and Taiwanese substrate specialists.
- Right-to-repair mandates:Modular design requirements under EU Ecodesign regulations threaten proprietary service revenue streams for integrated manufacturers.
- OLED burn-in limitations:Organic degradation mechanisms constrain deployment in high-static-content environments like airport departure boards.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing attract LED module assembly investments serving domestic retail modernization.
- AI-driven content optimization:Convergence of computer vision and edge processing enables real-time audience analytics on deployed signage networks.
- Healthcare wayfinding:Hospital campus navigation systems represent an underpenetrated application with stringent luminance and infection-control specifications.
Industry Challenges
- MicroLED transfer yield:Mass transfer of chips from wafer to backplane remains a yield-limiting step requiring specialized pick-and-place equipment and cleanroom protocols.
- EMC certification timelines:FCC Part 15 emissions testing and CE marking for RF-integrated smart signage extend product launch schedules by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart LED Indoor Signage Market |
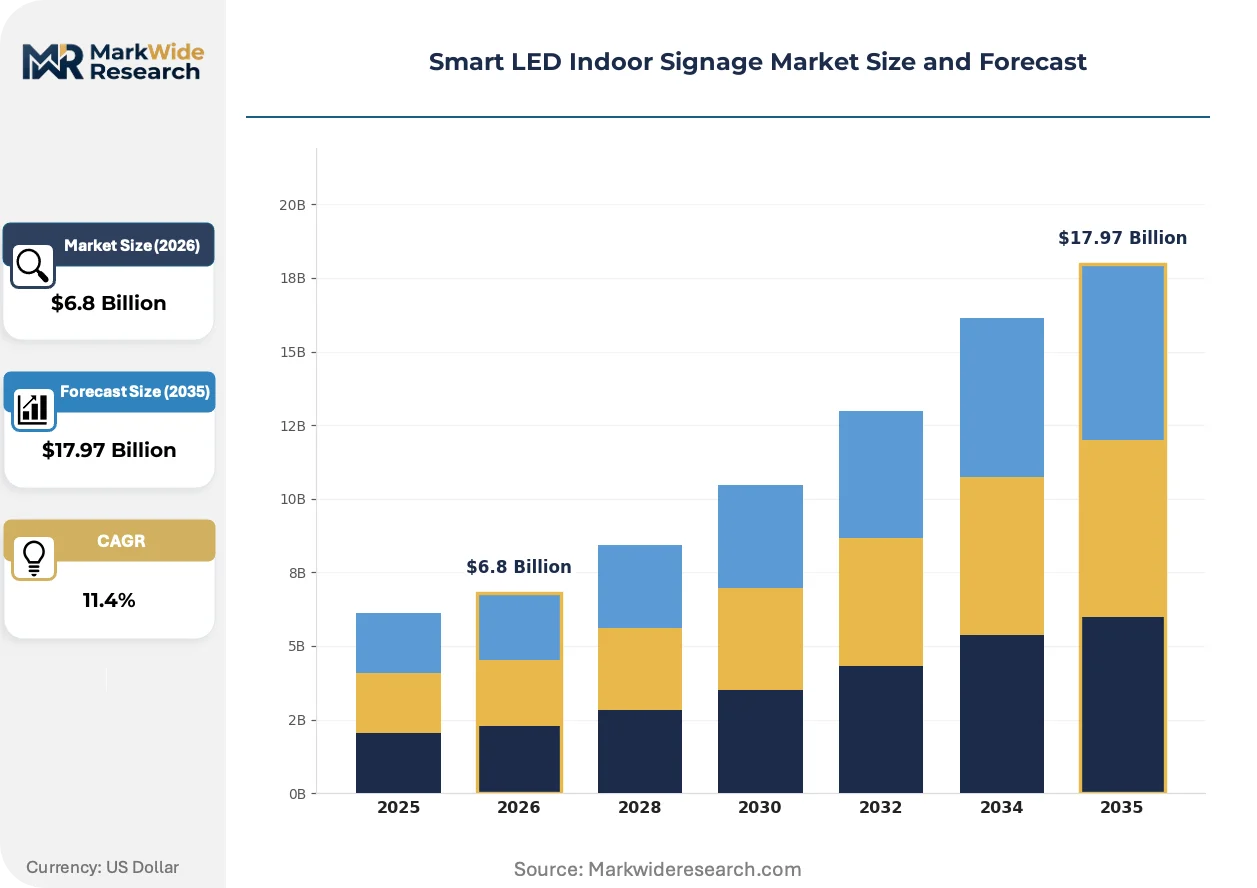
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent LED, Curved LED, Narrow Pixel Pitch, Poster LED, Floor LED, Shadow-Free LED Technology: MicroLED, OLED, RGB LED, MiniLED, Direct View LED, Surface Mount Device LED Application: Corporate Lobbies, Exhibition Booths, Shopping Complexes, Public Transportation Hubs, Museums, Educational Institutes End User: Retail Chains, Hospitality Venues, Entertainment Centers, Transportation Authorities, Educational Campuses, Corporate Offices |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Panasonic Corporation, NEC Corporation, Sharp NEC Display Solutions, Daktronics, Leyard Optoelectronic, AUO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart LED Indoor Signage Market Strategic Shifts & Innovations
Display technology is fragmenting across multiple performance tiers as buyers segment procurement between premium MicroLED, mid-range fine-pitch RGB, and architectural transparent systems. This stratification is compressing upgrade cycles and reshaping vendor specialization.
MicroLED technology is migrating from laboratory demonstration to commercial pilot deployments in executive briefing centers and broadcast studios. Early adopters in the United States and South Korea prioritize luminance efficiency and elimination of organic degradation over unit economics. The transition is compressing R&D amortization timelines and forcing legacy LED manufacturers to accelerate foundry partnerships or risk displacement in the premium tier.
The EU F-Gas Regulation and accompanying Ecodesign requirements now mandate lifecycle carbon disclosure for public-sector display tenders above specified energy thresholds. Manufacturers must eliminate hydrofluorocarbon cooling systems and demonstrate modularity for component replacement. German municipal procurement offices and French cultural institutions are most affected, with compliance costs filtering vendor qualification lists to vertically integrated suppliers with in-house environmental auditing.
Buyers are unbundling hardware procurement from content management and field service contracts. Large retail chains in the United States now separately tender display hardware, software platforms, and maintenance services, reversing prior bundled arrangements. This disintermediation pressures integrated manufacturers to defend margin through captive software ecosystems or surrender service revenue to specialized AV integrators.
Smart LED Indoor Signage Market Segmentation
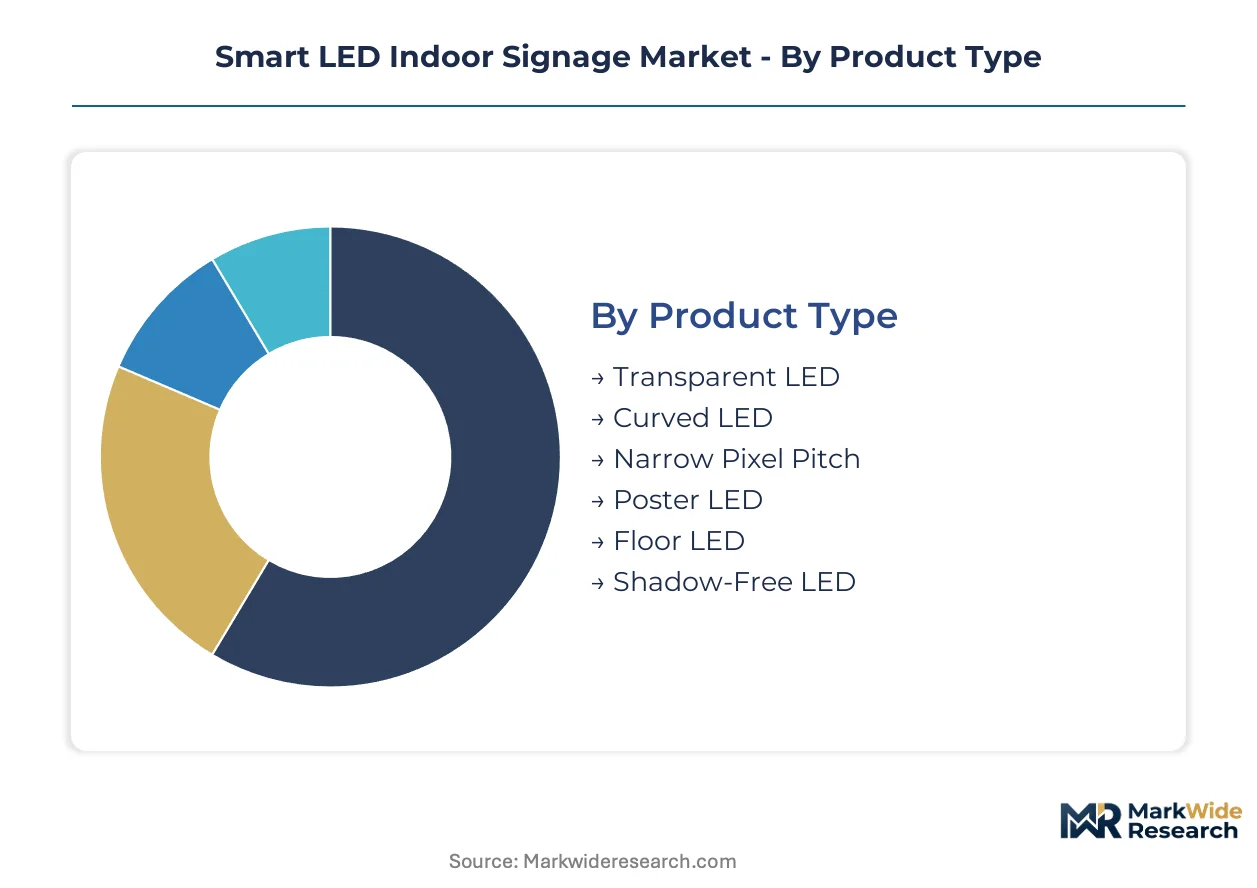
Smart LED Indoor Signage procurement patterns diverge sharply across product form factors and underlying technologies, with replacement cycles ranging from 3-year fashion-driven retail refreshes to 10-year infrastructure installations in transportation authorities. Understanding these velocity differentials helps vendors align inventory, service contracts, and R&D pipelines to segment-specific buyer behaviors.
Product Type:
Cycle times stretch from 18-month poster LED refreshes in fast-fashion retail to decade-long narrow pixel pitch deployments in command centers, creating distinct margin and service attach-rate profiles.
- Narrow Pixel Pitch:Pixel densities below 1.0mm enable continuous 24/7 readability at close viewing distances. Demand clusters in German traffic management facilities and South Korean security operations centers where failure tolerance approaches zero.
- Transparent LED:Grid-structured LED arrays mounted on transparent substrates preserve architectural sightlines while delivering luminance sufficient for daylight conditions. South Korean corporate lobbies and French museum atriums drive specification premiums for seamless spatial integration.
- Curved LED:Flexible PCB substrates conform to concave or convex architectural geometries. Deployment concentrates in Dubai hospitality venues and Las Vegas entertainment complexes seeking immersive brand environments.
- Poster LED:Slim-profile displays replacing static backlit posters in retail environments. Replacement cycles compress to 18-24 months as fashion retailers chase seasonal campaign refresh rates.
- Floor LED:Load-bearing LED tiles withstand pedestrian traffic for interactive wayfinding and brand activation. Airports in Singapore and shopping complexes in Mumbai deploy for passenger engagement metrics.
- Shadow-Free LED:Edge-lit diffusion panels eliminate pixel shadowing for photography and broadcast studio applications. Demand localizes in Los Angeles production facilities and London broadcast headquarters.
Narrow pixel pitch dominates installed base in mission-critical environments. Transparent LED is where expansion concentrates as architects specify integrated digital surfaces.
Technology:
Cost tiers separate laboratory-grade MicroLED pilot installations from volume RGB LED procurement in price-sensitive retail chains, with intermediate technologies capturing transitional upgrade budgets.
- RGB LED:Discrete red, green, and blue diodes deliver cost-per-lumen economics that sustain volume leadership. Shopping complexes across Germany and the United States specify for 50,000-hour lifecycle requirements in climate-controlled environments.
- MicroLED:Chip-scale LEDs bonded directly to backplane substrates eliminate organic degradation and deliver luminance efficiency gains. Pilot deployments in United States executive briefing centers and South Korean broadcast studios prioritize performance over unit economics.
- MiniLED:Mid-scale LED arrays with localized dimming bridge price-performance gaps. Adoption accelerates in mid-tier corporate lobbies seeking premium aesthetics without MicroLED capital commitment.
- OLED:Organic electroluminescent layers enable perfect black levels and thin form factors. Burn-in limitations constrain deployment in high-static-content environments like airport departure boards.
- Direct View LED:Modular LED cabinets tile into seamless video walls without bezels. Exhibition booths and temporary event installations favor for rapid assembly and disassembly cycles.
- Surface Mount Device LED:Conventional packaged diodes on PCB substrates serve replacement markets and cost-constrained educational campuses.
RGB LED commands installed base across commercial volume applications. MicroLED is gaining share fastest in premium tier displacement of legacy projection and LCD video walls.
Application:
Specification intensity varies from infection-control luminance requirements in healthcare navigation to fashion-driven refresh cycles in retail entertainment, fragmenting vendor qualification criteria.
- Corporate Lobbies:Brand immersion installations prioritize seamless form factors and architectural integration. Transparent LED and curved configurations dominate in Seoul and Frankfurt headquarters buildings.
- Shopping Complexes:High-ambient-light environments drive brightness specifications above 800 nits. RGB LED and poster LED configurations serve tenant mix requirements from luxury to fast fashion.
- Public Transportation Hubs:24/7 reliability mandates and EMC certification complexity filter vendor pools. Narrow pixel pitch and direct view LED serve wayfinding and real-time information display.
- Museums:Conservation-grade specifications limit UV emission and thermal load on artifacts. Transparent LED preserves sightlines while meeting lux-level restrictions in Paris and New York institutions.
- Exhibition Booths:Temporary deployment models favor rapid-install direct view LED and rental-service business models.
- Educational Institutes:Budget constraints and multi-purpose usage drive standardization on surface mount device LED and poster LED formats.
Shopping complexes hold the largest installed base by unit volume. Corporate lobbies represent the steepest expansion trajectory as headquarters construction resumes in United States and German commercial real estate markets.
End User:
Procurement sophistication spans from centralized AV standards in multinational retail chains to fragmented departmental purchasing in educational campuses, shaping vendor route-to-market requirements.
- Retail Chains:Centralized procurement functions specify network-managed signage platforms with remote content distribution. Narrow pixel pitch and poster LED dominate flagship and inline store formats respectively.
- Transportation Authorities:Public-sector tender processes mandate lifecycle carbon disclosure and modular serviceability under EU Ecodesign and F-Gas Regulation compliance frameworks.
- Hospitality Venues:Experience-driven specifications prioritize aesthetic integration and content flexibility. Curved LED and transparent LED capture premium positioning in Dubai and Singapore integrated resort developments.
- Corporate Offices:Hybrid workplace redesigns are expanding lobby and collaboration space signage budgets. MicroLED pilot installations concentrate in technology sector headquarters.
- Entertainment Centers:Immersive environment requirements drive floor LED and curved LED specifications for interactive guest engagement.
- Educational Campuses:Deferred maintenance backlogs and distributed purchasing constrain specification to cost-optimized surface mount device LED and poster LED formats.
Retail chains dominate current installed base by revenue value. Transportation authorities are where procurement volume is concentrating as infrastructure modernization programs accelerate in Germany, France, and South Korea.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. German buyers absorb premium pricing for F-Gas-compliant systems, while Indian retail chains prioritize cost-per-lumen thresholds above architectural integration.
United States
Corporate headquarters construction in Dallas and Atlanta drives transparent LED specifications for lobby installations. The EPA Energy Star program mandates disclosure of standby power consumption for federal procurement eligibility. Chicago O'Hare and Atlanta Hartsfield-Jackson airports deploy narrow pixel pitch systems for 24/7 passenger information displays.
Germany
Public-sector tender volume concentrates in municipal traffic management and cultural institutions. The EU F-Gas Regulation and Ecodesign directives enforce modular serviceability and lifecycle carbon accounting. Frankfurt and Munich corporate campuses specify narrow pixel pitch below 0.9mm for executive briefing environments.
South Korea
Seoul Capital Area corporate lobbies and broadcast studios anchor premium-tier demand for MicroLED pilot deployments. The country's national broadcasting regulator enforces luminance standards for studio display certification. Busan-Ulsan manufacturing clusters supply LED backplane substrates to domestic display integrators.
India
Production-linked incentives under the PLI scheme attract LED module assembly investments serving domestic retail modernization. Mumbai and Delhi shopping complexes drive poster LED volume for tenant mix flexibility. The Bureau of Indian Standards certifies electromagnetic compatibility for public installation safety.
United Arab Emirates
Dubai hospitality venues and integrated resorts specify curved LED and floor LED for immersive guest engagement environments. The country's telecommunications regulator governs RF emissions for smart signage network integration. Abu Dhabi museum developments prioritize transparent LED for conservation-grade artifact display.
Smart LED Indoor Signage Market Key Industry Players
Capability concentration sits with semiconductor fabrication specialists; scale advantage sits with display system integrators. The market structures around three tiers: captive component producers, vertical assemblers, and specialized narrow-pixel fabricators. Consolidation pressures mount as R&D amortization timelines compress and foundry partnerships determine premium-tier access. Dominant competitive moves include backward integration into LED epitaxy and strategic alliances for MicroLED transfer yield improvement.
Within the captive supply tier, Samsung Electronics and LG Electronics occupy positions anchored by in-house semiconductor depth. Leyard Optoelectronic exemplifies the specialized fabricator archetype, with its nomenclature indicating Chinese optoelectronic concentration. These three entities represent divergent strategic postures: semiconductor-led vertical control, display-system integration, and narrow-pixel specialization for mission-critical deployments.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Panasonic Corporation |
| NEC Corporation |
| Sharp NEC Display Solutions |
| Daktronics |
| Leyard Optoelectronic |
| AUO Corporation |
| Others |
Cost & Logistics Intelligence
Incheon-to-Frankfurt air freight corridors carry gallium nitride wafers and MicroLED backplane substrates where cargo cost spikes ripple through procurement budgets for German command-center installations and compress margins on premium-tier transparent LED deployments in Seoul corporate lobbies.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers now drive lifetime value capture, with three-tier pricing structure across premium, standard, and economy levels separating MicroLED pilot deployments from RGB LED volume procurement. Price differentiation rests on pixel density certification grades and F-Gas Regulation compliance status. Pricing pressure stems from unbundled procurement trends as US retail chains separately tender hardware, software, and maintenance. Educational campuses exhibit highest price sensitivity; corporate headquarters and broadcast studios show lowest.
Supply Chain Analysis
Gallium substrate feedstock draws from Japanese sapphire specialists and Taiwanese silicon carbide fabricators where supply concentrates among Sumco and II-VI operations. LED epitaxy equipment and pick-and-place transfer systems hinge on South Korean and German precision engineering. Single-source vulnerability in gallium nitride wafers threatens MicroLED scaling timelines. Distribution runs through specialized AV integrators and direct OEM channels to end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as content management software ecosystems displace hardware-centric margin capture, with interoperability between signage networks and building automation systems unlocking new revenue architectures.
For Market Incumbents: Insulate proprietary service revenue by accelerating captive software platform development and securing exclusive foundry partnerships for MicroLED backplane supply. Modular design mandates under EU Ecodesign threaten integrated maintenance contracts. Backward integration into LED epitaxy and substrate sourcing defends against gallium supply concentration risks.
For New Entrants and Emerging Players: Build out narrow pixel pitch assembly capabilities targeting Indian retail modernization under PLI scheme incentives, where domestic production requirements filter out established import-dependent suppliers. Healthcare wayfinding systems represent the most penetrable application segment with stringent luminance specifications that favor specialized engineering over brand recognition.
For Investors and Strategic Acquirers: Semiconductor fabrication specialists with captive LED epitaxy capabilities present the highest long-term viability profile across the analysis window as R&D amortization timelines compress and foundry access determines premium-tier market participation. Watch MicroLED transfer yield breakthroughs as the inflection signal for premium-tier displacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for MicroLED Backplane | Samsung Electronics leverages in-house semiconductor depth to control captive supply and lock out competitors from premium-tier pilot deployments. |
| Content Management Platform Integration | LG Electronics anchors ecosystem stickiness through proprietary software layers that resist unbundling pressures from US retail procurement offices. |
| Narrow Pixel Pitch Specialization | Leyard Optoelectronic concentrates engineering resources on sub-0.9mm assemblies for German traffic management and South Korean security operations. |
| PLI Scheme Manufacturing Localization | Domestic LED module assembly investments in India serve Mumbai and Delhi shopping complexes while meeting local content thresholds. |
| AI-Driven Content Optimization | Convergence of computer vision and edge processing enables real-time audience analytics that differentiates network-managed signage platforms. |
Research Approach
Cross-validation between primary interviews with display system procurement managers, AV integration specialists, semiconductor fabrication engineers, and regulatory compliance officers anchors the qualitative findings against secondary validation from EPA Energy Star certification databases, FCC Part 15 filings, EU Ecodesign directive documentation, and SEC 10-K disclosures from listed display manufacturers. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing across product type, technology, application, and end-user segmentation dimensions.
Calibration against historical replacement cycle data and procurement elasticity patterns shapes the analytical framework across the projection horizon. Segmentation modeling incorporates pixel pitch tier, display technology maturity stage, installation environment specification intensity, and regional regulatory compliance cluster. CAGR derivation synthesizes vendor shipment disclosures, import-export trade flows, and infrastructure investment pipeline tracking from transportation authority and retail chain capital expenditure announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese optoelectronic specialists or gallium substrate diversifiers would shift outcomes beyond modeled ranges. Cross-checking against Bureau of Indian Standards certification timelines and Korean broadcasting regulator luminance mandates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Europe Outdoor LED Lighting Market
LED
LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
Gan Micro LED Market
LED
Superluminescent Diodes Market
LED
UAE LED Lights Market
LED
Dot-Matrix LED Displays Market
LED
Global LED Phosphor Market
LED
Light Emitting Diode (LED) Backlight Display Market
LED
Thailand LED Market
LED
Global Waterproof LED Module Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
7 Segment LED Displays Market