
 UK LED Lighting Market | 2026-2036
UK LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
UK LED Lighting Market Insights
The capability gap between vertically integrated manufacturers and assembly-only competitors is rotating competitive advantage toward firms controlling chip sourcing and thermal engineering. Signify UK Ltd leverages its semiconductor partnerships to sustain margin resilience across public infrastructure tenders. Dialight plc anchors its position in hazardous-environment specifications where certification barriers limit new entrants.
UK LED lighting encompasses solid-state luminaires utilizing gallium nitride-based emitters operating between 2700K and 6500K correlated colour temperature, with efficacy thresholds typically exceeding 100 lumens per watt for commercial-grade products; these devices convert electrical current directly to visible light through electroluminescence, eliminating filament degradation and enabling directional output for task-specific illumination. Bulbs and fixtures dominate installed value across the residential and commercial application segments, while smart technology variants capture expanding share as building management systems integrate occupancy sensing and daylight harvesting protocols. Downlights compete intensely in retrofit channels where ease of installation determines contractor preference, and tunable white systems lead specification growth in healthcare and education environments.
BEIS energy efficiency mandates and the UK's continued alignment with Ecodesign standards shape minimum performance thresholds for domestic sales, while BSI Kitemark certification governs safety compliance in commercial and industrial deployment. The Environment Agency's WEEE enforcement directs end-of-life collection obligations back to producers, tightening cost structures for import-dependent distributors. Stakeholders must monitor regulatory divergence negotiations and decide whether to maintain dual-compliance inventories or commit fully to UK-specific testing regimes.
Market Dynamics
Retrofit mandates across UK distribution infrastructure are compressing replacement cycles and concentrating procurement authority with facilities managers who prioritize total-cost-of-ownership metrics over upfront fixture pricing.
Growth Catalysts
- BEIS Minimum Energy Efficiency Standards:Commercial landlords face compliance deadlines that accelerate LED upgrades across Class A office stock in Greater London and Manchester.
- Warehouse automation:Robotics integration in Midlands distribution centers demands high-CRI, flicker-free illumination for machine vision systems operating 24-hour cycles.
- Gallium nitride chip architecture:Next-generation emitters reduce thermal management costs and enable slimmer fixture profiles for heritage building retrofits.
Market Restraints
- Driver component concentration:Taiwan and China-based semiconductor foundries control 80% of LED driver IC supply, exposing UK assemblers to shipping volatility and currency fluctuation.
- WEEE compliance costs:Environment Agency enforcement of producer responsibility obligations raises per-unit administrative burden for import-dependent distributors without UK manufacturing presence.
- Incumbent fixture longevity:First-generation LED installations from 2012-2016 are failing to reach projected 50,000-hour lifespans, eroding buyer confidence in manufacturer claims.
Strategic Opportunities
- Human-centric lighting:Circadian rhythm protocols in NHS hospital wards and Scottish education facilities create specification pull for tunable-white systems with melanopic output control.
- Li-Fi convergence:Integration of visible light communication with building management systems offers data infrastructure redundancy for financial services headquarters in the City of London.
- Rural commercial underpenetration:Independent retailers and hospitality operators in Northern England and Wales remain reliant on legacy halogen, presenting retrofit volume for contractor-network expansion.
Industry Challenges
- Thermal engineering talent scarcity:British universities produce insufficient graduates with compound semiconductor packaging expertise, forcing manufacturers to recruit from Netherlands and Germany.
- BSI Kitemark certification timelines:Commercial product approval processes extend 14-22 weeks, delaying contractor payments and compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK LED Lighting Market |
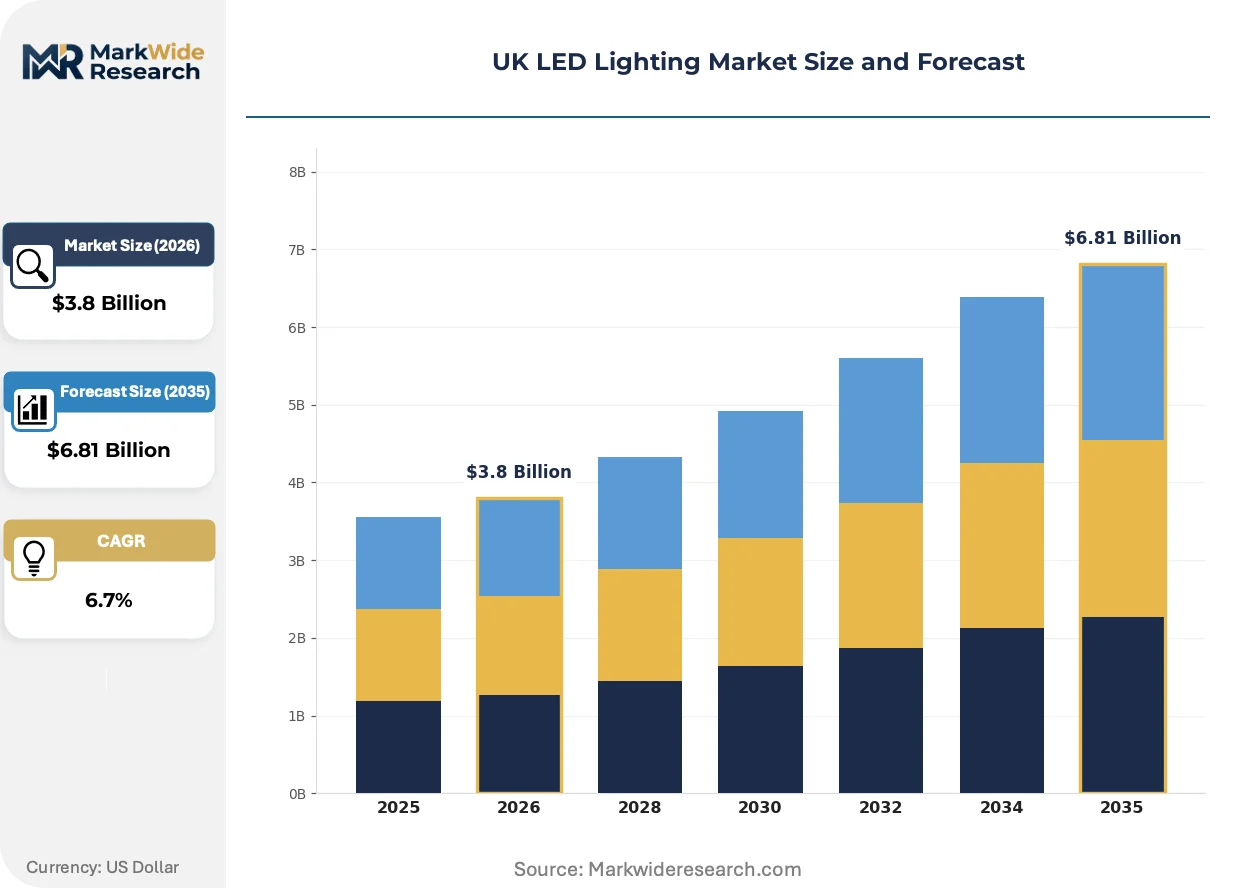
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Downlights Application: Residential, Commercial, Industrial, Outdoor Technology: Smart, Traditional, Tunable White, Dimmable End User: Households, Offices, Retail, Warehouses |
| Companies Covered | Dialight plc, Aurora Lighting Group, Signify UK Ltd, FW Thorpe plc, Crompton Lamps Limited, Osram Lighting Ltd, Thorlux Lighting, Tamlite Lighting, LEDVANCE Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK LED Lighting Market Trends and Innovations
Power-over-Ethernet infrastructure is rewiring how building systems integrate illumination, data, and environmental controls through single-cable architecture that reduces installation labor and enables granular zone management.
Chip-on-board LED modules is supplanting discrete SMD packages in high-bay industrial applications by eliminating solder joint failure modes and improving lumen density per square centimeter. Warehouse operators in the East Midlands are specifying COB fixtures for new-build distribution centers, compressing maintenance intervals from annual to triennial cycles and reducing lift equipment rental costs.
BEIS consultation on tightening Part L building regulations is mandating lower lighting power density limits for non-domestic construction, forcing specifiers to abandon legacy fluorescent designs. The proposed 2025 amendments target retail and office segments most aggressively, with draft guidance requiring automatic daylight dimming in all new commercial builds over 500 square meters.
Facilities management consortia are consolidating lighting procurement through framework agreements that unbundle installation from product supply, shifting margin capture toward national contractors with direct manufacturer relationships. This concentration is most visible across NHS estates and university campuses, where aggregated tender volumes exceed single-site retrofit economics and favor suppliers with UK-based technical support teams.
UK LED Lighting Market Segmentation
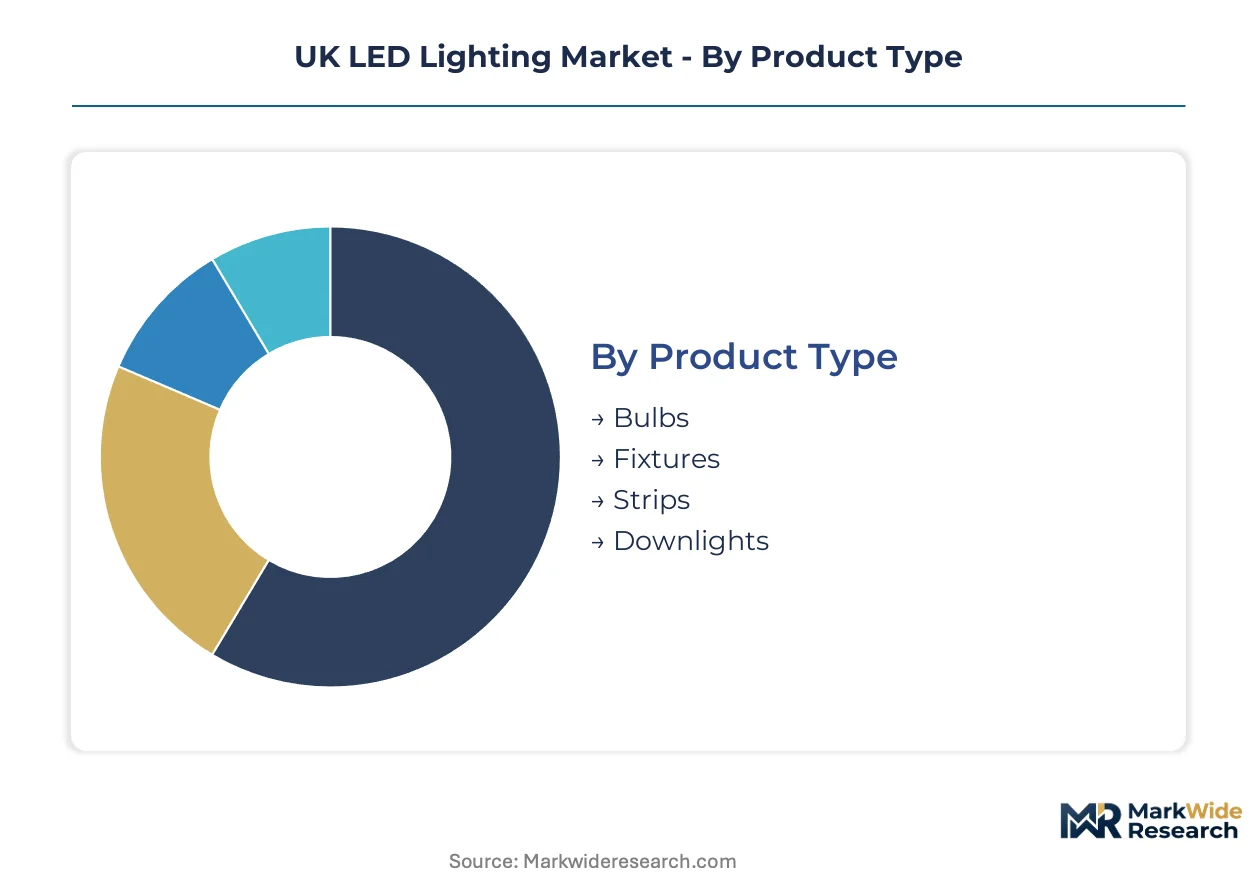
Segmentation in the UK LED lighting market reveals how regulatory pressure and retrofit economics concentrate demand across distinct procurement channels. Each dimension exposes different margin structures, certification burdens, and installation complexity that shape supplier positioning.
Product Type:
BEIS Ecodesign requirements and Part L building regulations create divergent compliance obligations across form factors, with integrated fixtures facing stricter thermal performance testing than replaceable lamps.
- Bulbs:Retrofit lamps utilizing Edison screw or bayonet bases deliver immediate efficiency gains without electrical modification. Residential demand concentrates in Greater London's private rental sector where Minimum Energy Efficiency Standards compel landlord upgrades ahead of compliance deadlines.
- Fixtures:Luminaires with integrated LED engines and dedicated thermal management eliminate lamp replacement cycles. Commercial refurbishment pipelines across Manchester and Birmingham specify these for new-build and deep retrofit projects where 50,000-hour lifespan claims justify premium first cost.
- Strips:Linear flexible arrays serve cove lighting and display accent applications. Retail fit-outs in West Midlands shopping centers drive specification for continuous illumination without dark zones.
- Downlights:Recessed ceiling modules dominate residential retrofit where ease of installation determines contractor preference. Fire-rated variants with intumescent seals command specification in multi-occupancy dwellings under Building Regulations Part B.
Fixtures handle the majority of throughput; Downlights is expanding most quickly on share.
Application:
Cost tier differentiation separates specification-grade systems from commodity procurement, with payback period thresholds varying sharply across use cases.
- Residential:Owner-occupied and rental housing stock drives replacement demand through energy cost savings and MEES compliance pressure. Retrofit activity concentrates in Southeast England's aging housing stock where halogen phase-out created immediate replacement need.
- Commercial:Offices, retail, and hospitality facilities prioritize total-cost-of-ownership metrics over upfront fixture pricing. Greater London's Class A office refurbishment pipeline accounts for disproportionate specification volume as landlords face BEIS compliance deadlines.
- Industrial:High-bay and hazardous-area installations demand high-CRI, flicker-free output for machine vision and safety-critical operations. East Midlands distribution centers specify these for 24-hour robotics integration.
- Outdoor:Street furniture, roadway, and amenity lighting falls under local authority procurement frameworks. CPO-led framework agreements aggregate demand across municipal boundaries, favoring suppliers with UK-based technical support.
Commercial commands the largest installed base; Industrial is gaining share fastest.
Technology:
Customer type fragmentation separates building management system integrators from standalone procurement, with connectivity requirements driving specification divergence.
- Smart:Networked luminaires with embedded sensors enable occupancy detection, daylight harvesting, and energy metering. NHS estates and university campuses specify these through framework agreements that unbundle installation from product supply.
- Traditional:Non-connected LED engines with fixed output and basic switching. Independent retailers and hospitality operators in Northern England and Wales remain reliant on these for cost-constrained retrofit.
- Tunable White:Correlated colour temperature adjustment from 2700K to 6500K supports circadian rhythm protocols. Scottish education facilities and hospital wards create specification pull for melanopic output control.
- Dimmable:Phase-cut or DALI-controlled output reduction for ambient adjustment. Residential and commercial retrofit channels specify these where existing wiring infrastructure limits smart system deployment.
Traditional still handles volume throughput; Tunable White is climbing the fastest on specification share.
End User:
Supply concentration in driver semiconductor foundries exposes different procurement risk profiles across end-use segments, with volume buyers negotiating direct manufacturer relationships.
- Households:Consumer-directed purchase through retail and e-commerce channels, with energy efficiency labeling driving selection. Online marketplaces capture growing share as price transparency compresses distributor margins.
- Offices:Facilities management consortia and landlord entities aggregate demand across multi-site portfolios. Procurement authority concentrates with national contractors who capture margin through installation bundling.
- Retail:Brand-led fit-out specifications prioritize color rendering and beam control for merchandise presentation. Shopping center operators in West Midlands and Greater Manchester drive replacement cycles through landlord contribution mechanisms.
- Warehouses:Logistics operators in East Midlands and Yorkshire specify high-bay systems for new-build and retrofit automation projects. Chip-on-board modules with triennial maintenance intervals reduce lift equipment rental costs.
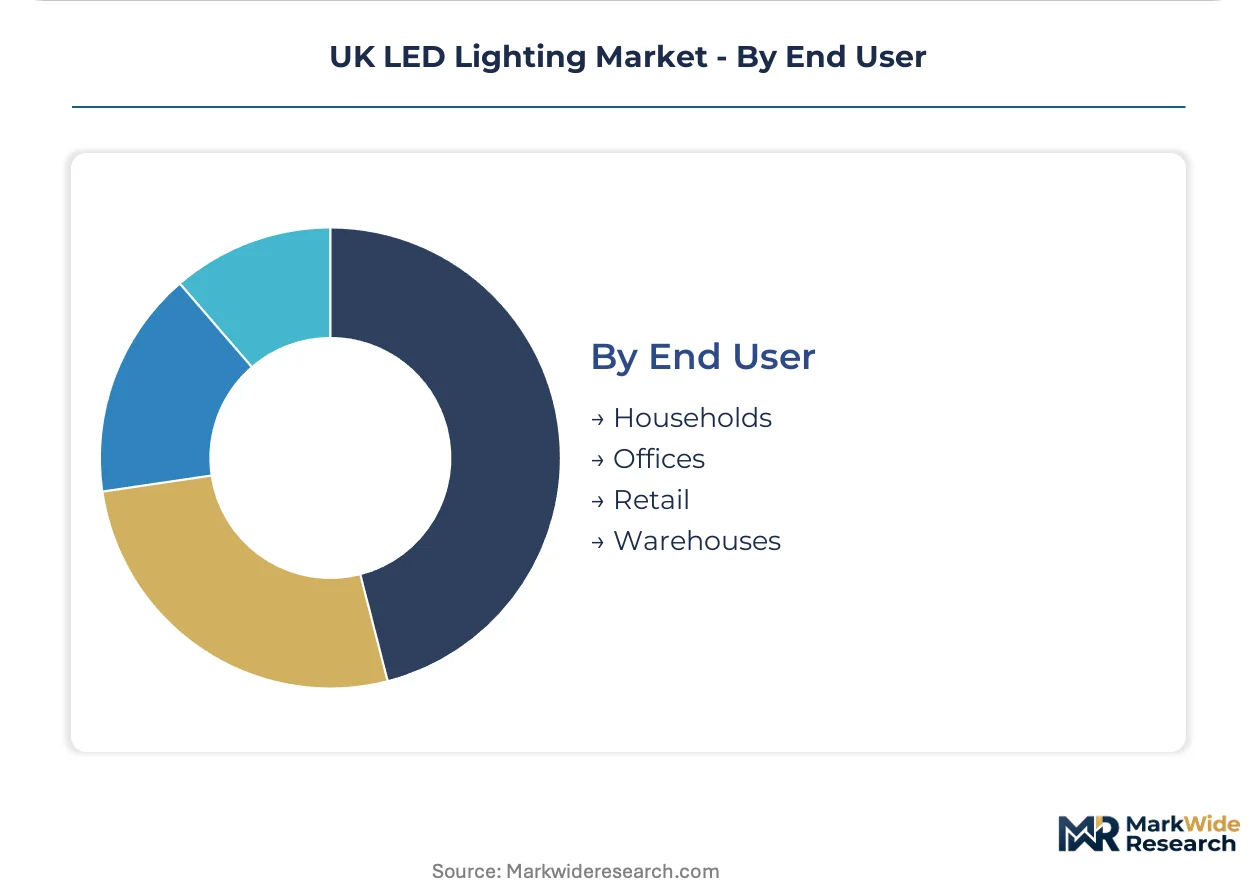
Offices dominates procurement volume; Warehouses is expanding fastest on retrofit momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the United Kingdom diverge sharply between Greater London's commercial refurbishment intensity and the retrofit lag in Northern England's independent retail sector. BEIS compliance deadlines concentrate procurement authority with facilities managers in England's core cities while Scottish education and NHS estates drive specification for human-centric systems.
London and the Southeast
Class A office stock in the City of London and Canary Wharf faces BEIS Minimum Energy Efficiency Standards deadlines that compress replacement cycles. The Greater London Authority's planning frameworks mandate lower lighting power density for new commercial builds over 500 square meters. Developments in King's Cross and Battersea Power Station specify tunable-white systems with daylight harvesting protocols.
Midlands
East Midlands distribution centers anchor industrial LED demand as warehouse automation accelerates retrofit programs. Derbyshire and Leicestershire logistics hubs specify chip-on-board high-bay fixtures for 24-hour robotics operations. West Midlands shopping centers in Birmingham and Solihull drive retail fit-out specifications for continuous linear strip lighting.
North England
Manchester's commercial refurbishment pipeline concentrates procurement authority with national contractors holding framework agreements. Yorkshire warehousing clusters around Leeds and Sheffield expand retrofit volumes for logistics operators. Independent hospitality operators in Cumbria and Northumberland remain reliant on legacy halogen, presenting contractor-network expansion opportunities.
Scotland
NHS Scotland estates and Scottish education facilities generate specification pull for circadian rhythm protocols with melanopic output control. The Scottish Government's energy efficiency programs accelerate public sector retrofit timelines. Hospital wards in Edinburgh and Glasgow specify tunable-white systems for patient recovery environments.
Wales
Rural commercial underpenetration characterizes Welsh demand, with independent retailers and hospitality operators in Cardiff and Swansea slower to adopt LED retrofit. Welsh Government procurement frameworks aggregate public sector demand across NHS Wales and university campuses. Heritage building constraints in Snowdonia and Pembrokeshire limit fixture profile options.
UK LED Lighting Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the UK LED lighting market, with vertical integration into semiconductor sourcing and thermal engineering separating margin-resilient players from assembly-only competitors. The specialist tier fragments across hazardous-environment certification holders, heritage retrofit specialists, and smart building system integrators. Two dominant competitive moves define current positioning: framework agreement consolidation with NHS and university estates, and backward integration into gallium nitride chip architecture for fixture slimming.
Within the integrated leader tier, Signify UK Ltd and Dialight plc anchor contrasting strategic positions. Signify occupies a position defined by semiconductor partnerships and public infrastructure tender resilience. Dialight exemplifies hazardous-environment specialization where certification barriers limit competitive entry. Aurora Lighting Group sits within the mid-tier specialist segment, representing the contractor-preferred retrofit channel focused on downlight ease-of-installation.
| Leading Market Players |
|---|
| Dialight plc |
| Aurora Lighting Group |
| Signify UK Ltd |
| FW Thorpe plc |
| Crompton Lamps Limited |
| Osram Lighting Ltd |
| Thorlux Lighting |
| Tamlite Lighting |
| LEDVANCE Ltd |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride chip architecture substitution for legacy silicon-based emitters simultaneously relocates sourcing gravity toward Taiwan and South Korea semiconductor foundries while compressing fixture pricing through reduced thermal management costs. This input transition concentrates procurement leverage with volume buyers negotiating direct manufacturer relationships.
Pricing Analysis
Long-term framework agreements dominate commercial procurement, particularly across NHS estates and university campuses where aggregated tender volumes exceed single-site economics. Three-tier pricing structure across premium specification-grade, standard commercial-grade, and economy retrofit tiers separates certified hazardous-environment fixtures from commodity downlights. Pricing pressure stems from facilities management consortia unbundling installation from product supply, compressing distributor margins. Independent retailers in Northern England and Wales exhibit highest price sensitivity, while specification-grade buyers prioritize total-cost-of-ownership metrics.
Supply Chain Analysis
Strategic stockpiling of LED driver ICs characterizes UK assembler behavior given Taiwan and China-based foundry concentration, contrasting with just-in-time preferences for passive components. Semiconductor sourcing rests on Taiwan, China, and South Korea manufacturing clusters. Gallium nitride wafers, aluminum substrates, and phosphor compounds constitute critical input dependencies. Single-source vulnerability in driver IC supply exposes assemblers to shipping volatility and currency fluctuation. Distribution runs through national contractor networks holding direct manufacturer relationships, particularly for commercial framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal engineering expertise scarcity constrains UK manufacturer expansion, with British universities producing insufficient compound semiconductor packaging graduates and forcing recruitment from Netherlands and Germany.
For Market Incumbents: Fortify positions through backward integration into gallium nitride chip architecture and captive supply of thermal management components. Prioritize framework agreement consolidation with NHS and university estates where aggregated volumes justify UK-based technical support investment. Defend against emerging specialist competitors by accelerating BSI Kitemark certification timelines for new product introductions. For New Entrants and Emerging Players: BSI Kitemark fast-track pathways offer entry acceleration for heritage retrofit specialists targeting slim-profile fixture demand. Penetrate Northern England and Wales independent hospitality sectors where legacy halogen dependence persists and contractor-network expansion remains underdeveloped. Pursue specification-grade positioning in Scottish education and NHS circadian rhythm protocols where tunable-white expertise gaps exist. For Investors and Strategic Acquirers: The market sits at a retrofit-mandate acceleration phase that favors vertically integrated manufacturers with semiconductor sourcing control over assembly-only competitors. Long-term viability hinges on five-to-ten year positioning around human-centric lighting and Li-Fi convergence capabilities. Monitor BEIS Part L building regulation tightening as inflection indicator for specification-grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Chip Architecture | Captive supply of gallium nitride emitters reduces thermal management costs and enables heritage building retrofit penetration. |
| Framework Agreement Consolidation | Direct relationships with NHS estates and university campuses aggregate tender volumes and compress competitor access. |
| Human-Centric Lighting Certification | Melanopic output control credentials unlock Scottish education and healthcare specification channels. |
| Li-Fi Convergence Development | Visible light communication integration offers data infrastructure redundancy for City of London financial services headquarters. |
| Contractor Network Expansion | Installation bundling capability captures margin in Northern England and Wales underpenetrated commercial retrofit markets. |
Research Methodology
Desk research of regulatory filings from BEIS and the Environment Agency, trade customs data, and BSI certification databases preceded structured interviews with facilities management directors, electrical contractors, semiconductor procurement leads, and lighting specification consultants. Primary fieldwork combined with secondary validation across SEC filings, WEEE enforcement records, and NHS procurement frameworks. Bottom-up segment sizing and top-down macroeconomic reconciliation ensured analytical triangulation.
Variance decomposition across product type, application, technology, and end user dimensions informed projection construction over the analysis window. CAGRs derived from installed base replacement cycle analysis, regulatory compliance deadline mapping, and automation-driven demand elasticity. Gallium nitride chip cost curves and thermal engineering labor market constraints served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued BEIS Ecodesign alignment and stable Taiwan semiconductor foundry output; material deviation would warrant model refresh. Specific risks include regulatory divergence negotiations, driver IC supply disruption, and first-generation LED lifespan claim erosion affecting buyer confidence. Revision becomes warranted when WEEE compliance cost thresholds or gallium nitride chip pricing crosses inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Panel Light Drivers Market
LED
LED Panel Market
LED
Japan Outdoor LED Lighting Market
LED
Mini LED Display Market
LED
Germany Outdoor LED Lighting Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
Africa LED Lighting Market
LED
Brazil LED Market
LED
LED Floodlight Drivers Market
LED
LED and OLED Display Market
LED
LED Work Light Market
LED
LED Services Market
LED
UV-C LED Market
LED
LED Lighting Solution Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Linear LED Strip Fixture Market