
 Linear LED Strip Fixture Market | 2026-2036
Linear LED Strip Fixture Market Size, Share, and Industry Trends Forecast 2026-2036
Linear LED Strip Fixture Market Analytics
Aftermarket service revenue is reconfiguring profit distribution across the Linear LED Strip Fixture value chain. Signify leverages its connected lighting platforms to capture recurring software and maintenance income beyond hardware sales. Acuity Brands anchors North American specification-grade projects through deep contractor relationships and design assistance programs. Osram competes in European industrial retrofits with high-efficacy modules that emphasize lumen maintenance over extended operating hours.
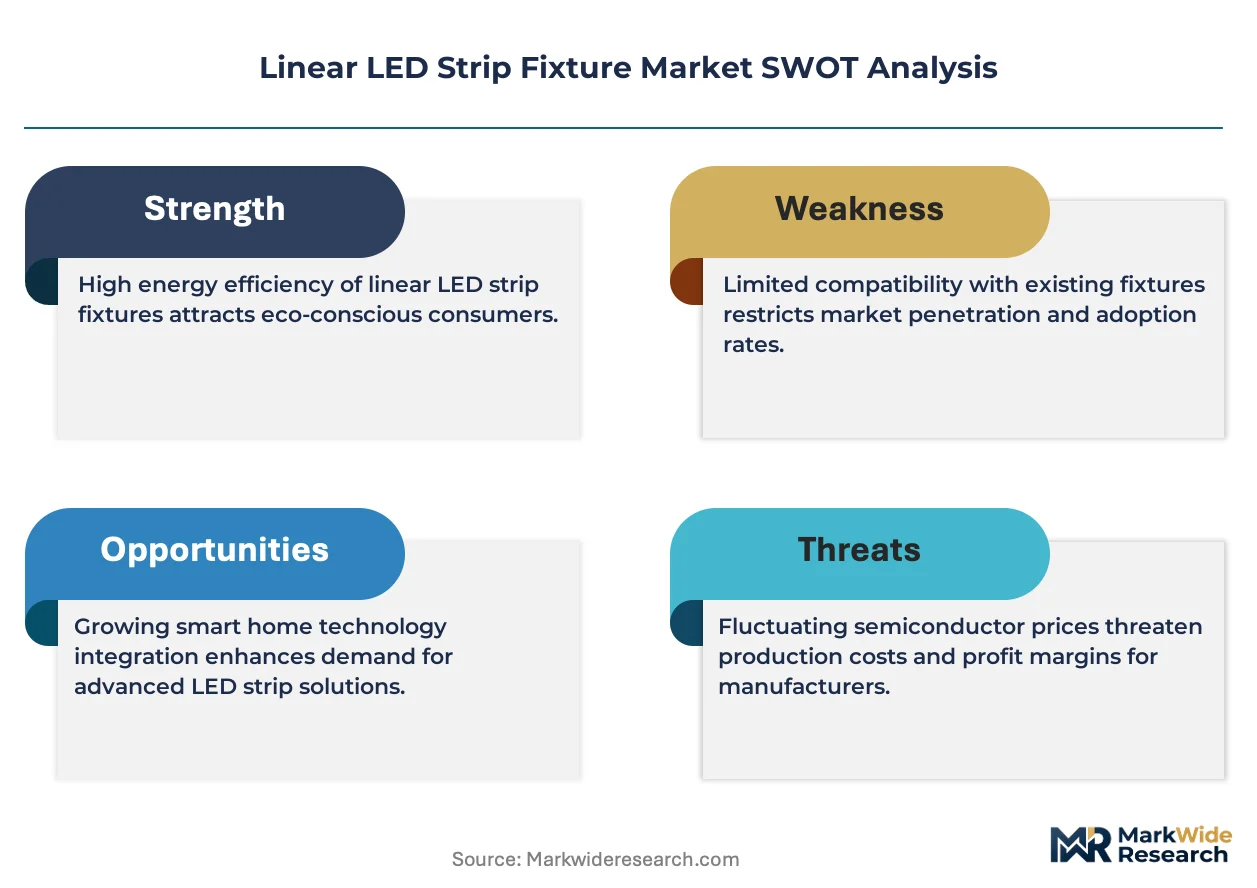
A linear LED strip fixture is a rigid or flexible luminaire housing surface-mounted or embedded LED arrays, typically operating at 12V to 48V DC or 120V to 277V AC with color temperatures spanning 2700K to 6500K, designed for continuous ambient, task, or accent illumination in commercial, residential, and industrial environments. Waterproof strip products command premium positioning in food processing, cold storage, and exterior architectural applications where ingress protection ratings determine specification eligibility. Smart strip technology integrating wireless control and Bluetooth enabled protocols is capturing the fastest expansion as facility managers prioritize zone-level dimming and occupancy-responsive operation over static installations.
The US Department of Energy enforces minimum efficacy standards through ENERGY STAR and DLC qualification requirements that filter non-compliant imports from utility rebate eligibility. The EU Ecodesign Directive and RoHS substance restrictions mandate recyclability thresholds and hazardous material limits that reshape component sourcing for fixtures sold in European member states. Stakeholders must monitor evolving interoperability standards between proprietary wireless protocols and open building automation frameworks to avoid stranded technology commitments in multi-vendor installations.
Market Dynamics
Building energy codes are compressing replacement cycles across commercial real estate, forcing facility managers to abandon fluorescent troffers ahead of scheduled maintenance intervals. This regulatory pressure is concentrating procurement authority with sustainability officers who prioritize connected lighting platforms over commodity hardware.
Growth Catalysts
- ENERGY STAR qualification thresholds:US utility rebate programs now require DLC Premium certification, filtering imports and redirecting procurement toward compliant domestic manufacturers.
- Food processing cold storage:IP67-rated waterproof strips are displacing vapor-tight fluorescents in USDA-inspected facilities where sanitation protocols demand hose-down capability.
- German smart building mandates:The EU Green Deal's building renovation wave is accelerating BMS integration requirements in commercial retrofits across German federal states.
Market Restraints
- Aluminum extrusion cost volatility:Housing material costs fluctuate with London Metal Exchange pricing, squeezing margin on specification-grade fixtures.
- Driver supply concentration:Taiwan and mainland China dominate LED driver manufacturing, creating single-source vulnerability for North American assemblers.
- RoHS substance complexity:ECHA's expanding restricted substance list forces reformulation of solder and phosphor compositions for European market access.
Strategic Opportunities
- India commercial real estate:BIS energy efficiency standards are newly mandatory in metro office construction, opening specification-grade demand in Bangalore and Mumbai.
- Horticultural cultivation:Full-spectrum tunable strips for vertical farming converge LED efficacy with crop science, penetrating controlled-environment agriculture.
- Utility-managed lighting-as-a-service:US demand-response programs enable third-party ownership models where utilities capture efficiency incentives.
Industry Challenges
- Controls integration talent scarcity:Facility engineering teams lack expertise commissioning Bluetooth mesh networks with legacy BACnet infrastructure.
- DLC certification timeline compression:Testing laboratory backlog extends product qualification cycles, delaying rebate eligibility and seasonal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear LED Strip Fixture Market |
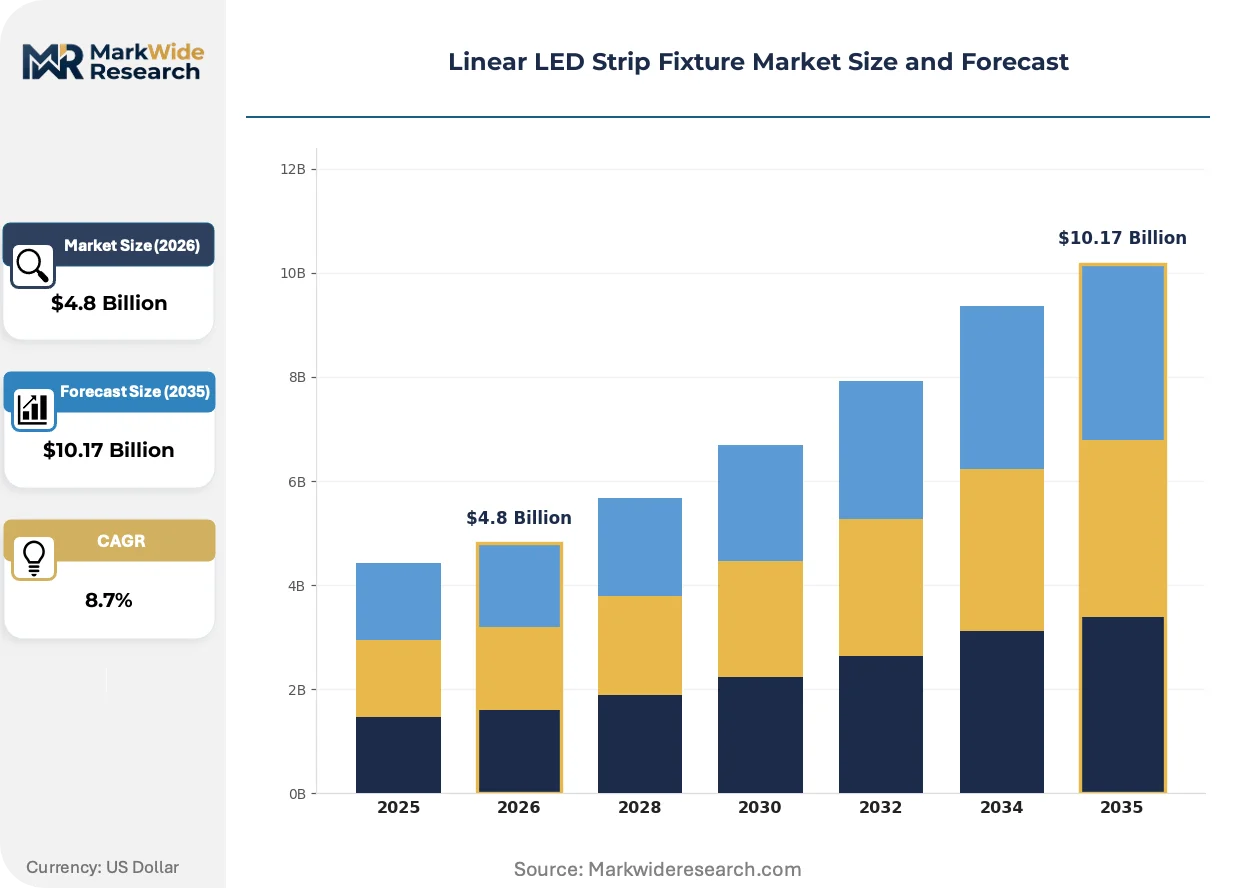
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Strip, Waterproof Strip, RGB Strip, Smart Strip Application: Commercial Spaces, Residential Lighting, Industrial Use, Event Decor Technology: AC Powered, DC Powered, Wireless Control, Bluetooth Enabled Installation Method: Surface Mount, Recessed Mount, Pendant Mount, Track Mount |
| Companies Covered | Acuity Brands, Philips, Osram, Cree Lighting, Signify, Zumtobel, American Lighting, Elemental LED, Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear LED Strip Fixture Market Evolving Landscape
Digital twin architectures are penetrating lighting specification, compressing the gap between design simulation and operational performance. This convergence is redistributing value toward software-enabled suppliers.
Power-over-Ethernet (PoE) distribution is virtualizing the traditional line-voltage infrastructure for LED strip deployments. Corporate campus developers in Texas and California are specifying PoE backbone networks during shell construction, collapsing electrical and data contracting scopes into single-trade installation. This technology is virtualizing the conventional segregation between lighting and IT infrastructure departments.
REACH authorization requirements are tightening supply chain documentation for phosphor and rare-earth components used in high-CRI LED packages. ECHA's 2024 substance evaluation roadmap is forcing fixture assemblers to audit upstream material declarations or risk market withdrawal. German industrial lighting specifications now require full SCIP database registration, adding compliance overhead that favors vertically integrated European manufacturers over import-dependent distributors.
Specification authority is migrating from electrical contractors to sustainability consultants who bundle lighting upgrades with carbon accounting services. Commercial office landlords in New York and London are procuring strip fixtures through performance contracts where payment ties to measured energy reduction, not unit volume. This model concentrates buyer power with national facility management platforms that aggregate multi-site retrofit demand.
Linear LED Strip Fixture Market Segmentation
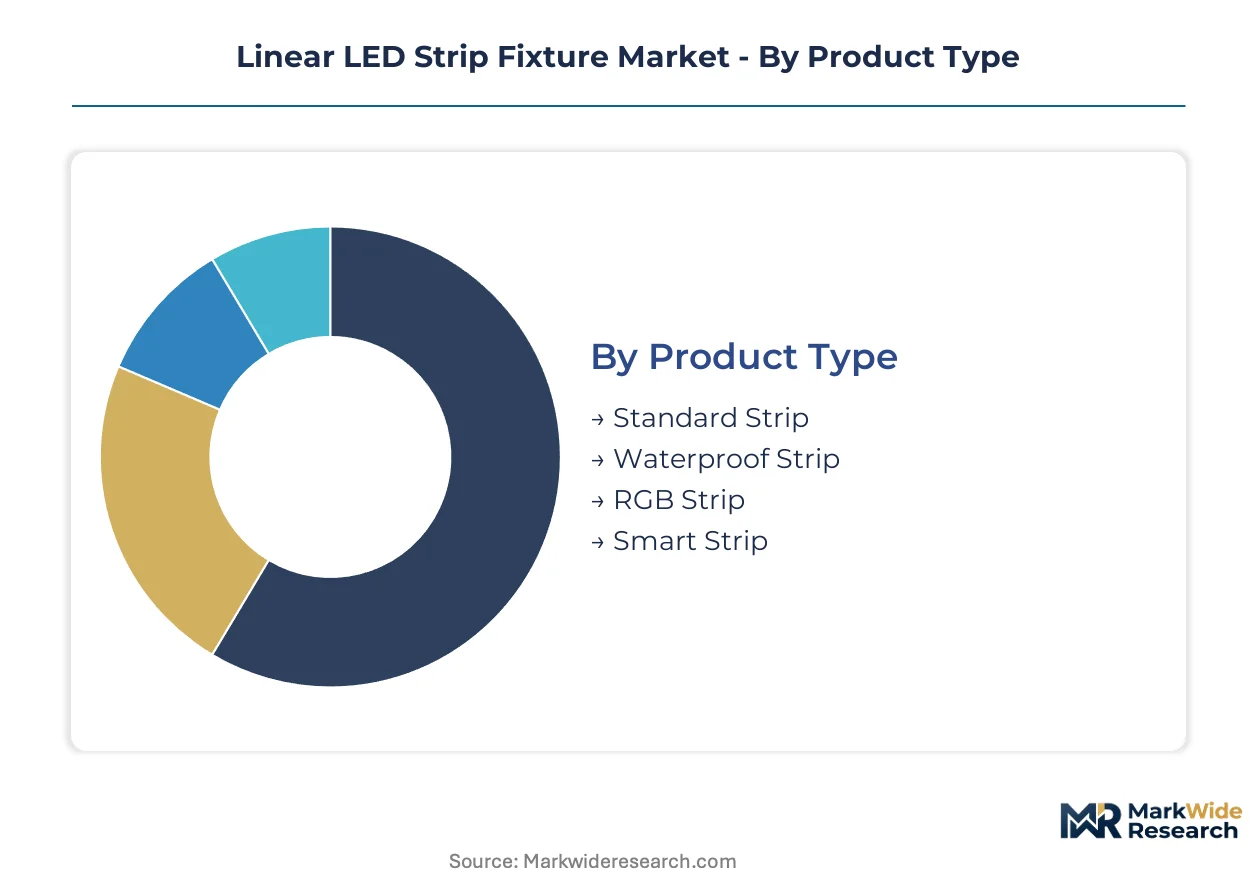
Linear LED strip fixture segmentation reveals divergent replacement cycles across product architectures. Waterproof and smart variants command accelerated upgrade schedules driven by sanitation mandates and software obsolescence, while standard strips follow slower capital refresh patterns tied to building renovation timelines.
Product Type:
Replacement velocity separates commodity strips from engineered variants, with connected products cycling fastest due to firmware deprecation and protocol evolution.
- Standard Strip:Basic 12V-48V DC or 120V-277V AC linear arrays with fixed CCT, typically 2700K-6500K, mounted via adhesive backing or aluminum channel extrusions. Office retrofit programs in Germany and the United States concentrate procurement through utility rebate channels, compressing replacement intervals as ENERGY STAR thresholds tighten.
- Waterproof Strip:IP65-IP67 encapsulated assemblies with silicone potting or extruded housing barriers, engineered for hose-down environments and exterior exposure. Food processing facilities in USDA-inspected cold storage operations displace vapor-tight fluorescents, driven by sanitation protocols requiring pressurized washdown compatibility.
- RGB Strip:Multi-channel LED arrays with red-green-blue die mixing for dynamic color rendering.
- Smart Strip:Wireless-enabled luminaires with zone-level dimming, occupancy sensing, and BMS integration capability.
Standard strip anchors the volume base while smart strip gains share at the steepest rate.
Application:
End-use economics dictate specification grade, with commercial and industrial deployments prioritizing efficacy certifications over residential cost minimization.
- Commercial Spaces:Office, retail, and hospitality installations requiring DLC Premium qualification for utility rebate eligibility. Corporate sustainability officers in New York and London bundle lighting upgrades with carbon accounting services, shifting procurement authority from contractors to facility management platforms.
- Industrial Use:High-bay manufacturing and warehouse applications demanding lumen maintenance over 50,000+ hour operating schedules. German industrial specifications now require full SCIP database registration under REACH, adding compliance overhead that favors vertically integrated European manufacturers.
- Residential Lighting:Consumer-grade under-cabinet, cove, and accent installations.
- Event Decor:Temporary and rental staging applications with rapid deployment requirements.
Commercial spaces generate the highest specification-grade revenue per fixture while industrial use demonstrates the most price-inelastic demand for extended warranty coverage.
Technology:
Power distribution architecture determines installation labor scope and infrastructure compatibility, with PoE and wireless options collapsing traditional electrical contracting boundaries.
- AC Powered:Line-voltage 120V-277V direct connection eliminating external drivers in integrated designs. Texas and California corporate campuses specify PoE backbone networks during shell construction, virtualizing the segregation between lighting and IT infrastructure departments.
- Bluetooth Enabled:Mesh protocol implementations supporting zone-level control without dedicated control wiring. Facility engineering teams in the United States face talent scarcity commissioning these networks with legacy BACnet infrastructure, creating implementation bottlenecks.
- DC Powered:Low-voltage 12V-48V systems requiring external driver conversion.
- Wireless Control:Proprietary RF or WiFi-based command systems.
AC powered maintains installed base dominance while Bluetooth enabled climbs fastest among new specification requests.
Installation Method:
Mounting geometry shapes channel partner relationships, with recessed and track systems demanding deeper contractor coordination than surface applications.
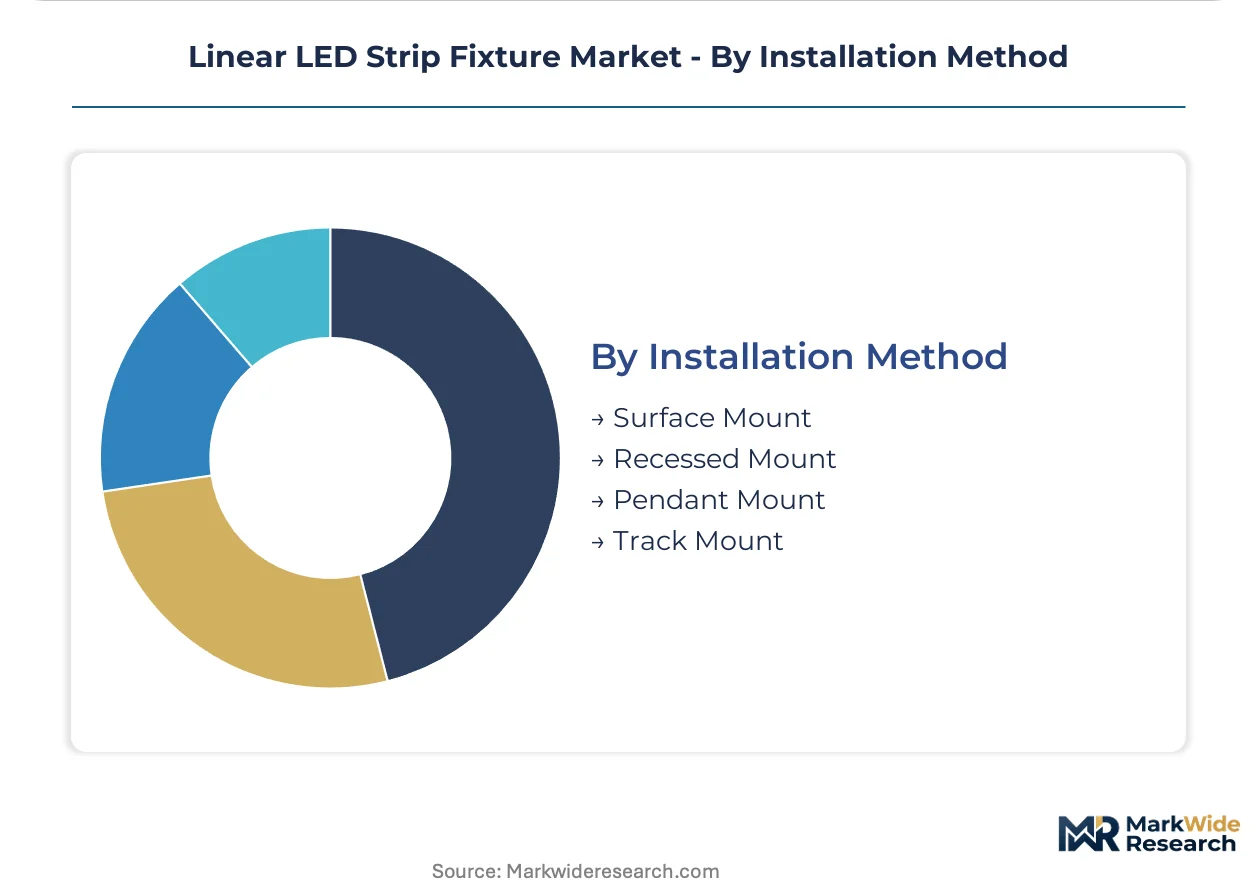
- Surface Mount:Direct adhesive or mechanical attachment to finished surfaces, lowest labor intensity. Electrical contractors retain specification influence in residential and small commercial projects where speed-to-completion outweighs aesthetic integration.
- Recessed Mount:Concealed channel integration requiring drywall or millwork modification. Design-assistance programs from specification-grade manufacturers anchor North American architectural lighting procurement through deep contractor relationships.
- Pendant Mount:Suspended cable or rod systems for task or ambient layering.
- Track Mount:Three-circuit or two-circuit adaptive rail systems for reconfigurable layouts.
Surface mount delivers the broadest channel penetration while recessed mount commands the highest project value per linear foot.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate the least price sensitivity, prioritizing connected lighting platforms and DLC Premium certification over unit cost minimization. Facility managers in India and Southeast Asia remain highly cost-conscious, driving procurement toward standard strip configurations with deferred smart upgrade investments.
United States
Corporate campus developers in Texas and California specify PoE backbone networks during shell construction, collapsing electrical and data contracting scopes. The US Department of Energy enforces ENERGY STAR and DLC qualification thresholds that filter non-compliant imports from utility rebate eligibility. New York commercial office landlords procure fixtures through performance contracts tying payment to measured energy reduction.
Germany
The EU Green Deal's building renovation wave accelerates BMS integration requirements across federal states, concentrating smart strip demand in commercial retrofits. ECHA's REACH authorization requirements tighten supply chain documentation for phosphor components, forcing fixture assemblers to audit upstream material declarations. Industrial specifications in Bavaria and North Rhine-Westphalia now mandate full SCIP database registration, adding compliance overhead.
China
Metro office construction in Shanghai and Shenzhen drives specification-grade demand as energy efficiency standards tighten in tier-one cities. MIIT oversees GB standards for lighting efficacy that reshape component sourcing for domestic manufacturers. Yangtze River Delta assemblers dominate LED driver manufacturing, creating supply concentration for North American import partners.
India
BIS energy efficiency standards are newly mandatory in Bangalore and Mumbai commercial real estate, opening specification-grade demand previously served by uncertified imports. The country's national standards body enforces efficacy thresholds that redirect procurement toward compliant domestic and multinational suppliers. Maharashtra and Karnataka industrial zones anchor retrofit program execution for manufacturing facility upgrades.
United Kingdom
London commercial landlords bundle lighting upgrades with carbon accounting services, shifting procurement authority from electrical contractors to facility management platforms. The UK's building regulations enforce minimum efficacy standards that accelerate fluorescent displacement ahead of scheduled maintenance intervals. Southeast England specification-grade projects concentrate demand for recessed mount systems in corporate headquarters renovations.
Linear LED Strip Fixture Market Competitive Landscape
Capability concentration sits with specification-grade specialists; scale advantage sits with diversified lighting conglomerates. The vendor base organizes into three tiers: multinational platform providers with connected lighting ecosystems, regional specialists with deep contractor relationships, and import-dependent distributors serving cost-sensitive segments. Dominant competitive moves include strategic partnerships for BMS interoperability and portfolio diversification into horticultural and industrial verticals.
Within the multinational platform tier, Signify and Acuity Brands exemplify divergent geographic anchoring strategies, with the former leveraging European regulatory compliance depth and the latter concentrating North American specification authority through contractor design-assistance programs. Osram occupies a position emphasizing high-efficacy module development for industrial operating environments. Hubbell Incorporated represents the diversified electrical infrastructure conglomerate archetype, while Cree Lighting sits within the LED-native specialist category.
| Leading Market Players |
|---|
| Acuity Brands |
| Philips |
| Osram |
| Cree Lighting |
| Signify |
| Zumtobel |
| American Lighting |
| Elemental LED |
| Hubbell Incorporated |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta assemblers anchor global LED driver capacity, translating semiconductor foundry constraints into tiered pricing power for North American specification-grade manufacturers.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational fixture brands and Taiwanese driver suppliers, insulating premium-tier pricing from spot-market aluminum volatility while spot purchasing concentrates among import-dependent distributors serving cost-sensitive Indian and Southeast Asian retrofit programs. Price differentiation rests on DLC Premium certification status and after-sales service bundling, with sustainability officers in New York and London demonstrating lowest sensitivity and facility managers in Mumbai remaining most price-responsive. Cost compression in standard-strip tiers intensifies as Yangtze River Delta capacity expands.
Supply Chain Analysis
Export-control scrutiny on semiconductor manufacturing equipment limits mainland China's advanced driver foundry expansion, concentrating high-efficacy component sourcing across Taiwan, South Korea, and Japan. Raw material flows draw from London Metal Exchange-priced aluminum extrusions, rare-earth phosphor compositions governed by REACH documentation, and silicone potting compounds for waterproof variants. Single-source vulnerability pervades driver procurement. Distribution runs through specification-grade manufacturer's representatives in developed markets and open-channel electronics distributors in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's platform-economics inflection centers on BMS interoperability convergence, where proprietary wireless protocols risk obsolescence against open building automation frameworks.
For Market Incumbents: Entrench specification authority by deepening design-assistance programs with North American electrical contractors and accelerating backward integration into captive LED driver production to offset Taiwan supply concentration. Bluetooth mesh firmware deprecation cycles and emerging PoE infrastructure standards represent primary technology threats requiring sustained R&D commitment. For New Entrants and Emerging Players: Mid-market commercial buildings in India's Maharashtra and Karnataka industrial zones represent the most penetrable entry point, where BIS energy efficiency mandates have newly restricted uncertified import channels without saturating local specification-grade supply. Horticultural cultivation applications in controlled-environment agriculture offer secondary white-space with converged crop-science service bundling as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical infrastructure conglomerates seeking lighting portfolio rationalization, particularly units with dormant connected-lighting software assets requiring platform integration investment. Long-term viability favors acquisition of specification-grade specialists with established SCIP database compliance and deep contractor relationships. The signal to watch is utility rebate program expansion into lighting-as-a-service ownership models.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bluetooth mesh and BACnet interoperability secures BMS specification in German federal retrofits. |
| Backward Integration | Captive LED driver production insulates margin from Taiwan supply concentration and tariff exposure. |
| Certification Investment | DLC Premium and ENERGY STAR qualification unlocks utility rebate eligibility across North American commercial real estate. |
| Geographic Expansion | India BIS compliance infrastructure captures specification-grade demand in Bangalore and Mumbai office construction. |
| Strategic Partnership | Utility-managed lighting-as-a-service agreements aggregate multi-site retrofit demand under third-party ownership. |
Research Methodology
The analysis maps standard strip, waterproof strip, and smart strip architectures, each validated through facility managers, electrical contractors, sustainability consultants, and lighting manufacturer's representatives. Primary fieldwork combined with secondary validation from ENERGY STAR qualified products database, DLC Premium certification listings, ECHA SCIP registration records, and utility rebate program documentation. Bottom-up shipment estimates and top-down construction spend allocation were triangulated to anchor volume figures.
Assumptions held fixed include continued ENERGY STAR and DLC threshold tightening, sustained utility rebate program funding, and stable BMS protocol evolution timelines; variables tested across aluminum price bands, semiconductor foundry capacity expansion, and REACH substance restriction scope. Segmentation modeling incorporated product type, application end-use, power distribution technology, and installation method dimensions. CAGRs were derived from replacement cycle compression rates in commercial retrofit programs and smart strip adoption curves.
Stress conditions across aluminum extrusion cost volatility, LED driver supply disruption, and Ecodesign Directive enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in US utility rebate program eligibility criteria or EU building renovation wave funding allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Tube Drivers Market
LED
Mexico LED Lighting Market
LED
LED Chip Market
LED
LED Modular Display Market
LED
Arrow LED Displays Market
LED
Saudi Arabia LED Lights Market
LED
Global LED Phosphor Market
LED
Mini LED Market
LED
LED Light Market
LED
United States Micro LED Market
LED
Vietnam LED Lighting Market
LED
LED Lighting Controllers Market
LED
UV-C LED Market
LED
France LED Lighting Market
LED
Infrared (IR) LED Market
LED
LED Street Light Drivers Market