
 LED Tester Market | 2026-2036
LED Tester Market Size, Share, and Industry Trends Forecast 2026-2036
LED Tester Market Outlook
Silicon photodiode arrays replacing traditional integrating sphere photometers is realigning cost structures for mid-range LED testers. Chroma ATE leverages captive semiconductor test expertise to dominate Taiwan's supply base for automotive LED validation. Keysight Technologies sustains premium positioning through precision source-measure unit integration in benchtop systems. Everfine Photo-E-Physics anchors China's domestic substitution push with state-backed R&D contracts for luminous efficacy certification.
An LED tester is an electro-optical instrument that measures luminous flux, chromaticity coordinates, forward voltage, and thermal resistance of light-emitting diode packages, modules, and luminaires using calibrated photodetectors, spectroradiometers, or source-measure units. Its primary purpose is to guarantee compliance with photometric, electrical, and thermal specifications across manufacturing, quality control, and research environments. Benchtop systems command the highest margin pools due to precision optics and software complexity, while portable units represent the fastest-growing category as field service electricians and HVAC contractors adopt handheld colorimeters for retrofit verification. The automotive application segment leads absolute volume as headlamp and interior lighting suppliers multiply test stations for adaptive driving beam certification.
China's SAMR enforces GB/T 24824 for LED module performance testing, while the EU's Ecodesign Directive through national market surveillance authorities mandates luminous efficacy thresholds that drive replacement of obsolete analog testers. The US EPA Energy Star program and NHTSA Federal Motor Vehicle Safety Standard 108 create dual compliance pathways for LED products entering North American markets. Stakeholders must monitor how IEC 62612 and IEC 62717 harmonization efforts reshape interoperability requirements for multinational manufacturing footprints.
Market Dynamics
Silicon photodiode arrays are compressing cost structures across mid-range LED tester configurations while automotive headlamp validation programs in Germany, Japan, and the United States multiply test station procurement. This technology substitution is redistributing margin pools away from traditional integrating sphere photometers toward solid-state detection architectures.
Growth Catalysts
- GB/T 24824 Enforcement:China's SAMR mandates standardized LED module performance testing, compelling domestic packaging houses to upgrade from analog to digital photometric systems.
- Adaptive Driving Beam Certification:Automotive headlamp suppliers in Stuttgart, Detroit, and Nagoya are expanding photometric test station counts to meet NHTSA Federal Motor Vehicle Safety Standard 108 and equivalent Japanese type-approval protocols.
- Shenzhen-Seoul Manufacturing Clusters:High-volume LED sorting lines in these East Asian hubs concentrate demand for high-speed luminous flux measurement equipment.
Market Restraints
- Precision Optics Input Volatility:Diffuser materials and calibrated reference standards face supply concentration among German and Japanese optical component specialists.
- Calibration Traceability Bottlenecks:National metrology institutes in limited geographies control primary luminous intensity standards, extending recertification lead times for multinational manufacturers.
- Benchtop-to-Portable Performance Gap:Handheld colorimeters remain unable to match integrating sphere accuracy for high-CRI LED validation, constraining field service adoption in premium segments.
Strategic Opportunities
- EU Ecodesign Directive Thresholds:National market surveillance authorities mandate luminous efficacy minimums that obsolete analog tester fleets, creating replacement demand across member states.
- Micro-LED Wafer-Level Testing:Emerging display manufacturing processes require sub-millimeter die photometry, opening adjacent equipment categories for spectral imaging integration.
- HVAC Contractor Channel Development:Retrofit verification workflows for solid-state lighting retrofits represent an underdeveloped distribution path for handheld verification tools.
Industry Challenges
- Spectroradiometric Calibration Expertise Scarcity:Qualified photometric engineers capable of maintaining CIE 127 compliance across multi-site manufacturing footprints command premium compensation.
- Legacy System Integration Friction:Semiconductor test equipment from prior technology generations lacks native interfaces with modern luminous flux databases, complicating MES connectivity.
- Harmonization Timeline Uncertainty:IEC 62612 and IEC 62717 convergence remains unresolved, forcing manufacturers to maintain parallel certification protocols for multinational product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Tester Market |
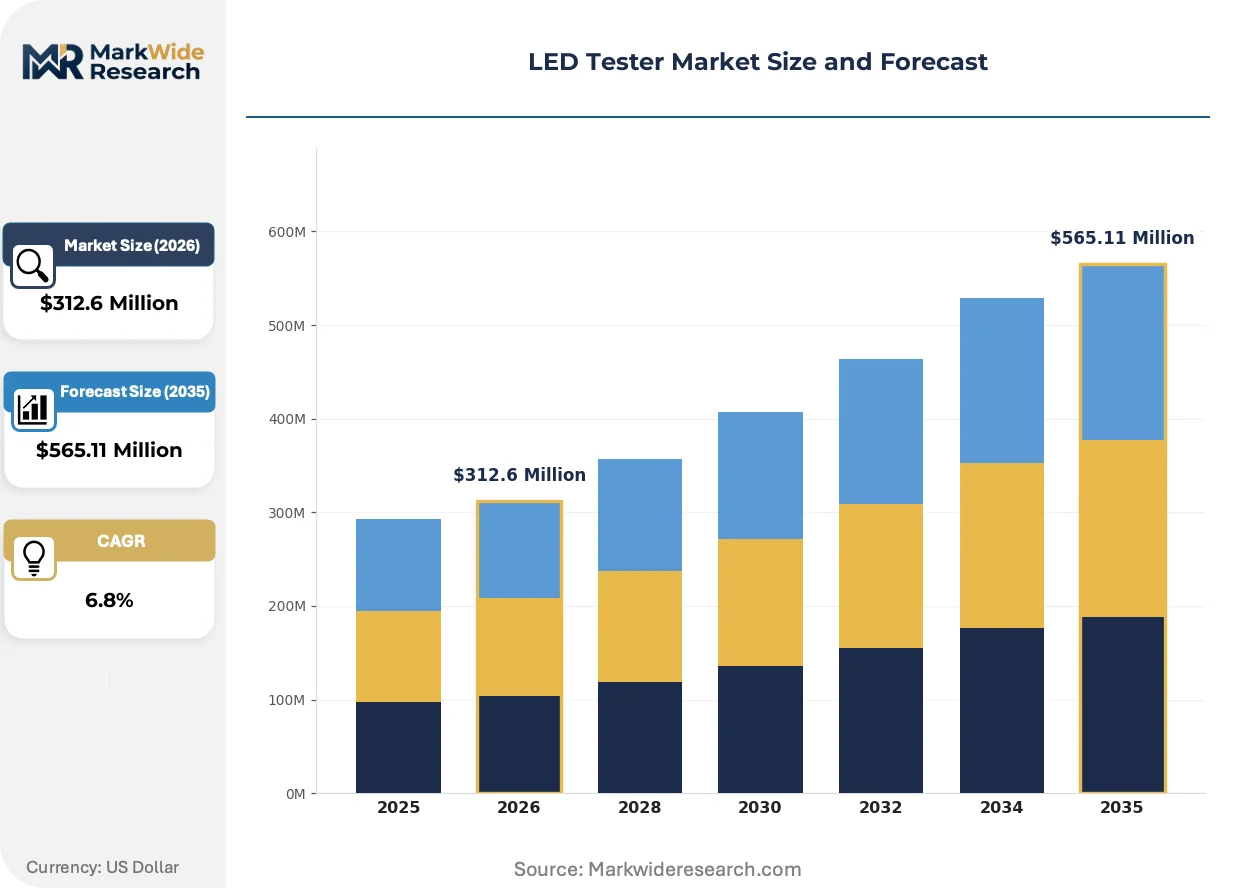
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Digital, Analog, Multifunctional, Portable Product Type: Handheld, Benchtop, Integrated, Modular Application: Industrial, Commercial, Residential, Automotive End User: Manufacturers, Electricians, Engineers, DIY Enthusiasts |
| Companies Covered | Chroma ATE, SPEA, Keysight Technologies, Instrument Systems, Konica Minolta Sensing, Everfine Photo-E-Physics, Zhuhai Bojie Electronics, Seica, Elsoft Research Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Tester Market Strategic Shifts
Photodetector architecture transitions and regulatory harmonization pressures are compressing equipment replacement cycles while reshaping competitive positioning across price tiers.
Spectrally-resolved silicon photodiode arrays are overtaking broadband filtered detectors in mid-range benchtop configurations. Automotive tier-one suppliers in Bavaria and Michigan are adopting these systems for production-line color consistency verification. The shift is enabling sub-100-millisecond measurement cycles that match high-volume LED sorting line speeds.
China's GB standards for solid-state lighting safety are tightening compliance protocols for luminous flux measurement accuracy. SAMR enforcement actions against non-conforming LED module imports are accelerating domestic substitution of foreign test equipment. Domestic packaging houses in Shenzhen and Dongguan are responding by consolidating procurement with state-backed certification laboratories.
Field service electricians are unbundling after-sales verification from original equipment manufacturer service contracts. Independent HVAC contractors in California and Texas are purchasing handheld colorimeters directly through industrial distributors rather than leasing through lighting manufacturers. This channel disintermediation is compressing margin capture for integrated lighting suppliers while expanding addressable volume for portable instrument vendors.
LED Tester Market Segmentation
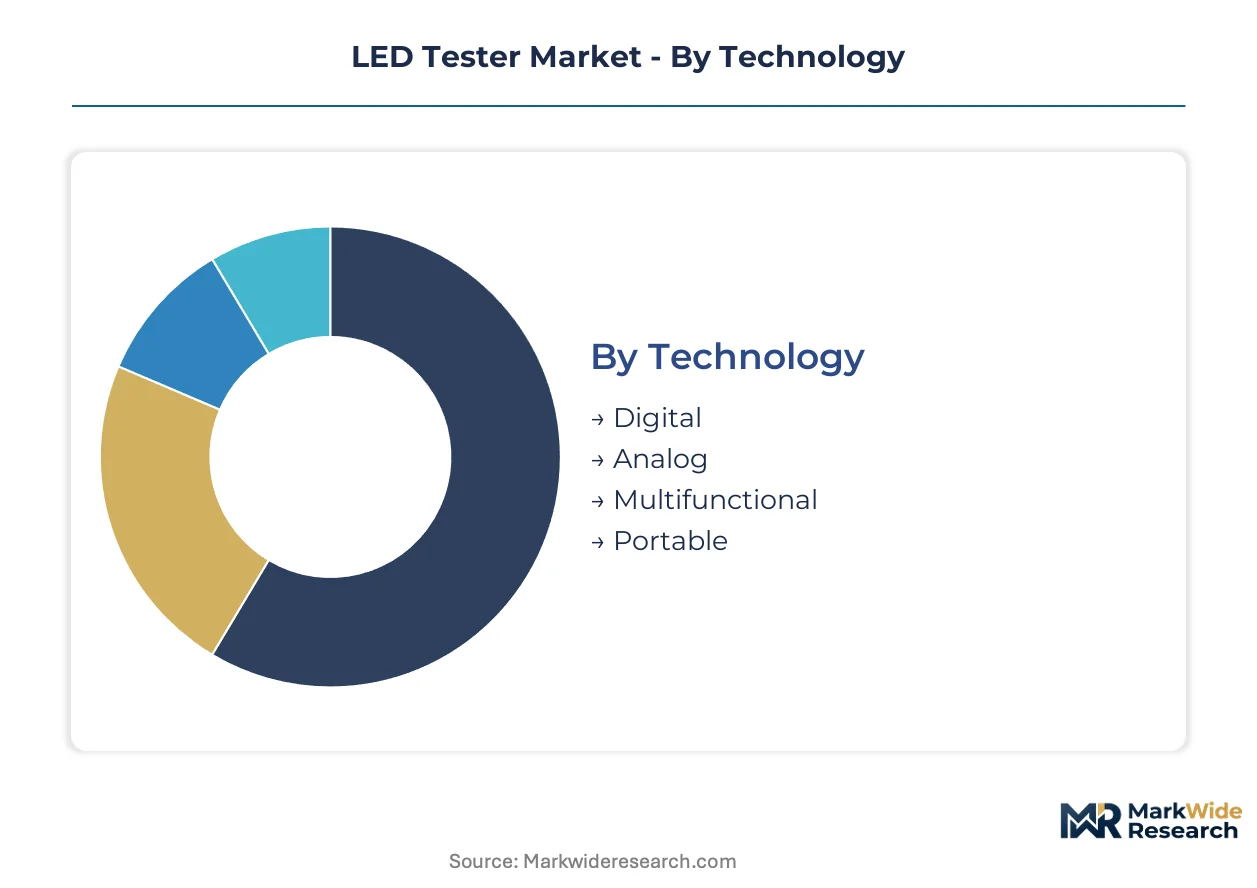
LED tester segmentation reveals divergent equipment requirements across precision certification, production-line throughput, and field verification workflows. Technology architecture and form factor choices directly determine which regulatory compliance pathways and end-user procurement budgets manufacturers can access.
Technology:
Standardization versus customization tension runs deepest here, with digital architectures enabling programmable test sequences while analog systems persist in cost-sensitive retrofit installations.
- Digital:Programmable source-measure units with calibrated photodiode arrays enable automated luminous flux logging compliant with CIE 127 protocols. Demand concentrates in Shenzhen and Seoul packaging houses where high-volume sorting lines require sub-100-millisecond measurement cycles matched to production throughput.
- Analog:Simpler potentiometer-based voltage and current measurement without spectral resolution. German automotive tier-one suppliers in Stuttgart retain limited analog fleets for legacy headlamp validation workflows where digital retrofit costs exceed replacement timelines.
- Multifunctional:Combined photometric, electrical, and thermal measurement in unified chassis configurations. Japanese type-approval laboratories favor these systems for consolidated adaptive driving beam certification.
- Portable:Battery-operated handheld units with simplified colorimetry for field verification. HVAC contractors in California and Texas are disintermediating from OEM service contracts through direct distributor procurement.
Most installed capacity flows through Digital. Expansion is steepest in Portable.
Product Type:
Margin concentration tracks physical scale, with larger-footprint systems capturing premium pricing for precision optics while compact units sacrifice accuracy for accessibility.
- Benchtop:Laboratory-grade integrating sphere photometers with calibrated spectral radiometry and thermal management chambers. Keysight Technologies and Chroma ATE dominate procurement for automotive headlamp validation programs in Michigan and Bavaria where NHTSA and KBA compliance mandates precision documentation.
- Handheld:Compact colorimeters with silicon photodiode arrays for field luminous efficacy verification. Electricians performing solid-state lighting retrofits in Texas commercial buildings drive volume through industrial distributor channels.
- Integrated:Production-line systems with conveyor interfacing and MES connectivity for real-time sorting decisions. Seoul LED packaging houses deploy these for automated binning of high-CRI emitters.
- Modular:Configurable chassis accepting interchangeable detector heads and source units. Research laboratories in Japan prefer modular architectures for protocol flexibility across IEC 62612 and IEC 62717 harmonization trials.
Revenue concentrates in Benchtop. Volume expansion is climbing fastest in Handheld.
Application:
Regulatory stringency varies sharply across use cases, with transportation safety mandates imposing stricter photometric accuracy than general illumination verification.
- Automotive:Headlamp and interior lighting validation against Federal Motor Vehicle Safety Standard 108 and equivalent Japanese type-approval protocols. Suppliers in Detroit, Stuttgart, and Nagoya multiply test station counts for adaptive driving beam certification.
- Industrial:High-bay and task lighting verification for factory floor compliance with OSHA illumination requirements. Manufacturing facilities in Ohio and Pennsylvania drive replacement demand as analog testers reach obsolescence.
- Commercial:Office and retail retrofit verification against EPA Energy Star luminous efficacy thresholds. Property managers in California prioritize handheld verification for LEED compliance documentation.
- Residential:Consumer-grade bulb testing with simplified pass-fail indication for DIY installation validation. Big-box retailer private label programs in Texas specify basic functionality screening.
Procurement volume concentrates in Automotive. Steepest expansion trajectory is appearing in Commercial.
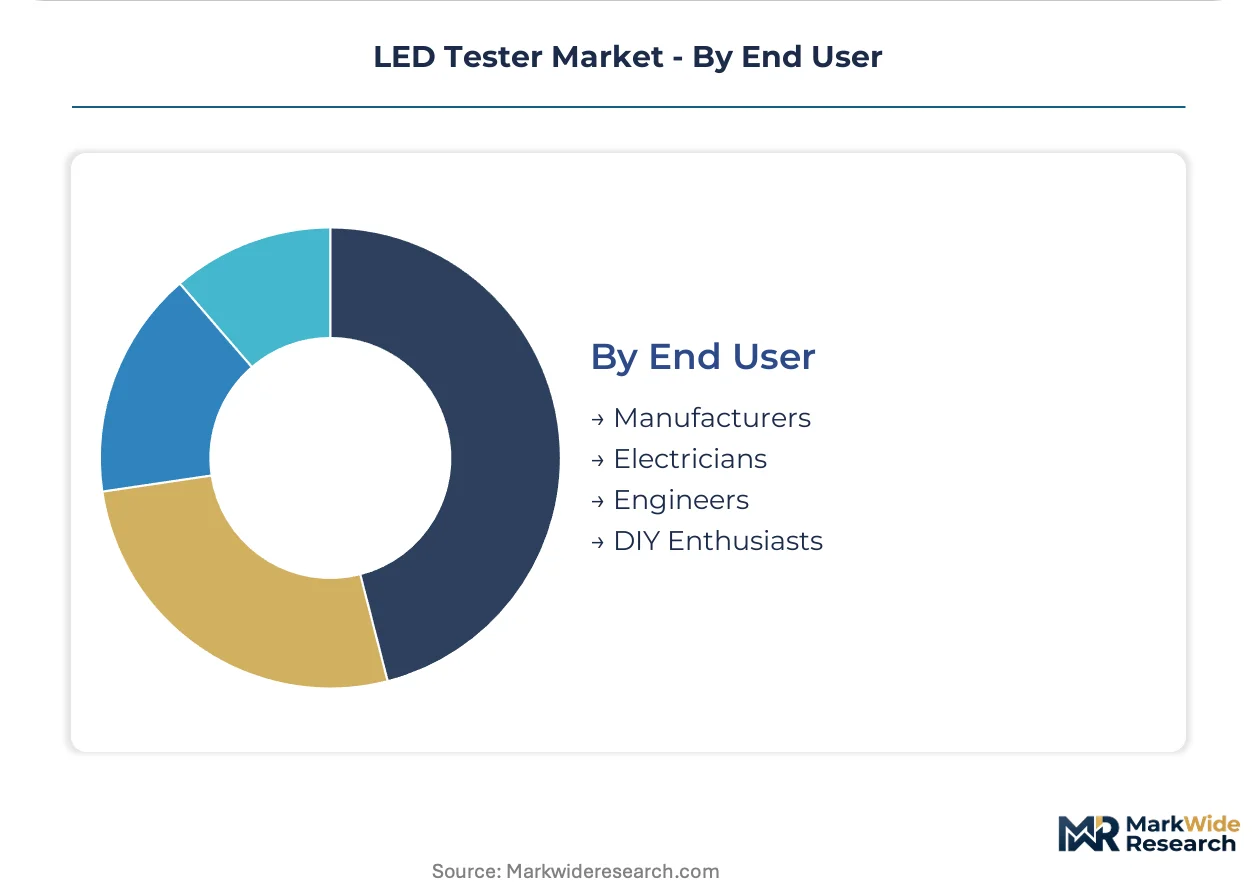
End User:
Technical sophistication and procurement authority split across organizational boundaries, with certified engineers specifying equipment that operators merely execute.
- Manufacturers:LED packaging houses and luminaire assemblers requiring production-line integration and traceable calibration chains. Shenzhen and Dongguan facilities consolidate procurement with SAMR-backed certification laboratories under GB/T 24824 enforcement.
- Engineers:Photometric engineers in R&D and quality assurance roles demanding CIE-compliant spectral analysis. These specialists command premium compensation for multi-site calibration maintenance expertise.
- Electricians:Licensed contractors performing field verification of retrofit installations. California HVAC contractors are unbundling after-sales service from original equipment manufacturer contracts.
- DIY Enthusiasts:Consumer purchasers of basic functionality testers for residential bulb verification. Limited price tolerance constrains feature sets to voltage and basic chromaticity indication.
Capital deployment concentrates with Manufacturers. Fastest share gain is appearing among Electricians.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen-Seoul manufacturing clusters concentrate the highest procurement volumes for high-speed LED sorting equipment, while automotive validation programs in Stuttgart, Detroit, and Nagoya drive precision photometric system demand across three continents.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 enforcement compels headlamp suppliers in Detroit and Michigan to expand adaptive driving beam test station counts. EPA Energy Star luminous efficacy thresholds create dual compliance pathways for LED products entering North American commercial and residential channels.
Germany
Automotive tier-one suppliers in Stuttgart and Bavaria multiply photometric validation stations for KBA type-approval protocols. The EU Ecodesign Directive through national market surveillance authorities mandates luminous efficacy minimums that obsolete analog tester fleets across member states.
China
SAMR enforcement of GB/T 24824 for LED module performance testing accelerates domestic substitution of foreign test equipment. Packaging houses in Shenzhen and Dongguan consolidate procurement with state-backed certification laboratories under tightening solid-state lighting safety protocols.
Japan
METI oversees type-approval protocols that drive headlamp and interior lighting validation demand among Nagoya and Kansai region suppliers. Japanese automotive laboratories favor multifunctional systems for consolidated adaptive driving beam certification workflows.
South Korea
High-volume LED sorting lines in Seoul manufacturing clusters concentrate demand for sub-100-millisecond luminous flux measurement equipment. Domestic packaging houses deploy integrated production-line systems with MES connectivity for automated binning of high-CRI emitters.
LED Tester Market Competitive Environment
Global majors compete with regional champions across precision certification and production-line throughput segments. Market structure shows tiered consolidation with premium benchtop systems commanding concentrated margin pools while portable and mid-range categories fragment across specialized vendors. Three archetypes dominate: semiconductor test equipment diversifiers, photometric instrumentation pure-plays, and state-backed domestic substitution champions. Competitive moves center on technology licensing for silicon photodiode array integration and geographic expansion into Shenzhen-Seoul manufacturing clusters.
Among Taiwan-based semiconductor test specialists, Chroma ATE exemplifies the captive expertise archetype leveraging integrated circuit validation heritage. Keysight Technologies occupies the premium precision tier through source-measure unit integration capabilities. Everfine Photo-E-Physics represents China's state-backed domestic substitution push with certification laboratory anchoring in Shenzhen and Dongguan industrial corridors.
| Leading Market Players |
|---|
| Chroma ATE |
| SPEA |
| Keysight Technologies |
| Instrument Systems |
| Konica Minolta Sensing |
| Everfine Photo-E-Physics |
| Zhuhai Bojie Electronics |
| Seica |
| Elsoft Research Berhad |
| Others |
Value Chain & Pricing Dynamics
Captive semiconductor test expertise anchors both supply security and pricing power for LED tester manufacturers serving automotive validation programs. Chroma ATE's backward integration into photodiode array calibration and Keysight Technologies' in-house source-measure unit production insulate premium benchtop margins against diffuser material volatility.
Pricing Analysis
Input-cost pass-through from German and Japanese optical component specialists compresses margins in mid-range configurations while silicon photodiode array substitution enables cost-down trajectories. Three-tier pricing structure across precision certification, production-line throughput, and field verification levels separates Keysight's premium benchtop systems from Chroma ATE's mid-range automotive offerings and Everfine's economy domestic substitution tier. Pricing pressure stems from SAMR enforcement accelerating domestic equipment substitution in Shenzhen packaging houses. DIY enthusiasts exhibit highest price sensitivity, constraining handheld units to basic functionality screening, while automotive tier-one suppliers in Stuttgart and Detroit demonstrate lowest sensitivity due to NHTSA compliance mandates.
Supply Chain Analysis
Reverse-logistics flows for calibrated reference standards and recertification services extend lead times from national metrology institutes in Germany, Japan, and the United States. Manufacturing concentration centers on Taiwan, China, and South Korea for photodiode array fabrication and system integration. Raw material dependencies encompass diffuser materials from German optical specialists, silicon wafers from Taiwanese foundries, and precision machined housings from Japanese metalwork suppliers. Single-source vulnerability in primary luminous intensity standards creates calibration traceability bottlenecks for multinational manufacturers. Distribution runs through state-backed certification laboratories in Shenzhen and Dongguan, industrial distributors serving California HVAC contractors, and direct OEM procurement channels for automotive validation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photodiode array cost-down curves and premium-tier shift toward adaptive driving beam certification create margin expansion headroom for positioned players. Automotive validation complexity and field service channel disintermediation reward capability depth over scale.
For Market Incumbents: Deepen captive calibration expertise to defend against state-backed domestic substitution in China. Invest in multifunctional system architectures for Japanese type-approval consolidation. Expand MES connectivity capabilities to lock in Seoul LED packaging house procurement. Certification investment in GB/T 24824 traceability anchors replacement demand cycles. For New Entrants and Emerging Players: Capture HVAC contractor channel development in California and Texas through industrial distributor partnerships. Target portable verification workflows where field service electricians unbundle from OEM service contracts. Pursue micro-LED wafer-level testing adjacent equipment as display manufacturing scales. Direct-to-contractor go-to-market bypasses integrated lighting supplier margin capture. For Investors and Strategic Acquirers: Roll-up economics work for photometric instrumentation pure-plays because calibration traceability expertise concentrates in limited geographies and commands premium compensation. Long-term viability hinges on spectral imaging integration for emerging display applications. Acquisition target archetype: regional champions with SAMR laboratory anchoring in Shenzhen-Dongguan corridor. Monitor IEC 62612 and IEC 62717 harmonization timeline for protocol consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photodiode Array Integration | Chroma ATE leverages semiconductor heritage to compress mid-range cost structures against traditional integrating spheres. |
| State-Backed Laboratory Anchoring | Everfine consolidates procurement with SAMR certification corridors under GB/T 24824 enforcement acceleration. |
| Adaptive Driving Beam Certification Investment | Keysight sustains premium positioning through NHTSA Federal Motor Vehicle Safety Standard 108 compliance depth. |
| HVAC Contractor Channel Development | Portable vendors capture field verification volume as California electricians disintermediate from OEM service contracts. |
| MES Connectivity Platform Expansion | Integrated system suppliers lock in Seoul packaging house automated binning workflows for high-CRI emitters. |
Study Parameters
Direct dialogue with photometric engineers, automotive tier-one supplier quality directors, LED packaging house procurement leads, and state-backed certification laboratory managers grounded qualitative findings. Secondary validation drew from SAMR enforcement disclosures, NHTSA Federal Motor Vehicle Safety Standard 108 compliance documentation, IEC standard harmonization committee records, and SEC filings from semiconductor test equipment providers. Bottom-up and top-down triangulation cross-checked equipment procurement volumes against regulatory mandate timelines.
Bottom-up modeling aggregated segment-level demand from automotive headlamp validation programs, industrial facility retrofit cycles, and field service contractor adoption curves across the projection horizon. Top-down analysis calibrated aggregate market scale against semiconductor test equipment industry benchmarks and photometric instrumentation trade flows. Segmentation dimensions encompassed technology architecture, product form factor, application regulatory stringency, and end-user technical sophistication. CAGRs derived from equipment replacement cycle compression rates and regulatory enforcement phase-in schedules.
Tariff exposure on German optical components, calibration traceability bottlenecks at national metrology institutes, and IEC standard harmonization delays are the dominant revision risks. Forecasts reflect documented assumptions on enforcement timelines and technology substitution rates. Practitioners should monitor SAMR import inspection data, METI type-approval queue lengths, and KBA market surveillance action reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Europe Indoor LED Lighting Market
LED
Monochrome Outdoor LED Display Market
LED
Vietnam LED Lighting Market
LED
LED Light Market
LED
UK Indoor LED Lighting Market
LED
North America LED Packaging Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
South America LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Egypt LED Lighting Market
LED
LED Tube Drivers Market
LED
India Indoor LED Lighting Market
LED
Programmable LED Drivers Market
LED
Pixel Pitch LED Market
LED
Asia Pacific LED Lighting Market
LED
Thailand LED Market