
 Outdoor LED Display Market | 2026-2036
Outdoor LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor LED Display Market Analysis
Market Context
Micro-LED and fine-pitch surface mount technology is rewriting the engineering economics of large-format outdoor visualization, compressing pixel gaps while extending luminance durability. Daktronics leverages its captive North American manufacturing network to dominate stadium and highway billboard installations. Unilumin Group anchors its competitive position through deep backward integration into LED chip packaging and driver IC design.
Technical Definition and Segment Structure
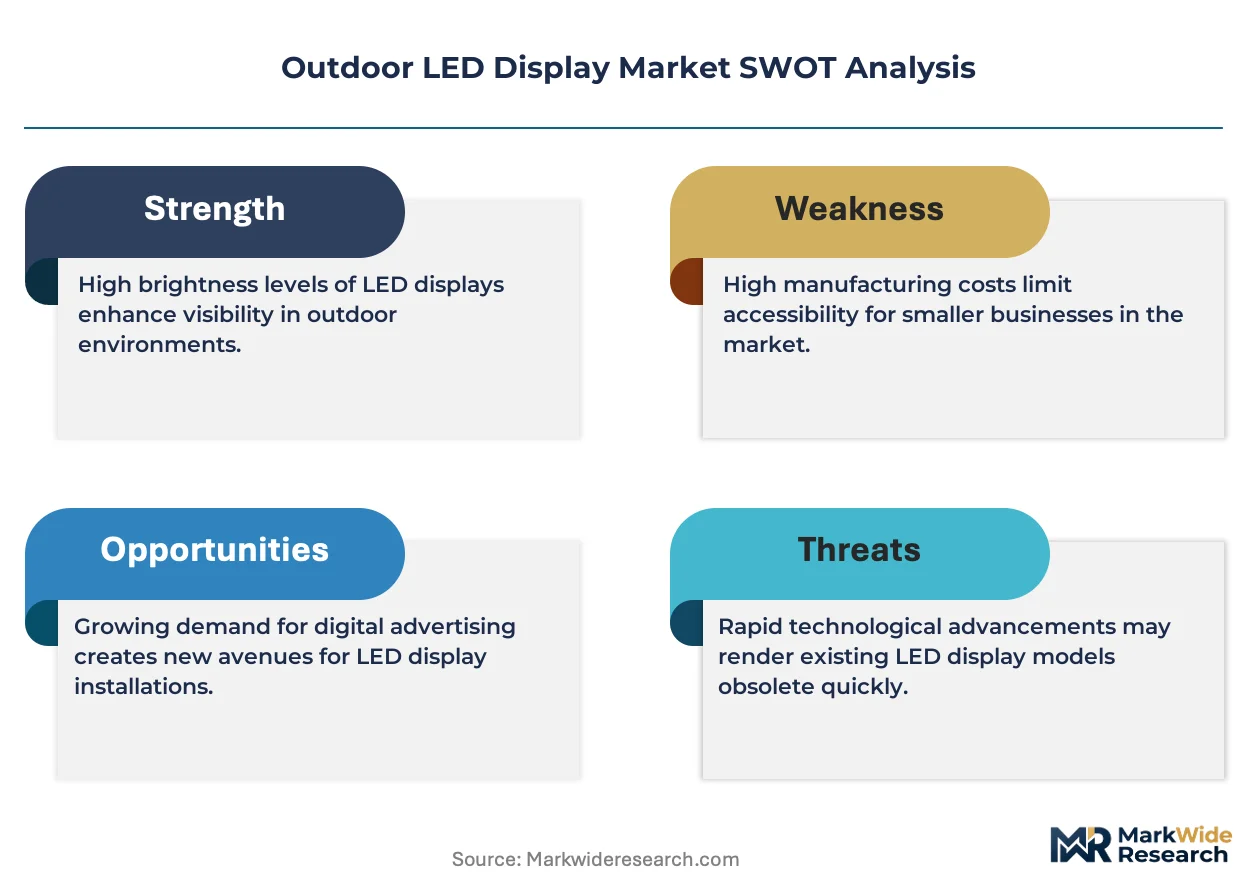
An outdoor LED display is a modular electronic screen engineered with IP65-rated enclosures, aluminum or steel cabinet frames, and high-brightness SMD or DIP LEDs exceeding 5000 nits, designed for continuous operation in rain, dust, and direct solar load. Billboards and digital signage together occupy the largest revenue share, with video walls representing the fastest-expanding category as retail and command-center applications migrate from indoor to weather-hardened formats. Scoreboards retain stable replacement demand across municipal and collegiate sports infrastructure, while transparent LED technology is carving out a niche in architectural facade advertising where sightline preservation matters.
Regulatory Framework and Outlook
FCC emission standards and UL 48 safety certifications govern product entry into the United States, while the EU RoHS directive and CE marking constrain hazardous substance profiles and electromagnetic compatibility across European deployments. China's GB standards and MIIT catalog requirements impose additional efficiency and reliability testing for domestic and export-bound manufacturers. Stakeholders must monitor evolving municipal zoning codes for digital signage brightness and operating hours, as these local ordinances increasingly determine site-level project viability and return-on-investment calculations.
Market Dynamics
Micro-LED die shrinkage and fine-pitch surface mount packaging are compressing pixel densities below 2mm while extending operational lifespans, fundamentally altering capital deployment patterns for large-format outdoor visualization infrastructure.
Growth Catalysts
- Smart city infrastructure mandates:India's Ministry of Housing and Urban Affairs is channeling funds into municipal digital signage networks, accelerating LED billboard procurement across tier-1 and tier-2 cities.
- Energy-efficiency directives:China's MIIT catalog requirements for display electronics are tightening compliance thresholds, forcing technology upgrades that favor high-efficiency SMD modules over legacy DIP architectures.
- Stadium modernization cycles:Collegiate and professional sports venues across the United States are replacing aging scoreboard systems with integrated LED video systems capable of real-time content synchronization.
Market Restraints
- Driver IC supply concentration:Taiwan and South Korea dominate integrated circuit fabrication for LED display controllers, creating vulnerability to regional disruption.
- Aluminum cabinet cost volatility:Raw material price swings for extruded enclosure components compress margin predictability for systems integrators.
- Municipal zoning friction:Local ordinances in jurisdictions including Los Angeles, London, and Mumbai impose brightness caps and operating-hour restrictions that constrain site-level revenue models.
Strategic Opportunities
- Transparent LED architectural integration:Building-integrated media facades in Dubai, Singapore, and Shanghai are creating demand for see-through display systems that preserve interior sightlines.
- Highway digital signage retrofit programs:Federal infrastructure allocations in the United States are funding variable message sign replacements along interstate corridors.
- Convergence of 5G broadcast and real-time content:Low-latency cellular networks are enabling dynamic ad insertion and traffic-responsive messaging on roadside billboards.
Industry Challenges
- IP65 certification timeline compression:Accelerated project schedules strain testing protocols for enclosure sealing and thermal management validation.
- Legacy control system integration:Municipal transit authorities require backward compatibility with existing content management platforms, complicating hardware refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor LED Display Market |
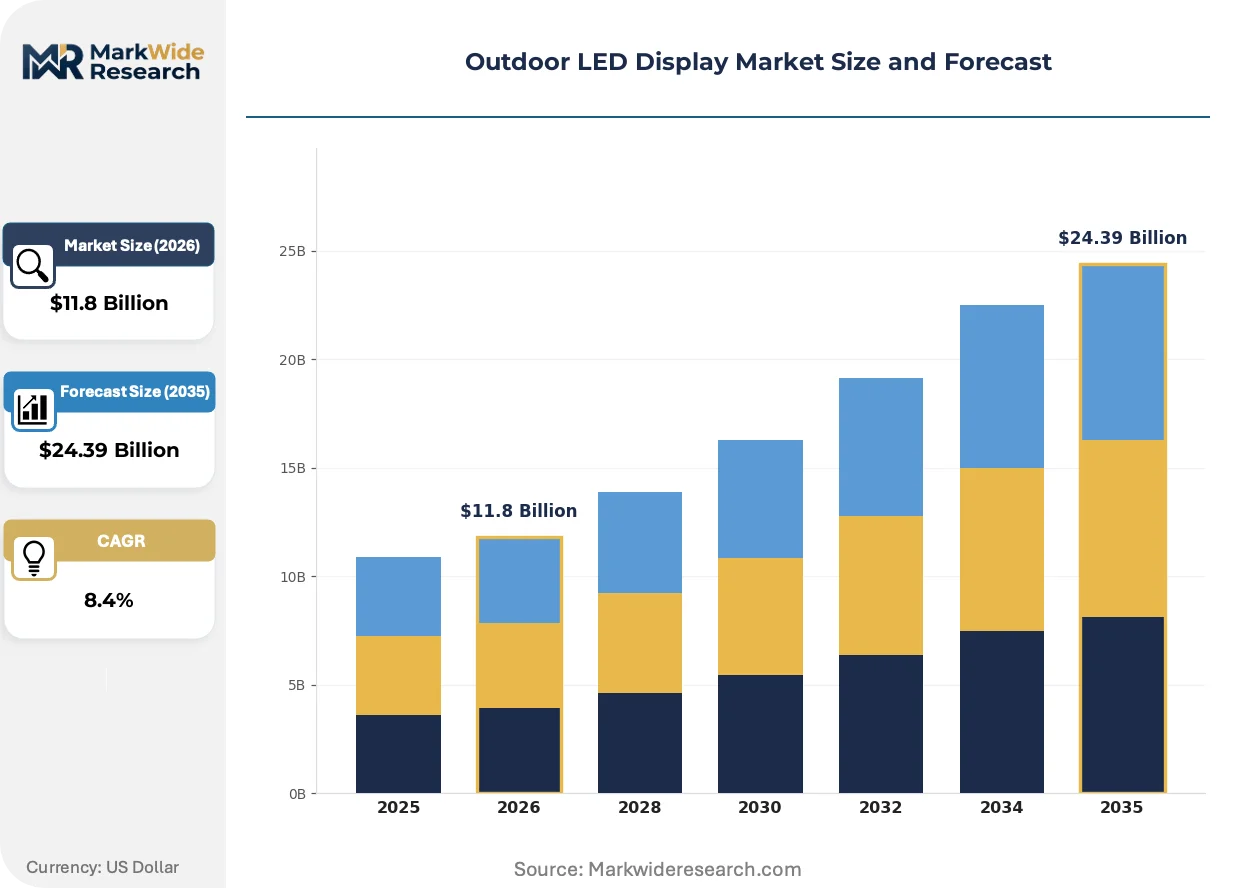
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Billboards, Video Walls, Digital Signage, Scoreboards Technology: Surface Mount, Edge-Lit, Transparent, Flexible End User: Advertising Agencies, Retail Outlets, Sports Venues, Traffic Management Installation Type: Fixed, Mobile, In-House, Outdoor Events |
| Companies Covered | Daktronics, Unilumin Group, Leyard, Absen, Samsung Electronics, LG Electronics, Barco, INFiLED, LianTronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor LED Display Market Emerging Trajectories
Active matrix driving schemes and chip-on-board architectures are redefining thermal management and power efficiency benchmarks for outdoor-rated display systems.
Chip-on-board LED technology eliminates traditional SMD packaging by mounting bare dies directly onto substrate boards, reducing thermal resistance paths. Large-format billboard operators in the United States and Germany are piloting these modules for 24/7 highway deployments. The elimination of intermediate packaging layers is virtualizing the traditional cost structure of high-brightness outdoor systems.
China's GB standards for electronic display energy efficiency are mandating standby power thresholds and luminous efficacy minimums that exceed prior certification requirements. Domestic manufacturers must retest product lines under accelerated thermal cycling protocols to maintain MIIT catalog listing. Outdoor advertising network operators in Beijing and Shenzhen are prioritizing compliant suppliers to secure municipal procurement contracts.
Content-as-a-service models are displacing capital purchase structures for digital billboard networks. Media companies in Brazil and South Africa are leasing display hardware with bundled creative and scheduling platforms, transferring technology obsolescence risk to integrators. This arrangement concentrates buyer power among national out-of-home advertising conglomerates while fragmenting vendor relationships.
Outdoor LED Display Market Segmentation
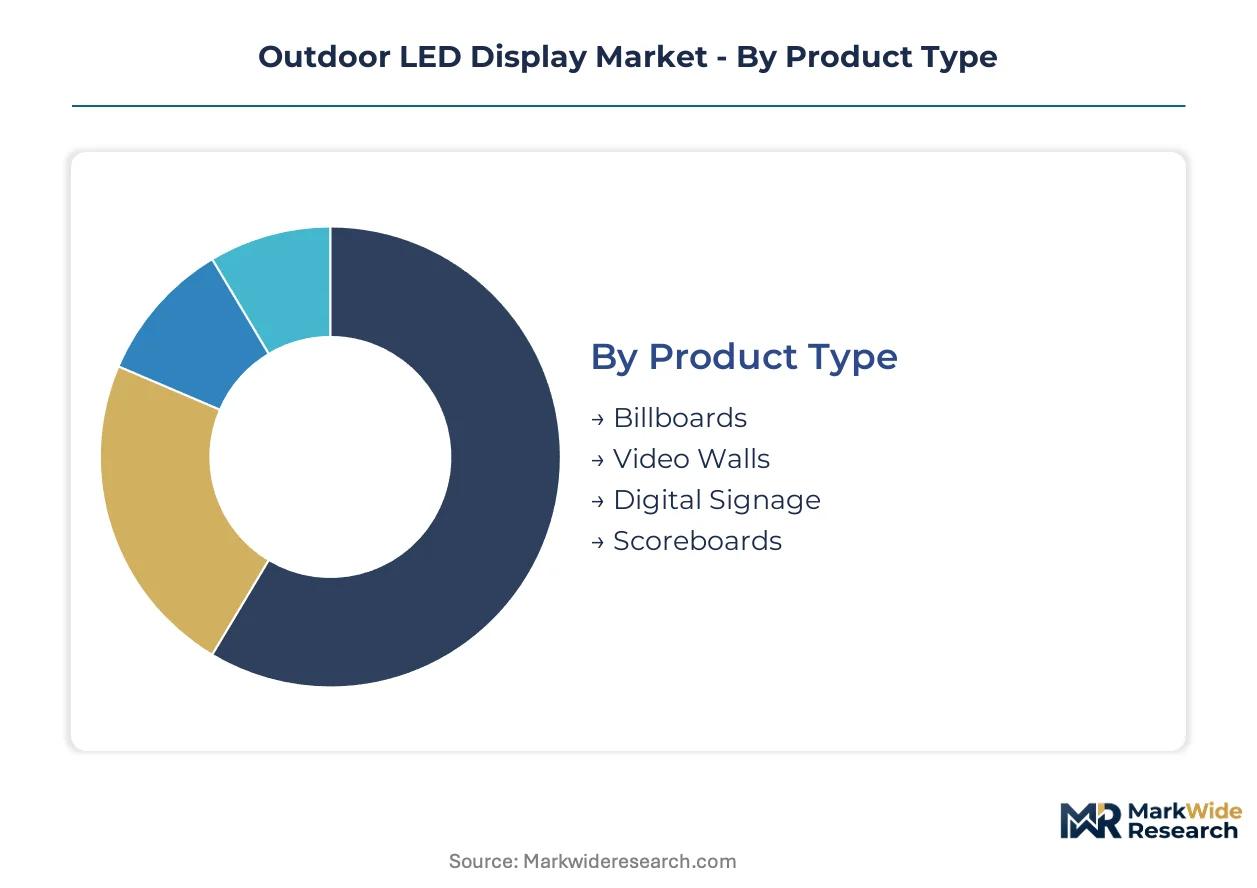
Outdoor LED display procurement patterns diverge sharply across technical specifications, deployment contexts, and ownership models. Understanding these dimensional splits reveals where margin pools concentrate and which technology transitions are accelerating replacement cycles.
Product Type:
Application context determines cabinet engineering priorities, pixel density requirements, and content management complexity across the four product categories.
- Billboards:Large-format roadside installations engineered for 5000+ nits luminance and 100-meter-plus viewing distances. Demand concentrates in India's smart city corridors and U.S. interstate highway programs where municipal authorities specify IP65-rated enclosures and remote diagnostics capability.
- Video Walls:Modular arrays of fine-pitch panels enabling seamless large-scale visualization. Sports venues in Germany and retail flagship stores in Dubai are driving specification shifts toward sub-2mm pixel pitch and 90-degree corner continuity.
- Digital Signage:Networked displays for transit hubs, shopping districts, and corporate campuses. Transit authorities in London and São Paulo prioritize daylight readability and cellular backhaul integration.
- Scoreboards:Purpose-built athletic venue systems with integrated timing, statistics, and instant replay. Collegiate athletic conferences in the United States are consolidating procurement through shared-service agreements.
Billboards hold installed capacity. Video walls are rotating up the share rankings.
Technology:
Packaging architecture and substrate engineering define thermal performance, manufacturing cost curves, and suitability for curved or transparent deployments.
- Surface Mount:Dominant LED packaging using soldered SMD components on PCB substrates. Chinese MIIT energy-efficiency catalog requirements are accelerating migration from DIP to SMD modules for domestic and export-bound production.
- Edge-Lit:Side-mounted LED arrays with light-guide plates for slim-profile applications. Airport concourses in Singapore and hotel lobbies in Paris specify these for aesthetic integration with interior architecture.
- Transparent:See-through LED matrices mounted on glass or acrylic substrates. Building-integrated media facades in Shanghai and Dubai are creating specification demand for 70%+ transparency ratios.
- Flexible:Polymer-substrate displays conforming to curved surfaces. Concert touring productions and temporary event installations in Brazil favor these for rapid deployment and non-planar mounting.
Surface mount commands production volume. Transparent technology is climbing the fastest.
End User:
Buyer sophistication, content refresh frequency, and total cost of ownership calculations vary substantially across ownership models and operational contexts.
- Advertising Agencies:National out-of-home media companies managing network-scale deployments. Operators in South Africa and Mexico are shifting toward hardware-as-a-service contracts to transfer obsolescence risk.
- Retail Outlets:Brand-direct installations for flagship stores and shopping mall concourses. Luxury retailers in Milan and Tokyo specify seamless bezel-less arrays for immersive brand storytelling.
- Sports Venues:Professional and collegiate athletic facilities requiring integrated scoring, replay, and sponsorship content systems. Stadium modernization bonds in Texas and Ohio are funding replacement cycles.
- Traffic Management:Municipal and state departments of transportation deploying variable message signs. Federal infrastructure allocations in the United States are accelerating interstate corridor retrofits.
Advertising agencies hold legacy network scale. Sports venues are rotating up the share rankings.
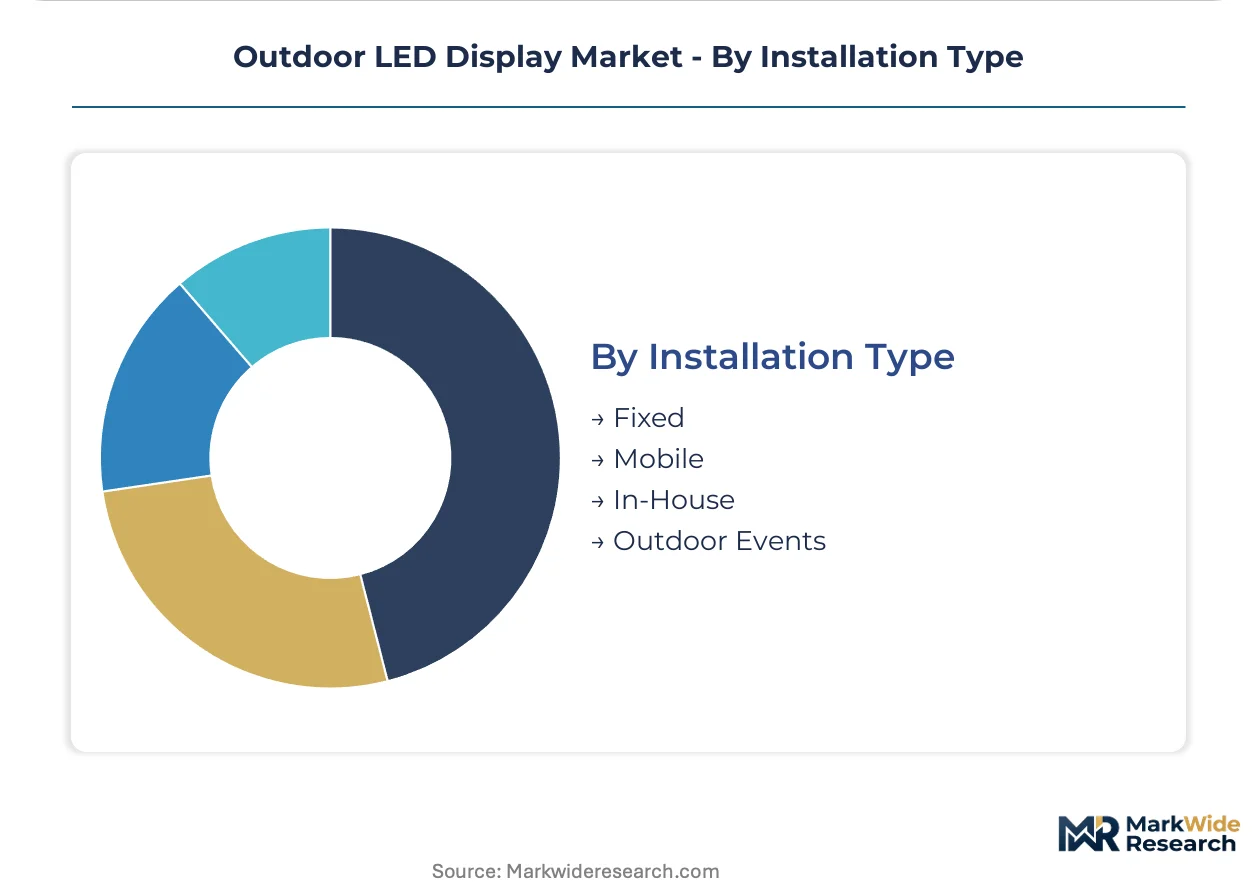
Installation Type:
Mobility requirements and ownership duration dictate structural engineering, power distribution, and content management architecture.
- Fixed:Permanent structural mounting on buildings, poles, or dedicated foundations. Highway billboards in Germany and rooftop installations in Mumbai require wind-load engineering for 20-year service life.
- Mobile:Trailer-mounted or vehicle-integrated displays for temporary deployment. Political campaigns in Brazil and festival promoters in the United Kingdom lease these for 30-90 day activations.
- In-House:Corporate and institutional installations on owned premises. Technology campuses in Bangalore and automotive headquarters in Stuttgart specify these for employee communication and visitor experience.
- Outdoor Events:Temporary staging for concerts, sporting events, and public gatherings. Rental houses in Los Angeles and Sydney maintain inventory pools for 48-hour deployment cycles.
Fixed installations hold structural permanence. Mobile deployments are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertising networks and municipal infrastructure buyers concentrate procurement authority in distinct geographic clusters where regulatory frameworks and smart city mandates shape deployment velocity.
United States
Federal highway infrastructure allocations and collegiate sports venue modernization bonds drive fixed-installation demand. FCC emission standards and UL 48 safety certifications govern product entry, while state DOTs specify IP65-rated variable message signs. Texas and Ohio stadium districts concentrate replacement cycles for integrated LED video systems.
China
MIIT energy-efficiency catalog requirements and GB standards for electronic displays accelerate technology upgrades across domestic manufacturing. Shenzhen and Beijing advertising network operators prioritize compliant suppliers for municipal procurement contracts. Guangdong Province anchors backward integration into LED chip packaging and driver IC design.
Germany
EU RoHS directive and CE marking requirements constrain hazardous substance profiles for European deployments. Autobahn digital signage retrofit programs and sports venue fine-pitch video wall specifications concentrate demand. Bavaria and North Rhine-Westphalia host manufacturing clusters for aluminum cabinet engineering and thermal management systems.
India
Ministry of Housing and Urban Affairs smart city mandates channel funds into municipal digital signage networks across tier-1 and tier-2 cities. BIS certification requirements and state-level urban infrastructure programs accelerate LED billboard procurement. Maharashtra and Karnataka concentrate transit authority deployments with cellular backhaul integration requirements.
United Arab Emirates
Building-integrated media facade specifications in Dubai and Abu Dhabi create demand for transparent LED systems with 70%+ transparency ratios. MOHAP and municipal zoning authorities regulate brightness caps for architectural advertising installations. Dubai Design District and Saadiyat Island concentrate premium retail and hospitality visualization deployments.
Outdoor LED Display Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by captive manufacturing depth and geographic coverage breadth. The structure consolidates around scale-driven systems integrators with captive North American or Chinese production networks, alongside modular specialists focused on fine-pitch architectural applications. Three archetypes dominate: vertically integrated display manufacturers with in-house LED chip capabilities, stadium-focused integrators with captive installation infrastructure, and transparent-display specialists serving building-facade advertising. Competitive moves concentrate on manufacturing capacity expansion in Southeast Asia and strategic technology licensing for chip-on-board thermal architectures.
Within the integrated-manufacturer tier, Daktronics and Unilumin Group exemplify divergent geographic anchoring strategies. Daktronics represents the captive North American production archetype with stadium and highway billboard installation dominance. Unilumin Group occupies the Shenzhen-based backward-integration position with LED chip packaging and driver IC design capabilities. Leyard sits within the fine-pitch video wall specialist tier, serving retail flagship and command-center applications migrating to weather-hardened formats.
| Leading Market Players |
|---|
| Daktronics |
| Unilumin Group |
| Leyard |
| Absen |
| Samsung Electronics |
| LG Electronics |
| Barco |
| INFiLED |
| LianTronics |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Guangdong Province LED chip packaging facilities is compressing module pricing while forcing integrators toward longer-term offtake contracts. This utilization dynamic simultaneously erodes spot-market margins and rewards buyers with procurement scale.
Pricing Analysis
Cost-plus contracts with aluminum LME indexation dominate large-format billboard procurement. Pricing stratifies across premium, standard, and economy tiers based on pixel density grades and UL 48 certification status. Cost compression in standard-tier SMD modules is intensifying because Chinese MIIT energy-efficiency retesting is disqualifying legacy architectures. Municipal transit authorities exhibit highest price sensitivity; luxury retail flagships show lowest.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Foxconn, Jabil, and local Shenzhen EMS providers serving module assembly. Supply chains draw from China, Taiwan, and South Korea for LED epitaxy and driver IC fabrication. Aluminum extrusion and copper PCB substrate dependencies create exposure to commodity volatility. Single-source vulnerability in Taiwan-sourced driver ICs threatens continuity. Distribution runs through systems integrators with captive installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national out-of-home advertising conglomerates consolidating network-scale procurement. This consolidation fragments vendor relationships and compresses supplier margins.
For Market Incumbents: Build captive thermal-management IP moats through chip-on-board architecture patents. Defensive moves center on backward integration into LED chip packaging and capacity addition in Vietnam to circumvent tariff exposure. Threat: Transparent LED specialists with architectural facade relationships. Lever: Certification investment in China's evolving MIIT catalog requirements. For New Entrants and Emerging Players: India's tier-2 smart city corridors represent the most penetrable geography. White-space targets include municipal digital signage networks with cellular backhaul requirements and highway variable message sign retrofits. Go-to-market angle: Hardware-as-a-service contracts transferring obsolescence risk from municipal buyers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fine-pitch video wall sub-segments. Long-term viability favors acquisition targets with in-house driver IC design capabilities and established MIIT catalog listings. Signal to watch: Municipal zoning code liberalization in Mumbai, Los Angeles, and London as inflection indicator for site-level revenue model expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Chip-on-Board Thermal Architecture Licensing | Patent licensing from Unilumin and Daktronics accelerates module efficiency gains for highway deployments. |
| Southeast Asia Manufacturing Expansion | Vietnam and Thailand capacity buildout reduces tariff exposure for North American billboard installations. |
| Transparent LED Architectural Partnership | Collaboration with Dubai and Shanghai developers secures premium media facade specifications. |
| 5G-Enabled Dynamic Content Platform | Low-latency cellular integration enables real-time ad insertion for roadside advertising networks. |
| MIIT Energy-Efficiency Certification Investment | Accelerated retesting protocols maintain catalog listing access for China's municipal procurement. |
Methodological Framework
Desk research of customs trade data, FCC equipment authorization filings, and MIIT catalog databases preceded structured interviews with LED display procurement managers, municipal transit authority engineers, stadium facility directors, and out-of-home advertising network operators. Primary intelligence combined with secondary validation through SEC 10-K disclosures, aluminum price indices, and smart city tender databases. Bottom-up module shipment estimates triangulated against top-down advertising network capex surveys.
Assumptions held fixed include China's MIIT efficiency directive enforcement trajectory and U.S. federal highway infrastructure allocation continuity; variables tested included municipal zoning liberalization scenarios and driver IC supply disruption durations. Segmentation modeled across product type, technology architecture, end-user ownership model, and installation mobility. CAGRs derived from curve-fitting historical replacement cycles against projected smart city procurement acceleration. Industry-specific inputs incorporated LED chip die-shrinkage roadmaps and aluminum extrusion cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by transparent LED specialists or sudden driver IC supply consolidation would shift outcomes. Specific risks include municipal zoning code tightening in European heritage districts and China's dual carbon goals accelerating manufacturing compliance costs. Quarterly review of MIIT catalog update frequency and municipal tender award volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Monochrome Outdoor LED Display Market
LED
India Indoor LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Bi-Color LED Ring Light Market
LED
North America Indoor LED Lighting Market
LED
LED Phosphor Materials Market
LED
China LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
Middle East LED Lighting Market
LED
Europe Indoor LED Lighting Market
LED
Programmable LED Drivers Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Philippines LED Market
LED
Architectural LED Products Market