
 Global Medium Voltage Electric Drives Market | 2026-2036
Global Medium Voltage Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medium Voltage Electric Drives Market Foresight
A shift from single-source procurement to multi-source qualification is recalibrating how OEMs and EPC firms contract medium voltage drive suppliers. ABB sustains technology leadership through in-house IGBT module production. Siemens dominates European infrastructure retrofits with integrated automation portfolios. WEG anchors Latin American supply chains through regional manufacturing footprints.
Global medium voltage electric drives are power conversion systems operating between 1 kV and 35 kV that modulate motor speed and torque through variable frequency output, primarily serving energy-intensive industries seeking process optimization and demand-side energy management. AC drives occupy the largest installed base across pump control and compressor operation applications due to proven reliability in harsh environments. IGBT technology leads power semiconductor configurations while resonant converter architectures are gaining traction in high-power density installations where switching losses constrain thermal budgets.
EU Ecodesign regulations and IEC 61800-4 efficiency standards are mandating minimum performance thresholds that filter lower-tier suppliers from European project tenders. China's GB standards and NMPA certification requirements are shaping product localization strategies for multinational vendors. India's BIS efficiency labeling and CEA grid codes are accelerating domestic manufacturing investments. Stakeholders must monitor how regional certification divergence affects platform standardization decisions and service network economics.
Market Dynamics
IGBT module sourcing concentration among Asian foundries is compressing supplier margins while accelerating in-house semiconductor fabrication investments among tier-one drive manufacturers seeking supply security.
Growth Catalysts
- Water treatment infrastructure:Municipal desalination and wastewater facilities in Saudi Arabia and Australia are specifying medium voltage drives for energy recovery in reverse osmosis trains. IEC 61800-4 compliance mandates are filtering non-compliant vendors from European tenders.
- Semiconductor packaging advances:Silicon carbide integration is reducing switching losses in high-power density installations. Mining operations in Chile and Peru are retrofitting conveyor systems with resonant converter architectures.
- India's PLI scheme:Production-linked incentives for electrical equipment manufacturing are attracting multinational assembly investments. Domestic BIS certification requirements are accelerating localized supply chain development.
Market Restraints
- Copper and rare earth price volatility:Magnet material costs in permanent motor-drive systems fluctuate with Chinese export quotas. Procurement hedging consumes working capital at mid-tier manufacturers.
- Foundry concentration risk:IGBT wafer production clusters in Taiwan and South Korea create single-point vulnerability. Geopolitical friction threatens delivery timelines for European and North American OEMs.
- Technical limitation in retrofit compatibility:Legacy motor insulation systems degrade under PWM voltage stress. Replacement costs for stator rewinding deter full-system upgrades in aged industrial facilities.
Strategic Opportunities
- Underpenetrated Vietnamese market:Textile and electronics manufacturing clusters around Ho Chi Minh City lack qualified drive service networks. First-mover technical support investments capture long-term maintenance contracts.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms incentivize energy-intensive exporters to adopt demand-side management. Steel and cement producers face mounting pressure to document efficiency improvements.
- Technology convergence:Digital twin integration with variable frequency drives enables predictive maintenance algorithms. Oil and gas operators in the North Sea are piloting combined hardware-software offerings.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized firmware development for resonant control algorithms exceeds graduate pipeline output. German and Japanese manufacturers compete for the same limited specialist pool.
- Certification timeline compression:China's NMPA and India's BIS are implementing parallel but non-harmonized testing protocols. Platform standardization decisions fragment as regional requirements diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medium Voltage Electric Drives Market |
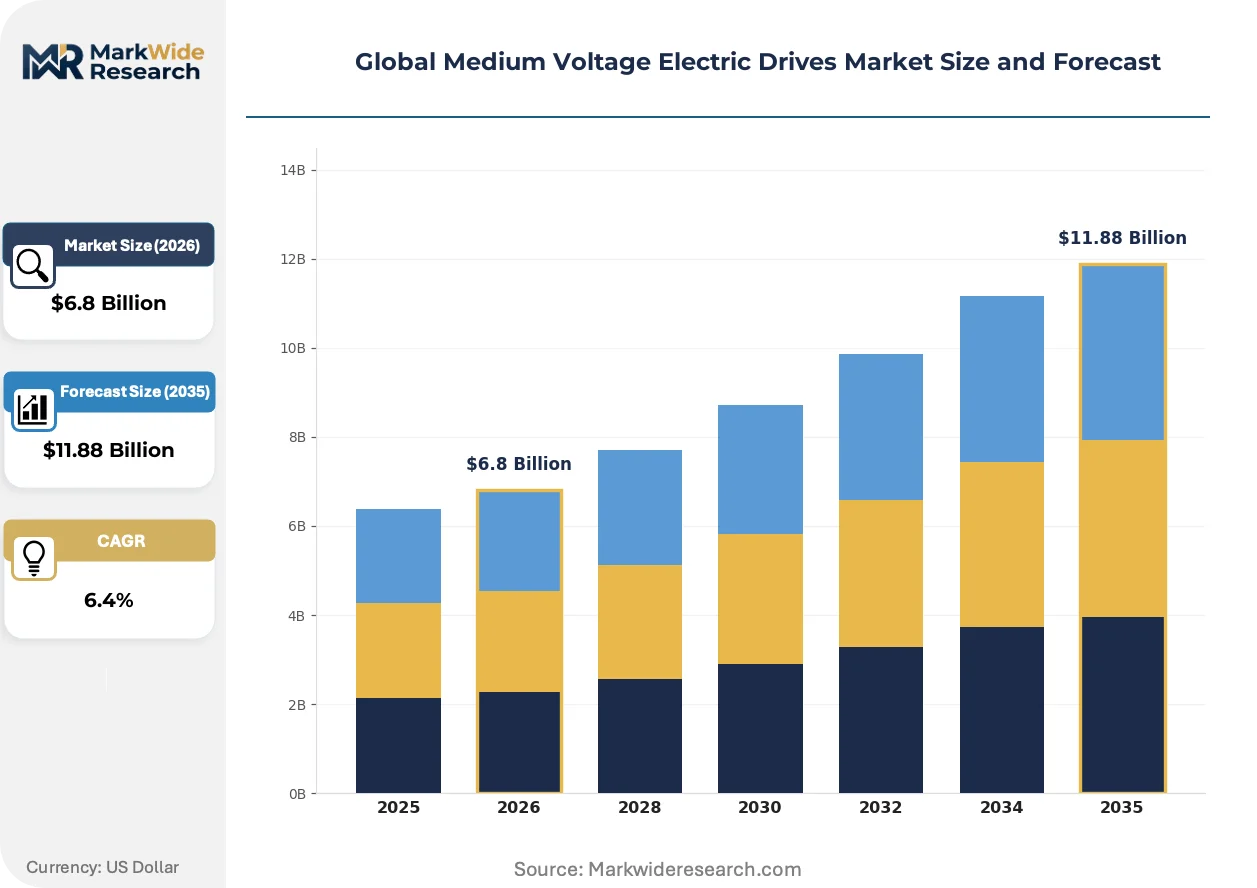
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drive Type: AC Drives, DC Drives, Servo Drives, Vector Drives, Direct Torque Control Technology: IGBT, MOSFET, SCR, Cycloconverter, Resonant Converter Application: Pump Control, Compressor Operation, Conveyor Systems, Fans Operation, Material Handling End User Industry: Power Generation, Mining & Extraction, Chemical Processing, Water Treatment, Waste Management |
| Companies Covered | Eaton, WEG, ABB, Rockwell Automation, Danfoss, Siemens, Mitsubishi Electric, Yaskawa Electric, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medium Voltage Electric Drives Market Shifts & Advancements
Power semiconductor architectures and control software are converging to enable smaller footprints and higher switching frequencies, compressing the physical envelope of medium voltage installations while expanding their functional scope.
Resonant converter topologies are modularizing drive system design. These architectures eliminate DC-link capacitors and enable direct medium voltage output without output transformers. Offshore wind turbine manufacturers in Denmark and Germany are specifying modular power cells for nacelle-mounted applications. The technology is modularizing how OEMs configure scalable drive platforms across varying power ratings.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas use in drive cooling systems. Manufacturers are engineering air-cooled and dielectric fluid alternatives for high-thermal-load installations. Water treatment and mining applications in Spain and Poland face accelerated retrofit timelines as refrigerant-dependent designs lose regulatory approval.
Asset-as-a-service contracting is displacing traditional capital purchase models in energy-intensive process industries. Chemical producers in the US Gulf Coast and Rotterdam harbor are leasing drive capacity with guaranteed uptime clauses. This shift transfers operational risk to vendors while locking in long-term maintenance revenue streams.
Global Medium Voltage Electric Drives Market Segmentation
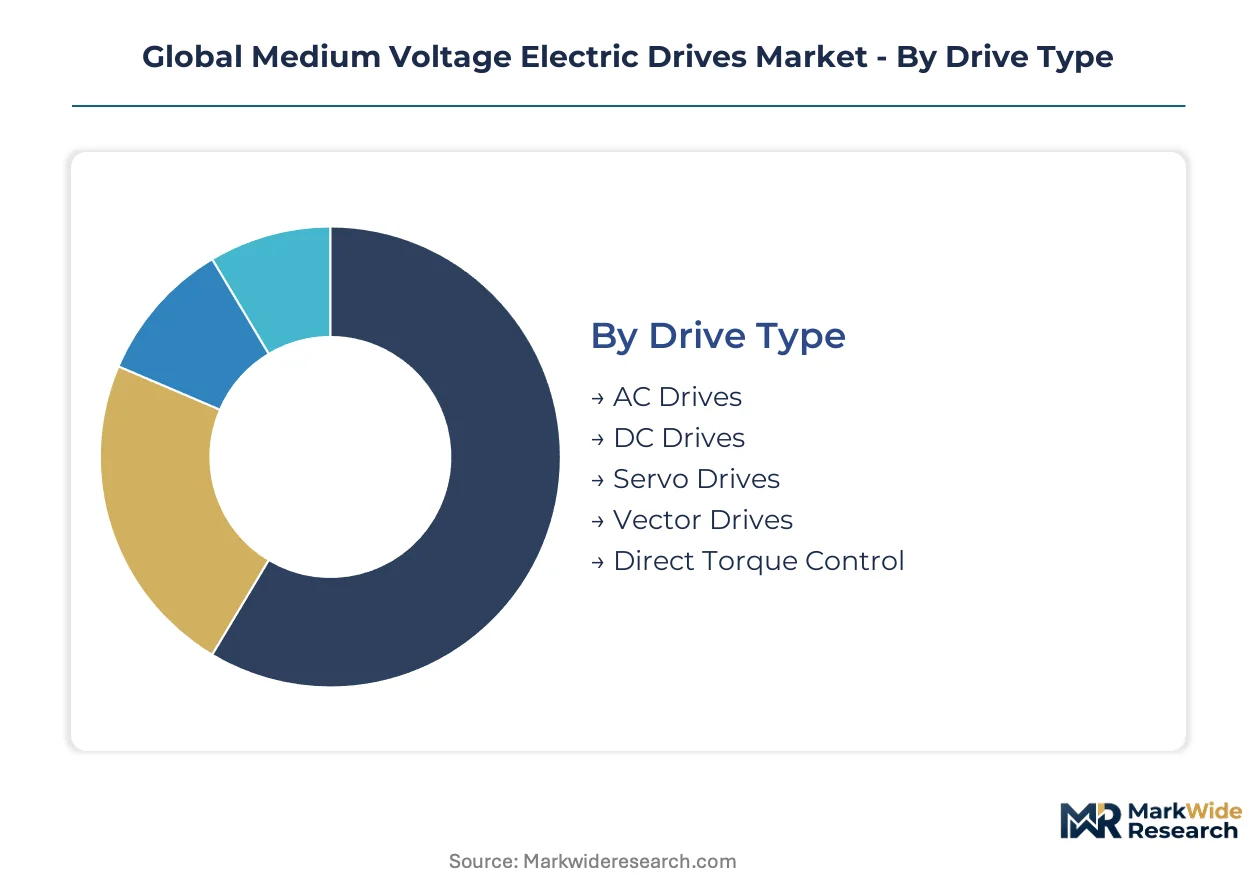
Medium voltage drive procurement varies sharply by operational intensity and process criticality. Capital allocation patterns differ between continuous-process industries and batch-oriented facilities. Technology selection directly determines maintenance schedules, energy recovery potential, and compatibility with legacy motor infrastructure.
Drive Type:
Capital intensity peaks with vector control architectures requiring precision feedback systems and specialized commissioning expertise.
- AC Drives:Variable frequency units modulate induction motor speed through pulse-width modulation. Demand concentrates in Saudi Arabian desalination plants where reverse osmosis trains require precise flow control under IEC 61800-4 mandates.
- Direct Torque Control:Sensorless torque regulation eliminates encoder dependencies in harsh environments. Mining conveyors in Chile specify these units for dust-resistant operation without mechanical feedback components.
- DC Drives:Ward Leonard legacy systems persist in aging steel mill installations.
- Servo Drives:High-dynamic-response units serve precision positioning in automated material handling.
- Vector Drives:Field-oriented control enables full torque at zero speed for crane and hoist applications.
Most installed capacity flows through AC Drives. Expansion is steepest in Direct Torque Control.
Technology:
Semiconductor switching losses and thermal management requirements create tiered cost structures across power electronic architectures.
- IGBT:Insulated gate bipolar transistors dominate medium voltage ratings through proven ruggedness and mature driver ecosystems. German offshore wind nacelle manufacturers specify modular IGBT power cells for scalable platform architectures.
- Resonant Converter:Soft-switching topologies eliminate DC-link capacitors and enable transformerless medium voltage output. Polish water treatment facilities adopt these for compact footprint compliance with EU F-Gas phase-down schedules.
- MOSFET:Metal-oxide-semiconductor field-effect transistors serve lower voltage medium drive derivatives.
- SCR:Silicon-controlled rectifiers persist in cycloconverter retrofits for high-horsepower cement mills.
- Cycloconverter:Direct frequency conversion without DC link finds niche use in ultra-high-power grinding mills.
IGBT configurations anchor current procurement volumes. Resonant architectures are climbing the fastest as thermal density constraints tighten.
Application:
Process duty cycles and load torque profiles determine drive specification complexity and spare parts stocking requirements.
- Pump Control:Centrifugal and positive displacement pump modulation dominates energy recovery applications. Australian wastewater facilities specify medium voltage drives for variable flow management in membrane bioreactor trains.
- Compressor Operation:Dynamic torque control matches reciprocating and centrifugal compressor load curves. Chemical processing clusters around Rotterdam Harbor deploy these for demand-side energy management under carbon border adjustment pressure.
- Conveyor Systems:Long-distance bulk material transport requires coordinated multi-drive control.
- Fans Operation:Draft and ventilation systems in power plants specify drives for combustion optimization.
- Material Handling:Crane and stacker systems demand precise speed-torque coordination.
Pump Control absorbs the largest share of current installations. Compressor Operation is gaining share fastest on process efficiency mandates.
End User Industry:
Regulatory exposure and energy cost intensity create divergent procurement sophistication across industrial verticals.
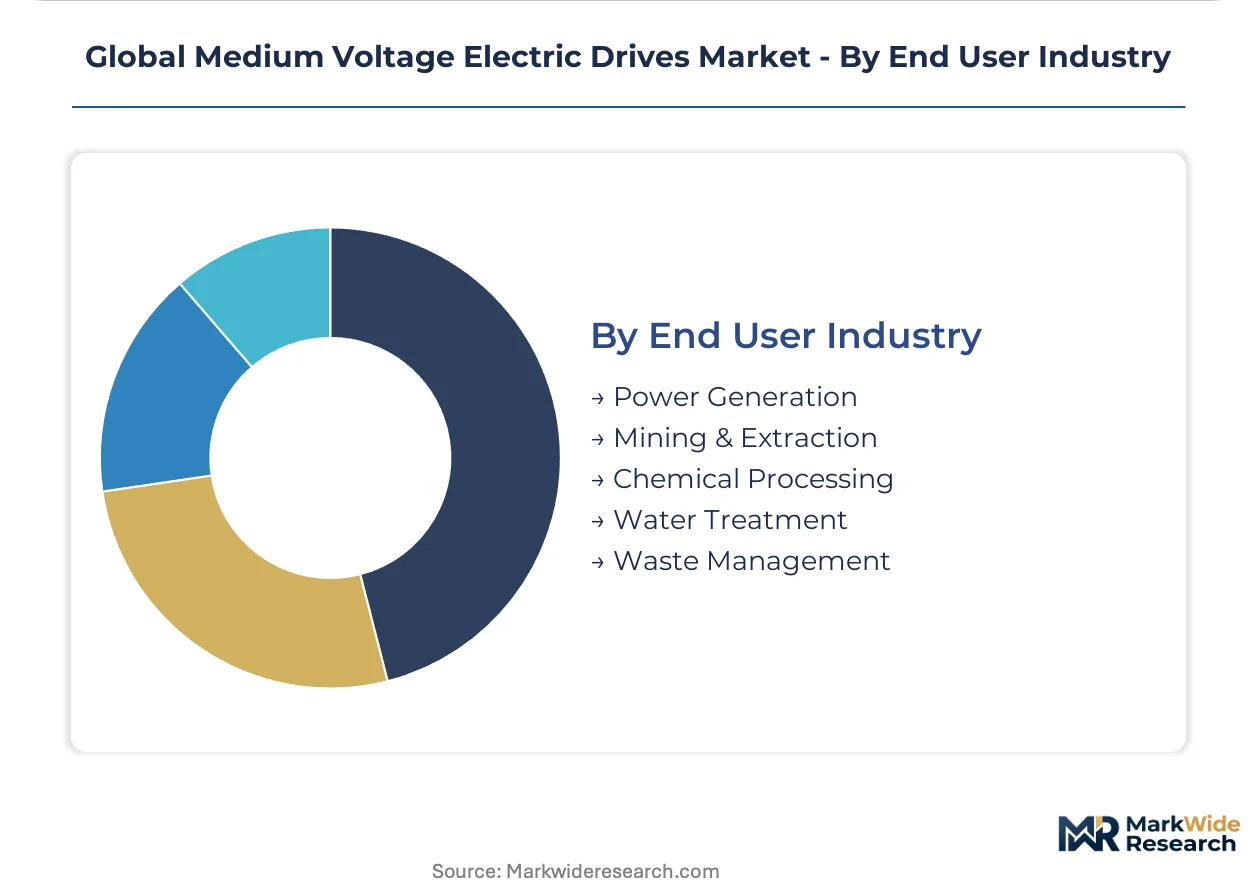
- Water Treatment:Municipal and industrial desalination, wastewater, and distribution systems specify drives for energy recovery. Saudi Arabian megaprojects mandate IEC-compliant medium voltage drives for reverse osmosis energy recovery turbines.
- Mining & Extraction:Conveyor, grinding, and ventilation systems in surface and underground operations require ruggedized enclosures. Peruvian copper belt operations retrofit resonant converters for altitude-derated thermal performance.
- Power Generation:Boiler feed pumps and induced draft fans in thermal plants drive replacement demand.
- Chemical Processing:Continuous process industries specify drives for reactor agitation and compression duty.
- Waste Management:Incineration and anaerobic digestion facilities adopt drives for fan and pump modulation.
Water Treatment commands the deepest installed base. Mining & Extraction shows the steepest expansion trajectory on electrification of extraction operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters anchor procurement sophistication for medium voltage electric drives, with demand radiating across water treatment retrofits, offshore wind nacelle integration, and chemical process optimization.
Germany
Offshore wind turbine manufacturers in northern coastal zones specify modular medium voltage drives for nacelle-mounted power conversion. EU F-Gas Regulation phase-down schedules accelerate adoption of air-cooled and dielectric fluid alternatives. Chemical processing complexes around Ludwigshafen and Leverkusen deploy asset-as-a-service contracts with guaranteed uptime clauses.
China
GB standards and NMPA certification requirements shape product localization strategies for multinational drive vendors. Dual carbon goals under MIIT directives pressure steel and cement producers toward demand-side energy management. Yangtze River Delta manufacturing clusters concentrate domestic assembly investments attracted by production-linked incentive structures.
India
BIS efficiency labeling and CEA grid codes accelerate localized supply chain development for electrical equipment manufacturing. PLI scheme disbursements attract multinational assembly footprints to Gujarat and Maharashtra industrial corridors. Desalination projects in Tamil Nadu specify IEC-compliant drives for reverse osmosis energy recovery.
Saudi Arabia
Municipal desalination megaprojects mandate medium voltage drives for energy recovery turbine integration in reverse osmosis trains. SFDA-equivalent industrial equipment standards filter non-compliant vendors from infrastructure tenders. Jubail Industrial City water treatment facilities specify drives under efficiency mandates tied to Vision 2030 diversification targets.
United States
Chemical producers in the US Gulf Coast region lease drive capacity through outcome-based contracting with guaranteed uptime provisions. EPA efficiency guidelines and FERC demand-side management incentives shape procurement specifications. Rotterdam-comparable Houston Ship Channel petrochemical clusters pilot digital twin integration with variable frequency drives.
Global Medium Voltage Electric Drives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue resonant converter architectures and silicon carbide integration. The vendor base stratifies across three tiers: integrated automation conglomerates with captive semiconductor fabrication, regional specialists with localized service networks, and technology-focused innovators modularizing power cell designs. Competitive positioning hinges on in-house IGBT module production versus foundry-dependent sourcing strategies. Market participants defend margin positions through backward integration into power semiconductor supply and forward integration into predictive maintenance software.
Among diversified electrical equipment conglomerates, Eaton, ABB, and Siemens exemplify archetypes spanning integrated automation portfolios, in-house semiconductor fabrication, and European infrastructure retrofit dominance. These entities occupy positions where technology leadership converges with multi-source qualification requirements from OEM and EPC procurement committees. Regional manufacturing footprint specialists such as WEG anchor Latin American supply chains through localized production and service infrastructure. Japanese electrical equipment manufacturers including Mitsubishi Electric and Yaskawa Electric sit within precision control technology tiers, while Schneider Electric and Rockwell Automation represent automation-integrated positioning. Danfoss occupies a specialist position in thermal management and energy efficiency optimization.
| Leading Market Players |
|---|
| Eaton |
| WEG |
| ABB |
| Rockwell Automation |
| Danfoss |
| Siemens |
| Mitsubishi Electric |
| Yaskawa Electric |
| Schneider Electric |
| Others |
Supply & Pricing Matrix
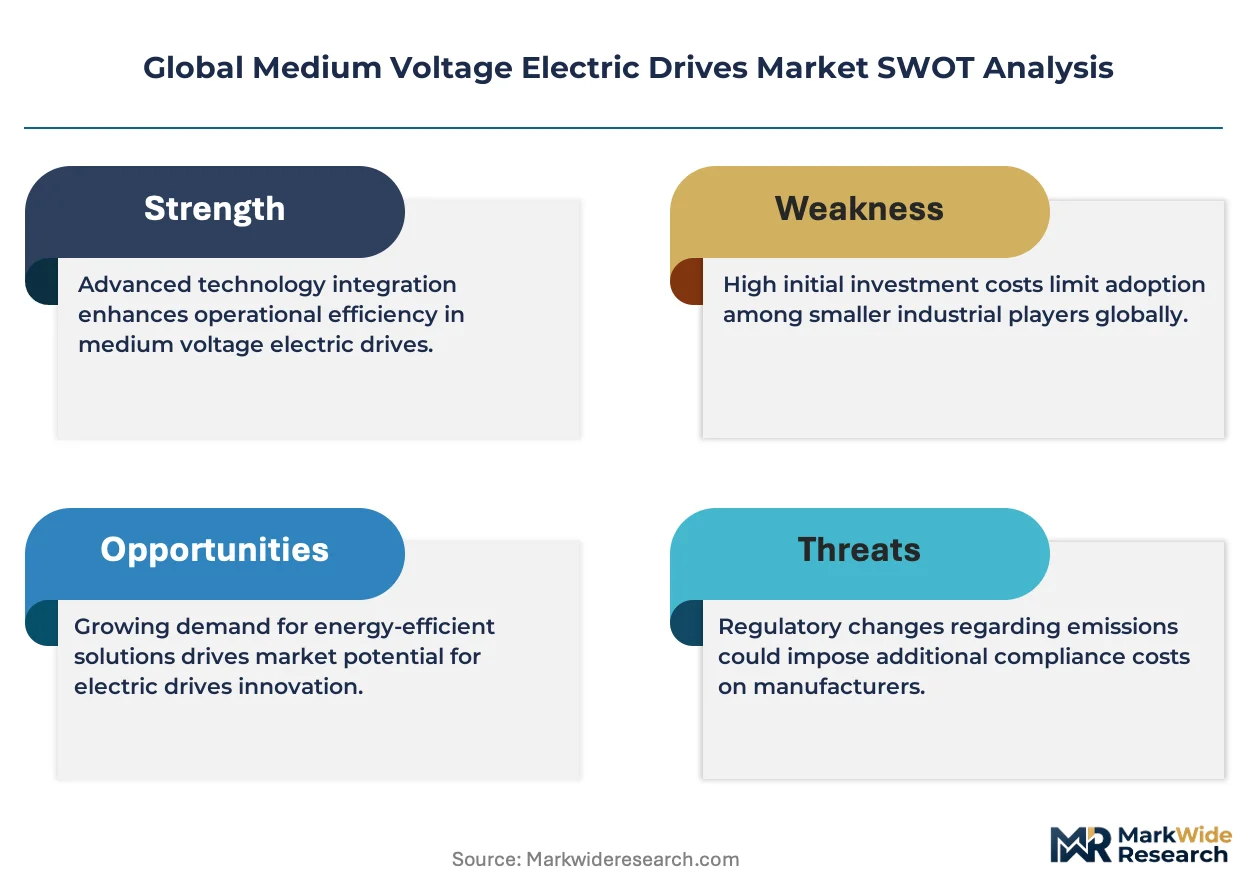
Captive IGBT module fabrication anchors both supply security and pricing power for tier-one manufacturers, insulating them from foundry margin compression while forcing foundry-dependent competitors into cost pass-through dilemmas. This integration choice separates vendors who command premium positioning from those locked in transactional bidding wars.
Pricing Analysis
Copper and rare earth magnet cost pass-through dominates pricing dynamics for permanent motor-drive systems, with Chinese export quota volatility forcing mid-tier manufacturers into procurement hedging that consumes working capital. Pricing stratifies across IEC 61800-4 certified premium tiers, BIS-compliant standard tiers, and non-certified economy tiers. Cost compression in the standard tier is intensifying because Asian foundry concentration squeezes IGBT module margins. Municipal EPC firms in water treatment show highest price sensitivity; offshore wind OEMs demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Regional distribution centers in Germany, China, and India anchor hub-and-spoke fulfillment patterns for drive system components. Manufacturing concentration clusters in Taiwan and South Korea for IGBT wafer fabrication, Germany for precision mechanical assemblies, and China for magnetic materials and enclosures. Raw material dependencies draw from copper windings, silicon carbide substrates, and rare earth permanent magnets. Single-source vulnerability in Taiwanese foundry capacity threatens delivery timelines for European and North American OEMs. Distribution runs through authorized service networks with localized commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide integration and resonant converter architectures are expanding margin capture in premium thermal-density applications, rewarding early movers with pricing power as efficiency mandates tighten.
For Market Incumbents: Deploy in-house semiconductor fabrication to secure IGBT supply against foundry concentration risk. ABB's captive module production exemplifies this defensive posture. Accelerate air-cooled and dielectric fluid cooling investments ahead of EU F-Gas Regulation phase-down deadlines. Resonant converter specialists threaten premium positioning in Polish and Spanish water treatment retrofits. For New Entrants and Emerging Players: Vietnamese textile and electronics manufacturing clusters around Ho Chi Minh City represent an underserved buyer archetype lacking qualified drive service networks. First-mover technical support investments capture long-term maintenance contracts. Target resonant converter architectures for compact footprint compliance in EU F-Gas restricted installations. Partner with local EPC firms for commissioning credibility. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with localized BIS or NMPA certification capabilities because fragmented aftermarket networks struggle to meet tightening compliance timelines. Mid-cap targets with captive semiconductor packaging expertise offer the strongest long-term viability through the projection horizon. Monitor IGBT foundry utilization rates as an inflection indicator for supply-constraint pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into IGBT Fabrication | Captive wafer production insulates ABB and Siemens from Taiwanese foundry bottlenecks and margin compression. |
| Resonant Converter Platform Launch | Eliminating DC-link capacitors enables Polish water treatment facilities to meet EU F-Gas footprint restrictions. |
| Air-Cooled Thermal System Development | Dielectric fluid alternatives capture retrofit demand as refrigerant-dependent designs lose regulatory approval in Spain. |
| Asset-as-a-Service Contracting | US Gulf Coast chemical producers lease drive capacity with guaranteed uptime clauses, locking maintenance revenue streams. |
| Vietnamese Service Network Expansion | Localized technical support captures long-term contracts from Ho Chi Minh City textile manufacturing clusters. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, EPC contractors, and aftermarket service heads grounded qualitative findings in operational realities across water treatment, mining, and offshore wind installations. Secondary validation drew from IEC 61800-4 certification databases, BIS efficiency labeling registries, EU F-Gas Regulation implementation schedules, and customs trade data for IGBT module flows. Bottom-up and top-down triangulation reconciled equipment shipment volumes with end-use industry capital expenditure patterns.
Bottom-up modeling segmented the analysis window by drive type, power semiconductor technology, application duty cycle, and end-user industry regulatory exposure. Top-down cross-checks incorporated energy intensity benchmarks for desalination, mining electrification, and chemical process optimization. CAGRs were derived from segment-level demand elasticity and replacement cycle analysis. Forecast inputs included PLI scheme disbursement timelines in India and MIIT dual carbon compliance trajectories in China.
Underlying measurement precision varies by segment; water treatment and mining applications carry tighter precision than waste management due to documented project pipelines. Forecasts reflect assumptions around semiconductor supply stabilization and regulatory harmonization timelines. Geopolitical friction in Taiwanese foundry access, copper price volatility, and divergent BIS-NMPA certification protocols present specific revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Europe Circuit Breakers Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Global Circuit Breakers Market
Electrical Equipment
Low Voltage Electric Motor Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Asia-Pacific Electrical Bushing Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
North America Electrical Bushing Market