
 Fiber Optical Cable and Cable Assembly Products Market | 2026-2036
Fiber Optical Cable and Cable Assembly Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optical Cable and Cable Assembly Products Market Foresight
Hyperscale data center operators are unwinding the traditional dominance of telecom carriers as the primary volume buyers of fiber optical cable and cable assembly products. Corning leverages its vertically integrated fused silica supply chain to anchor premium single-mode fiber production in North America. YOFC competes on manufacturing scale across central China, while Prysmian sustains its position through deep specialization in submarine and terrestrial cable systems for European utility networks.
Fiber optical cable and cable assembly products encompass silica-core waveguides with doped cladding layers, typically housed in UV-cured acrylate buffers and aramid strength members, engineered to transmit photonic signals across single-mode or multi-mode architectures with attenuation below 0.2 dB per kilometer at 1550 nanometers. Their primary commercial purpose is to replace copper conductors in high-bandwidth, electromagnetically sensitive environments where signal integrity over distance determines system economics. Outdoor cables dominate volume shipments due to 5G fronthaul and FTTH network builds, while connectorized assemblies capture disproportionate margin pools through factory-terminated precision and reduced field labor costs. Active optical technology leads growth in data center interconnects where reach and power efficiency override first-cost considerations.
The Federal Communications Commission in the United States shapes demand through broadband subsidy programs requiring fiber-to-the-premises compliance, while the European Commission's F-Gas Regulation and CE marking directives enforce environmental and performance standards on cable jacketing materials. China's Ministry of Industry and Information Technology sets domestic deployment targets that directly influence global silica preform allocation. Stakeholders must monitor divergence between national security-driven supply chain localization mandates and the technical interoperability requirements of multinational cloud platforms.
Market Dynamics
Hyperscale data center buildouts are compressing deployment cycles and forcing fiber cable suppliers to recalibrate capacity planning around AI-driven bandwidth spikes rather than traditional telecom capex rhythms.
Growth Catalysts
- 5G fronthaul densification:Mobile network operators in China are deploying massive MIMO architectures that require fiber counts per cell site to quadruple, sustaining volume pull through MIIT-mandated coverage targets.
- REACH and RoHS compliance mandates:European cable procurement specifications now exclude halogenated jacketing materials, redirecting contract awards toward suppliers with certified low-smoke zero-halogen product lines.
- AI training cluster interconnects:Data center operators are specifying single-mode fiber for GPU-to-GPU links exceeding 500 meters, creating premium demand segments distinct from traditional enterprise LAN specifications.
Market Restraints
- Silica preform supply concentration:High-purity synthetic quartz crucible production clusters in Hubei province and upstate New York, exposing buyers to geographic concentration risk during trade policy disruptions.
- Copper cable residual cost advantage:Short-reach data center applications under 30 meters continue to evaluate passive copper direct attach cables for 400G Ethernet, delaying fiber conversion at the rack level.
- F-Gas Regulation compliance friction:European cable jacketing compound suppliers face extended reformulation timelines to eliminate fluorinated greenhouse gases from manufacturing processes.
Strategic Opportunities
- India national broadband mission:The BharatNet program's phase-three rural fiberization targets create demand for cost-optimized cable designs suited to trenching and aerial deployment constraints.
- Subsea cable system refresh cycles:Transoceanic routes approaching 25-year design lifespans require repeatered cable replacements, opening specialized assembly contracts for marine-qualified suppliers.
- Photonic integrated circuit convergence:Co-packaged optics in switch silicon are driving demand for precision fiber array units that bridge semiconductor packaging with external cable connectivity.
Industry Challenges
- Fusion splicing technician scarcity:Field termination quality for single-mode fiber depends on certified installer density, which lags deployment schedules in emerging markets.
- Interoperability certification timelines:Cable assemblies must complete GR-326-CORE and IEC-61300-3-34 testing sequences before hyperscale qualification, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optical Cable and Cable Assembly Products Market |
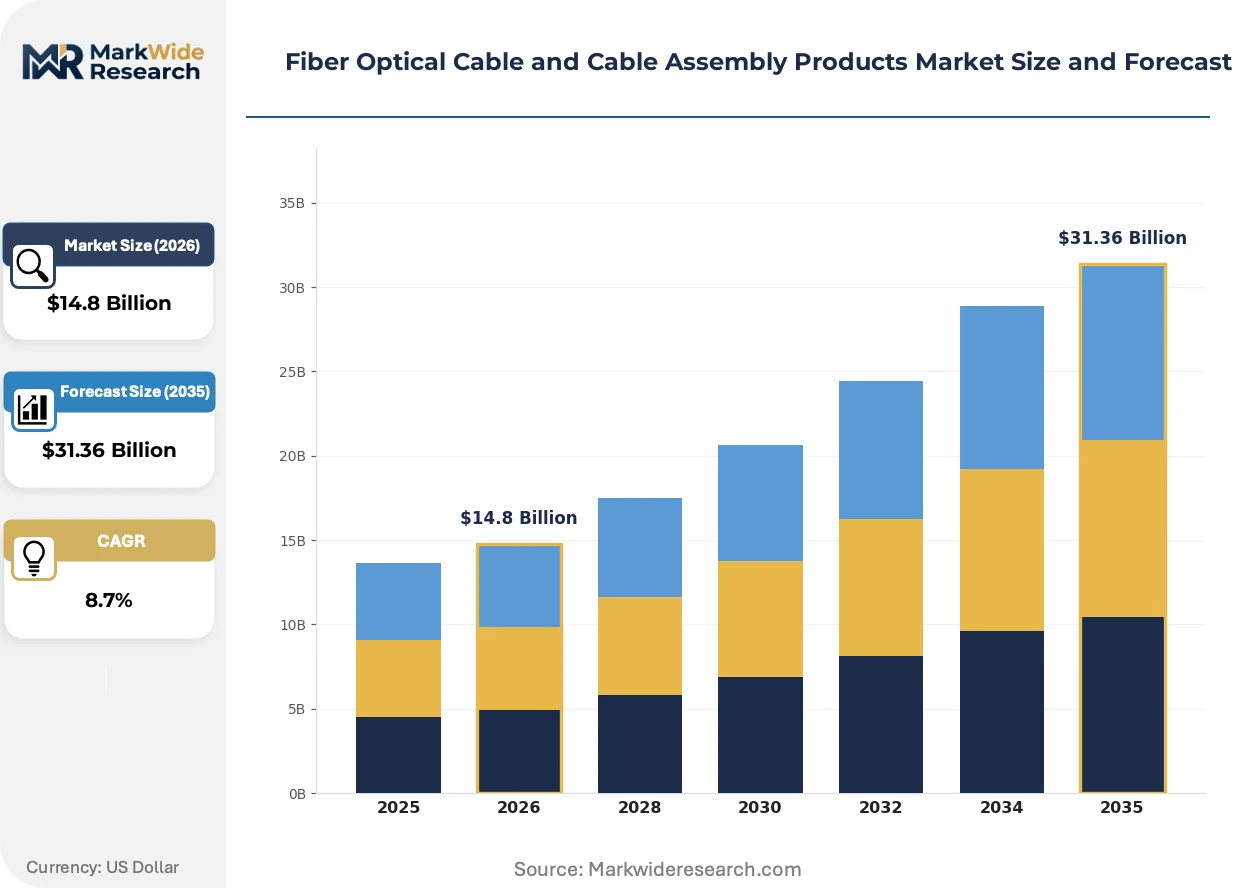
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Cables, Outdoor Cables, Connectorized Assemblies, Patch Cords Application: Telecommunications, Data Centers, Industrial Networking, Utilities Technology: Single-Mode, Multi-Mode, Active Optical, Passive Optical End User: Telecom Providers, Enterprises, Government, Educational Institutions |
| Companies Covered | Fujikura, Nexans, Prysmian, Furukawa Electric, YOFC, Corning, CommScope, LS Cable & System, Sumitomo Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optical Cable and Cable Assembly Products Market Shifts & Advancements
Optical connectivity is bifurcating between commodity volume plays in access networks and precision-engineered assemblies for AI infrastructure, with manufacturing automation and materials science determining competitive position across both tiers.
Hollow-core fiber is supplanting conventional solid-core single-mode designs in select latency-sensitive applications. Financial trading networks and distributed AI training clusters are piloting photonic-bandgap structures that reduce signal propagation delay by approximately one-third. This substitution is compressing the addressable market for premium low-dispersion fiber in sub-100 kilometer reaches.
REACH Annex XVII restrictions on phthalate plasticizers are forcing compound reformulation across European cable jacketing supply chains. Manufacturers are accelerating bio-based thermoplastic polyurethane development to maintain flexibility ratings without restricted additives. Outdoor-rated cable categories face the steepest compliance cost inflation as weathering performance specifications tighten concurrently.
Specification consolidation among hyperscale cloud architects is narrowing the approved vendor lists for data center interconnect assemblies. Buyers are unbundling cable procurement from switch hardware contracts, creating direct sourcing relationships that bypass traditional distribution channels. This pattern concentrates most visibly in Northern Virginia and Frankfurt metro area buildouts where multiple operators share colocation ecosystems.
Fiber Optical Cable and Cable Assembly Products Market Segmentation
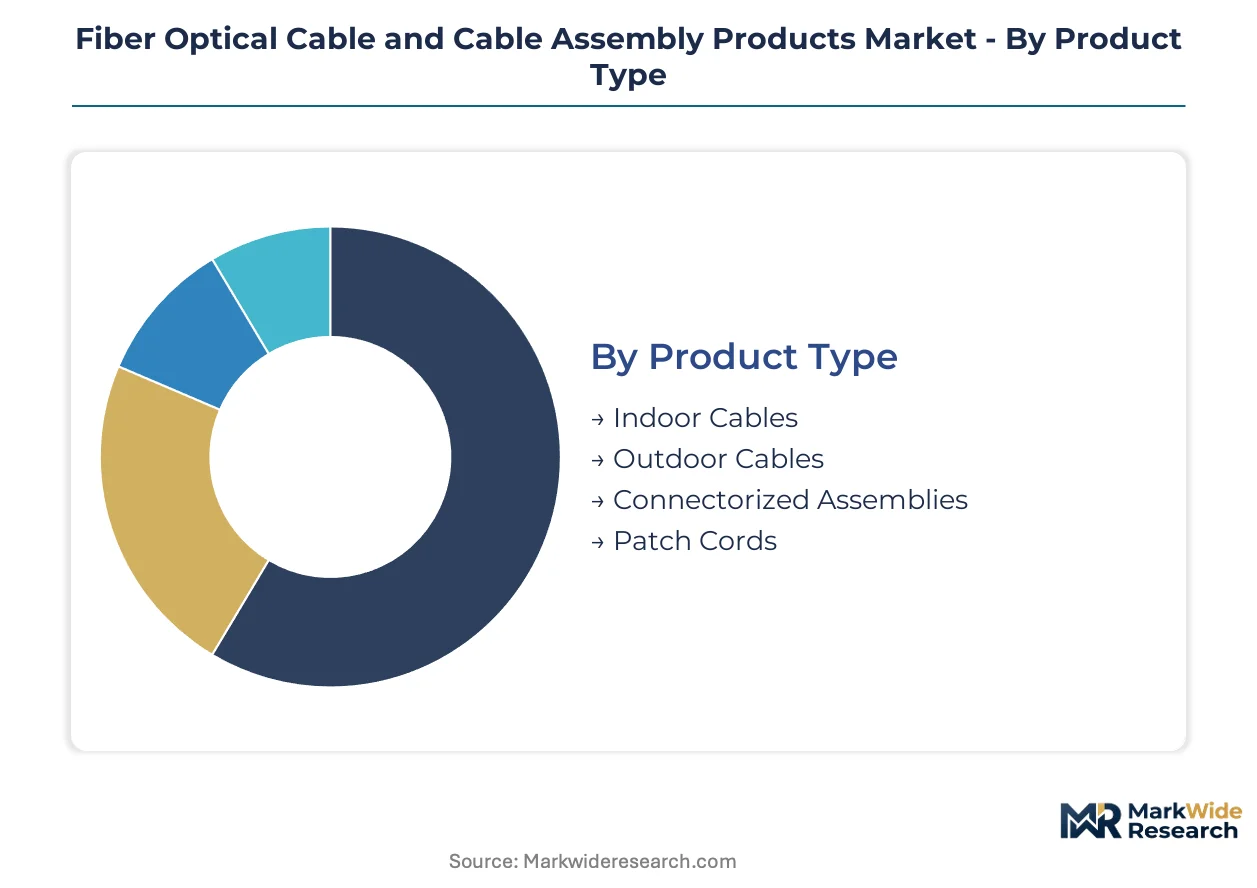
Segmentation in fiber optical cable markets separates volume-driven commodity flows from precision-engineered premium channels. Procurement patterns diverge sharply between carrier-led infrastructure builds and hyperscale direct sourcing for AI clusters.
Product Type:
Channel mix varies dramatically: outdoor cables flow through carrier procurement frameworks and national broadband tenders, while connectorized assemblies increasingly bypass distribution through direct hyperscale contracts.
- Outdoor Cables:These incorporate UV-stabilized polyethylene sheathing, gel-filled loose tubes, and steel or FRP strength members rated for aerial, duct, and direct-buried installation. Demand concentrates in China's MIIT-mandated 5G fronthaul and BharatNet rural fiberization, where trenching and pole-mounting dominate deployment economics.
- Connectorized Assemblies:Factory-terminated with ceramic ferrules polished to sub-micron eccentricity tolerances, these arrive pre-tested to GR-326-CORE standards. Data center operators in Northern Virginia and Frankfurt metro areas specify these for GPU interconnects to eliminate field splicing labor and quality variance.
- Indoor Cables:Tight-buffered designs with LSZH-rated jackets serve enterprise LAN riser and plenum applications under REACH fire safety mandates.
- Patch Cords:Short-reach duplex assemblies with standardized connector interfaces complete rack-level connectivity in enterprise and colocation environments.
Outdoor cables dominate installed base. Connectorized assemblies are where expansion concentrates.
Application:
Cost tier separation is pronounced: telecommunications deployments optimize for first-cost per fiber-kilometer, while data center specifications prioritize attenuation uniformity and bend-insensitivity regardless of premium pricing.
- Telecommunications:Carrier backbone and access networks drive single-mode fiber volume through ITU-T G.652.D and G.654.E specifications. China's three-tier operator structure—China Mobile, China Telecom, China Unicom—accounts for sustained large-scale procurement through centralized tenders.
- Data Centers:AI training clusters require low-latency, high-fiber-count trunk cables for GPU-to-GPU communication exceeding 500 meters. Operators specify MPO/MTP multifiber push-on assemblies with factory-controlled polarity and loss budgets below 0.35 dB per mated pair.
- Industrial Networking:Ruggedized cables with armored jackets and oil-resistant compounds serve manufacturing automation and process control in automotive and chemical facilities.
- Utilities:Electric power companies deploy optical ground wire and all-dielectric self-supporting cables for grid monitoring and smart metering backhaul.
Telecommunications anchors volume procurement. Data centers are climbing the fastest as AI infrastructure scales.
Technology:
Customer type determines specification: telecom carriers standardize on mature passive optical formats, while cloud operators pilot active optical and hollow-core alternatives for reach extension.
- Single-Mode:Doped-silica core with 8.3-micron mode field diameter achieves attenuation below 0.17 dB/km at 1550 nanometers. This technology captures long-haul, metro, and now data center interconnect demand as reach requirements extend.
- Multi-Mode:50-micron graded-index cores optimized for 850-nanometer VCSEL transmission serve enterprise LANs and short-reach data center links under 100 meters where transceiver cost differentials favor vertical-cavity technology.
- Active Optical:Pluggable modules with integrated photonics and retimers enable reach extension to 10 kilometers without discrete transponder shelves. Cloud operators specify these for spine-leaf architectures.
- Passive Optical:Unamplified, unpowered splitters and WDM devices remain the cost-optimized standard for FTTH GPON and XGS-PON access networks.
Single-mode fiber dominates installed base. Active optical is gaining share fastest in hyperscale environments.
End User:
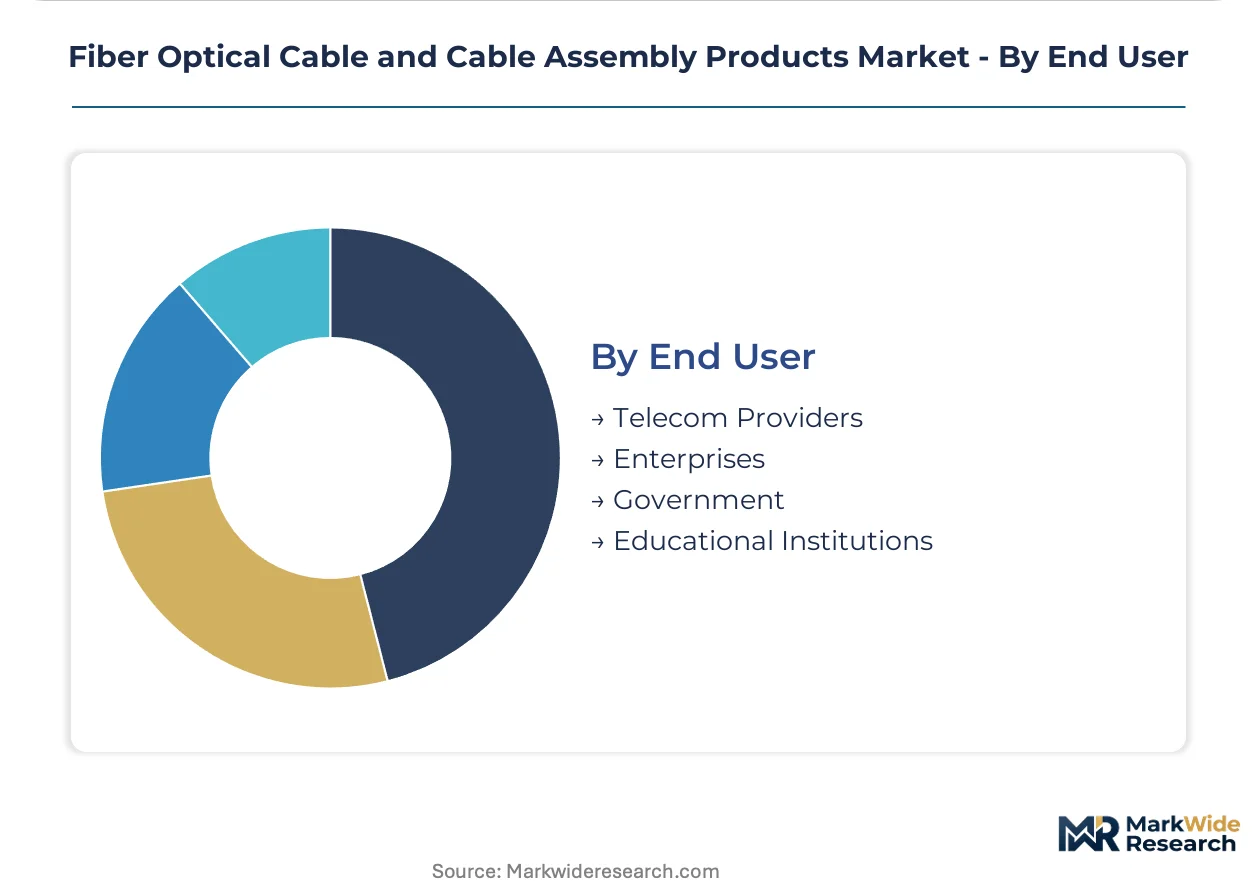
Volume concentration sits with telecom providers, though procurement autonomy is fragmenting as enterprises and government entities develop direct supplier relationships for specialized requirements.
- Telecom Providers:Incumbent and competitive carriers execute multi-year framework agreements with Corning, YOFC, and Prysmian for fiber and cable supply. Their capex cycles—historically 3-5 year infrastructure refresh rhythms—are compressing under 5G densification urgency.
- Enterprises:Financial services, healthcare, and cloud-adopting corporations specify private fiber networks for latency control and security compliance. Trading firms in London and New York pilot hollow-core fiber for microsecond advantages.
- Government:National security agencies and defense departments mandate TAA-compliant, domestic-manufactured cable for classified facility interconnects under Buy America provisions.
- Educucational Institutions:Research universities deploy specialized fiber for scientific instrumentation, quantum networking testbeds, and campus backbone refresh cycles funded by federal research grants.
Telecom providers dominate installed base. Enterprises are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable landing stations in Bude, Cornwall and Marseille anchor Europe's transatlantic and Mediterranean bandwidth exchange, underwriting the continent's role as a fiber interconnection hub between Asia-Pacific and North American traffic flows.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives single-mode fiber consumption for AI cluster interconnects. The FCC's broadband subsidy programs mandate fiber-to-the-premises compliance for rural deployment funding. Corning's fused silica preform operations in upstate New York supply premium fiber to domestic cable fabricators serving cloud operator specifications.
China
MIIT-mandated 5G fronthaul densification and national broadband expansion sustain the world's largest optical cable procurement volumes. The dual carbon goals framework imposes energy efficiency standards on preform manufacturing processes. YOFC's manufacturing base in Wuhan, Hubei province, anchors central China's optical materials production cluster serving domestic three-tier carrier tenders.
Germany
Utility network modernization and industrial automation backhaul requirements drive specialty cable demand for smart grid applications. REACH Annex XVII restrictions on phthalate plasticizers force jacketing compound reformulation across European supply chains. Prysmian's cable system engineering operations in Milan and Essen specialize in submarine and high-voltage terrestrial fiber deployments for European infrastructure operators.
India
BharatNet phase-three rural fiberization targets create demand for cost-optimized cable designs suited to trenching and aerial constraints. TRAI's infrastructure sharing mandates reduce duplicate fiber deployment in urban corridors. Manufacturing clusters in Gujarat and Maharashtra produce LSZH-rated indoor cables for commercial building installations under evolving fire safety codes.
Japan
Financial trading networks in Tokyo and Osaka pilot hollow-core fiber for microsecond latency advantages in high-frequency applications. METI's technology roadmaps support photonic integrated circuit development for co-packaged optics convergence. Furukawa Electric and Sumitomo Electric's Chubu region operations maintain precision fiber array manufacturing for semiconductor packaging integration.
Fiber Optical Cable and Cable Assembly Products Market Competitive Landscape
Concentration sits with integrated materials suppliers controlling synthetic quartz crucible production and cable system specialists commanding submarine installation expertise. The market structure tiers between premium fiber preform manufacturers, scale-driven cable fabricators, and precision assembly houses serving hyperscale direct procurement. Strategic moves center on backward integration into high-purity silica supply and geographic expansion through national broadband framework agreements.
Among integrated materials-to-cable suppliers, Corning, YOFC, and Prysmian occupy positions spanning preform production through finished cable systems. Corning represents the North American vertically integrated archetype with captive fused silica supply. YOFC exemplifies scale-driven manufacturing concentration serving domestic Chinese carrier tenders. Prysmian anchors European specialization in submarine and utility-grade terrestrial systems. These three entities illustrate how control over upstream optical materials separates premium fiber positioning from commodity cable assembly competition.
| Leading Market Players |
|---|
| Fujikura |
| Nexans |
| Prysmian |
| Furukawa Electric |
| YOFC |
| Corning |
| CommScope |
| LS Cable & System |
| Sumitomo Electric |
| Others |
Supply & Pricing Matrix
Capacity utilization at synthetic quartz crucible facilities in Hubei province and upstate New York shapes both supply concentration and price floors across the fiber optical cable value chain. Scale economies in fused silica preform production concentrate margin capture upstream, while downstream cable fabricators face compressed spreads when carrier capex cycles decelerate.
Pricing Analysis
Volume-discount tiering structures separate hyperscale direct contracts from carrier framework agreements. Three-tier pricing stratifies across premium low-dispersion fiber for AI clusters, standard single-mode for telecom backbones, and economy multi-mode for enterprise LANs. Price differentiation hinges on ITU-T G.654.E certification grade and bend-insensitivity specifications. Cost compression in the economy tier intensifies as Chinese manufacturers expand LSZH-rated indoor cable capacity. Carrier procurement teams demonstrate highest price sensitivity, while cloud operators prioritize attenuation uniformity over unit cost.
Supply Chain Analysis
Strategic stockpiling of high-purity synthetic quartz crucibles dominates inventory strategy given 18-24 month lead times for specialized furnace components. Geographic supply concentration centers on China, the United States, and Japan for preform manufacturing, with Italy and Germany anchoring submarine cable system assembly. Raw material dependencies draw from semiconductor-grade silicon tetrachloride, germanium tetrachloride dopants, and UV-cured acrylate buffer compounds. Single-source vulnerability in synthetic quartz crucible supply exposes buyers to trade policy disruptions. Distribution runs through carrier procurement frameworks, hyperscale direct sourcing channels, and specialized marine cable contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical connectivity is approaching a platform-economics inflection as co-packaged optics convergence forces interoperability standardization between semiconductor packaging and external fiber arrays.
For Market Incumbents: Compound defensive positioning through captive fused silica supply and GR-326-CORE certification density. Hollow-core fiber pilot deployments by financial trading networks threaten premium low-dispersion fiber margins. Prioritize backward integration into photonic integrated circuit packaging partnerships to anchor switch silicon co-design relationships. For New Entrants and Emerging Players: CE marking fast-tracks for LSZH-rated indoor cables open European commercial building retrofit demand. India's BharatNet phase-three rural fiberization presents the most penetrable geography given cost-optimized cable requirements and limited incumbent saturation. Pursue direct sourcing relationships with state-level fiberization agencies bypassing national carrier frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connectorized assembly specialists serving hyperscale data center interconnect programs. Long-term viability favors precision fiber array manufacturers bridging semiconductor packaging with external connectivity. Monitor hollow-core fiber field trial outcomes as inflection indicator for latency-sensitive application substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fused Silica Preform Production | Captive supply of synthetic quartz crucibles secures margin capture against Hubei province concentration risk. |
| GR-326-CORE Certification Investment | Factory-terminated precision assemblies qualify for hyperscale direct procurement bypassing distribution channels. |
| Photonic Integrated Circuit Packaging Partnership | Co-packaged optics convergence demands fiber array units bridging semiconductor packaging with external connectivity. |
| LSZH Compound Reformulation for REACH Compliance | Bio-based thermoplastic polyurethane development maintains European market access under Annex XVII restrictions. |
| Submarine Cable System Engineering Capability Buildout | Transoceanic route refresh cycles open specialized marine-qualified assembly contracts for European utility networks. |
Research Methodology
Operator-level perspectives from data center infrastructure directors, carrier procurement executives, fiber cable plant managers, and hyperscale network architects anchored the qualitative base. Primary interviews combined with secondary validation from FCC broadband subsidy filings, MIIT deployment target disclosures, SEC 10-K supply chain disclosures, and ITU-T standards documentation. Bottom-up fiber kilometer demand modeling triangulated against top-down capex flow analysis.
Sensitivity analysis tested forecast outputs against varying AI cluster buildout trajectories and carrier densification schedules. Segmentation dimensions modeled include cable type, application architecture, fiber technology, and end-user procurement autonomy across the projection horizon. CAGRs derived from installed base replacement cycles, net new deployment velocity, and unit value migration toward precision-engineered assemblies. Forecast inputs incorporated silica preform capacity expansion timelines and REACH regulatory compliance cost pass-through assumptions.
Underlying assumptions cover sustained MIIT-mandated 5G fronthaul targets, hyperscale AI infrastructure scaling, and stable trade policy conditions for optical materials, with deviation risk concentrated in tariff exposure on synthetic quartz crucibles and F-Gas Regulation reformulation timelines. Revision becomes warranted when hollow-core fiber field deployment crosses commercialization thresholds or when carrier capex cycles compress beyond historical 3-5 year rhythms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cable Materials Market
Cables
Global Cable Gland Market
Cables
Copper Cable Market
Cables
Patch Cable Market
Cables
Submarine Cables Market
Cables
Wire and Cable Label Market
Cables
Asia-Pacific Cable Joints Market
Cables
Anti-Static Space Wires Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Middle East Cable Market
Cables
Coaxial Cable Market
Cables
Asia-Pacific Premise Cable Market
Cables
Hybrid Cables Market
Cables
Global Wires and Cables Market
Cables
Latin America Wire and Cable Market
Cables
Sensing Cable Market