
 Russia LED Market | 2026-2036
Russia LED Market Size, Share, and Industry Trends Forecast 2026-2036
Russia LED Market Intelligence
Subscription-based luminaire management is realigning how Russian municipalities and enterprises procure lighting infrastructure. GS Group leverages captive semiconductor fabrication to control chip supply through domestic foundries. Varton sustains manufacturing scale at its Tatarstan facilities, anchoring regional distribution networks. Arlight specializes in architectural fixture customization, competing for premium commercial fit-outs in Moscow's redevelopment zones.
A light-emitting diode converts electrical current directly into photons through electroluminescence in a semiconductor junction, typically achieving luminous efficacy above 150 lumens per watt in contemporary phosphor-converted white packages. The technology serves primarily to displace gas-discharge and incandescent sources across illumination, signaling, and display backlighting functions. Bulbs and fixtures command the majority of current procurement value, though smart LED systems are capturing margin pools through connected controls and energy management integration. Commercial application demand outpaces residential expansion, driven by corporate sustainability mandates and operating cost reduction targets. Standard LED technology retains volume dominance while quantum dot-enhanced variants occupy premium display and high-CRI professional segments.
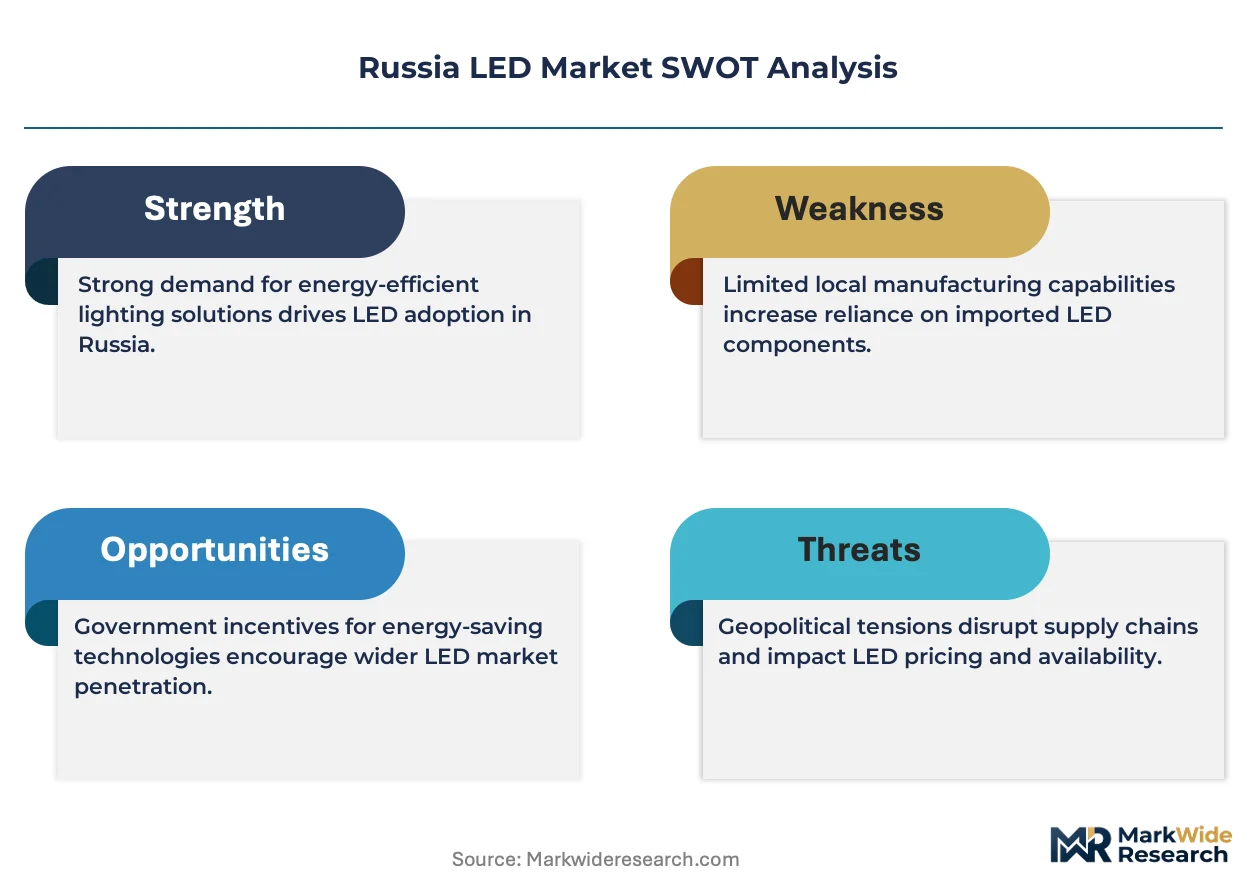
Russia's national technical regulation framework, administered through Rosstandart and GOST R certification requirements, mandates electromagnetic compatibility and energy efficiency compliance for lighting equipment placed on the market. The country's sanitary-epidemiological regulator enforces photobiological safety standards aligned with IEC 62471 hazard classifications for blue light exposure. Federal tariff regulation and grid connection rules from the Ministry of Energy shape demand-side management incentives for large-scale LED deployment. Stakeholders must monitor how import substitution policies and localization requirements evolve for semiconductor packaging and driver electronics supply.
Market Dynamics
Federal energy efficiency mandates are accelerating the displacement of sodium vapor infrastructure, while import substitution policies force rapid localization of semiconductor packaging and driver electronics supply chains.
Growth Catalysts
- GOST R Certification Alignment:Electromagnetic compatibility mandates from Rosstandart create compliance-driven replacement cycles across commercial installations.
- Moscow Street Lighting Modernization:Municipal procurement programs in the capital region prioritize high-efficacy LED retrofits for arterial road networks.
- Smart Controls Integration:Connected energy management systems are absorbing margin pools from standalone luminaire sales through subscription-based monitoring.
Market Restraints
- Semiconductor Import Dependency:Wafer and chip supply concentrates in Asian foundries, exposing Russian assemblers to logistics volatility and payment clearance friction.
- Phosphor Material Cost Structure:Rare earth element pricing for warm-white conversion layers fluctuates with export quota regimes.
- Driver Electronics Localization Gap:Domestic capacity for power management ICs remains underdeveloped relative to fixture assembly scale.
Strategic Opportunities
- Siberian Industrial Corridor Penetration:Remote mining and extraction facilities present untapped demand for ruggedized high-bay systems with extreme temperature tolerance.
- Human-Centric Lighting Convergence:Circadian rhythm tuning is absorbing specification share in healthcare and education verticals.
- Rosstandart Fast-Track Certification:Streamlined testing pathways for locally manufactured components reduce time-to-market for domestic packaging ventures.
Industry Challenges
- Optical Design Talent Scarcity:Russian engineering programs produce insufficient specialists in photometric simulation and thermal management modeling.
- Legacy Sodium Vapor Infrastructure Interoperability:Municipal maintenance crews require retraining for semiconductor-based fault diagnosis and networked control troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia LED Market |
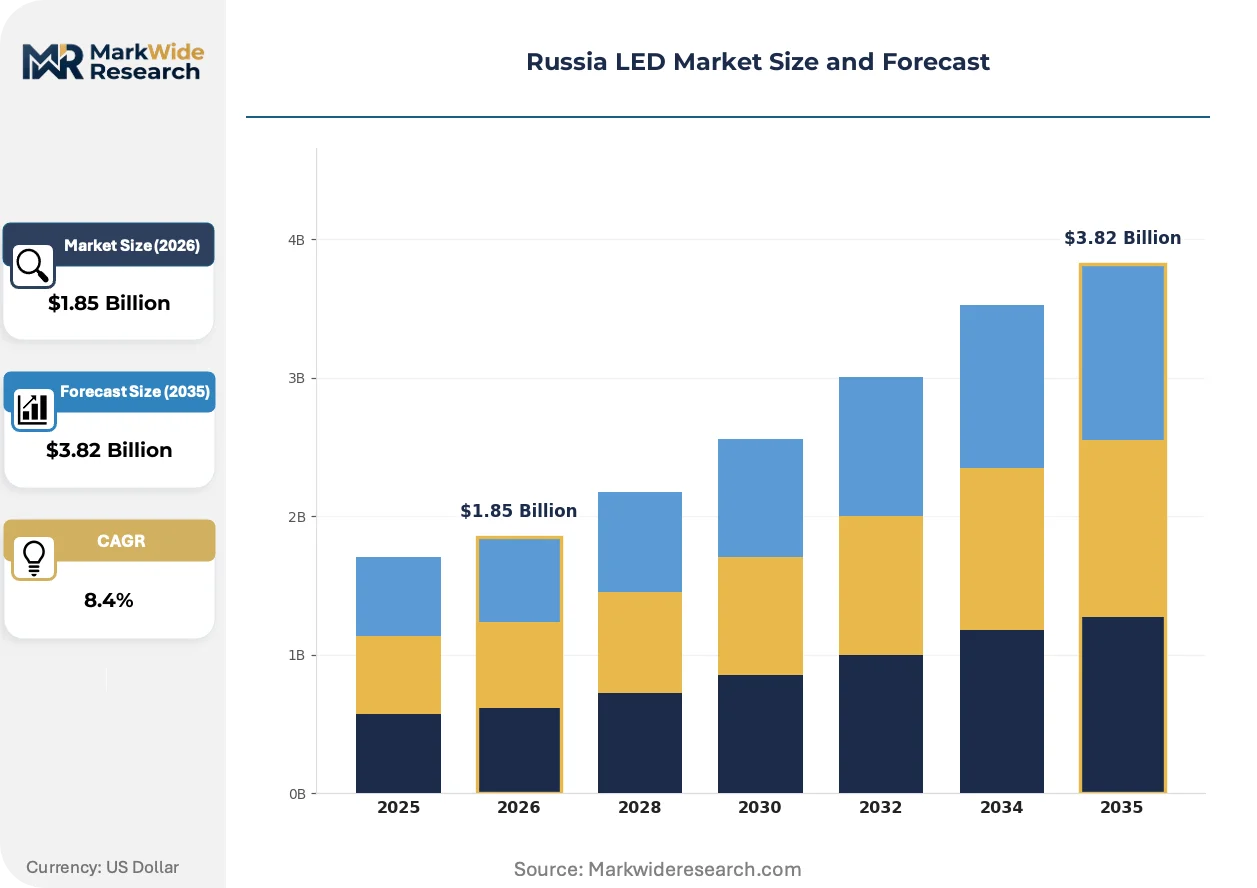
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Modules Application: Commercial, Residential, Industrial, Outdoor Technology: Organic LED, Quantum Dot, Standard LED, Smart LED End User: Retailers, Contractors, Government, Enterprises |
| Companies Covered | GS Group (GS LED), Arlight, Optogan, LedEcoDom, Planeta Sid, Varton, LED Effect, RW Light, Era LED Light Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia LED Market Strategic Shifts & Innovations
Technological substitution is compressing traditional luminaire economics while regulatory pressure and procurement model innovation reshape competitive positioning.
Phosphor-converted white LED packages are absorbing specification share across professional illumination applications. Retail chains and logistics operators in Saint Petersburg are specifying efficacy thresholds above 150 lumens per watt for new construction. This performance tier is absorbing margin from legacy fluorescent retrofits and accelerating payback-driven procurement decisions.
Rosstandart's alignment with IEC 62471 photobiological safety classifications is tightening blue light hazard assessment protocols for consumer-facing installations. Fixture manufacturers must now submit spectral power distribution data for certification review. Educational and healthcare facilities face the steepest compliance burden as hazard classification documentation becomes mandatory for public tender participation.
Subscription-based luminaire management is displacing capital expenditure models among municipal and enterprise buyers. GS Group and regional operators now bundle hardware, installation, and remote monitoring into per-lumen-hour contracts. This financing structure is most visible in Moscow's street lighting modernization, where energy service companies assume performance risk and capture savings through guaranteed efficacy clauses.
Russia LED Market Segmentation
Russia's LED procurement patterns fragment sharply across buyer sophistication and technical requirements. Municipal tender specifications diverge fundamentally from retail chain retrofit criteria, forcing suppliers to maintain parallel certification and distribution capabilities.
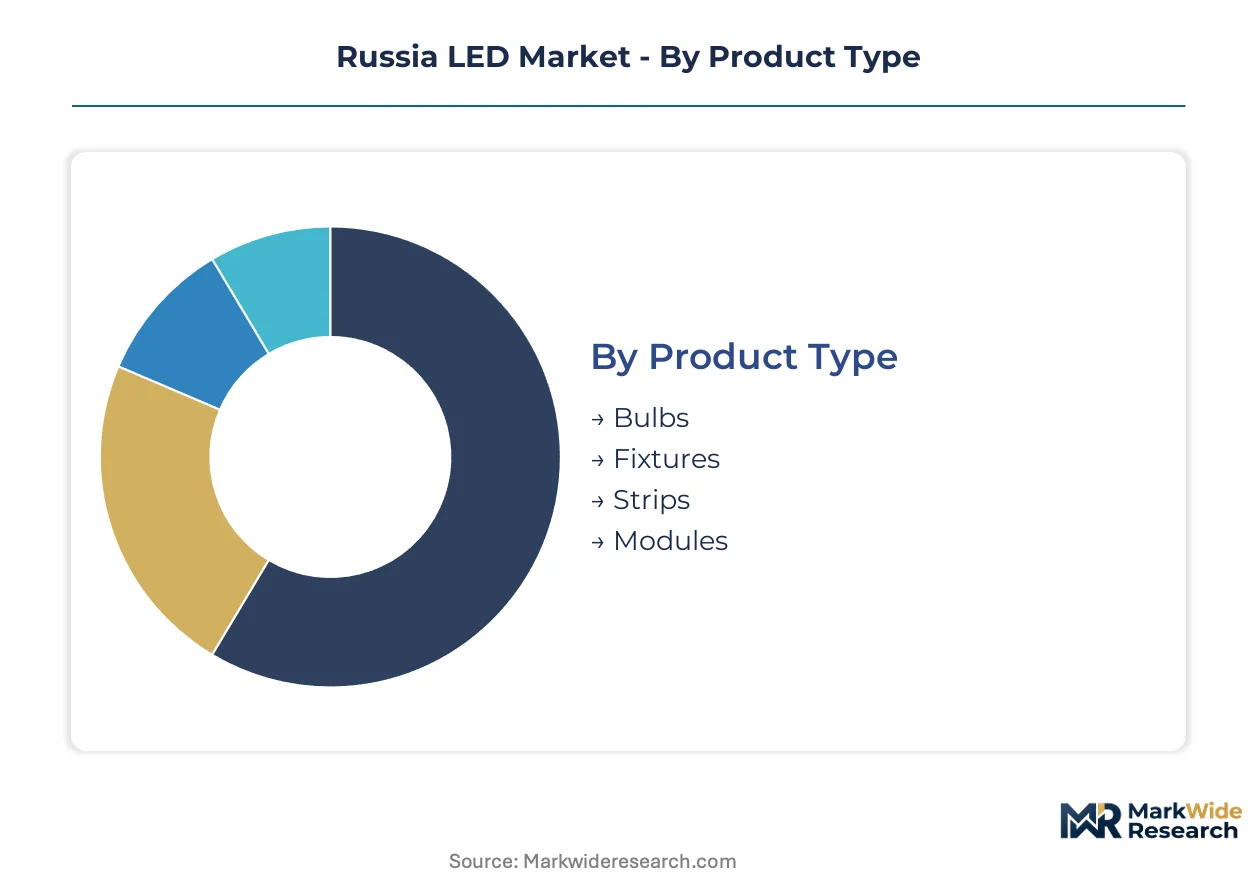
Product Type:
Cost tier separates volume buyers from specification-driven procurement.
- Fixtures:Integrated luminaire assemblies with thermal management housings and optical systems dominate commercial new-build specifications. Moscow's street lighting modernization and Saint Petersburg retail redevelopment absorb the majority of high-bay and roadway fixture procurement, driven by federal energy efficiency mandates phasing out sodium vapor infrastructure.
- Bulbs:Retrofit lamps with Edison and bayonet bases serve residential replacement cycles and legacy fixture upgrades. Replacement demand concentrates in multi-unit residential buildings across Moscow Oblast and Tatarstan, constrained by consumer price sensitivity and limited distribution reach beyond major urban centers.
- Strips:Flexible linear arrays with adhesive mounting serve architectural accent and display lighting applications.
- Modules:Bare board assemblies with LED arrays and onboard drivers target OEM integration and custom fixture fabrication.
Volume sits with bulbs; growth tilts toward fixtures.
Application:
Customer type determines margin structure and contract duration.
- Commercial:Office complexes, retail chains, and hospitality operators specify efficacy thresholds above 150 lumens per watt for payback-driven retrofits. Saint Petersburg logistics operators and Moscow financial district landlords prioritize connected controls integration for demand-side management compliance.
- Outdoor:Roadway, tunnel, and municipal illumination requires IP-rated housings and extreme temperature tolerance. Federal street lighting programs in Moscow and regional capitals absorb high-bay and cobra-head luminaire production from domestic assembly facilities.
- Industrial:Mining extraction facilities and manufacturing plants in the Siberian Industrial Corridor demand ruggedized high-bay systems.
- Residential:Single-family and multi-unit dwelling retrofits follow replacement cycles and renovation activity.
Commercial captures the deepest margin pools; outdoor expands most quickly through municipal procurement acceleration.
Technology:
Maturity stage separates incumbent volume from emerging specification share.
- Standard LED:Phosphor-converted white packages with luminous efficacy above 150 lumens per watt dominate professional illumination. Retail and logistics operators in Saint Petersburg specify this performance tier for new construction, displacing legacy fluorescent retrofits through accelerated payback economics.
- Smart LED:Connected luminaires with embedded sensors and networked controls absorb margin from standalone hardware through subscription-based energy management. GS Group and regional operators bundle installation and remote monitoring into per-lumen-hour contracts for Moscow municipal street lighting.
- Quantum Dot:Nanocrystal-enhanced emission delivers high-CRI output for premium display and professional visualization applications.
- Organic LED:Thin-film electroluminescent panels serve architectural accent and display backlighting niches.
Standard LED maintains volume dominance; smart LED climbs the fastest through procurement model innovation.
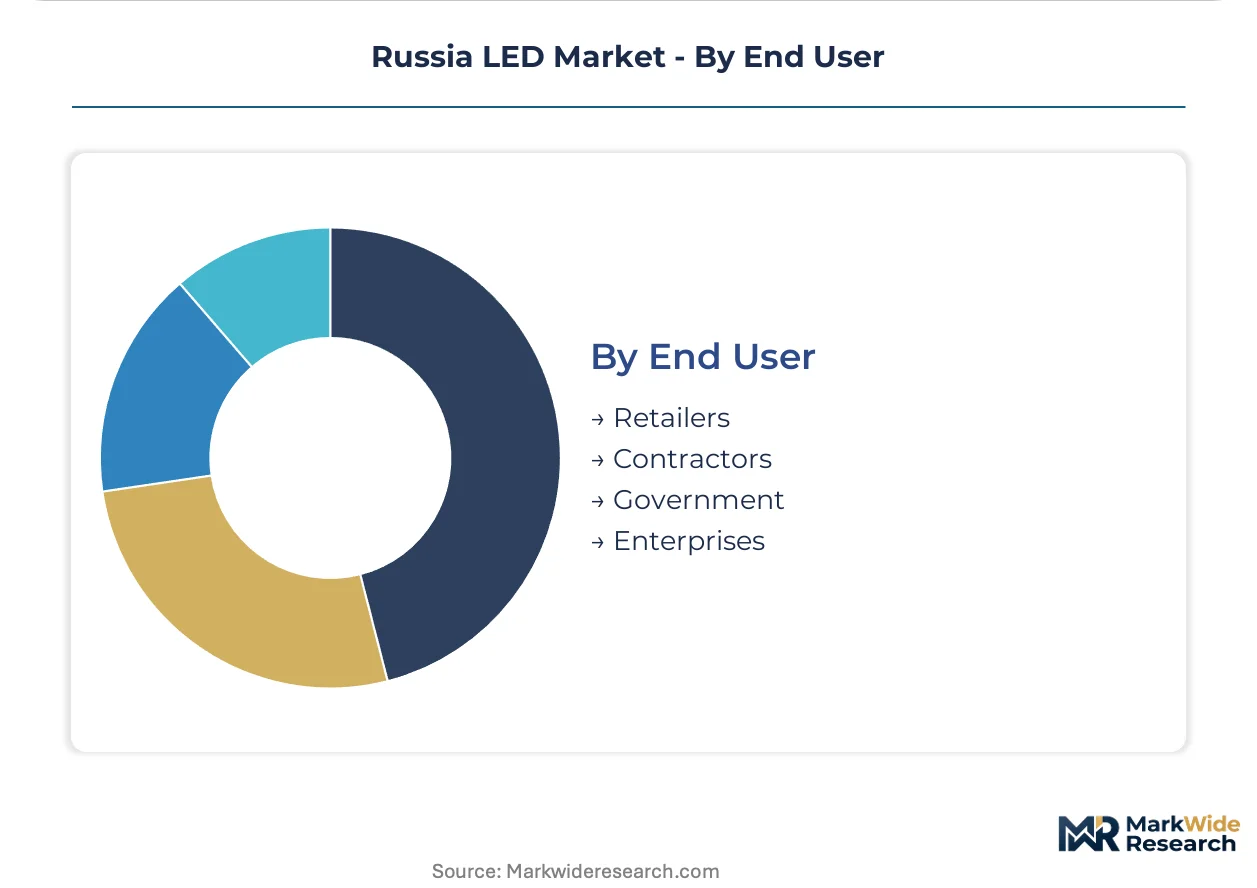
End User:
Procurement authority separates centralized tender participation from fragmented spot buying.
- Government:Federal and municipal agencies administer large-scale street lighting and public building retrofit programs through competitive tender. Rosstandart certification and GOST R electromagnetic compliance are mandatory for contract eligibility, with hazard classification documentation required for educational and healthcare facility tenders.
- Enterprises:Corporate facility managers and sustainability officers specify retrofit packages for operating cost reduction. Moscow headquarters operations and Saint Petersburg industrial parks drive bulk procurement through energy service company arrangements.
- Contractors:Electrical installation firms source project-specific quantities for new construction and renovation.
- Retailers:DIY chains and electrical wholesalers serve replacement demand and small-scale residential projects.
Government commands the largest individual contracts; enterprises gain specification influence fastest through sustainability mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic LED assembly capacity concentrates in Central Russia while consumption spreads across federal districts with varying infrastructure maturity. Moscow and Saint Petersburg absorb premium fixture volumes; regional capitals drive replacement cycles through municipal procurement.
Central Federal District
Moscow's street lighting modernization program mandates efficacy thresholds above 150 lumens per watt for arterial roadway retrofits. Rosstandart enforces GOST R electromagnetic compliance for all luminaires entering municipal tenders. The Moscow Oblast corridor anchors fixture distribution networks serving commercial new-build specifications.
Northwestern Federal District
Saint Petersburg logistics operators and retail chains specify connected controls integration for demand-side management compliance. The Ministry of Energy's grid connection rules shape large-scale deployment incentives for warehouse and port illumination. The Neva River industrial zone absorbs high-bay production from domestic assembly facilities.
Volga Federal District
Tatarstan hosts captive semiconductor packaging operations supplying chip-on-board modules to regional fixture manufacturers. Federal import substitution policies accelerate localization of driver electronics production. Kazan serves as a distribution hub for Bulb retrofit demand across multi-unit residential buildings.
Siberian Federal District
Remote mining extraction facilities in the Kemerovo and Krasnoyarsk regions generate demand for ruggedized high-bay systems with extreme temperature tolerance. The Siberian Industrial Corridor remains underpenetrated by smart controls integration due to connectivity infrastructure gaps. Norilsk Nickel operations specify IP-rated housings for sub-zero operational environments.
Southern Federal District
Rostov-on-Don and Krasnodar municipal programs prioritize sodium vapor displacement through federal energy efficiency mandate compliance. Sanitary-epidemiological regulators enforce photobiological safety documentation for educational facility tenders. The Black Sea port cluster drives marine-grade fixture specifications for dock and warehouse illumination.
Russia LED Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Russian LED sector. Foundry-backed players control upstream chip supply through captive semiconductor fabrication, while fabless assemblers source packaged dies from import channels. The vendor base fragments between integrated luminaire manufacturers, component suppliers, and energy service companies bundling hardware with monitoring subscriptions. Two archetypes dominate: vertically integrated domestic producers leveraging localization policy advantages, and regional distributors capturing spot procurement through inventory proximity. Competitive moves center on backward integration into driver electronics and strategic partnerships with municipal energy service companies.
Among domestic integrated producers, GS Group and Varton occupy positions anchoring volume supply to federal modernization programs. Arlight exemplifies the specification-driven tier, competing for premium commercial fit-outs through architectural customization capabilities. These three entities represent the competitive spectrum from scale-driven municipal contracting to margin-focused professional segment penetration.
| Leading Market Players |
|---|
| GS Group (GS LED) |
| Arlight |
| Optogan |
| LedEcoDom |
| Planeta Sid |
| Varton |
| LED Effect |
| RW Light |
| Era LED Light Technologies |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers anchored in Tatarstan and Moscow Oblast exercise pricing discipline through captive chip supply and municipal contract bundling, while private distributors compete on inventory proximity for spot procurement in bulb retrofit segments. This ownership split concentrates margin capture among integrated domestic players and fragments pricing power across fabless assemblers dependent on Asian packaged die imports.
Pricing Analysis
Margin tightening in standard LED fixtures reflects phosphor material cost volatility and rare earth export quota regimes. Three-tier pricing structure across premium architectural, standard commercial, and economy residential levels separates specification-driven payback calculations from replacement-cycle price sensitivity. Cost-down pressure accelerates as municipal energy service companies assume performance risk through subscription-based per-lumen-hour contracts. Retail chains and logistics operators in Saint Petersburg exhibit the least price sensitivity due to corporate sustainability mandates, while multi-unit residential buildings in Tatarstan and Moscow Oblast drive the most aggressive procurement cost minimization.
Supply Chain Analysis
Refurbishment flows for legacy sodium vapor luminaires remain underdeveloped, creating stranded asset risk for municipal maintenance crews. Wafer and chip supply concentrates in Taiwan, South Korea, and China, exposing Russian assemblers to logistics volatility and payment clearance friction. Phosphor materials for warm-white conversion layers draw from Chinese rare earth processing capacity, while driver electronics rest on Malaysian and Vietnamese packaging operations. Single-source vulnerability in semiconductor foundry access constitutes the dominant structural risk. Distribution runs through Tatarstan-based regional hubs serving Central and Volga Federal Districts, with direct municipal contracting bypassing wholesale channels for large-scale street lighting programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around players controlling upstream chip supply and municipal energy service relationships, with import substitution policies accelerating displacement of import-dependent assemblers lacking backward integration into driver electronics.
For Market Incumbents: Acquire optical design and thermal management engineering talent pools to offset capability scarcity in Russian technical programs. Secure Rosstandart fast-track certification pathways for locally manufactured components to reduce domestic competitor time-to-market advantages. Defensive consolidation should prioritize captive semiconductor packaging capacity and municipal ESCO partnership anchoring against emerging fabless entrants. For New Entrants and Emerging Players: Launch via subscription-based luminaire management contracts targeting Siberian Industrial Corridor mining extraction facilities with ruggedized high-bay specifications. The underpenetrated smart controls integration gap in Kemerovo and Krasnoyarsk regions offers white-space access, with extreme temperature tolerance requirements creating specification barriers to incumbent replication. Circadian rhythm tuning for healthcare and education verticals provides a second penetrable entry point. For Investors and Strategic Acquirers: Rosstandart fast-track certification queue volumes are the leading indicator that domestic packaging ventures are achieving scale velocity sufficient for platform consolidation. The five-to-ten year viability window favors vertically integrated producers with captive foundry relationships over distributors dependent on Asian chip imports. Acquisition targets should display in-house driver electronics development capability and established municipal ESCO contracting track records.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Reduces import dependency for power management ICs under federal localization mandates. |
| Municipal ESCO Partnership Formation | Captures guaranteed efficacy clause revenue through Moscow and Saint Petersburg street lighting modernization. |
| Siberian Industrial Corridor Penetration | Addresses untapped demand for IP-rated ruggedized high-bay systems in sub-zero extraction environments. |
| Rosstandart Fast-Track Certification Investment | Accelerates time-to-market for domestic packaging ventures competing against import-dependent assemblers. |
| Human-Centric Lighting Product Line Launch | Absorbs specification share in healthcare and education verticals requiring circadian rhythm tuning compliance. |
Research Approach
Independent corroboration across municipal procurement databases, semiconductor trade flow records, and GOST R certification filings underwrites the qualitative findings in this study. Primary interviews with fixture manufacturing plant managers, municipal energy service company procurement leads, Rosstandart compliance officers, and electrical installation contractor project directors combined with secondary validation from customs records, federal energy efficiency mandate documentation, and regional grid connection rule filings. Bottom-up triangulation across product type, application, technology, and end user segmentation dimensions anchored top-down market sizing.
Comparable-period anchoring linked historical sodium vapor infrastructure stock data to projected LED displacement rates across the analysis window. The forecast framework modeled product type segmentation by cost tier, application segmentation by customer sophistication, technology segmentation by maturity stage, and end user segmentation by procurement authority. CAGRs derived from efficacy threshold adoption curves and subscription-based contract penetration assumptions. Industry-specific inputs included federal import substitution policy implementation velocity and municipal modernization program budget allocation patterns.
The model assumes a particular technology adoption path; alternative pathways for quantum dot-enhanced and organic LED architectures would alter the outlook for premium segment margin pools. Forecasts reflect assumptions regarding Rosstandart certification streamlining effectiveness and rare earth element pricing stability. Practitioners should monitor municipal ESCO contract award volumes, driver electronics localization facility commissioning announcements, and phosphor material export quota regime adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Lighting Market
LED
Africa LED Lighting Market
LED
GCC LED Lighting Market
LED
France LED Lighting Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
Dot-Matrix LED Displays Market
LED
Japan Indoor LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
France Indoor LED Lighting Market
LED
LED Light Market
LED
Europe Outdoor LED Lighting Market
LED
US Outdoor LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
LED Power Supplies Market
LED
LED Chip Market
LED
LED Lighting Controllers Market