
 Middle East LED Lights Market | 2026-2036
Middle East LED Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East LED Lights Market Insights
Lighting-as-a-service and subscription-based maintenance packages is pivoting vendor revenue models away from one-time hardware sales. Signify (Philips) leverages its Interact platform to anchor recurring software revenue across Dubai's commercial towers. ams OSRAM AG sustains technology leadership through high-efficacy chip architectures for extreme desert climates. Al Nasser Group dominates local distribution channels with deep wholesaler relationships across Saudi Arabia and the UAE.
Light-emitting diode (LED) fixtures convert electrical current through semiconductor junctions into visible light with luminous efficacy exceeding 150 lumens per watt, serving as the dominant artificial illumination technology for energy-conscious commercial and municipal infrastructure. Indoor lighting occupies the largest revenue pool across Middle East hospitality and retail fit-outs, while smart lighting represents the fastest-expanding segment as building automation systems integrate occupancy sensing and daylight harvesting protocols. The technology dimension spans OLED panels for architectural accent applications and quantum dot-enhanced systems pushing color rendering indices above 90 for premium commercial environments.
Saudi Standards, Metrology and Quality Organization (SASO) mandates minimum efficacy thresholds and labeling requirements that filter low-performance imports from regional distribution channels. The UAE's Emirates Authority for Standardization and Metrology (ESMA) enforces ECAS certification for electrical safety and electromagnetic compatibility across LED product categories. Stakeholders must monitor how Gulf Cooperation Council harmonization of energy performance standards reshapes supplier qualification criteria and procurement specifications across public infrastructure tenders.
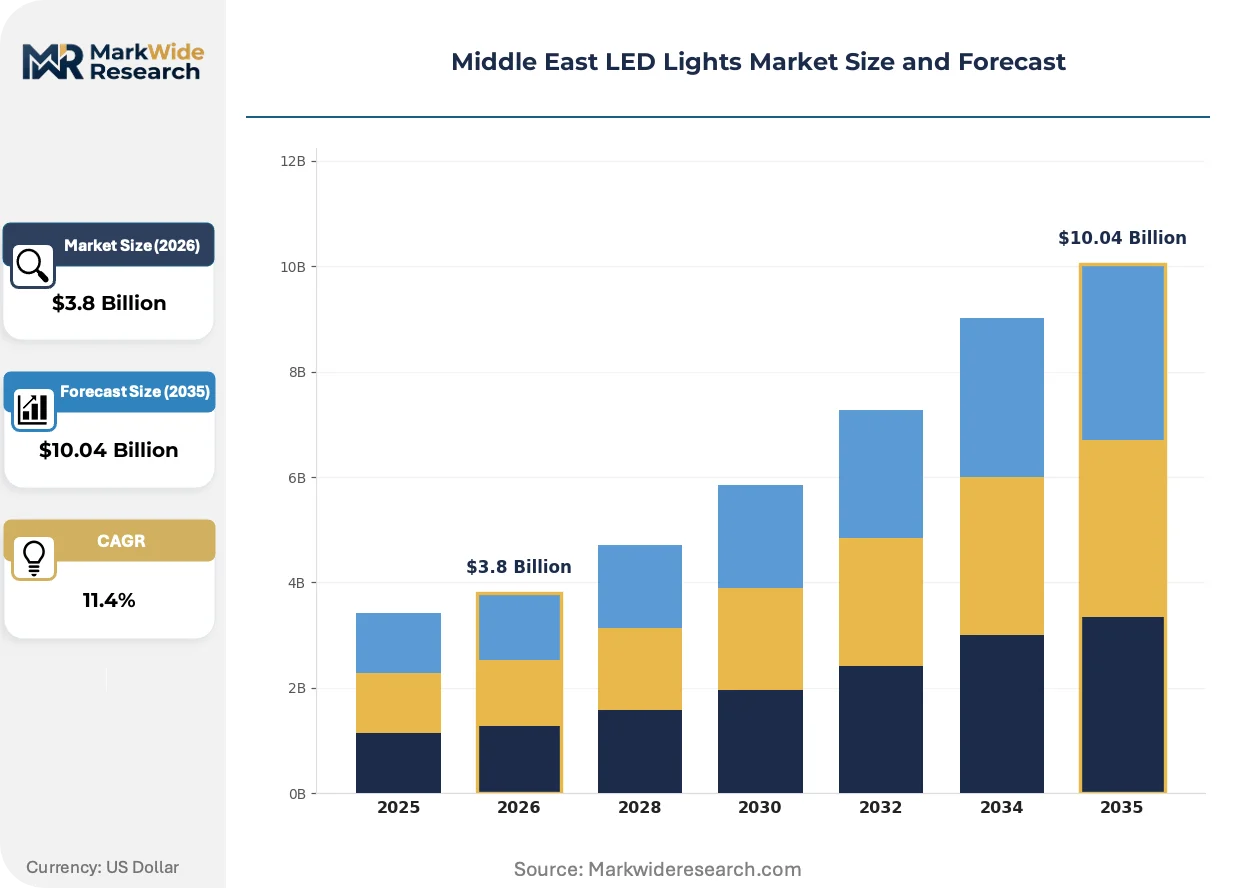
Market Dynamics
SASO efficacy mandates and ESMA certification requirements are compressing supplier margins while accelerating product turnover across Gulf commercial and municipal procurement channels.
Growth Catalysts
- SASO Energy Efficiency Mandates:Saudi Arabia's minimum efficacy thresholds filter low-performance imports, creating replacement cycles across existing installed bases.
- Smart City Infrastructure:Dubai's building automation integration drives demand for occupancy-sensing and daylight-harvesting protocols in commercial towers.
- Commercial Construction Corridor:UAE hospitality and retail fit-outs concentrate procurement volume for premium color-rendering fixtures.
Market Restraints
- Input Cost Volatility:Rare earth element pricing for phosphor materials creates margin pressure on domestic assemblers.
- Supply Concentration Risk:High-efficacy chip architectures depend on concentrated East Asian foundry capacity.
- Technical Limitation:Extreme desert thermal cycling degrades driver electronics faster than temperate climate benchmarks.
Strategic Opportunities
- Kuwait Municipal Modernization:Underpenetrated street lighting infrastructure offers tender volume for system integrators.
- Lighting-as-a-Service:Subscription maintenance packages pivot vendor revenue from hardware sales to recurring software streams.
- Quantum Dot Convergence:Color rendering indices above 90 unlock premium positioning in hospitality verticals.
Industry Challenges
- Certification Timeline Compression:ESMA electromagnetic compatibility testing creates six-month approval bottlenecks for new product introductions.
- Legacy System Integration:Building management protocol fragmentation forces custom middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East LED Lights Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Lighting, Outdoor Lighting, Automotive Lighting, Smart Lighting Technology: OLED, Quantum Dot, RGB, Dual-Color End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Signify (Philips), ams OSRAM AG, Acuity Brands Lighting, Cree Lighting, OPPLE Lighting, General Electric Lighting, LEDVANCE, Nichia Corporation, Al Nasser Group, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East LED Lights Market Trends and Innovations
Human-centric circadian lighting and connected fixture ecosystems are redefining value capture models across Middle East commercial and healthcare environments.
Human-centric lighting systems with tunable white and melanopic lux control is overtaking static color temperature fixtures in Dubai healthcare and education verticals. Hospital operators adopt circadian protocols to support patient recovery metrics. This technology is overtaking conventional specification standards in RFP documentation.
ESMA's ECAS certification expansion for networked lighting controls creates compliance layering for imported smart fixtures. Manufacturers must now submit separate electromagnetic compatibility and cybersecurity test suites. Commercial tower developers in Abu Dhabi delay procurement timelines to await harmonized Gulf Cooperation Council standards.
Performance-based service contracts with guaranteed energy savings clauses displace conventional capital expenditure purchases in Saudi municipal tenders. Facility managers transfer technology obsolescence risk to vendor balance sheets. This model concentrates in Riyadh district cooling and lighting bundled procurements.
Middle East LED Lights Market Segmentation
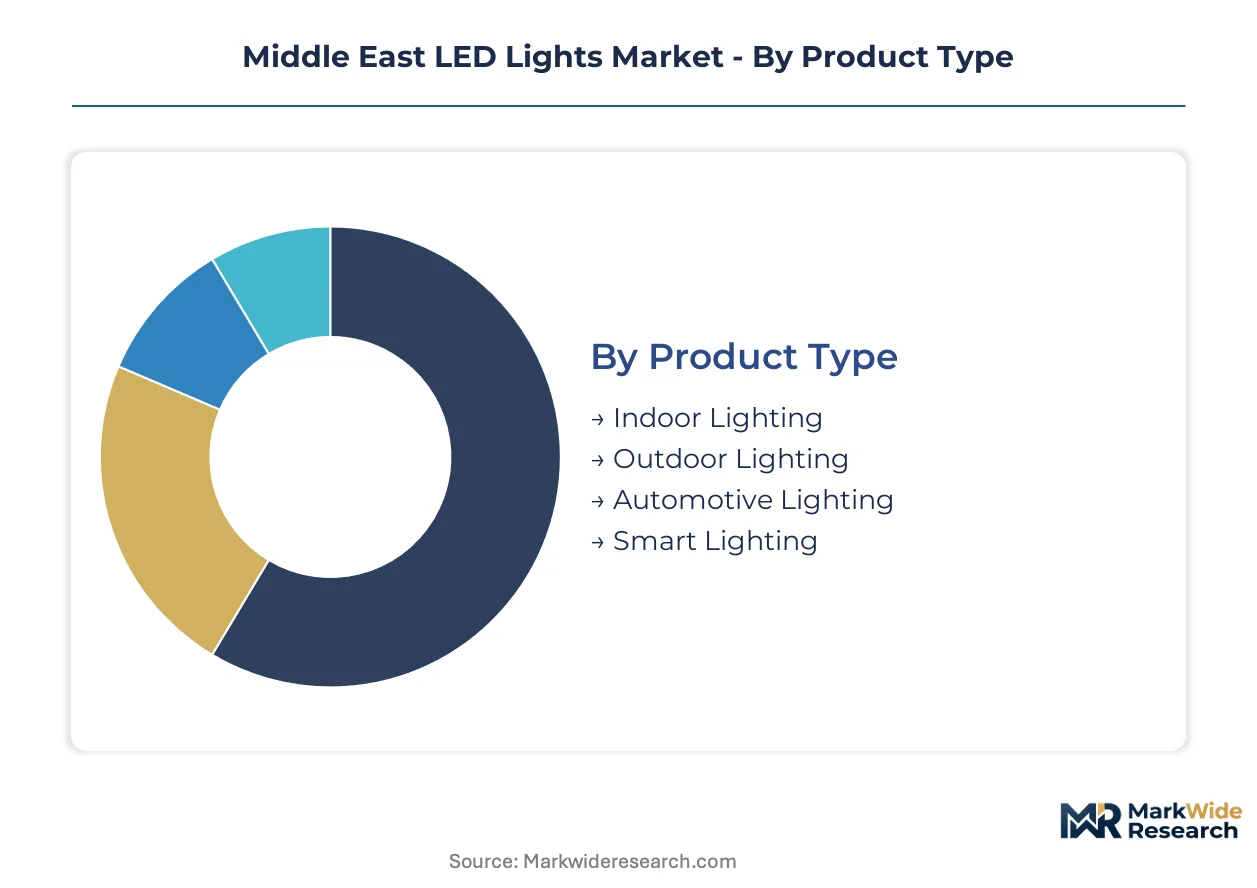
Segmentation in the Middle East LED market reveals how capital deployment, regulatory pressure, and infrastructure maturity create divergent investment profiles across product categories and channel structures.
Product Type:
Capital intensity varies sharply across installation environments, with outdoor infrastructure demanding the heaviest upfront commitment for thermal management and IP-rated enclosures.
- Indoor Lighting:Fixtures designed for climate-controlled environments prioritize color rendering and glare control over thermal resilience. Hospitality fit-outs across Dubai's commercial corridor drive specification for premium downlights and panel systems with CRI above 90.
- Smart Lighting:Connected systems integrate occupancy sensors, daylight harvesting controllers, and building automation protocols. Dubai's smart city mandates accelerate procurement for networked fixtures in commercial towers, though middleware customization extends deployment timelines.
- Outdoor Lighting:Street and area luminaires require die-cast aluminum housings and advanced driver protection against desert thermal cycling. Municipal tenders in Riyadh and Jeddah concentrate volume for high-efficacy roadway retrofits.
- Automotive Lighting:Headlamp and interior modules serve OEM assembly plants and aftermarket channels across the Gulf, with LED penetration now standard across premium vehicle segments.
Indoor lighting absorbs the bulk of installed capacity; smart lighting is expanding most quickly.
Technology:
Manufacturing complexity and material costs stratify technology segments, with quantum dot architectures commanding the steepest process investments.
- Quantum Dot:Nanocrystal-enhanced phosphors deliver color rendering indices exceeding 95 with precise spectral tuning. Premium hospitality and healthcare verticals in Abu Dhabi and Doha specify these systems for circadian lighting protocols.
- OLED:Organic electroluminescent panels enable ultra-thin form factors and uniform surface illumination without point-source glare. Architectural accent applications in luxury retail and museum environments concentrate niche demand.
- RGB:Multi-chip arrays enable dynamic color mixing for entertainment and branded environment applications. Hotel lobbies and retail facades across the UAE deploy tunable RGB systems for programmable scene settings.
- Dual-Color:Correlated color temperature switching between warm and cool white supports basic circadian functionality at lower cost points. Educational facilities and standard commercial offices specify these as entry-level human-centric alternatives.
Quantum dot systems command the highest unit economics; dual-color configurations are gaining share fastest in cost-sensitive institutional verticals.
End User:
Procurement sophistication and contract scale differentiate end-user segments, with commercial buyers leveraging the strongest negotiating leverage for performance guarantees.
- Commercial:Corporate offices, retail chains, and hospitality groups specify integrated lighting systems with energy performance contracting. Dubai's commercial construction corridor concentrates procurement volume for fit-out projects exceeding ten thousand fixtures.
- Institutional:Healthcare facilities, educational campuses, and government buildings prioritize circadian lighting and infection-control compatible designs. Saudi Arabia's hospital modernization programs drive tender volume for tunable white systems.
- Industrial:Manufacturing plants and logistics centers demand high-bay luminaires with extreme lumen packages and vibration resistance. Petrochemical facilities along the Gulf coast specify explosion-rated LED fixtures for hazardous area illumination.
- Residential:Individual consumers and small-scale developers purchase through retail and contractor channels, with smart home integration emerging as a specification factor in premium villa developments.
Commercial end-users absorb the bulk of procurement volume; institutional buyers are climbing the fastest as healthcare modernization accelerates.
Distribution Channel:
Channel economics reflect working capital requirements and technical support intensity, with direct sales demanding the deepest field engineering investments.
- Direct Sales:Manufacturer-led specification teams engage directly with project developers and MEP consultants for complex building automation integrations. Large commercial tower developments in Dubai and Riyadh prefer this channel for warranty alignment and commissioning support.
- Wholesalers:Bulk inventory holders serve electrical contractors and smaller project developers across Saudi Arabia's provincial construction markets. Al Nasser Group and comparable regional players dominate this tier through established credit relationships.
- Distributors:Authorized partners provide localized logistics and basic technical support for mid-scale commercial and industrial accounts. UAE-based distributors concentrate inventory for rapid response to contractor procurement schedules.
- Online Retail:E-commerce platforms capture residential replacement lamp sales and small fixture orders, with logistics networks improving delivery reliability across Gulf urban centers.
Wholesalers absorb the bulk of transaction volume; direct sales channels are expanding most quickly as smart lighting complexity demands manufacturer involvement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional production capacity concentrates in East Asian semiconductor foundries, while Gulf Cooperation Council states absorb the bulk of Middle Eastern consumption through infrastructure modernization and smart city deployments.
Saudi Arabia
SASO efficacy mandates and municipal retrofit programs drive replacement demand across Riyadh and Jeddah street lighting networks. The Saudi Standards, Metrology and Quality Organization enforces minimum luminous efficacy thresholds that filter low-performance imports. Eastern Province petrochemical facilities specify explosion-rated LED fixtures for hazardous area illumination, anchoring industrial procurement volume.
United Arab Emirates
Dubai's commercial construction corridor and hospitality fit-out cycles concentrate premium fixture demand for color rendering indices above 90. ESMA's ECAS certification requirements create six-month approval timelines for electromagnetic compatibility testing. Abu Dhabi commercial tower developers delay procurement to await harmonized Gulf Cooperation Council cybersecurity standards for networked lighting controls.
Kuwait
Underpenetrated municipal street lighting infrastructure offers tender volume for system integrators targeting modernization programs. The country's national standardization body aligns with Gulf Cooperation Council energy performance harmonization initiatives. Kuwait City district cooling and lighting bundled procurements concentrate performance-based service contract adoption.
Qatar
Healthcare facility modernization and education campus expansions prioritize circadian lighting with tunable white protocols. The Qatar General Organization for Standardization enforces electrical safety certifications for imported LED product categories. Doha luxury retail and museum environments specify OLED architectural accent applications for ultra-thin form factor requirements.
Oman
Industrial zone development and logistics center construction drive high-bay luminaire specifications with extreme lumen packages. The national standards and metrology organization implements Gulf Cooperation Council labeling requirements for energy-consuming products. Sohar Port free zone clusters concentrate warehousing and manufacturing facility lighting retrofits.
Middle East LED Lights Market Competitive Landscape
Top-tier vendors anchor premium specification channels through direct sales teams and building automation integration capabilities, while regional wholesalers and domestic assemblers occupy mid-market procurement tiers through established credit relationships and rapid logistics response. Market structure reflects a bifurcation between technology licensors with semiconductor chip architectures and system integrators with local commissioning expertise. Strategic archetypes include platform-anchored software vendors, desert-climate thermal management specialists, and Gulf distribution channel dominators. Competitive moves concentrate on lighting-as-a-service contract structures and backward integration into driver electronics manufacturing.
Among technology-anchored multinationals, Signify (Philips) and ams OSRAM AG exemplify divergent positioning strategies within premium-tier specification channels. Signify represents the platform-centric archetype through its Interact software ecosystem for commercial tower automation. ams OSRAM AG occupies a position emphasizing high-efficacy chip architectures engineered for extreme thermal cycling environments. Al Nasser Group anchors the regional distribution archetype through deep wholesaler relationships spanning Saudi Arabia and the UAE.
| Leading Market Players |
|---|
| Signify (Philips) |
| ams OSRAM AG |
| Acuity Brands Lighting |
| Cree Lighting |
| OPPLE Lighting |
| General Electric Lighting |
| LEDVANCE |
| Nichia Corporation |
| Al Nasser Group |
| Others |
Pricing and Supply Chain Analysis
Rare earth oxide pricing indices for europium and terbium phosphor materials cascade through Middle East LED supply chains, compressing assembler margins and forcing three-tier pricing stratification across premium certified, standard compliant, and economy import tiers.
Pricing Analysis
Margin tightening in economy-tier fixtures reflects SASO efficacy mandate compliance costs that filter uncertified imports from Saudi distribution channels. Three-tier pricing structure across premium, standard, and economy levels differentiates by ESMA certification status and thermal management specification, with hospitality developers in Dubai showing lowest price sensitivity for quantum dot-enhanced systems. Cost-down pressure on domestic assemblers accelerates as East Asian chip foundries capture value upstream.
Supply Chain Analysis
High-efficacy LED chip supply rests on concentrated Taiwanese and South Korean semiconductor foundry capacity, with phosphor deposition materials drawing from Chinese rare earth processing clusters. Aluminum die-cast housings and driver electronics feed from Chinese and Vietnamese component manufacturers. Single-source vulnerability in gallium nitride wafer supply creates procurement risk for desert-rated thermal architectures. Distribution runs through Al Nasser Group and comparable regional wholesalers holding inventory across Saudi provincial construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity constraints for high-efficacy chips prop pricing power for vendors with captive semiconductor supply, sustaining margin premiums across the analysis window.
For Market Incumbents: Lock in long-term wafer supply agreements with Taiwanese foundries before capacity allocation tightens further. Defend specification channels by embedding Interact-class software platforms into Dubai commercial tower RFPs, raising switching costs for building automation integrators. Deepen backward integration into driver electronics manufacturing to capture value lost to East Asian component suppliers.
For New Entrants and Emerging Players: Kuwaiti municipal street lighting authorities represent an underserved buyer archetype with limited incumbent relationships and tender volumes concentrated in Riyadh-adjacent modernization programs. Qatar healthcare facility operators seeking circadian lighting protocols offer white-space entry with lower certification backlog than UAE markets. Lead with performance-based service contracts that transfer technology obsolescence risk from facility managers to vendor balance sheets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distribution specialists with established credit relationships across Saudi Arabia and the UAE, as input cost volatility pressures smaller wholesaler margins. Long-term viability hinges on software platform ownership rather than hardware transaction economics. Watch for harmonized Gulf Cooperation Council cybersecurity standards as the inflection signal triggering accelerated smart lighting procurement in Abu Dhabi commercial developments.
| Strategic Initiative | Industry Significance |
|---|---|
| Lighting-as-a-Service Contract Expansion | Recurring revenue streams displace capital expenditure purchases in Saudi municipal tenders. |
| Backward Integration into Driver Electronics | Captive manufacturing reduces dependency on East Asian component suppliers facing rare earth volatility. |
| Quantum Dot Technology Licensing | Premium positioning in Abu Dhabi and Doha hospitality verticals commands specification priority. |
| Regional Distribution Channel Acquisition | Al Nasser-class wholesaler relationships accelerate penetration of Saudi provincial construction markets. |
| ESMA Certification Pre-Positioning | Six-month approval timelines create first-mover advantage for electromagnetic compatibility test suites. |
Research Methodology
Independent corroboration across primary interviews with MEP consultants, facility managers at Dubai commercial towers, procurement officers at Saudi municipal utilities, and lighting specification architects, combined with secondary validation through SASO efficacy standard filings, ESMA ECAS certification databases, and Gulf Cooperation Council trade flow records, underwrites the qualitative findings. Bottom-up fixture shipment estimates and top-down construction spend allocation triangulate market sizing.
Rate-of-change decomposition across the projection horizon segments volume by product type, technology architecture, end-user vertical, and distribution channel, with CAGRs derived from regression analysis of historical efficacy standard adoption curves and smart city infrastructure deployment schedules. Forecast inputs incorporate petrochemical facility expansion timelines along the Gulf coast and hospital modernization program announcements from Saudi Arabia's Ministry of Health.
Revisions become necessary when rare earth export restrictions materialize, Gulf Cooperation Council harmonization timelines shift, or desert thermal cycling failure rates diverge from temperate climate benchmarks. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Lighting Solution Market
LED
Led Video Walls Market
LED
LED Flip Chip Market
LED
LED Power Supplies Market
LED
LED Downlight Market
LED
East Africa LED Lighting Market
LED
UAE LED Lights Market
LED
LED Work Light Market
LED
LED Phosphor Materials Market
LED
LED Lighting Market
LED
Microled Market
LED
India Indoor LED Lighting Market
LED
Arrow LED Displays Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Global Waterproof LED Module Market