
 Mine Ventilation System Market | 2026-2036
Mine Ventilation System Market Size, Share, and Industry Trends Forecast 2026-2036
Mine Ventilation System Market Foresight
ISO 19434 certification for mining equipment safety classification is collapsing the supplier base for ventilation components in hazardous zones. Howden leverages its axial fan manufacturing scale across Nordic and Australian mining corridors. Twin City Fan & Blower anchors North American aftermarket service networks for underground coal operations. Epiroc competes through its mine automation ecosystem, integrating ventilation controls with drilling and haulage fleets.
A mine ventilation system comprises mechanical and natural airflow infrastructure designed to deliver fresh air, remove contaminants, and regulate thermal conditions in underground excavations, typically achieving face velocities of 0.25–1.5 m/s depending on activity intensity and pollutant generation rates. Primary ventilation systems utilizing main surface fans and dedicated intake-return shafts command the largest installed base, though auxiliary ventilation with ducted forcing fans is gaining share as mines adopt selective mining methods requiring flexible circuit reconfiguration. Active ventilation dominates capital expenditure, while control systems containing gas sensors and variable-frequency drives capture disproportionate margin pools through software-enabled optimization and predictive maintenance contracts.
OSHA's diesel particulate matter standard and Australia's Work Health and Safety Act impose continuous monitoring mandates that accelerate sensor deployment and automated damper controls. The EU's F-Gas Regulation restricts refrigerants used in deep-mine cooling systems, pushing vendors toward ammonia-based and water-chiller alternatives. Stakeholders must weigh capital intensity against regulatory compliance timelines when selecting between retrofit upgrades and full ventilation infrastructure replacement.
Market Dynamics
The transition from diesel-powered to battery-electric mining fleets is fundamentally recalibrating airflow engineering specifications across underground operations worldwide. This electrification shift eliminates diesel particulate matter generation at source, reducing ventilation volume requirements while simultaneously introducing new thermal management demands from battery cooling systems.
Growth Catalysts
- OSHA diesel particulate matter standards:Stricter occupational exposure limits in US underground metal and non-metal mines mandate enhanced ventilation infrastructure, driving capital deployment toward high-capacity exhaust systems and continuous monitoring arrays.
- Battery-electric vehicle adoption:Mining operators in Australia's hard-rock gold and copper districts are retrofitting ventilation circuits to accommodate reduced airflow needs alongside specialized cooling for battery thermal runaway risks.
- Depth extension projects:Chilean and Peruvian underground copper operations exceeding 1,000 meters vertical depth require refrigeration-grade ventilation systems to manage wet-bulb temperatures beyond human tolerance thresholds.
Market Restraints
- Steel and copper input volatility:Axial fan housings, ductwork, and motor windings depend on commodity metal prices that have fluctuated sharply, compressing fabrication margins and delaying project commitments.
- Supplier concentration in Nordic manufacturing:Critical axial fan production clusters in Sweden and Finland create geographic vulnerability to energy cost shocks and logistics disruptions affecting delivery timelines.
- Legacy shaft infrastructure limitations:Older mines in South Africa's Witwatersrand basin face physical constraints on intake-return shaft diameter that cap ventilation capacity regardless of surface fan upgrades.
Strategic Opportunities
- Indonesia nickel belt expansion:Sulawesi and Halmahera underground operations are greenfield developments where integrated ventilation-automation packages can bypass legacy retrofit constraints entirely.
- EU F-Gas Regulation phase-down:The refrigerant restriction timeline accelerates demand for ammonia-based and water-chiller cooling systems in deep European potash and salt mines seeking compliance pathways.
- Digital twin convergence:Ventilation control systems integrating computational fluid dynamics with real-time sensor networks enable predictive airflow optimization that reduces energy intensity by double-digit percentages.
Industry Challenges
- Ventilation engineer scarcity:Specialized expertise in thermodynamic modeling for deep-mine refrigeration is concentrated among retiring practitioners, with university mining engineering programs producing insufficient replacement capacity.
- ISO 19434 certification complexity:The safety classification framework for equipment in explosive atmospheres requires extensive third-party validation that extends product development cycles by 12-18 months.
- Legacy SCADA integration friction:Modern variable-frequency drive controls must interface with decades-old mine automation architectures, creating commissioning delays and interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine Ventilation System Market |
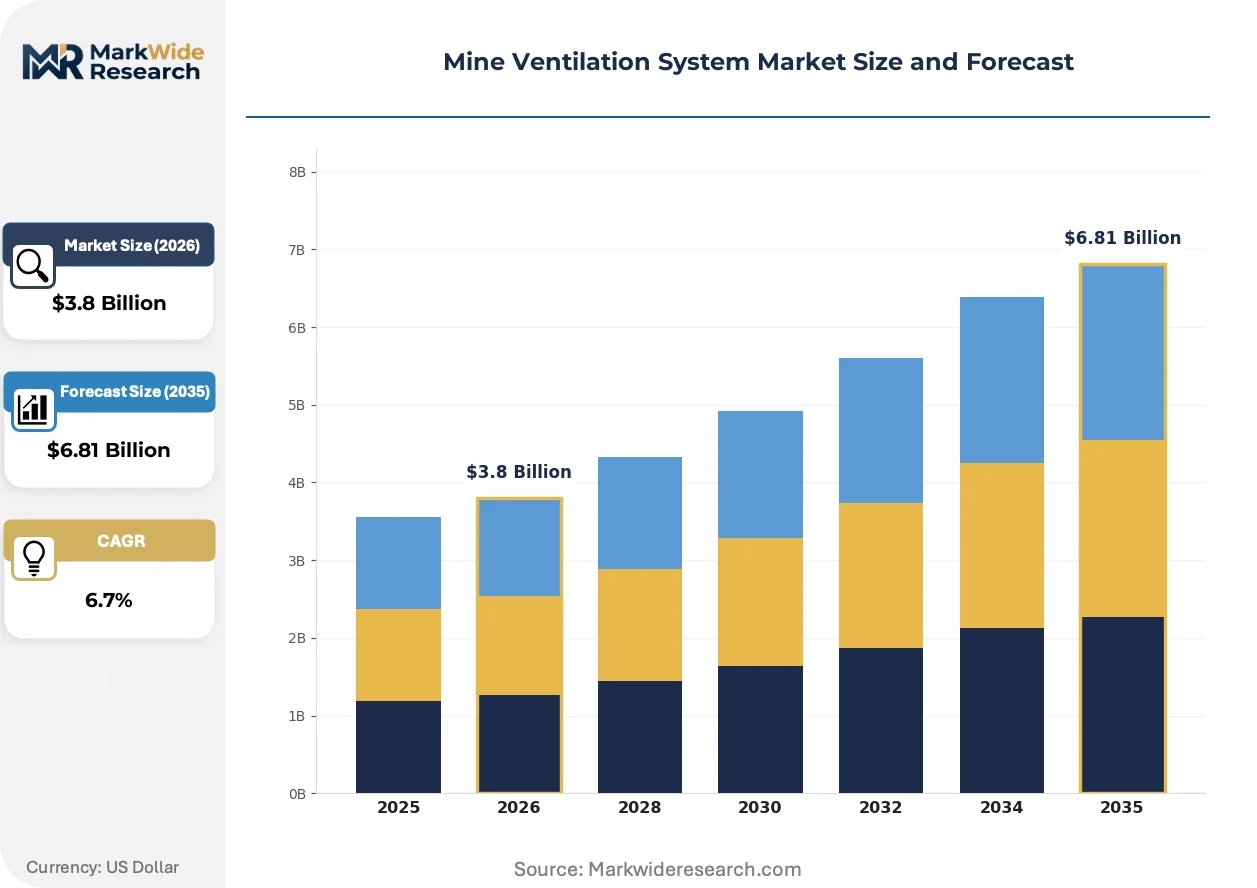
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active Ventilation, Passive Ventilation, Auxiliary Ventilation, Primary Ventilation Component: Fans, Ducting, Sensors, Control Systems End User: Coal Mines, Metal Mines, Mineral Mines, Oil Sands Application: Airflow Management, Gas Control, Heat Control, Dust Control |
| Companies Covered | ABB, Twin City Fan & Blower, Howden, Zitron, New York Blower, Epiroc, ABC Industries, Chicago Blower, TLT-Turbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine Ventilation System Market Shifts & Advancements
Real-time environmental sensing and autonomous damper control are converging to transform ventilation from fixed infrastructure into dynamically optimized utility networks. This intelligence layer is compressing energy consumption while tightening regulatory compliance.
On-demand ventilation using distributed gas sensor arrays and automated fan speed modulation is displacing constant-volume operation in advanced underground mines. Canadian base metal operators in Ontario's Sudbury Basin are deploying these systems at scale. The technology is displacing traditional ventilation-on-schedule practices that maintained full airflow regardless of actual contaminant generation, cutting electricity costs by substantial margins.
Australia's Work Health and Safety Act continuous monitoring mandates are accelerating sensor deployment and automated damper controls across Queensland and Western Australian operations. The legislation requires real-time diesel particulate matter tracking with automated ventilation response triggers. Deep gold mines in Kalgoorlie are retrofitting auxiliary fan circuits with networked carbon monoxide and nitrogen dioxide detectors to satisfy enforcement timelines.
Buying committees at major diversified miners are unbundling ventilation system procurement from mine construction contracts, creating standalone tender processes for controls and aftermarket service. This pattern separates capital equipment selection from EPC wrap arrangements. The behavior is most pronounced in Chilean copper operations where Codelco and Antofagasta Minerals now specify ventilation controls separately from shaft sinking contracts.
Mine Ventilation System Market Segmentation
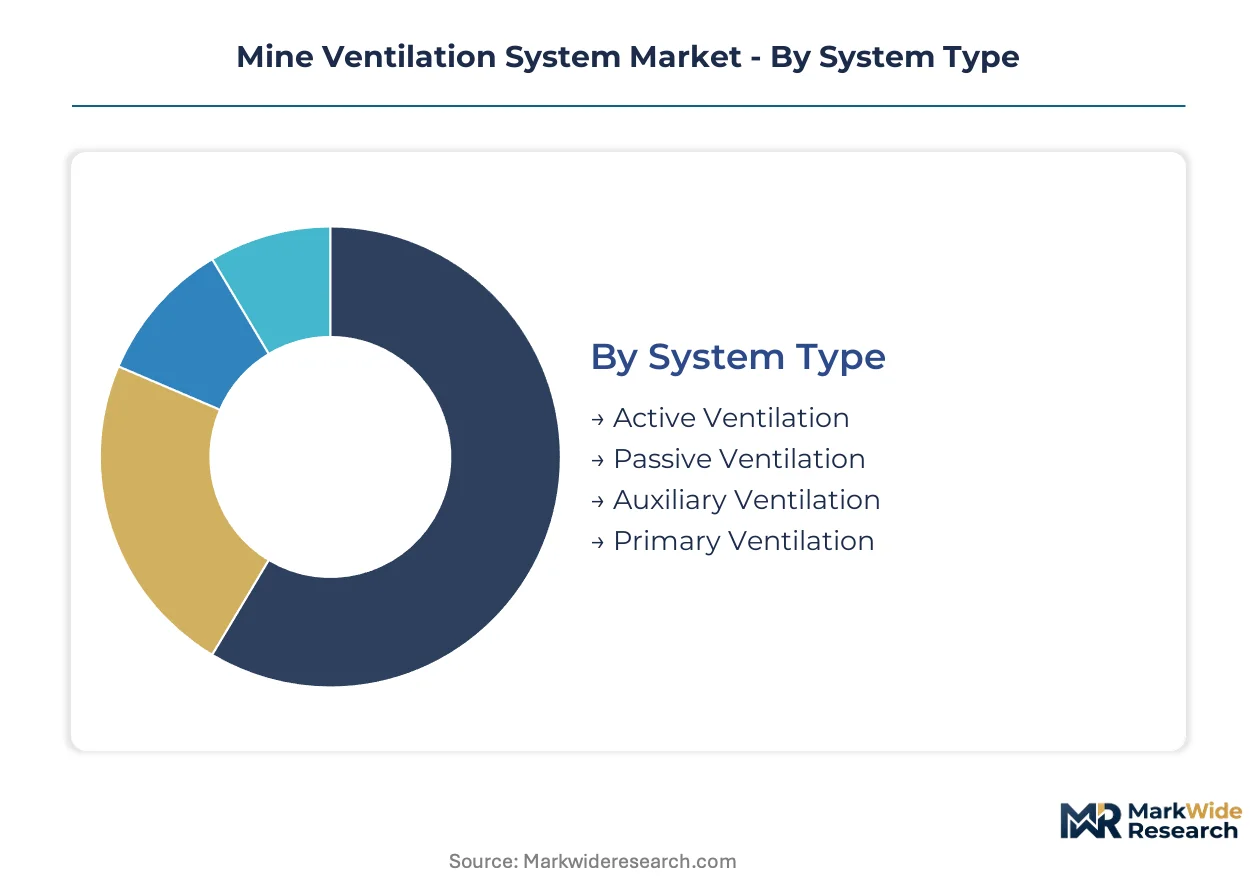
Mine ventilation procurement channels diverge sharply by system complexity and regulatory exposure. Capital-intensive primary installations flow through EPC contractors, while aftermarket components and controls increasingly bypass construction wraps for direct vendor relationships.
System Type:
Channel mix varies by deployment scale: full infrastructure projects route through mining contractors, whereas modular auxiliary systems increasingly sell direct to mine operators seeking operational flexibility.
- Active Ventilation:Mechanically driven airflow using surface and booster fans achieving face velocities up to 1.5 m/s, with variable-frequency drives enabling demand-responsive operation. Australian hard-rock gold and copper districts concentrate procurement for depth-extension cooling requirements under Work Health and Safety Act mandates. By volume, Active Ventilation leads. By growth pace, Auxiliary Ventilation is expanding most quickly.
- Primary Ventilation:Dedicated intake-return shafts with main surface fans forming the backbone ventilation circuit for entire mine operations. Chilean and Peruvian underground copper mines exceeding 1,000 meters depth drive specification for refrigeration-grade capacity to manage wet-bulb temperature thresholds.
- Passive Ventilation:Natural airflow leveraging thermal buoyancy and barometric pressure differentials without mechanical assistance, typically supplementing active systems in shallow workings or emergency scenarios.
- Auxiliary Ventilation:Ducted forcing fans delivering targeted airflow to development headings and stopes, gaining share as selective mining methods require flexible circuit reconfiguration.
Cost tier separation is pronounced: primary systems command capital budgets an order of magnitude above auxiliary packages, with payback periods driving procurement timing.
Component:
Application context determines margin structure: hardware components compete on fabrication scale, while control systems capture recurring revenue through software-enabled optimization contracts.
- Control Systems:Integrated gas sensors, variable-frequency drives, and automated damper networks enabling real-time airflow optimization. Australia's Work Health and Safety Act continuous monitoring mandates accelerate deployment across Queensland and Western Australian operations, with predictive maintenance contracts extending vendor relationships beyond initial sale.
- Fans:Axial and centrifugal designs ranging from auxiliary ducting units to main surface installations exceeding 5,000 kW capacity. Nordic manufacturing clusters in Sweden and Finland concentrate production for Australian and Chilean mining corridors.
- Sensors:Distributed arrays for diesel particulate matter, carbon monoxide, nitrogen dioxide, and methane detection triggering automated ventilation responses.
- Ducting:Flexible and rigid conduit systems for auxiliary ventilation circuits, with flame-resistant materials specified for coal operations under OSHA standards.
Maturity gradients separate the segments: fan and ducting procurement follows established engineering specifications, whereas control system selection increasingly depends on software integration capabilities and data analytics roadmaps.
End User:
Customer type shapes specification priorities: diversified miners emphasize total cost of ownership and automation integration, while single-commodity operators prioritize capital efficiency and regulatory compliance velocity.
- Metal Mines:Underground copper, gold, and nickel operations driving deepest ventilation requirements with refrigeration-grade thermal management. Indonesian nickel belt greenfield developments in Sulawesi and Halmahera specify integrated ventilation-automation packages without legacy retrofit constraints.
- Coal Mines:Underground and surface thermal coal operations with stringent methane control and dust suppression mandates. US Appalachian and Powder River Basin operations face OSHA diesel particulate matter standards requiring enhanced exhaust infrastructure.
- Mineral Mines:Potash, salt, and phosphate extraction with specialized corrosion-resistant equipment requirements for high-humidity environments.
- Oil Sands:In-situ extraction operations in Alberta's Athabasca deposit requiring ventilation for confined-space working and hydrogen sulfide management.
Supply concentration differs by customer: metal mine procurement concentrates among Nordic and Australian equipment vendors, while coal operations sustain North American aftermarket service networks.
Application:
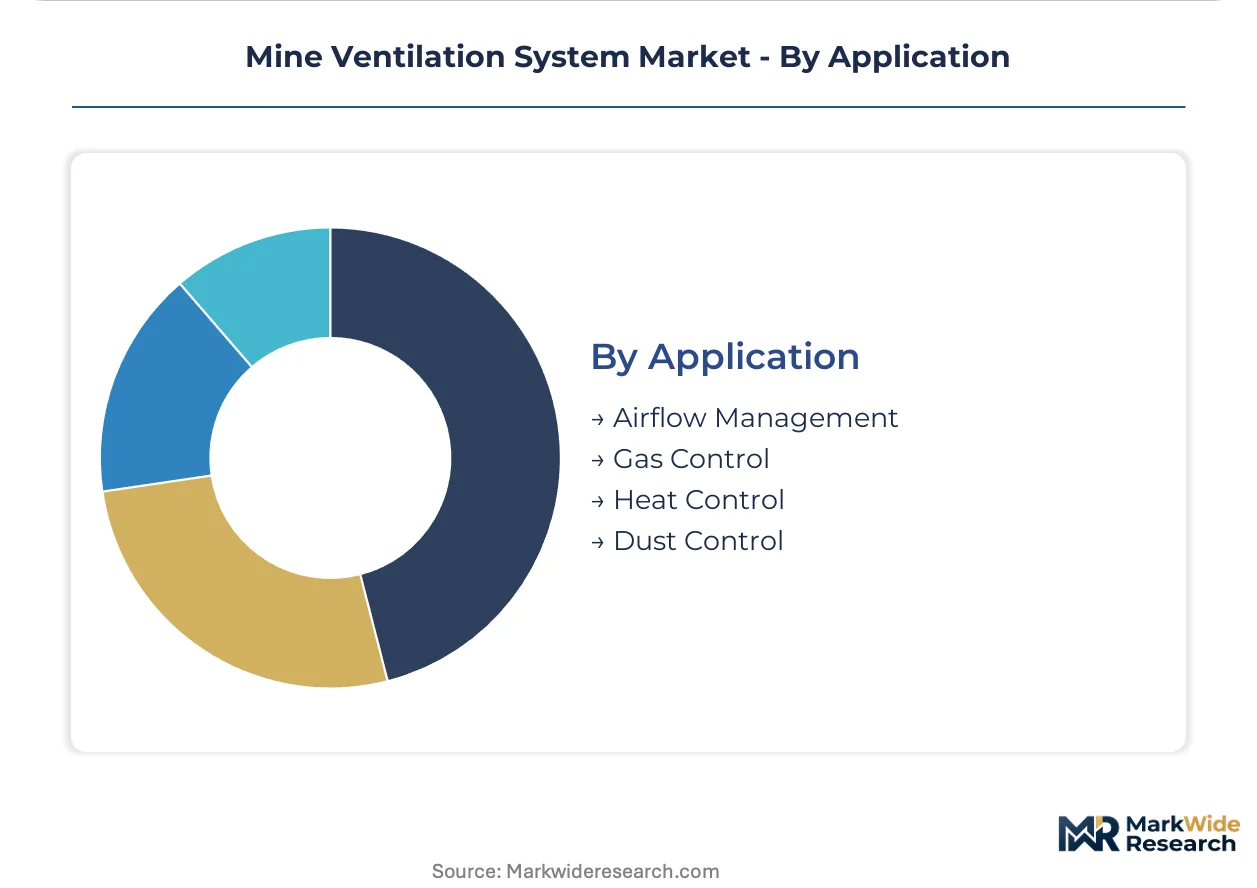
Volume distribution reflects operational intensity: airflow management commands the largest installed base, while gas control captures disproportionate capital allocation due to regulatory enforcement timelines.
- Airflow Management:Primary ventilation circuit design and auxiliary distribution ensuring adequate fresh air delivery to all working faces. Deep South African gold mines in the Witwatersrand basin face physical shaft diameter constraints that cap capacity regardless of surface fan upgrades.
- Gas Control:Methane, carbon monoxide, and nitrogen dioxide detection and dilution systems with automated emergency response protocols. EU F-Gas Regulation refrigerant restrictions push European potash mines toward ammonia-based cooling alternatives.
- Heat Control:Refrigeration and cooling systems managing wet-bulb temperatures in deep operations exceeding human tolerance thresholds without thermal intervention.
- Dust Control:Particulate suppression through ventilation velocity management and filtration, with diesel particulate matter standards driving sensor deployment in US metal and non-metal mines.
Technology substitution is reshaping priority rankings: battery-electric vehicle adoption is reducing diesel particulate matter generation and shifting investment toward battery thermal management and reduced overall airflow volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA's diesel particulate matter standards and Australia's Work Health and Safety Act continuous monitoring mandates are accelerating ventilation infrastructure deployment across underground mining corridors worldwide. Regulatory enforcement timelines in Chile and Peru are compressing procurement cycles for refrigeration-grade systems. Depth extension projects in multiple jurisdictions are recalibrating thermal management specifications.
Australia
Hard-rock gold and copper districts in Queensland and Western Australia are retrofitting ventilation circuits for battery-electric vehicle thermal management. The country's Work Health and Safety Act mandates real-time diesel particulate matter tracking with automated response triggers. Kalgoorlie deep gold operations are installing networked carbon monoxide and nitrogen dioxide detectors to satisfy enforcement timelines.
Chile
Underground copper mines exceeding 1,000 meters vertical depth require refrigeration-grade ventilation systems for wet-bulb temperature control. Codelco and Antofagasta Minerals now specify ventilation controls separately from shaft sinking contracts. The Atacama Desert mining corridor is deploying integrated ventilation-automation packages for new depth extensions.
Peru
Underground copper operations are expanding ventilation infrastructure to comply with stricter occupational exposure limits for diesel particulate matter. The country's mining regulator enforces continuous monitoring mandates that accelerate sensor deployment. The Andean highland mining belt is retrofitting auxiliary fan circuits with automated damper controls.
United States
Underground metal and non-metal mines face OSHA diesel particulate matter standards mandating enhanced exhaust infrastructure. Appalachian and Powder River Basin coal operations require high-capacity exhaust systems and continuous monitoring arrays. US procurement is shifting toward standalone tender processes for controls and aftermarket service unbundled from mine construction contracts.
Indonesia
Sulawesi and Halmahera underground nickel operations are greenfield developments specifying integrated ventilation-automation packages without legacy retrofit constraints. The country's mineral export policies are accelerating underground mine development. The Indonesian nickel belt is bypassing retrofit limitations entirely through new-build ventilation infrastructure.
Mine Ventilation System Market Competitive Landscape
Listed leaders compete with private specialists across axial fan manufacturing and ventilation controls integration. The supplier base concentrates around Nordic manufacturing clusters for heavy-duty fan production and North American service networks for aftermarket support. Three archetypes dominate: scale-driven axial fan fabricators, automation-integrated system providers, and regional aftermarket service specialists. Competitive moves center on certification compliance velocity and geographic corridor anchoring rather than price-based displacement.
Within the scale-driven tier, Howden and TLT-Turbo exemplify Nordic-based manufacturing concentration for Australian and Chilean mining corridors. Twin City Fan & Blower occupies a position among North American aftermarket service networks for underground coal operations. Epiroc represents the automation-integrated archetype, with its mine ventilation controls sitting within broader drilling and haulage fleet ecosystems.
| Leading Market Players |
|---|
| ABB |
| Twin City Fan & Blower |
| Howden |
| Zitron |
| New York Blower |
| Epiroc |
| ABC Industries |
| Chicago Blower |
| TLT-Turbo |
| Others |
Supply & Pricing Matrix
Axial fan manufacturing scale in Sweden and Finland anchors cost floors for ventilation infrastructure across Australian and Chilean mining corridors, with Nordic energy costs and capacity utilization directly shaping price bands for heavy-duty surface installations. Steel and copper input volatility propagates through fabrication margins, compressing supplier pricing power while procurement committees at diversified miners unbundle controls from EPC contracts to extract standalone value.
Pricing Analysis
Certification level (ISO 19434 for explosive atmospheres) creates the primary spread between premium and standard tiers, with third-party validation extending product development cycles and embedding compliance costs into quoted pricing. Project-based contracting dominates capital equipment, while control systems capture recurring revenue through predictive maintenance subscriptions. Cost compression in auxiliary fan segments intensifies as Chinese manufacturers enter ducted forcing fan markets. Junior miners and single-commodity operators exhibit highest price sensitivity, prioritizing capital efficiency over automation integration.
Supply Chain Analysis
Baltic Sea port congestion and Nordic electricity grid constraints constitute the critical chokepoint for axial fan delivery timelines to Australian and South American mining corridors. Manufacturing concentrates in Sweden, Finland, and Germany for heavy-duty fan assemblies, with motor windings and VFD controllers drawing from Chinese and South Korean electronics clusters. Steel plate and copper winding supply volatility remains the dominant structural risk. Distribution runs through mining contractors for primary infrastructure and direct vendor relationships for aftermarket controls and sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Codelco, Antofagasta Minerals, and Australian diversified miners separate ventilation controls from shaft sinking contracts, fragmenting procurement across standalone tender processes. This unbundling shifts negotiation leverage toward operators with sufficient engineering staff to specify and integrate components independently.
For Market Incumbents: Fortify certification velocity as the primary defensive moat, compressing ISO 19434 validation timelines to outpace emerging competitors from low-cost manufacturing jurisdictions. Anchor aftermarket service networks in North American coal corridors where Twin City Fan & Blower has established technician density, creating switching costs that offset price pressure from unbundled procurement. Deepen backward integration into VFD controller assembly to capture margin pools migrating from hardware to software-enabled optimization. For New Entrants and Emerging Players: Differentiate on battery-thermal management integration as battery-electric vehicle adoption recalibrates airflow engineering specifications. Target Indonesian nickel belt greenfield developments in Sulawesi and Halmahera where integrated ventilation-automation packages face no legacy SCADA retrofit constraints. Pursue direct relationships with mine operators rather than EPC channel dependence, leveraging software-native control architectures as the go-to-market wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors control system specialists with embedded software revenue over pure hardware fabricators exposed to commodity metal volatility. Long-term viability rests on predictive maintenance contract attach rates and digital twin integration capabilities. Acquisition targets should demonstrate refrigerant-transition readiness for EU F-Gas Regulation compliance and ammonia-based cooling system deployment. Watch battery-electric vehicle penetration rates in Australian hard-rock districts as the inflection signal for ventilation volume demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19434 Certification Acceleration | Third-party validation compression creates 12-18 month product development advantage over emerging competitors. |
| Backward Integration into VFD Assembly | In-house controller production captures margin pools shifting from hardware to software-enabled optimization contracts. |
| Digital Twin Platform Development | Computational fluid dynamics integration with real-time sensor networks enables double-digit energy intensity reduction. |
| Ammonia-Based Cooling System Transition | EU F-Gas Regulation compliance pathway secures positioning in European potash and salt mine refrigeration markets. |
| Indonesian Greenfield Market Entry | Sulawesi and Halmahera nickel belt developments specify integrated packages without legacy SCADA integration friction. |
Research Methodology
Operator-level perspectives from mine ventilation engineers, EPC procurement directors, aftermarket service managers, and mining contractor project controllers anchored the qualitative base for this analysis. Primary fieldwork across Australian hard-rock gold operations, Chilean copper depth extensions, and Indonesian nickel belt greenfields was cross-referenced with secondary validation from equipment supplier technical documentation, mining engineering journals, and regulatory filings with OSHA and Australia's Work Health and Safety authorities. Bottom-up installation counts and top-down capital expenditure estimates were triangulated to establish market sizing boundaries.
Sensitivity analysis across commodity metal price scenarios and regulatory enforcement timelines shaped the analytical framework for projections across the modeling period. Segmentation dimensions include system type (primary, auxiliary, control), component category (fans, sensors, ducting, automation), end-user commodity (copper, gold, nickel, coal), and application function (airflow, gas, heat, dust management). CAGRs were derived from installed base growth adjusted for technology substitution effects, with battery-electric vehicle penetration and refrigeration-grade cooling demand as mine-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained copper price levels, Nordic manufacturing cost stability, or OSHA enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding electrification pace and depth extension project commitments. Practitioners should keep alternative scenarios live as battery-thermal management specifications and EU F-Gas Regulation phase-down timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Air Core Drilling Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Mining Drill Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Logging Cable Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Asia Pacific Mining Equipment Market