
 Saudi Arabia Building Thermal Insulation Market | 2026-2036
Saudi Arabia Building Thermal Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Building Thermal Insulation Market Analytics
Premium-performance insulation specification is rotating through Saudi Arabia's construction procurement channels. Owens Corning leverages its mineral wool technology leadership to anchor high-rise commercial specifications in Riyadh. Saint-Gobain sustains broad distribution across the Kingdom's contractor networks. Knauf Insulation specializes in glass mineral wool systems tailored to Saudi Building Code thermal resistance benchmarks.
Saudi Arabia building thermal insulation comprises engineered materials—mineral fibers, rigid foams, or blown cellulose—manufactured to declared thermal conductivity values measured in W/m·K and installed to achieve specified R-values that reduce conductive heat flow through building envelopes. The primary purpose is to limit cooling energy consumption in a climate where ambient temperatures routinely exceed 45°C for extended periods. Fiberglass insulation occupies the largest installed base due to contractor familiarity and cost predictability across residential and commercial volumes. Spray foam commands premium positioning in complex roof geometries and industrial facilities where air sealing integration drives specification value. Rigid foam board extends into exterior insulation finish systems for commercial facades where space constraints limit cavity depths.
SFDA and SASO standards govern material safety declarations and product conformity marking for insulation materials distributed within the Kingdom. The Saudi Building Code, administered by the National Committee for Building Code, mandates minimum thermal transmittance values that directly determine insulation thickness and material selection in permit approvals. Municipal building departments in Riyadh, Jeddah, and Dammam enforce these standards through construction inspection protocols. Stakeholders must monitor evolving green building certification adoption through the Saudi Green Building Forum and corresponding specification tier migrations that reward lower embodied-carbon insulation alternatives.
Market Dynamics
Saudi Building Code thermal transmittance mandates are compressing specification cycles across Riyadh's commercial development pipeline. Contractors now front-load insulation decisions during schematic design phases to secure municipal permit pre-approvals.
Growth Catalysts
- Saudi Building Code enforcement:Municipal building departments in Riyadh, Jeddah, and Dammam now require declared thermal conductivity values at permit submission. This regulatory pressure accelerates material substitution toward higher-performance mineral wool systems.
- Central Region construction velocity:The Riyadh metropolitan corridor accounts for disproportionate specification volume as government-backed giga-projects advance through procurement channels. Developer concentration here creates demand pull for standardized thermal envelope packages.
- Glass mineral wool technology maturation:Knauf Insulation and comparable suppliers have calibrated product lines to SASO conformity marking requirements. This technical readiness reduces contractor adoption friction in residential mid-rise segments.
Market Restraints
- Petrochemical feedstock volatility:Rigid foam board production depends on polyisocyanurate and expanded polystyrene precursors tied to regional olefin pricing. This input cost exposure compresses margin predictability for system integrators serving commercial facade contracts.
- Contractor capability concentration:Spray foam installation expertise clusters in Jeddah and Dammam industrial zones. Geographic scarcity of certified applicators limits specification uptake in secondary cities across the Asir and Tabuk regions.
- Fiberglass incumbent lock-in:Decades of contractor familiarity with batt installation techniques create switching costs. This technical path dependency slows displacement even where mineral wool delivers superior thermal resistance per unit thickness.
Strategic Opportunities
- Eastern Province industrial retrofit:Petrochemical facilities in Jubail Industrial City present underpenetrated demand for high-temperature pipe and vessel insulation. Process energy efficiency mandates from Saudi Aramco suppliers are accelerating specification reviews.
- Saudi Green Building Forum certification tier:Projects pursuing enhanced sustainability ratings gain access to preferential financing through national development funds. This incentive structure rewards lower-embodied-carbon insulation alternatives in competitive bidding.
- Prefabricated envelope panel integration:Modular construction suppliers are consolidating insulation, air barrier, and cladding layers in factory conditions. This channel innovation reduces field installation variability for hospital and data center projects.
Industry Challenges
- Thermal bridging analysis capability gap:Few Saudi engineering consultancies maintain in-house computational fluid dynamics expertise for envelope performance modeling. This skill scarcity delays optimized insulation specification in complex geometries.
- SASO product conformity timeline:New material introductions require extended laboratory testing protocols for SFDA safety declarations. Certification delays compress available construction windows for fast-track developments.
- Multisystem integration complexity:Insulation performance depends on coordination with vapor retarders, air barriers, and structural connections. Interface detailing errors in field conditions undermine declared R-values in building commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Building Thermal Insulation Market |
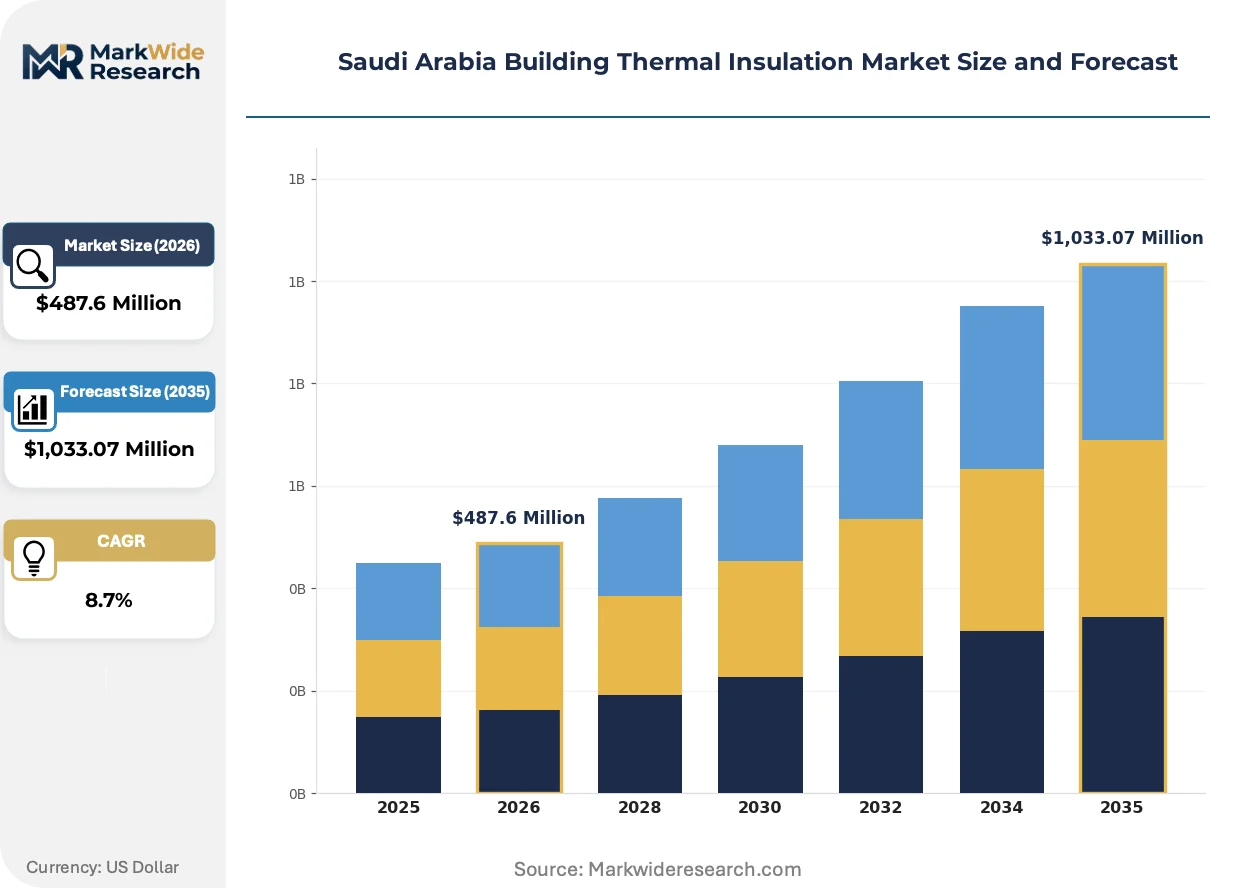
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass Insulation, Foam Board, Cellulose Insulation, Spray Foam Installation Method: Batts & Rolls, Blown-In, Spray Applied, Rigid Board End User: Residential Buildings, Commercial Construction, Industrial Facilities, Infrastructure Projects Application: Exterior Insulation, Roof Insulation, Wall Insulation, Floor Insulation |
| Companies Covered | Saudi Rockwool Factory, Owens Corning, Saint-Gobain, BASF Saudi Arabia, Rockwool International, Knauf Insulation, Arabian Fiberglass Insulation Company, Kingspan Insulation, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Building Thermal Insulation Market Evolving Landscape
Specification methodology is pivoting from prescriptive R-value compliance toward whole-envelope thermal performance modeling. This analytical shift rewards materials suppliers capable of delivering calibrated conductivity data and system integration support.
Aerogel-enhanced blanket systems are bifurcating the premium insulation segment. These silica-based materials deliver thermal conductivity below 0.020 W/m·K in compressed thickness profiles. Hospital and laboratory developers in Riyadh are specifying aerogel for space-constrained roof assemblies where traditional mineral wool would exceed structural load limits. This technology is bifurcating project portfolios into standard mineral wool specifications versus ultra-thin premium systems with compressed payback calculations.
SASO technical regulations for construction materials are tightening declared-performance documentation requirements. Manufacturers must now submit third-party thermal conductivity testing from accredited laboratories for product conformity marking renewal. This policy shift elevates quality assurance costs for smaller regional suppliers while reinforcing specification preference for established mineral wool and rigid foam producers with in-house metrology capabilities. The commercial high-rise segment is responding by consolidating approved vendor lists to reduce compliance verification burden.
Developer procurement departments are consolidating insulation specification authority from general contractors to envelope consultants. This organizational shift concentrates material selection decisions with firms capable of integrated thermal-hygrostatic modeling. The transition is most visible in Riyadh's giga-project developments where single-source envelope performance warranties are replacing fragmented trade subcontracting. Consultants now specify complete systems rather than discrete insulation products, compressing supplier direct access to decision-makers.
Saudi Arabia Building Thermal Insulation Market Segmentation
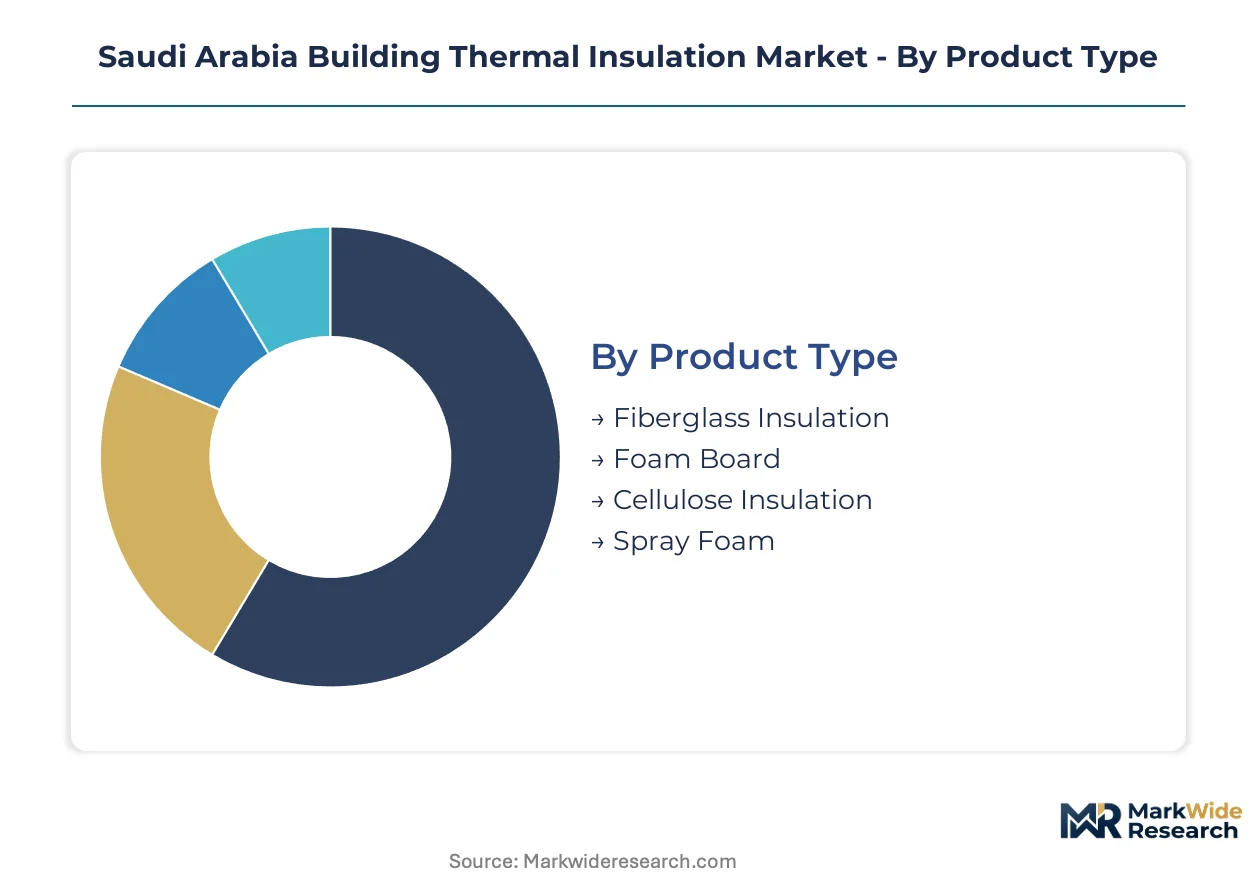
Segmentation in Saudi Arabia's building thermal insulation market reveals how SASO conformity marking and Saudi Building Code enforcement reshape procurement patterns across material categories. Contractors navigate distinct compliance pathways depending on product chemistry and installation methodology.
Product Type:
SASO technical regulations differentiate thermal conductivity documentation requirements by material chemistry, with mineral fiber systems facing distinct laboratory protocols from hydrocarbon-based foams.
- Fiberglass Insulation:Glass fiber batts and loose-fill materials dominate contractor familiarity across Riyadh residential developments. Batt installation techniques reduce training costs for mid-rise apartment builders in the Central Region, though thermal bridging at studs limits performance in high-performance envelopes.
- Foam Board:Rigid polyisocyanurate and expanded polystyrene panels deliver compressive strength for commercial facade systems where cavity depths are constrained. Petrochemical feedstock volatility from regional olefin pricing compresses margin predictability for system integrators serving Jeddah high-rise contracts.
- Cellulose Insulation:Recycled fiber blown-in systems face extended SFDA safety declaration timelines for fire-retardant chemical verification.
- Spray Foam:Polyurethane systems command premium positioning where air sealing integration drives specification value in complex roof geometries.
Fiberglass handles the majority of throughput; foam board is expanding most quickly on share as commercial facade specifications tighten.
Installation Method:
Contractor capability concentration across Saudi Arabia's secondary cities creates geographic segmentation in installation methodology adoption.
- Batts & Rolls:Pre-cut fiberglass segments install through friction-fit or staple attachment in wood-framed assemblies. Decades of technique standardization across Saudi contractor networks entrenches this method in volume residential construction despite thermal bridging limitations.
- Blown-In:Loose-fill cellulose and fiberglass pneumatic installation achieves higher coverage ratios in irregular attic geometries. Equipment rental availability concentrates in Riyadh and Jeddah metropolitan zones, restricting uptake in Asir and Tabuk regional markets.
- Spray Applied:Polyurethane foam requires certified applicator networks that cluster in Dammam industrial corridors.
- Rigid Board:Factory-cut panels demand precise substrate preparation and mechanical fastening expertise.
Batts and rolls anchor volume deployment; spray applied methods are gaining share fastest as air barrier integration requirements intensify.
End User:
Giga-project procurement concentration in the Riyadh metropolitan corridor concentrates specification authority by end-user category.
- Residential Buildings:Mid-rise apartment developments across Riyadh's northern expansion zones standardize on mineral wool systems meeting Saudi Building Code thermal transmittance minimums. Developer procurement departments consolidate insulation decisions during schematic design phases to secure municipal permit pre-approvals.
- Commercial Construction:High-rise office and retail envelopes in Jeddah's central business district specify integrated thermal-hygrostatic systems with single-source performance warranties. Envelope consultants now control material selection, compressing supplier direct access.
- Industrial Facilities:Petrochemical complexes in Jubail Industrial City present underpenetrated demand for high-temperature pipe and vessel insulation.
- Infrastructure Projects:Transportation and utility construction specifies insulation for mechanical systems and buried pipelines.
Residential buildings process the greatest material volume; commercial construction shows the steepest specification upgrade trajectory.
Application:
Climate load distribution across Saudi Arabia's envelope surfaces drives differential insulation performance requirements by application zone.
- Roof Insulation:Ceiling assemblies face the most severe thermal load in a climate where ambient temperatures exceed 45°C for extended periods. Aerogel-enhanced blanket systems are bifurcating the premium segment for space-constrained hospital and laboratory developments where traditional mineral wool would exceed structural load limits.
- Wall Insulation:Cavity fill and exterior insulation finish systems dominate commercial facade specifications across Riyadh and Jeddah. Municipal building departments enforce declared thermal conductivity values at permit submission, accelerating material substitution toward higher-performance mineral wool.
- Exterior Insulation:Continuous insulation outboard of structural frames eliminates thermal bridging in high-performance envelopes.
- Floor Insulation:Slab-edge and under-slab applications address conductive heat loss in conditioned basements and plenums.
Roof insulation commands the highest performance premiums; wall insulation processes the largest cumulative square meterage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's building thermal insulation sector maintains a narrow trade surplus, with mineral wool exports to GCC neighbors offsetting imports of specialized rigid foam systems. Domestic production capacity concentrates in the Central and Eastern regions, reducing import dependency for standard-grade materials.
Riyadh
Government-backed giga-projects drive specification volume across the metropolitan corridor. Municipal building departments enforce Saudi Building Code thermal transmittance minimums through permit pre-approval protocols. Developer procurement departments consolidate insulation decisions during schematic design phases to secure construction timelines.
Eastern Province
Petrochemical facilities in Jubail Industrial City generate underpenetrated demand for high-temperature pipe and vessel insulation. Process energy efficiency mandates from Saudi Aramco suppliers accelerate specification reviews for industrial applications. Local mineral wool production serves regional commercial construction with reduced logistics costs.
Western Region
Jeddah's central business district specifies integrated thermal-hygrostatic systems for high-rise envelopes. Envelope consultants control material selection, compressing supplier direct access to decision-makers. Spray foam installation expertise clusters here, creating geographic capability concentration.
NEOM Northwest
Modular construction suppliers consolidate insulation, air barrier, and cladding layers in factory conditions for this greenfield development. Prefabricated envelope panel integration reduces field installation variability for hospital and data center projects. SASO conformity marking requirements shape approved vendor list consolidation.
Saudi Arabia Building Thermal Insulation Market Competitive Landscape
Concentration sits with multinational mineral wool specialists and domestic fiberglass producers serving volume residential construction. The vendor base organizes around three strategic archetypes: technology-led multinationals with calibrated product lines to Saudi Building Code benchmarks, regional fiberglass incumbents leveraging contractor familiarity, and rigid foam suppliers exposed to petrochemical feedstock volatility. Capacity expansion and strategic partnerships represent the dominant competitive moves, with envelope system integration emerging as a differentiation vector.
Among technology-led multinationals, Owens Corning and Saint-Gobain exemplify archetypes capable of delivering calibrated conductivity data and system integration support. Saudi Rockwool Factory anchors domestic mineral wool production, occupying a position within the regional supply base that reduces import dependency for standard-grade materials. These three represent the competitive core around which specification authority concentrates in Riyadh's commercial development pipeline.
| Leading Market Players |
|---|
| Saudi Rockwool Factory |
| Owens Corning |
| Saint-Gobain |
| BASF Saudi Arabia |
| Rockwool International |
| Knauf Insulation |
| Arabian Fiberglass Insulation Company |
| Kingspan Insulation |
| Sika AG |
| Others |
Value Network & Pricing Analysis
SASO product conformity marking gates both supplier qualification and price tiering simultaneously. Contractors face extended laboratory testing timelines that compress construction windows, forcing premium payments for pre-certified materials. Municipal permit pre-approval protocols in Riyadh and Jeddah accelerate demand for documented thermal conductivity values, bifurcating procurement between compliant premiums and uncertified discounts.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure across petrochemical facility insulation packages. Price differentiation separates SASO-certified mineral wool systems from uncertified alternatives, with volume scale and brand premium driving secondary spreads. Cost compression in rigid foam board is intensifying because regional olefin feedstock volatility undermines margin predictability. Residential mid-rise developers exhibit highest price sensitivity, while hospital and data center procurement teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Just-in-time inventory preferences dominate fiberglass batt distribution through Riyadh contractor networks, while strategic stockpiling of rigid foam board concentrates in Jeddah commercial facade specialists. Domestic production in Saudi Arabia, the UAE, and Turkey supplies standard-grade mineral fiber systems. Raw material flows draw from regional petrochemical complexes for polyisocyanurate precursors, silica sand for glass wool, and recycled paper feedstocks for cellulose. Single-source vulnerability sits with certified spray foam applicator networks clustered in Dammam. Distribution runs through envelope consultants consolidating specification authority in giga-project developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as envelope performance modeling displaces prescriptive R-value procurement, creating specialist niches for integrated system suppliers. Giga-project procurement concentration in Riyadh fragments decision-making across envelope consultants, municipal building departments, and developer procurement teams.
For Market Incumbents: Secure municipal pre-approval relationships in Riyadh and Jeddah to lock specification pathways before schematic design phases. Backward integration into raw material blending for mineral wool reduces exposure to regional silica sand price volatility. Certification investment in SASO thermal conductivity documentation capabilities defends against emerging regional suppliers with shorter conformity timelines. For New Entrants and Emerging Players: Anchor in Jubail Industrial City's high-temperature pipe and vessel insulation segment, where Saudi Aramco supplier mandates accelerate specification reviews with limited incumbent presence. Aerogel-enhanced blanket systems for space-constrained roof assemblies offer the most penetrable premium niche. Go-to-market leverage rests on calibrated conductivity data partnerships with Riyadh engineering consultancies lacking in-house CFD expertise. For Investors and Strategic Acquirers: Saudi Green Building Forum certification tier adoption reshapes the acquisition landscape toward lower-embodied-carbon insulation alternatives. Long-term viability favors envelope system integrators with factory-controlled prefabrication capabilities over discrete product manufacturers. Target acquisition archetype: modular construction suppliers consolidating insulation, air barrier, and cladding layers. Signal to watch: preferential financing terms from national development funds for enhanced sustainability ratings crossing threshold adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive silica sand and binder chemical supply secures margin stability against regional feedstock volatility. |
| SASO Certification Acceleration Program | In-house thermal conductivity metrology compresses product conformity timelines for fast-track developments. |
| Envelope Consultant Partnership Network | Direct specification access with Riyadh giga-project envelope consultants displaces fragmented trade subcontracting. |
| Prefabricated Panel Integration | Factory-controlled assembly of insulation, air barrier, and cladding layers reduces field installation variability. |
| Aerogel Technology Licensing | Ultra-thin premium system capabilities penetrate hospital and laboratory segments with compressed payback positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews encompassed envelope consultants specifying thermal-hygrostatic systems, municipal building department permit reviewers, developer procurement directors, contractor installation supervisors, and mineral wool production plant managers. Secondary sources integrated Saudi Building Code technical bulletins, SASO conformity marking registries, customs import records for rigid foam systems, and Saudi Green Building Forum certification databases. Bottom-up project pipeline aggregation across Riyadh, Jeddah, and Dammam construction permits triangulated against top-down material consumption estimates from regional mineral wool producers.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmented demand drivers. Segmentation dimensions encompassed material chemistry tiers, installation methodology categories, end-user construction types, and envelope application zones. CAGRs derived from regression analysis of permit approval velocity, municipal enforcement intensity, and technology substitution elasticities. Industry-specific inputs included petrochemical feedstock price indices, giga-project procurement schedules, and certified applicator network expansion rates.
Material uncertainties — regulatory enforcement variance across municipal jurisdictions, petrochemical feedstock price volatility, and aerogel technology cost curves — sit outside the modeled envelope. Forecasts reflect assumptions regarding Saudi Building Code amendment trajectories and green building certification adoption thresholds. Revision becomes warranted when municipal pre-approval protocol standardization crosses implementation thresholds or when regional olefin pricing volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Hydronic Control Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Aeration System Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Ductless HVAC System Market