
 North America UPVC Doors and Windows Market | 2026-2036
North America UPVC Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
North America UPVC Doors and Windows Market Analytics
A shift from single-source vinyl extrusion supply toward multi-source resin and profile outsourcing is restructuring procurement economics for fabricators across the region. JELD-WEN leverages its captive distribution network to control last-mile delivery costs in fragmented local markets. Andersen Corporation anchors its position through deep backward integration into custom compound formulation. Rehau Group competes on co-extrusion technology leadership for multi-chamber frame systems.
North America UPVC doors and windows are thermoplastic fenestration assemblies fabricated from unplasticized polyvinyl chloride resin compounded with titanium dioxide stabilizers and calcium carbonate fillers, extruded into multi-chamber hollow profiles that achieve U-factors below 0.30 when paired with low-emissivity glazing. Their primary commercial purpose is to deliver code-compliant thermal barriers for building envelopes while eliminating the maintenance cycles demanded by wood or aluminum alternatives. The residential end-user segment carries the volume base, though margin pools concentrate in commercial replacement installations where performance specifications justify premium hardware and glazing packages. New construction installations dominate unit throughput, yet renovation and retrofit channels are expanding fastest as aging stock triggers replacement demand across the Midwest and Northeast housing stock.
EPA Energy Star certification and IECC model code adoptions by state jurisdictions shape minimum U-factor and solar heat gain coefficient thresholds that manufacturers must meet for market access. NHTSA surface transportation regulations and DOT modal standards govern the logistics economics of oversized window shipments across interstate corridors. CSA Group standards in Canada create a parallel compliance track that dual-certified suppliers must navigate for cross-border product lines. Stakeholders must monitor state-by-state IECC amendment cycles and emerging embodied-carbon disclosure requirements that could reshape material specification protocols.
Market Dynamics
Multi-chamber frame engineering and low-emissivity glazing integration are compressing thermal performance thresholds faster than legacy fabrication assets can retool, forcing capital deployment decisions across the North American fabricator base.
Growth Catalysts
- IECC Code Cycles:State-level adoptions of 2021 and 2024 IECC amendments mandate U-factors below 0.30 for residential fenestration, compelling wholesale product line upgrades.
- Sun Belt Construction:Housing starts in Texas, Florida, and Arizona concentrate demand for tilt-and-turn systems that satisfy both hurricane impact ratings and thermal codes.
- Calcium-Zinc Stabilizers:Lead-free compound chemistry advances are eliminating regulatory friction with EPA toxic substance guidelines while maintaining extrusion throughput rates.
Market Restraints
- Resin Price Volatility:Ethylene and chlorine feedstock exposure ties UPVC profile costs to Gulf Coast petrochemical capacity swings.
- Canadian Import Friction:CSA Group certification requirements create parallel testing burdens for US fabricators seeking cross-border market access.
- Aluminum-Clad Wood Substitution:Premium residential segments in coastal Northeast markets specify hybrid frames that outperform UPVC on aesthetic and thermal metrics.
Strategic Opportunities
- Retrofit Channel Expansion:Aging window stock across Midwest and Northeast housing built 1960-1990 triggers replacement cycles independent of new construction volatility.
- Commercial Performance Tier:Curtain wall and storefront applications specify triple-glazed UPVC assemblies with warm-edge spacers, opening margin pools above residential baselines.
- IRA Tax Credits:Inflation Reduction Act efficiency incentives for window replacements subsidize consumer upgrades in states with aligned rebate programs.
Industry Challenges
- Co-Extrusion Technician Scarcity:Multi-layer profile engineering demands skilled operators capable of calibrating die flow for titanium dioxide distribution uniformity.
- Dual Certification Timelines:Simultaneous NFRC and CSA Group testing extends product launch cycles by four to six months for cross-border suppliers.
- Legacy Hardware Integration:Tilt-and-turn mechanism retrofits into existing frame extrusions require machining tolerances that strain fabricator quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America UPVC Doors and Windows Market |
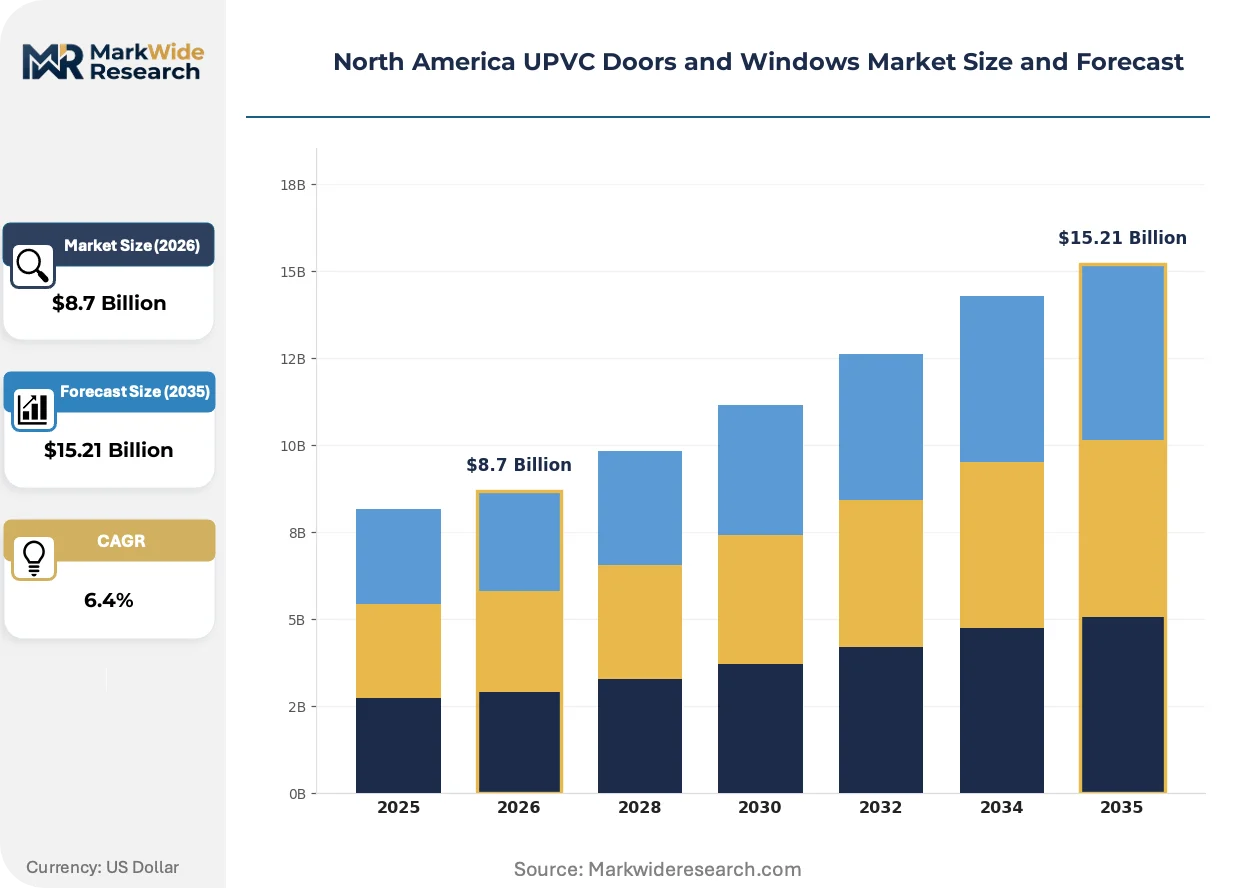
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding, Casement, Awning, Tilt and Turn End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Renovation, Replacement, Retrofit Accessories: Hardware, Sealants, Fasteners, Glazing |
| Companies Covered | Cornerstone Building Brands, Rehau Group, JELD-WEN, All Seasons Window and Door Systems, Crystal uPVC, Andersen Corporation, Ply Gem, Deceuninck, Pella Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America UPVC Doors and Windows Market Evolving Landscape
Digital fabrication workflows and automated glazing lines are compressing lead times while regulatory pressure on embodied carbon forces material transparency upstream.
Recycled content feedstock integration is decentralizing resin sourcing away from virgin petrochemical supply chains. Regional compounders in Ohio and Ontario are blending post-industrial PVC regrind at 15-25% load rates without sacrificing impact resistance. This distributed sourcing model is decentralizing procurement risk concentration previously anchored to Gulf Coast ethylene crackers.
EPA Energy Star Version 7.0 certification requirements tighten U-factor and solar heat gain coefficient thresholds for climate zone specifications. Fabricators must retest entire product portfolios against the revised criteria to maintain program eligibility. The residential replacement segment faces the steepest compliance burden as existing stock loses certified status.
Direct-to-builder digital ordering platforms are compressing distributor margins in fragmented local markets. Large multi-family developers in Texas and Florida now specify frames through centralized procurement portals that bypass traditional two-step distribution. This channel compression is most visible in Sun Belt metro markets where builder concentration supports platform economics.
North America UPVC Doors and Windows Market Segmentation
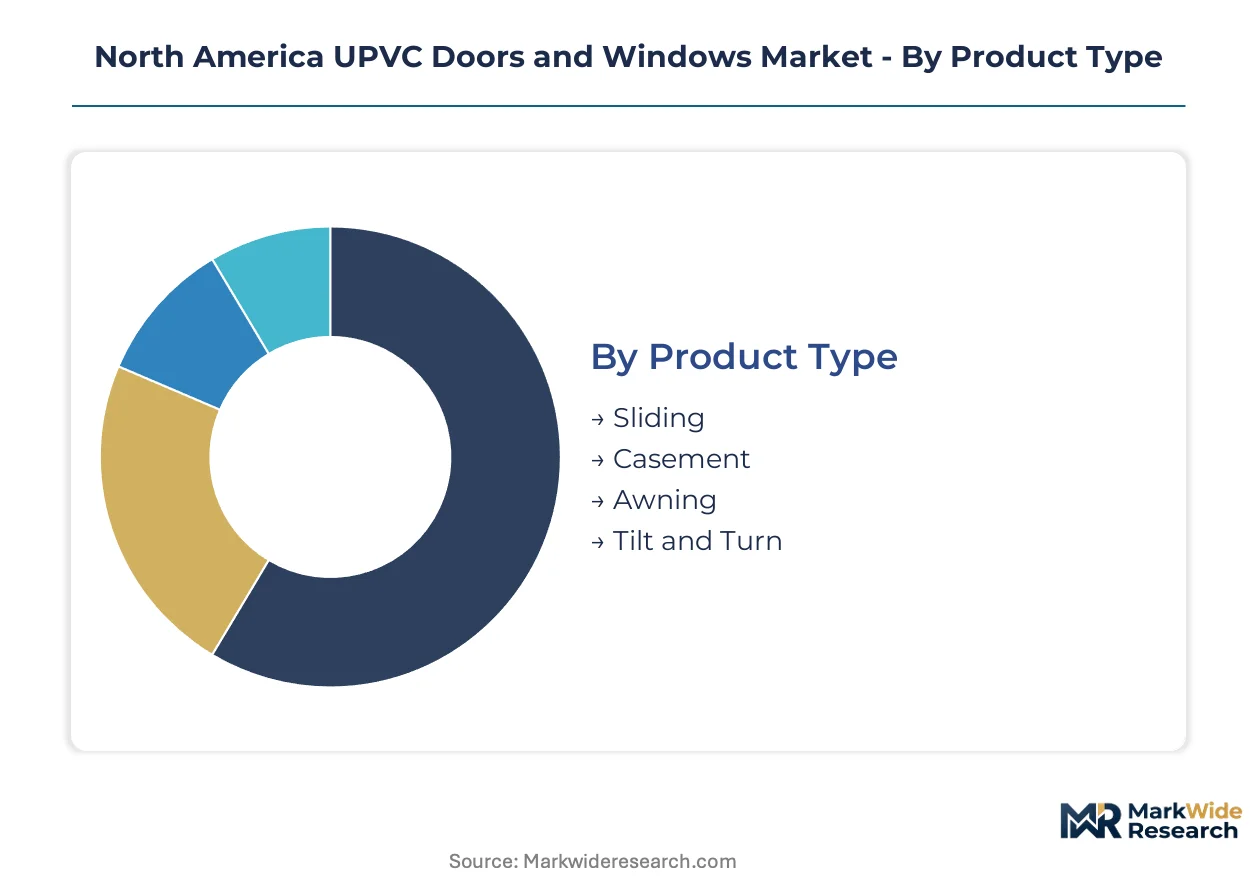
Segmentation in the North America UPVC doors and windows market determines which fabrication assets, certification pathways, and distribution channels manufacturers must deploy. Each dimension carries distinct margin profiles and regulatory burdens that shape competitive positioning across the United States and Canada.
Product Type:
Tilt-and-turn systems require NFRC certification for U-factor performance and CSA Group testing for Canadian market access, while sliding configurations face lighter thermal validation burdens in southern climate zones.
- Sliding:Horizontal track systems dominate Sun Belt residential construction where hurricane impact ratings and thermal codes overlap. Texas and Florida builders specify these for multi-family housing starts due to lower installed cost per opening. Sliding sits at the top of the volume ranking, with tilt and turn climbing the fastest.
- Casement:Hinged sash designs with compression seals achieve superior air infiltration ratings required by IECC 2021 amendments in northern climate zones. Midwest and Northeast replacement contractors favor these for aging stock upgrades where thermal performance justifies premium positioning.
- Awning:Top-hinged configurations with rain-shedding geometry concentrate in coastal Pacific Northwest markets where moisture management drives specification.
- Tilt and Turn:Dual-mode hardware enables ventilation and cleaning access, commanding specification in high-performance residential and commercial tiers where European-style fenestration gains traction.
Cost tier separation is pronounced: tilt-and-turn hardware complexity supports premium pricing, while sliding systems compete on fabricated cost per linear foot.
End User:
Residential volumes anchor production scale, yet commercial and institutional segments concentrate margin pools where performance specifications justify triple-glazing and warm-edge spacer packages.
- Residential:Single-family and multi-family housing stock drives unit throughput across new construction and replacement channels. Sun Belt states concentrate demand for tilt-and-turn systems in energy-efficient housing developments. Residential sits at the top of the volume ranking, with institutional climbing the fastest.
- Commercial:Curtain wall and storefront applications specify assemblies with U-factors below 0.25, opening procurement budgets for enhanced frame engineering and low-emissivity glazing combinations.
- Industrial:Warehousing and light manufacturing facilities prioritize durability and low maintenance over thermal performance, accepting wider frame profiles that reduce fabrication complexity.
- Institutional:Schools, hospitals, and government buildings mandate EPA Energy Star certification and extended warranty terms, creating specification barriers that filter supplier pools.
Application focus shifts procurement criteria: residential buyers prioritize installed cost, while institutional purchasers weight lifecycle performance and compliance documentation.
Installation Type:
New construction dominates unit throughput with standardized opening sizes and bulk ordering patterns, yet renovation and retrofit channels expand fastest as aging stock triggers replacement demand.
- New Construction:Builder-direct procurement through centralized platforms compresses distributor margins in Texas and Florida metro markets. Volume commitments support dedicated production lines and compressed lead times.
- Renovation:Whole-building envelope upgrades in Midwest and Northeast housing built 1960-1990 drive demand for custom-sized replacements with minimal structural modification.
- Replacement:Single-unit swaps concentrate in older housing stock where failed seals and degraded hardware trigger homeowner-initiated purchases. IRA tax credits subsidize upgrades in states with aligned rebate programs.
- Retrofit:Insert window installations preserve existing frames while upgrading glazing performance, minimizing labor cost and disruption for occupied buildings.
Channel maturity varies: new construction correlates with housing start volatility, while replacement demand offers countercyclical stability.
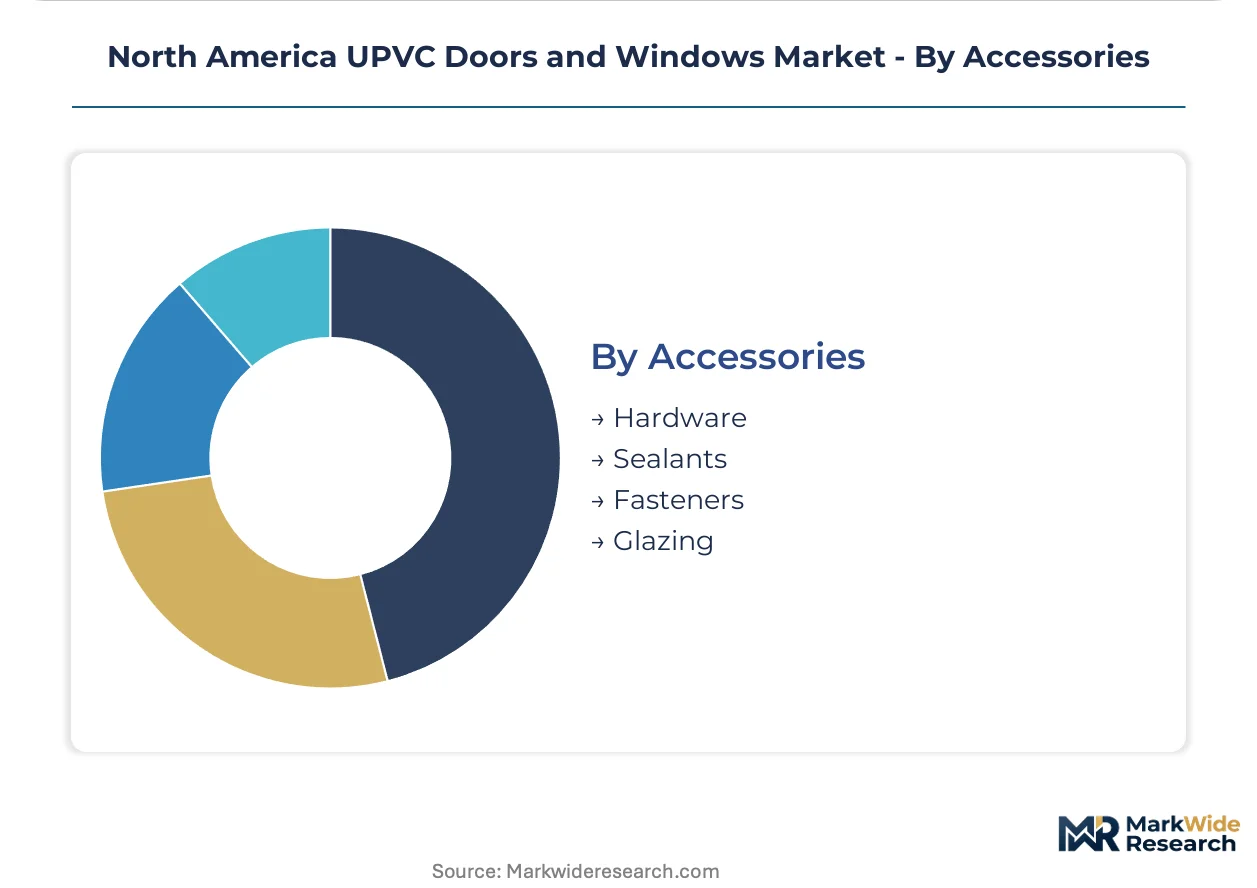
Accessories:
Hardware specification determines tilt-and-turn mechanism functionality, while glazing selection governs thermal performance certification eligibility.
- Hardware:Multi-point locking systems and concealed hinges command premium positioning in coastal markets where hurricane impact ratings apply. Machining tolerances for tilt-and-turn mechanisms strain fabricator quality systems.
- Sealants:Dual-durometer gaskets and compression seals enable air infiltration ratings required by IECC amendments, with silicone formulations dominating high-performance tiers.
- Fasteners:Corrosion-resistant anchoring systems concentrate specification in coastal and industrial environments where chemical exposure accelerates degradation.
- Glazing:Low-emissivity coatings and warm-edge spacers determine U-factor performance, with triple-glazed units penetrating commercial and institutional specification.
Supply concentration is highest in glazing, where regional glass processors control access to low-emissivity coating capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors North American UPVC fenestration capacity, with extrusion plants clustered near resin supply chains and transport infrastructure. State-level IECC adoptions and federal efficiency incentives reshape demand geography across the United States, Canada, and Mexico.
United States
Sun Belt housing starts in Texas and Florida drive tilt-and-turn specification for hurricane-rated thermal assemblies. EPA Energy Star Version 7.0 compliance deadlines force fabricators in Ohio and Pennsylvania to retest entire product portfolios. The Midwest replacement channel concentrates in Detroit and Cleveland metros where 1960-1990 housing stock triggers renovation demand.
Canada
CSA Group certification requirements create parallel testing tracks for cross-border suppliers serving Ontario and Quebec markets. Toronto and Vancouver multi-family developers specify triple-glazed UPVC assemblies to meet provincial energy codes. Health Canada toxic substance guidelines accelerate calcium-zinc stabilizer adoption among compounders in the Windsor-Quebec corridor.
Mexico
Nuevo León and Jalisco manufacturing clusters supply duty-free UPVC profiles to US Southwest builders under USMCA provisions. Monterrey extrusion plants leverage Gulf Coast petrochemical feedstock proximity for resin cost advantages. Mexico City metro area drives residential replacement demand as 1980s construction stock ages.
North America UPVC Doors and Windows Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized hardware integration and recycled-content differentiation. The fabricator base concentrates among multi-regional extruders with captive compound formulation and regional specialists serving single-state markets. Three archetypes dominate: vertically integrated resin-to-frame manufacturers, distribution-captive assemblers, and technology-licensed regional players. Capacity expansion and backward integration into custom compounding represent the dominant competitive vectors as thermal performance thresholds tighten.
Among North American fabricators, Andersen Corporation exemplifies the integrated-compounder archetype through captive resin formulation capabilities. JELD-WEN represents distribution-captive positioning with controlled last-mile logistics. Rehau Group anchors the technology-licensed tier, with co-extrusion specialization for multi-chamber frame engineering. These three occupy distinct strategic positions without direct segment overlap.
| Leading Market Players |
|---|
| Cornerstone Building Brands |
| Rehau Group |
| JELD-WEN |
| All Seasons Window and Door Systems |
| Crystal uPVC |
| Andersen Corporation |
| Ply Gem |
| Deceuninck |
| Pella Corporation |
| Others |
Value Network & Pricing Analysis
Multi-family developer procurement consolidation across Texas and Florida metros forces fabricators to absorb resin volatility or cede volume to vertically integrated competitors, compressing margin pools in the standard tier while premium positioning holds.
Pricing Analysis
Ethylene and chlorine feedstock pass-through dominates UPVC profile economics, with Gulf Coast petrochemical capacity swings transmitting directly to extrusion plant cost bases. Pricing stratifies across premium tilt-and-turn, standard casement, and economy sliding tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the standard tier intensifies as direct-to-builder platforms eliminate distributor markups. Residential replacement buyers exhibit highest price sensitivity, while institutional purchasers accept premiums for extended warranty and compliance documentation.
Supply Chain Analysis
Resin supply rests on Gulf Coast ethylene crackers, Ontario compounders, and Monterrey extrusion plants feeding USMCA duty-free channels. Titanium dioxide stabilizers, calcium carbonate fillers, and low-emissivity coated glass constitute critical input dependencies. Single-source vulnerability concentrates in regional glass processors controlling low-emissivity coating capacity. Distribution runs through captive assembler networks, independent fabricators, and emerging direct-to-builder platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America UPVC doors and windows market functions as a geographic-arbitrage play where CSA Group certification burdens in Canada create margin premiums for dual-certified US fabricators versus domestic-only competitors.
For Market Incumbents: Anticipate aluminum-clad wood substitution pressure in coastal Northeast premium segments by deepening backward integration into custom compound formulation. Anchor position through captive distribution control in fragmented Sun Belt local markets. Prioritize IECC 2024 pre-compliance testing to avoid four-to-six month launch delays.
For New Entrants and Emerging Players: Direct-to-builder digital ordering platforms offer the lowest-friction entry vector into Texas and Florida multi-family procurement channels. Target the Midwest replacement channel where aging 1960-1990 housing stock triggers renovation demand independent of new construction volatility. Pursue recycled-content feedstock differentiation to escape Gulf Coast resin price exposure.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing CSA Group dual-certification and tilt-and-turn hardware integration capabilities. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than scale alone. Monitor state-level IECC amendment adoption timelines as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Compounding | Andersen Corporation's captive resin formulation insulates margin from ethylene volatility. |
| Dual Certification Investment | Simultaneous NFRC and CSA Group testing opens Ontario and Quebec institutional specification. |
| Recycled Content Feedstock Transition | Ohio and Ontario compounders blending post-industrial PVC regrind at 15-25% reduce petrochemical dependency. |
| Direct-to-Builder Platform Deployment | Centralized procurement portals in Texas and Florida metros bypass traditional two-step distribution. |
| Tilt-and-Turn Hardware Engineering | European-style fenestration penetration in high-performance residential tiers commands premium positioning. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down extrusion capacity and resin consumption tracking forms the analytical core. Primary interviews with fenestration fabricators, multi-family developer procurement officers, regional glass processors, and distributor channel managers combined with secondary validation from EPA Energy Star certification databases, NFRC product listings, CSA Group standards documentation, and US Census Bureau housing starts data. Triangulation across supply-side capacity announcements and demand-side specification trends anchors volume and value estimates.
Historical trendline analysis of housing start correlations, replacement cycle timing, and code adoption patterns informs the projection framework. Segmentation dimensions span product type, end-user category, installation channel, and accessories specification, with climate zone regulatory clustering as an industry-specific overlay. CAGRs derive from fitted growth curves applied to construction cycle-adjusted baselines, incorporating IECC amendment adoption schedules and IRA tax credit program alignment as demand-side inputs.
The model assumes a particular technology adoption path; alternative pathways for calcium-zinc stabilizer chemistry or triple-glazing penetration would alter the outlook. Forecasts reflect assumptions regarding state-level code adoption timelines and petrochemical feedstock cost trajectories. A small set of triggers—including CSA Group standard revisions, EPA toxic substance guideline updates, and Sun Belt housing start volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Global Elastic Rail Fasteners Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
GCC Exterior Sheathing Market