
 Chilled Beams Market | 2026-2036
Chilled Beams Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Beams Market Analysis
ISO 16484 building automation certification is redrawing competitive barriers for chilled beam suppliers. TROX GmbH leverages its deep product engineering heritage to dominate European specification channels. Halton Group anchors its position through specialized healthcare ventilation integration with active beam systems. Lindab International AB extends its reach via modular ductwork and climate solutions that bundle installation efficiency.
Chilled beams are hydronic terminal units that use convective and radiant heat transfer from ceiling-mounted heat exchangers, typically operating with supply water temperatures of 14–17°C for cooling, to condition occupied zones without forced air distribution. Active chilled beams lead product type demand due to their ventilation air integration, while passive variants capture margin pools in deep-energy retrofit projects where ductwork modification proves prohibitive. Commercial buildings anchor end user volume, though healthcare facilities represent the fastest-growing installation type segment as infection control protocols elevate demand for draft-free, low-turbulence air distribution.
EU F-Gas Regulation and Ecodesign Directive frame product development requirements, with REACH compliance adding material transparency obligations for copper-aluminum coil assemblies. The US EPA and ASHRAE Standard 90.1 shape efficiency benchmarks that chilled beam systems must satisfy to qualify for federal tax incentives and utility rebate programs. Stakeholders must monitor evolving refrigerant-phase-down schedules and building performance standard adoptions to align product roadmaps with compliance-driven specification windows.
Market Dynamics
The EU F-Gas Regulation is compressing specification windows for conventional HVAC systems, redirecting capital toward hydronic cooling architectures that eliminate refrigerant exposure in occupied zones entirely.
Growth Catalysts
- Healthcare Infection Control Mandates:Active chilled beams deliver draft-free air distribution that satisfies Joint Commission ventilation standards for operating theaters and isolation rooms.
- REACH Material Transparency:Copper-aluminum coil assemblies with full substance disclosure now qualify for green building certification credits across Nordic and German specification channels.
- Deep Energy Retrofit Pipelines:Passive beam variants capture renovation volume where existing ductwork cannot accommodate conventional air handling unit upgrades.
Market Restraints
- Copper Price Volatility:Coil material costs fluctuate with London Metal Exchange pricing, compressing margin predictability for project-based manufacturers.
- Specialized Contractor Scarcity:Installation requires certified hydronic technicians concentrated in Northern European markets, limiting deployment speed elsewhere.
- Chilled Ceiling Panel Substitution:Radiant cooling surfaces compete for the same ceiling real estate with lower first-cost positioning in speculative office construction.
Strategic Opportunities
- US Federal Tax Incentives:ASHRAE Standard 90.1 compliance unlocks utility rebate programs for high-performance envelope-integrated systems in commercial new construction.
- Smart Building Convergence:Integration with BACnet and IoT sensor networks enables demand-responsive cooling modulation that reduces pumping energy.
- Modular Prefabrication Channels:Offsite manufacturing of beam-ductwork assemblies accelerates installation timelines for fast-track healthcare projects.
Industry Challenges
- ISO 16484 Certification Timelines:Building automation integration testing extends product qualification cycles by eight to fourteen months for specification-grade suppliers.
- Legacy Controls Integration:Pneumatic thermostat infrastructure in existing commercial buildings requires costly gateway retrofits to enable beam zone control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Beams Market |
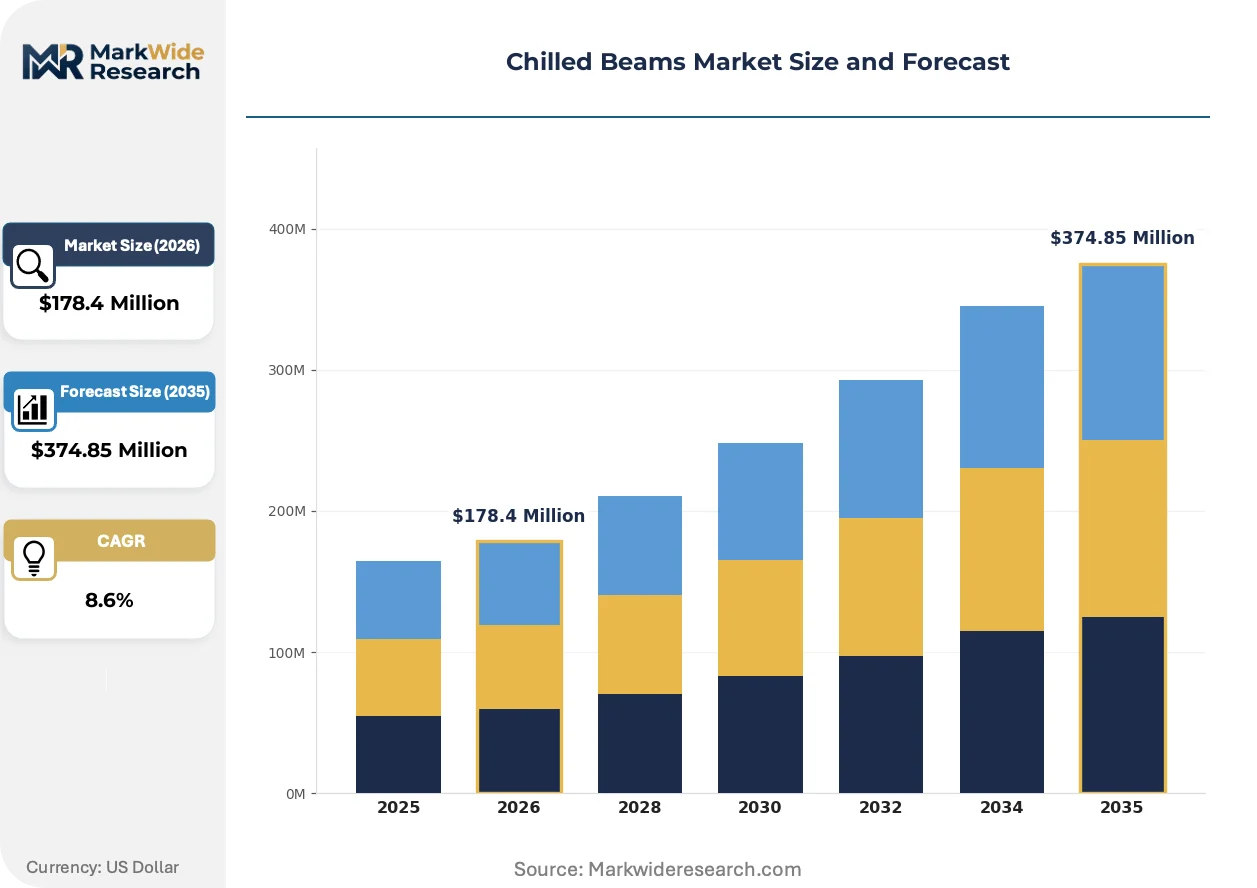
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $374.85 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Chilled Beams, Active Chilled Beams, Underfloor Chilled Beams, Multi-service Chilled Beams Installation Type: New Construction, Renovation, Retrofit, Modular Installation End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Residential Buildings Functionality: Heating, Cooling, Ventilation, Humidity Control |
| Companies Covered | TROX GmbH, Halton Group, Lindab International AB, Swegon Group AB, FläktGroup Holding GmbH, Johnson Controls International plc, Carrier Global Corporation, Price Industries Inc., Daikin Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Beams Market Emerging Trajectories
Product engineering is pivoting toward sensor-embedded terminal units that enable real-time performance verification, while regulatory pressure on refrigerant-based systems accelerates specification migration toward hydronic alternatives.
Multi-service chilled beams are fragmenting the traditional ceiling component stack by integrating lighting, fire suppression, and acoustic treatment into single suspended modules. Healthcare facility managers in Germany and the Netherlands are specifying these consolidated systems to reduce ceiling complexity and maintenance access conflicts. The consolidation is fragmenting supplier relationships as mechanical, electrical, and fire protection contractors negotiate unified procurement packages rather than discrete trade contracts.
The EU F-Gas Regulation's phasedown schedule is compressing the installed base of variable refrigerant flow systems in commercial buildings across France, Belgium, and Austria. Building operators face mandatory refrigerant containment audits and leakage repair obligations that inflate operating costs for conventional split systems. Hydronic beam specifications are capturing retrofit volume in Munich, Vienna, and Brussels office markets where lease renewals trigger HVAC refresh cycles.
Performance-based maintenance contracts are displacing traditional time-and-material service agreements for active beam installations in Nordic markets. Facility management providers in Stockholm and Copenhagen are underwriting energy performance guarantees that bundle commissioning, filter replacement, and coil cleaning into fixed annual fees. This unbundling concentrates service revenue with OEM-certified technicians who control proprietary control algorithms and sensor calibration protocols.
Chilled Beams Market Segmentation
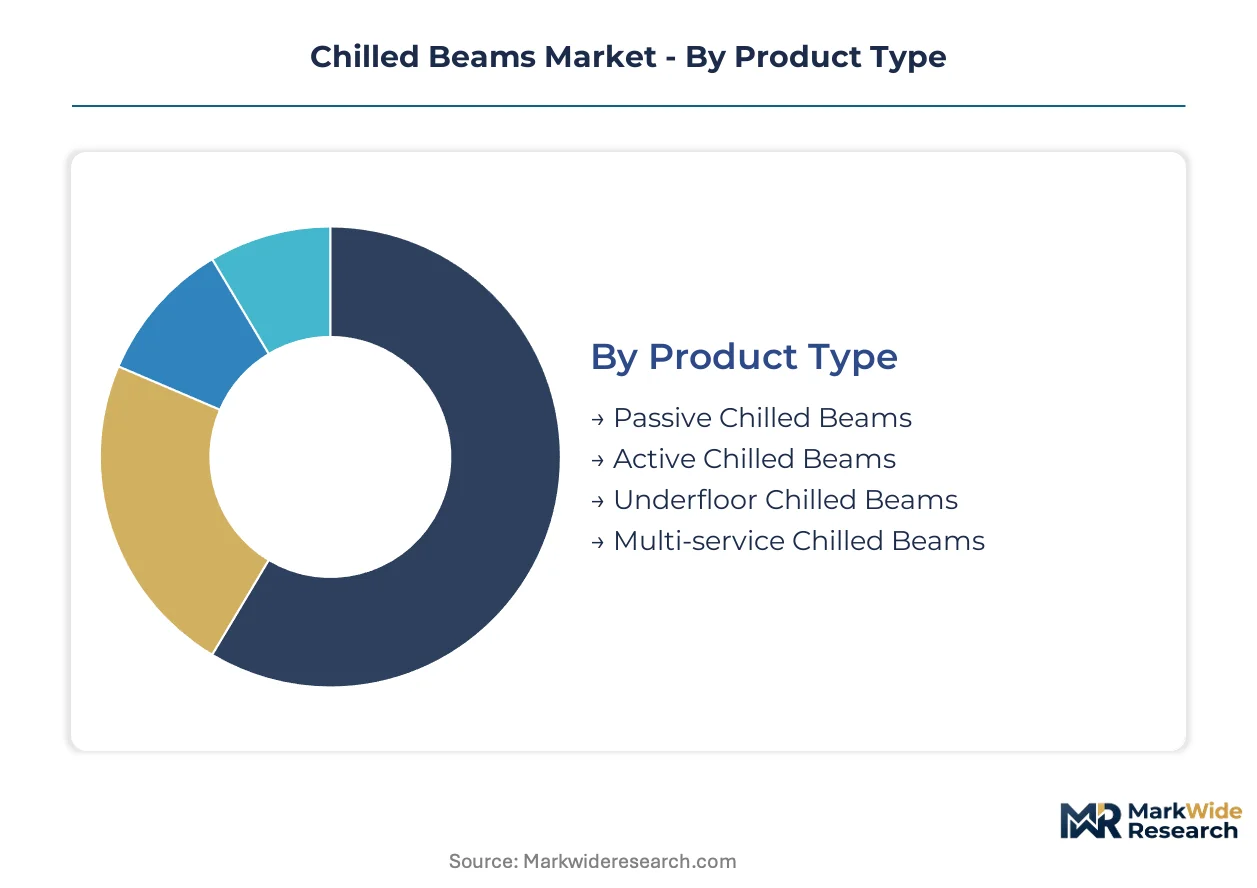
Segmentation in the chilled beams market reveals how regulatory pressure and building typology intersect to determine technology selection. Understanding these divides exposes where specification power concentrates and which product architectures capture margin.
Product Type:
EU F-Gas Regulation compliance timelines differentiate specification eligibility across hydronic terminal categories, with refrigerant-phase-down schedules pushing building operators toward architectures that eliminate on-site refrigerant exposure entirely.
- Passive Chilled Beams:These units rely solely on natural convection and radiant heat transfer from ceiling-mounted heat exchangers, operating without integrated ventilation air distribution. Demand concentrates in German and Austrian deep-energy retrofit pipelines where existing ductwork cannot accommodate mechanical ventilation upgrades, with Ecodesign Directive efficiency benchmarks favoring their ultra-low pumping energy profiles.
- Active Chilled Beams:Ventilation air integration through induction nozzles enables these systems to handle both thermal loads and fresh air delivery simultaneously. Healthcare facilities in the Netherlands and Denmark specify active beams for operating theaters and isolation rooms where Joint Commission standards mandate draft-free, low-turbulence air distribution that conventional VAV systems cannot achieve.
- Underfloor Chilled Beams:Floor-mounted configurations serve perimeter zones with high solar gain in Nordic commercial buildings where ceiling real estate is occupied by structural or acoustic systems.
- Multi-service Chilled Beams:Consolidated modules integrating lighting, fire suppression, and acoustic treatment reduce ceiling complexity in German hospital new construction.
Active chilled beams handle the majority of throughput in specification-grade commercial projects; multi-service variants are gaining share fastest as integrated procurement packages displace discrete trade contracting.
Installation Type:
Project delivery timelines and capital cycle positioning determine which installation modes capture volume, with fast-track healthcare construction favoring pre-engineered approaches.
- New Construction:Greenfield projects enable full hydronic infrastructure design from slab installation through ceiling integration. German office developments in Munich and Frankfurt specify active beams during core-and-shell phases to meet EnEV energy code requirements for primary energy demand limits.
- Renovation:Building envelope upgrades trigger HVAC refresh cycles where passive beams substitute for refrigerant-based systems facing F-Gas containment audit obligations. Vienna and Brussels lease renewal pipelines are concentrating renovation demand as landlords face mandatory efficiency improvements.
- Retrofit:Existing building constraints limit retrofit applications to perimeter zones with accessible ceiling plenums and compatible structural loading.
- Modular Installation:Prefabricated beam-ductwork assemblies compress construction schedules for Stockholm and Copenhagen healthcare projects with fixed commissioning deadlines.
New construction commands the largest project value per site; modular installation is climbing the fastest as offsite manufacturing penetrates fast-track delivery models.
End User:
Building use type dictates infection control requirements, occupancy patterns, and thermal comfort specifications that filter product selection.
- Commercial Buildings:Office developments in Belgium and France anchor baseline volume for standard active beam configurations with BACnet integration for demand-responsive zone control.
- Healthcare Facilities:Operating theaters, patient rooms, and isolation units require active beams with HEPA filtration compatibility and laminar flow patterns that satisfy ASHRAE Standard 170 ventilation standards.
- Educational Institutions:University laboratory buildings in the Netherlands specify passive beams for fume hood-dominated zones where air change requirements conflict with conventional all-air systems.
- Residential Buildings:High-end multifamily developments in Copenhagen and Hamburg deploy underfloor chilled beams for perimeter cooling without occupant-adjustable controls that compromise efficiency.
Commercial buildings generate the broadest installation base; healthcare facilities show the steepest expansion trajectory as infection control protocols elevate specification standards.
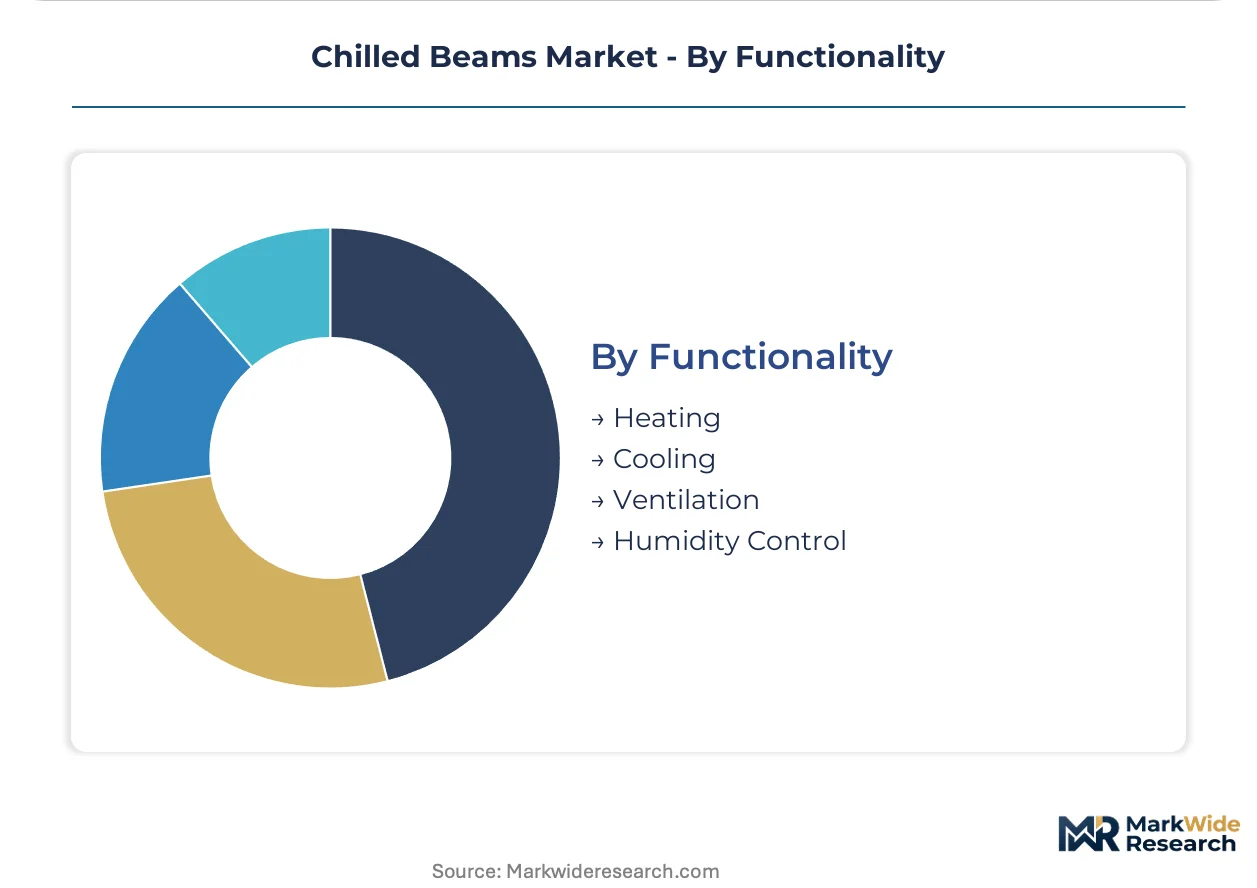
Functionality:
Climate zone and building envelope performance determine which functional capabilities dominate system design, with cooling-centric architectures leading in Southern European applications.
- Cooling:Supply water temperatures of 14–17°C enable radiant and convective heat removal without condensation risk in German and Austrian office markets with high internal gains.
- Ventilation:Active beam induction nozzles deliver primary air volumes required for occupancy-based fresh air standards in Nordic commercial buildings with stringent ventilation codes.
- Heating:Reversible hydronic circuits extend beam operation into shoulder seasons in mixed-mode buildings with moderate heating loads.
- Humidity Control:Dedicated outdoor air systems paired with beams handle latent loads separately from sensible cooling in high-occupancy healthcare environments.
Cooling functionality accounts for the dominant share of installed capacity; ventilation integration is expanding most quickly as airtight building envelopes tighten fresh air delivery requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's dominance in chilled beam specification, connecting manufacturing clusters in Bavaria to installation markets across the Danube basin.
Germany
Deep renovation pipelines in Munich and Frankfurt drive specification volume for passive and active beam variants. The Federal Ministry for Economic Affairs enforces EnEV energy code requirements that mandate primary energy demand limits in commercial new construction. Bavarian hospital clusters specify multi-service chilled beams to consolidate ceiling infrastructure in operating theater complexes.
Netherlands
Healthcare facility managers in Amsterdam and Rotterdam prioritize active beams for infection control in isolation rooms and surgical suites. The Dutch Building Decree mandates airtightness standards that favor hydronic systems with dedicated outdoor air integration. Eindhoven's university medical center anchors demand for sensor-embedded terminal units with real-time performance verification.
Denmark
Copenhagen's fast-track healthcare construction compresses installation timelines through modular prefabrication of beam-ductwork assemblies. The Danish Building Regulations impose strict ventilation rates that active beams satisfy through induction nozzle design. Stockholm-Copenhagen corridor projects concentrate performance-based maintenance contract adoption.
Belgium
Brussels office lease renewals trigger HVAC refresh cycles where hydronic beams replace refrigerant-based systems facing F-Gas containment audit obligations. The Brussels-Capital Region enforces building performance standards that accelerate efficiency-driven retrofits. Flemish hospital networks specify underfloor chilled beams for perimeter zones with high solar gain.
Austria
Vienna's historic building stock constrains ductwork modifications, concentrating passive beam demand in deep-energy retrofits. The Austrian Federal Ministry for Climate Action implements refrigerant-phase-down schedules that redirect capital toward hydronic architectures. Graz and Linz commercial developments specify active beams during core-and-shell phases to meet stringent envelope-integrated system requirements.
Chilled Beams Market Vendor Landscape
Listed leaders compete with private specialists across specification-grade commercial and healthcare channels, creating a tiered structure where scale advantages clash with application-specific engineering depth. European-headquartered entities dominate product engineering heritage, while global HVAC conglomerates leverage distribution breadth. Two archetypes anchor positioning: heritage engineering houses with ISO 16484 certification depth, and diversified climate-systems platforms bundling beams with broader mechanical portfolios. Consolidation pressure manifests through strategic partnerships for smart building integration and modular prefabrication capacity expansion.
Within the heritage engineering tier, TROX GmbH and Halton Group occupy positions defined by decades of ventilation product specialization. Lindab International AB anchors the climate-systems platform archetype through modular ductwork bundling. These three entities exemplify how European specification channels reward engineering credibility and installation efficiency integration.
| Leading Market Players |
|---|
| TROX GmbH |
| Halton Group |
| Lindab International AB |
| Swegon Group AB |
| FläktGroup Holding GmbH |
| Johnson Controls International plc |
| Carrier Global Corporation |
| Price Industries Inc. |
| Daikin Industries, Ltd. |
| Others |
Supply Flow & Price Mechanics
Aluminum-for-copper substitution in coil assemblies simultaneously redraws procurement geography toward Nordic smelters and compresses margin structures for mid-tier suppliers locked into London Metal Exchange pricing cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 16484-certified specification-grade suppliers from project-based regional manufacturers and basic passive beam commodity producers. Price differentiation hinges on certification depth and volume scale, with healthcare procurement bundling after-sales service premiums. Cost compression in the standard tier is intensifying because copper-aluminum volatility transfers inventory risk to smaller fabricators. Speculative office developers exhibit the highest price sensitivity, while hospital procurement committees prioritize infection-control performance over first-cost positioning.
Supply Chain Analysis
Extended coil fabrication lead times now stretch fourteen to twenty weeks for specification-grade heat exchangers, forcing project contractors into buffer stock commitments. Manufacturing concentrates in Germany, Sweden, and Austria, with Bavarian engineering houses anchoring premium active beam production. Raw material sourcing draws from Chilean copper cathode, Nordic primary aluminum, and Chinese fin stock. Single-source vulnerability concentrates in specialized induction nozzle machining capacity held by a limited supplier base. Distribution runs through specification-grade mechanical contractors and OEM-certified installation networks rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as BACnet-integrated beam systems transform from standalone HVAC components into data-layer infrastructure, with interoperability certification becoming the new margin gate.
For Market Incumbents: Shield specification-grade positioning by deepening ISO 16484 automation certification depth against emerging controls-agnostic entrants. Prioritize captive coil fabrication capacity in Germany or Sweden to neutralize copper price volatility exposure. Consolidate service revenue through performance-based maintenance contracts that lock out independent technicians from proprietary sensor calibration protocols. For New Entrants and Emerging Players: Aftermarket sensor retrofit and legacy controls integration services represent underserved white space where incumbents cede ground to avoid margin dilution. Target the US commercial retrofit segment, where ASHRAE 90.1 compliance deadlines create specification windows without entrenched European supplier relationships. Lead with packaged DOAS-beam integration that simplifies contractor procurement decisions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed climate-systems platforms that acquired regional ductwork specialists but lack chilled beam engineering depth. Five-to-ten-year viability favors targets with healthcare specification track records and modular prefabrication capacity. Monitor F-Gas Regulation phase-down acceleration in France and Belgium as the inflection signal for hydronic retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16484 Certification Investment | Building automation integration qualification unlocks specification-grade commercial and healthcare channels. |
| Modular Prefabrication Capacity Expansion | Offsite beam-ductwork assembly compresses installation timelines for fast-track Copenhagen and Stockholm healthcare projects. |
| Performance-Based Maintenance Contract Launch | Fixed-fee energy guarantees concentrate recurring revenue with OEM-certified technicians controlling proprietary algorithms. |
| Copper-Aluminum Coil Assembly Backward Integration | In-house heat exchanger fabrication neutralizes London Metal Exchange price volatility exposure. |
| Multi-Service Beam Platform Development | Consolidated lighting-fire-acoustic modules capture German hospital new construction procurement bundling. |
Methodological Framework
Initial hypotheses were tested against primary input from HVAC specification engineers, healthcare facility managers, mechanical contractors, and hydronic controls specialists and refined through secondary validation across SEC filings, EU Ecodesign Directive implementation reports, EnEV compliance databases, and building automation certification registries. Bottom-up project pipeline tracking across Munich, Vienna, and Brussels office markets triangulated against top-down regulatory impact modeling.
Variance decomposition across product type, installation mode, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented demand elasticity modeling and technology substitution curves. Forecast inputs incorporated F-Gas Regulation phase-down schedules and healthcare infection control protocol evolution.
Underlying assumptions cover copper price stabilization, contractor certification availability, and EU building code enforcement continuity, with deviation risk concentrated in refrigerant-phase-down acceleration or sudden hydronic technician labor shortages. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Air Handlers Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Fume Extraction System Market
HVAC Equipment
North America Heat Exchanger Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Industrial Exhaust System Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Foamer Pump Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Europe HVAC Field Device Market