
 Building Management System Market | 2026-2036
Building Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Building Management System Market Analysis
The EU Green Deal's building renovation requirements is pivoting procurement priorities across European commercial real estate portfolios. Schneider Electric leverages its EcoStruxure platform to anchor integrated energy and power management solutions. Johnson Controls competes through deep specialization in smart HVAC and fire safety integration. Siemens dominates automation-heavy segments with its Desigo portfolio spanning building control and enterprise analytics.
A Building Management System constitutes an integrated hardware-software platform that monitors, controls, and optimizes mechanical, electrical, and electromechanical services within a facility, typically operating through protocols such as BACnet or Modbus to coordinate HVAC, lighting, power, and security subsystems. Its primary purpose centers on reducing operational expenditure, ensuring occupant safety, and maintaining environmental compliance across complex built environments. Cloud-based solutions are capturing accelerated deployment momentum as facility managers prioritize remote diagnostics and predictive maintenance over capital-intensive on-premise infrastructure. Energy Management Systems within the technology dimension command concentrated margin pools, particularly where AI Analytics overlays enable real-time demand response and carbon accounting for commercial buildings and educational institutions.
The US Environmental Protection Agency's ENERGY STAR certification requirements and the European Union's Energy Performance of Buildings Directive jointly shape product standards and procurement eligibility across transatlantic markets. China's Ministry of Housing and Urban-Rural Development enforces GB standards for intelligent building design, conditioning market access for imported control platforms. India's Bureau of Energy Efficiency mandates Energy Conservation Building Codes that directly specify automation thresholds for commercial structures above defined floor areas. Stakeholders must monitor how fragmented national cybersecurity frameworks for operational technology reshape vendor qualification criteria and system architecture decisions.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for facility automation, while the EU Green Deal's renovation mandates force asset owners to consolidate fragmented control systems into unified platforms.
Growth Catalysts
- EU Green Deal renovation mandates:The directive compels commercial building owners across member states to install integrated energy management systems, triggering wholesale control platform replacements.
- Healthcare environmental controls:Hospital operators are deploying unified HVAC and air quality monitoring to meet Joint Commission infection prevention standards and reduce energy intensity per bed.
- KfW efficiency financing:Germany's state development bank subsidizes building automation retrofits, lowering capital barriers for mid-sized commercial portfolios.
Market Restraints
- Semiconductor supply concentration:BACnet and Modbus controller chipsets depend on Taiwanese foundry capacity, exposing lead times to geopolitical disruption.
- Cybersecurity compliance fragmentation:The US NIST Cybersecurity Framework, EU NIS2 Directive, and China's GB/T 22239 standards impose conflicting OT security architectures on multinational deployments.
- Legacy protocol entrenchment:Existing buildings running proprietary LonWorks or proprietary vendor protocols resist migration to open standards without full infrastructure replacement.
Strategic Opportunities
- India ECBC enforcement gaps:Bureau of Energy Efficiency mandates for buildings above 100,000 square feet remain underenforced in tier-2 cities, creating first-mover advantage for automation vendors.
- AI-overlay carbon accounting:Real-time Scope 1 and 2 emissions tracking for commercial real estate investment trusts converges environmental compliance with asset valuation.
- Remote diagnostics channel shift:Facility management outsourcing firms are procuring predictive maintenance subscriptions rather than capital equipment, opening recurring revenue models.
Industry Challenges
- OT-IT skill convergence:Building automation engineering now demands cybersecurity, data science, and cloud architecture competencies that legacy mechanical contractors rarely possess.
- Multi-protocol integration complexity:Retrofit projects must bridge BACnet, Modbus, KNX, and proprietary legacy systems without disrupting 24/7 facility operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Management System Market |
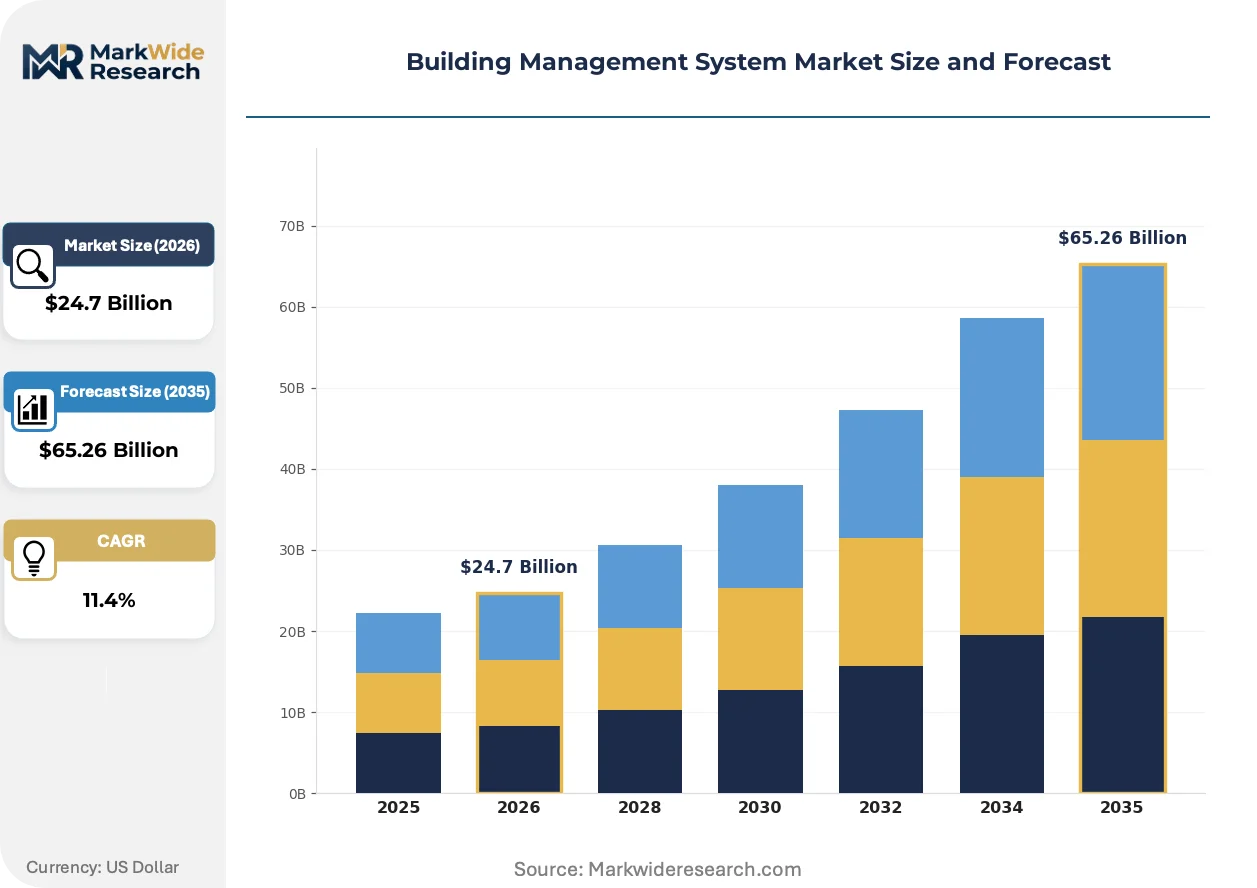
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $65.26 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Solutions, Standalone Systems, Cloud-Based Solutions, On-Premise Solutions Application: Commercial Buildings, Residential Complexes, Industrial Facilities, Educational Institutions Technology: IoT Devices, AI Analytics, Energy Management Systems, Access Control Systems End User: Facility Managers, Building Owners, Service Providers, Tenants |
| Companies Covered | Schneider Electric, Lutron Electronics, Honeywell, ABB, Control4, Johnson Controls, Legrand, Bosch, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Management System Market Emerging Trajectories
Digital twin technology is absorbing capital allocation from traditional SCADA upgrades, compressing the physical-digital feedback loop for energy optimization and predictive maintenance workflows.
Edge computing nodes with onboard AI inference engines are absorbing processing loads previously routed to cloud data centers, enabling sub-second demand response for commercial building HVAC systems. Large retail chains and data center operators are deploying these at scale, reducing bandwidth costs and latency. The shift is absorbing market share from centralized building automation server architectures.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing HVAC control system redesigns to accommodate alternative chemistries and lower charge systems. Equipment manufacturers must recalibrate sensor arrays and pressure monitoring protocols. Commercial refrigeration and district cooling networks in Germany, France, and Italy face the most compressed compliance timelines.
Subscription-based energy-as-a-service contracts are displacing traditional equipment procurement for municipal and educational building portfolios. Facility directors in US public school districts and university systems are trading capital budgets for performance-guaranteed operating agreements. California and New York procurement offices have formalized this shift through master service agreements.
Building Management System Market Segmentation
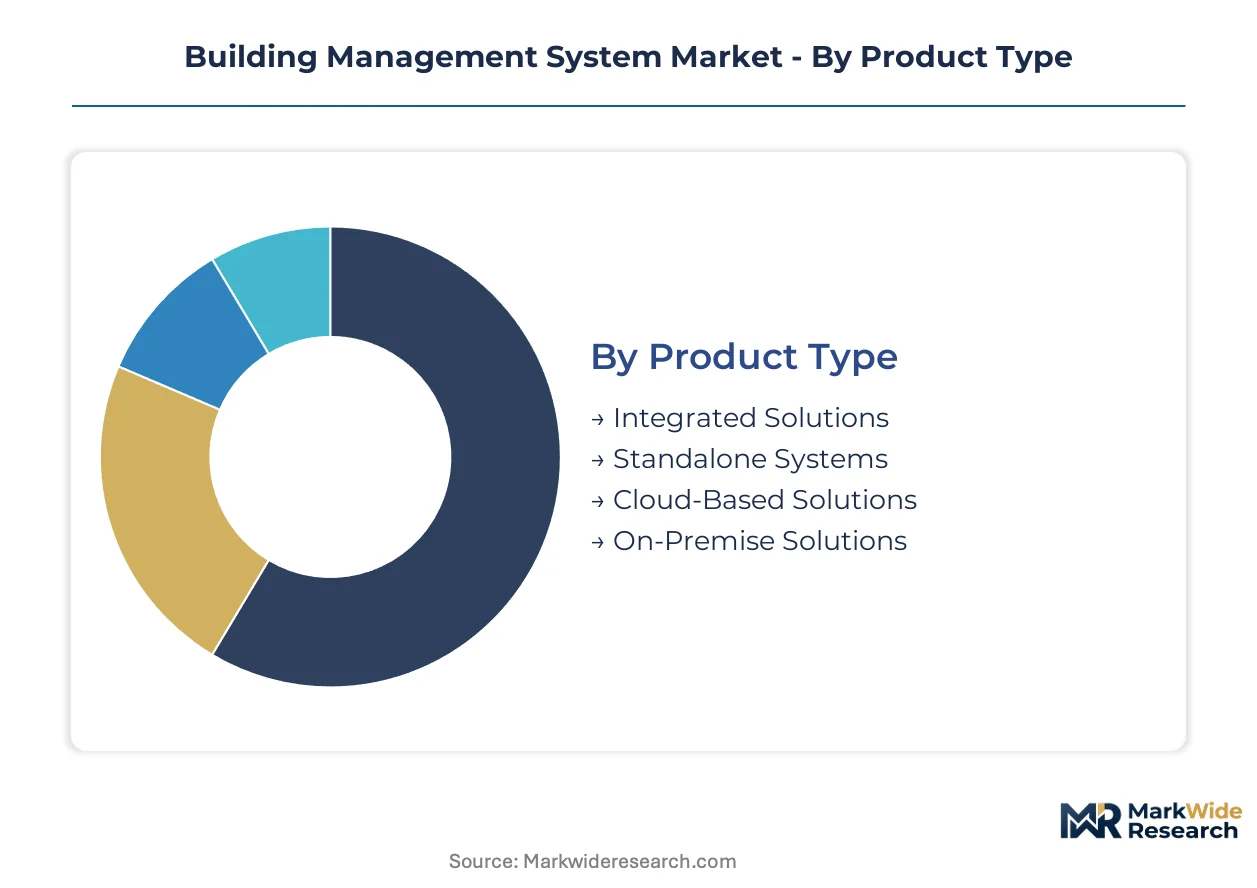
Building Management System segmentation reveals how procurement patterns fragment across deployment architectures, facility types, and stakeholder incentives. Vendors must align product configurations with distinct buyer risk tolerances, legacy infrastructure constraints, and regulatory compliance pathways.
Product Type:
Supply concentration in semiconductor-dependent controller hardware favors integrated platform vendors with captive chipset relationships over modular specialists.
- Integrated Solutions:Unified hardware-software stacks coordinate HVAC, lighting, security, and power through single-pane dashboards using BACnet or Modbus protocols. Healthcare facility operators in Germany prioritize these for Joint Commission alignment and KfW financing eligibility, consolidating previously fragmented vendor relationships.
- Cloud-Based Solutions:Browser-accessible platforms eliminate on-premise server infrastructure, enabling remote diagnostics and predictive maintenance subscriptions. US municipal procurement offices and European facility management outsourcing firms are displacing capital budgets with recurring SaaS agreements, particularly in California and New York public school districts.
- Standalone Systems:Single-function controllers for isolated HVAC or lighting zones serve legacy retrofit projects with constrained integration budgets.
- On-Premise Solutions:Locally hosted servers with air-gapped architectures persist in critical infrastructure and defense-adjacent facilities with stringent OT cybersecurity requirements.
Today's leader: Integrated Solutions. Tomorrow's challenger: Cloud-Based Solutions.
Application:
Margin pools concentrate where regulatory enforcement is strictest and energy intensity benchmarking is mandatory.
- Commercial Buildings:Office towers and retail portfolios deploy BMS platforms to meet EU Energy Performance of Buildings Directive disclosure requirements and US EPA ENERGY STAR certification thresholds. Real estate investment trusts overlay AI analytics for real-time Scope 1 and 2 emissions tracking, converging compliance with asset valuation methodologies.
- Educational Institutions:Universities and K-12 districts leverage subscription-based energy-as-a-service contracts to bypass capital budget constraints. Performance-guaranteed operating agreements with remote diagnostics clauses are displacing traditional equipment procurement in US public school systems.
- Industrial Facilities:Manufacturing plants integrate BMS with process automation layers, requiring hardened OT-IT convergence and cybersecurity frameworks aligned with NIST and EU NIS2 directives.
- Residential Complexes:Multi-family housing automation concentrates in premium developments with district heating integration and smart grid demand response participation.
Commercial Buildings anchor current procurement volume. Educational Institutions are climbing the fastest as public sector financing models shift.
Technology:
AI inference capabilities at the edge are absorbing processing loads from centralized cloud architectures, compressing demand response latency for HVAC optimization.
- AI Analytics:Machine learning overlays on sensor data enable predictive maintenance, occupancy-based HVAC scheduling, and automated fault detection. Large retail chains and data center operators deploy these at scale, reducing bandwidth costs and operational downtime through sub-second control loop execution.
- Energy Management Systems:Dedicated platforms for real-time demand response and carbon accounting command concentrated margin pools in commercial real estate. The EU F-Gas Regulation's hydrofluorocarbon phasedown is forcing sensor array recalibrations for alternative refrigerant chemistries in Germany, France, and Italy.
- IoT Devices:Wireless sensor networks with low-power protocols extend monitoring coverage to legacy buildings without structured cabling infrastructure.
- Access Control Systems:Biometric and mobile credential integration converges physical security with building automation, particularly in healthcare and financial services facilities.
Energy Management Systems dominate current spending. AI Analytics represents the steepest expansion trajectory as edge computing nodes proliferate.
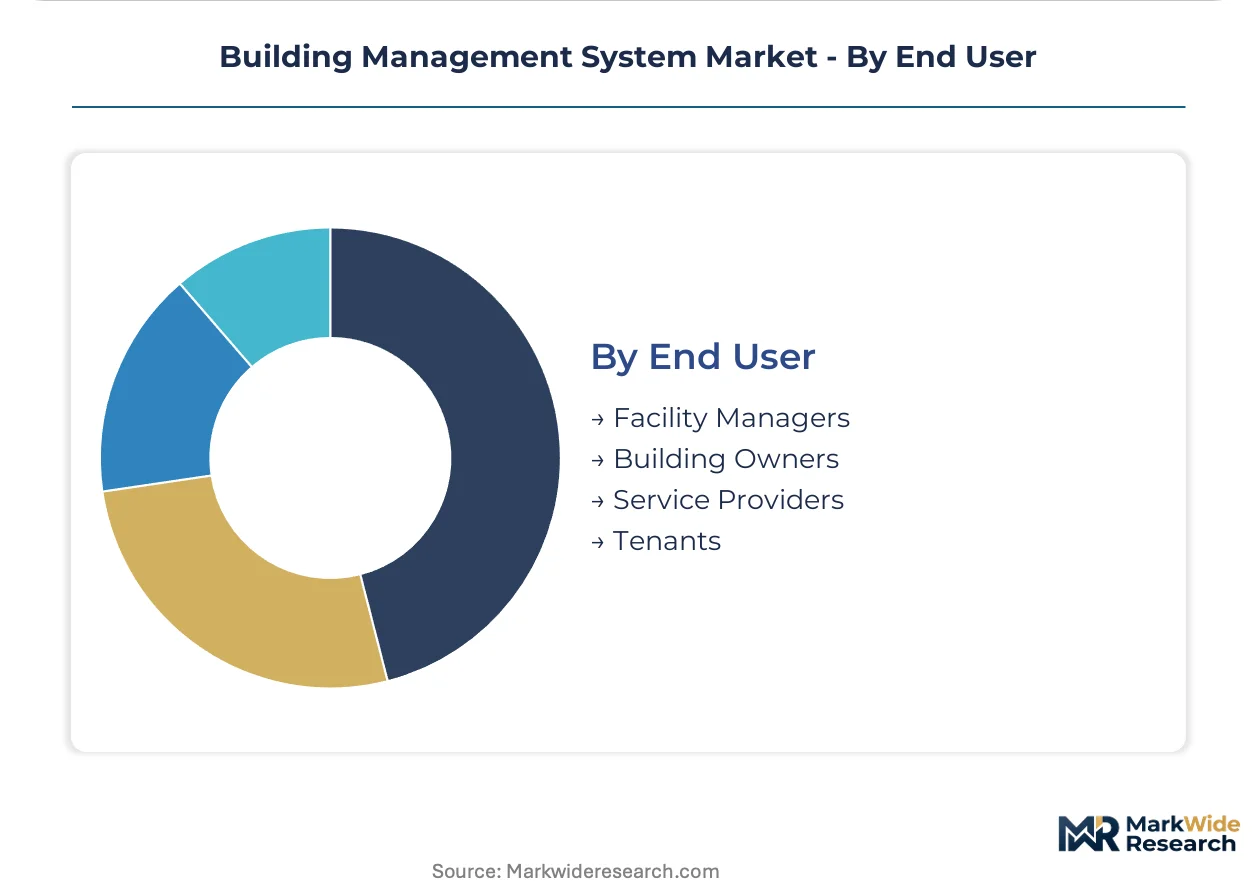
End User:
Procurement authority is fragmenting as facility management outsourcing firms assume operational control from asset owners.
- Facility Managers:Operational decision-makers prioritize remote diagnostics capabilities and predictive maintenance subscriptions over capital-intensive equipment purchases. OT-IT skill convergence demands now include cybersecurity, data science, and cloud architecture competencies rarely possessed by legacy mechanical contractors.
- Building Owners:Asset holders focus on integrated platforms that satisfy EU Green Deal renovation mandates and consolidate fragmented control systems into unified compliance-ready architectures.
- Service Providers:Third-party facility management firms procure white-label BMS platforms to deliver energy-as-a-service contracts with performance guarantees.
- Tenants:Commercial leaseholders increasingly demand granular environmental control and air quality transparency as workplace health standards tighten.
Facility Managers control operational procurement today. Service Providers are gaining share fastest as outsourcing contracts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Building automation originated in post-war Germany and the United States, where industrial control engineering first merged with commercial facility operations. Early pneumatic control systems deployed in Frankfurt and Chicago office towers established the technical foundations that evolved into today's digital platforms.
Germany
KfW efficiency financing and the EU Green Deal's renovation mandates drive wholesale control system replacements across commercial portfolios. The Federal Ministry for Economic Affairs and Climate Action coordinates building energy standards with the national development bank's subsidized retrofit programs. Automation deployment concentrates in Frankfurt's financial district and Munich's corporate campuses, where landlords consolidate fragmented legacy systems into unified compliance-ready architectures.
United States
EPA ENERGY STAR certification requirements and municipal energy-as-a-service procurement reshape demand patterns across office and educational buildings. California and New York procurement offices have formalized subscription-based master service agreements that displace traditional capital equipment purchases. Deployment clusters in Silicon Valley data centers and Manhattan commercial towers prioritize edge computing nodes with onboard AI inference for sub-second HVAC demand response.
China
GB standards for intelligent building design and dual carbon goals condition market access for imported control platforms while accelerating domestic substitution. The Ministry of Housing and Urban-Rural Development enforces automation thresholds for commercial structures above defined floor areas. Implementation concentrates in Shanghai's Lujiazui financial district and Shenzhen's technology corridors, where district cooling networks integrate with smart grid demand response systems.
India
Bureau of Energy Efficiency mandates for buildings above 100,000 square feet remain underenforced in tier-2 cities, creating first-mover positioning for automation vendors. The Energy Conservation Building Code specifies automation thresholds that procurement officers in Delhi-NCR and Mumbai increasingly reference. Commercial development in Bangalore's Whitefield tech corridor and Hyderabad's HITEC City drives integrated environmental control adoption for LEED-equivalent certification.
United Arab Emirates
MOHAP facility standards and district cooling network expansion accelerate BMS deployment across healthcare and hospitality portfolios. Dubai's building codes mandate smart building readiness for new commercial developments above specified thresholds. Automation integration concentrates in Dubai Healthcare City and Abu Dhabi's Masdar City, where predictive maintenance subscriptions replace capital-intensive on-premise infrastructure procurement.
Building Management System Market Vendor Landscape
Capital-heavy integrated platform producers compete with asset-light software specialists across the building automation value chain. The vendor base organizes around three tiers: diversified industrial conglomerates with captive semiconductor relationships, pure-play automation specialists with deep HVAC-fire safety integration, and cloud-native entrants with subscription-based energy-as-a-service models. Consolidation pressure intensifies as facility management outsourcing firms demand unified single-pane dashboards rather than fragmented point solutions. Dominant competitive moves include strategic partnerships with semiconductor foundries and vertical integration into edge computing hardware.
Within the diversified industrial tier, Schneider Electric and Siemens occupy positions anchoring integrated energy and power management portfolios. Johnson Controls exemplifies the automation specialist archetype with concentrated expertise in environmental control and fire safety convergence. Honeywell represents the industrial conglomerate model with cross-sector technology transfer from aerospace and process automation domains.
| Leading Market Players |
|---|
| Schneider Electric |
| Lutron Electronics |
| Honeywell |
| ABB |
| Control4 |
| Johnson Controls |
| Legrand |
| Bosch |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between BACnet-verified integrated platforms and uncertified standalone controllers manifests in both pricing premiums of forty to sixty percent and supply chain configurations that favor captive semiconductor relationships for premium tiers while commodity chipset sourcing serves economy segments.
Pricing Analysis
Subscription-based energy-as-a-service contracts dominate procurement for municipal and educational portfolios, displacing capital-intensive equipment purchases. Price differentiation hinges on cybersecurity certification tiers aligned with NIST and EU NIS2 frameworks, plus remote diagnostics bundling. Cost compression in standalone controller tiers intensifies due to Taiwanese foundry capacity constraints. Facility management outsourcing firms exhibit lowest price sensitivity, prioritizing predictive maintenance uptime guarantees over per-unit hardware costs.
Supply Chain Analysis
Automation engineering talent scarcity in Germany and the United States constrains system integration capacity for complex retrofit deployments. Controller hardware production centers on Taiwan, China, and South Korea, with BACnet and Modbus chipsets drawing from concentrated foundry output. Legacy LonWorks protocol obsolescence and proprietary vendor lock-in create single-source vulnerability for infrastructure replacement cycles. Distribution runs through authorized system integrators and direct OEM channels to facility management outsourcing firms and commercial real estate investment trusts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
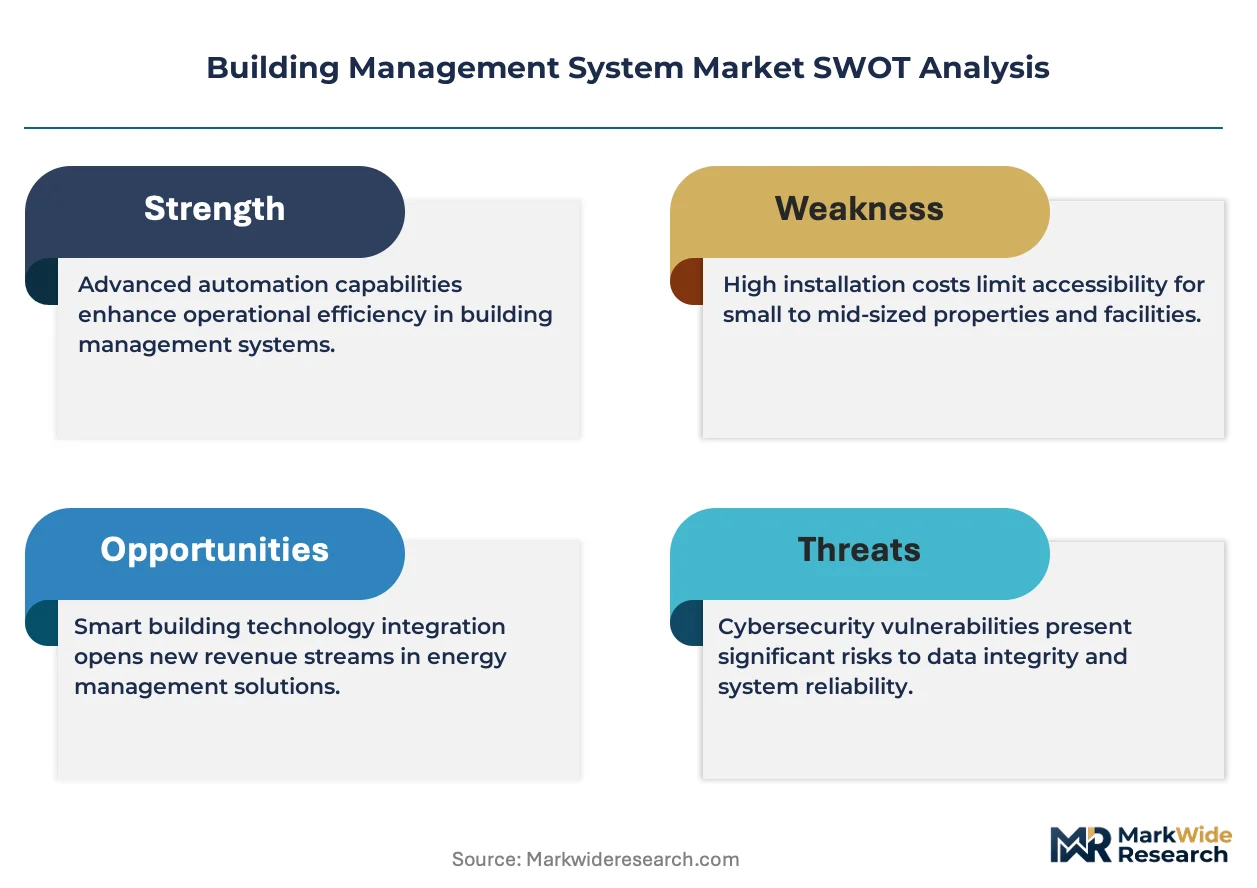
Regulatory arbitrage between Germany's KfW-subsidized retrofit financing and India's underenforced Energy Conservation Building Code creates divergent margin profiles for identical hardware-software stacks.
For Market Incumbents: Cement market position through backward integration into edge computing hardware production and captive semiconductor supply agreements that buffer Taiwanese foundry disruption. Cloud-native entrants with AI-overlay platforms threaten traditional equipment vendors; prioritize cybersecurity certification investments aligned with EU NIS2 and US NIST frameworks to defend procurement eligibility in transatlantic commercial real estate portfolios. For New Entrants and Emerging Players: Enter via India's tier-2 cities where Bureau of Energy Efficiency mandates for buildings above 100,000 square feet remain underenforced, creating first-mover positioning before compliance tightens. White-space targets include AI-analytics overlays for carbon accounting in commercial real estate investment trusts and predictive maintenance subscriptions for US public school districts. Go-to-market through facility management outsourcing firms rather than direct asset owner sales. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented legacy protocol ecosystems resist migration to open standards without full infrastructure replacement. Long-term viability favors vendors with unified single-pane dashboards spanning HVAC, lighting, security, and power subsystems. Acquisition target archetypes include edge-AI inference specialists with healthcare or data center deployment track records. Monitor EU F-Gas Regulation compliance timelines as inflection indicator for HVAC control system redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Onboard AI inference engines reduce cloud latency for sub-second HVAC demand response in data centers. |
| Cybersecurity Certification Investment | NIST and EU NIS2 alignment secures procurement eligibility across US federal and European commercial portfolios. |
| Energy-as-a-Service Contract Expansion | Performance-guaranteed subscriptions displace capital budgets in California and New York public school districts. |
| Backward Integration into Semiconductor Supply | Captive controller chipset relationships buffer Taiwanese foundry capacity exposure and compress lead times. |
| AI-Overlay Carbon Accounting Development | Real-time Scope 1 and 2 emissions tracking converges environmental compliance with commercial real estate asset valuation. |
Methodological Framework
Multiple input streams — facility director interviews, system integrator operational data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged building automation engineering directors, healthcare facility compliance officers, commercial real estate portfolio managers, KfW program administrators, and facility management outsourcing procurement leads. Secondary validation drew from EPA ENERGY STAR certification databases, EU Energy Performance of Buildings Directive disclosure filings, Bureau of Energy Efficiency enforcement records, and semiconductor trade flow customs data.
Data-stream reconciliation across deployment architecture, facility type, technology layer, and end-user authority dimensions anchored the analytical framework. Segmentation modeling incorporated product type transitions from on-premise to cloud-native architectures, application shifts in educational institutions toward subscription procurement, technology adoption curves for AI analytics at the edge, and end-user fragmentation as service providers gain operational control. CAGRs were derived from installed base growth, replacement cycle compression, and regulatory mandate enforcement timelines.
Inputs from KfW disbursement records and EPA ENERGY STAR certification databases were available through the study window; gaps in tier-2 Indian city enforcement data introduce uncertainty bands for penetration rate assumptions. Forecasts reflect documented assumptions regarding EU Green Deal renovation mandate adherence, semiconductor supply normalization, and cybersecurity framework convergence. Material deviation in F-Gas Regulation compliance timelines or Taiwanese foundry capacity utilization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Zero Energy Buildings Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Global Building Information Modeling (BIM) Market
Building Automation Systems
Global Door Closers Market
Building Automation Systems
Intelligent Building Automation Technologies Market
Building Automation Systems
Building Automation and Control System Market
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Underfloor Heating Actuator Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Smart Passenger Elevators Market
Building Automation Systems
Europe Smart Windows Market
Building Automation Systems
Electrochromic Glass Market
Building Automation Systems
Architecture Smart Glass Market