
 Tunnel and Metro Ventilation Fans Market | 2026-2036
Tunnel and Metro Ventilation Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel and Metro Ventilation Fans Market Insights
The capital-intensity divergence between integrated manufacturers and component assemblers is redrawing competitive boundaries in tunnel and metro ventilation. Howden leverages captive engineering capabilities for high-pressure axial fan systems in rail infrastructure. TLT-Turbo GmbH anchors its position through precision-machined impeller technology for underground road tunnels. Jindun competes on cost-optimized production scale serving domestic metro expansion programs.
Tunnel and metro ventilation fans are electromechanical air-movement devices engineered to maintain breathable atmospheres, control smoke propagation, and manage thermal loads in enclosed underground passages, typically achieving static pressures from 500 to 4,000 pascals and flow rates exceeding 100 cubic meters per second. These systems constitute critical life-safety infrastructure where failure modes directly impact occupant evacuation timelines during fire events. Axial fan configurations dominate high-volume, low-pressure tunnel ventilation applications where bidirectional traffic flow demands reversible airflow patterns. Jet fans are capturing share in segmental tunnel construction by eliminating ductwork and reducing civil infrastructure costs. Smart control systems with variable-speed drives concentrate margin pools through energy-recovery algorithms and predictive maintenance integration.
The European Union's F-Gas Regulation and Machinery Directive constrain refrigerant-based cooling integration and mandate fail-safe operational redundancy in underground environments. China's GB standards for metro ventilation and the US NFPA 130 standard for fixed guideway transit establish mandatory airflow capacities and emergency smoke-extraction protocols that shape product certification requirements. Stakeholders must monitor evolving fire-resistance testing protocols and carbon-accounting disclosures as procurement criteria harden across publicly funded infrastructure programs.
Market Dynamics
The Tunnel and Metro Ventilation Fans Market is undergoing structural compression as jet fan architectures eliminate ductwork requirements and civil infrastructure costs in long-bore road tunnels, while fire safety mandates harden certification barriers for equipment suppliers.
Growth Catalysts
- Asia-Pacific Metro Expansion:China's central and western provinces are accelerating underground rail construction under GB standards for metro ventilation, absorbing dominant shares of new axial fan procurement.
- EU F-Gas Regulation:Mandatory refrigerant phase-downs and fail-safe redundancy requirements are forcing infrastructure upgrades in existing European tunnel networks.
- Jet Fan Technology:Reversible airflow systems are capturing share in segmental tunnel construction by reducing civil works and enabling faster project completion timelines.
Market Restraints
- Steel and Rare Earth Input Volatility:Precision-machined impellers and high-efficiency motor laminates face cost pressure from concentrated raw material supply chains.
- Certification Timeline Friction:NFPA 130 and EN 12101 fire-resistance testing protocols extend product validation cycles by 12-18 months for new market entrants.
- Integrated Manufacturer Concentration:Captive engineering capabilities at dominant axial fan producers limit component assembler access to high-pressure rail infrastructure contracts.
Strategic Opportunities
- Smart Control System Integration:Variable-speed drives with energy-recovery algorithms are opening margin pools through predictive maintenance service contracts.
- India Underground Rail:Metro construction in Delhi, Mumbai, and Bangalore corridors under CEA electrical standards presents underpenetrated demand for reversible jet fan configurations.
- Carbon Accounting Disclosures:Procurement criteria in publicly funded EU infrastructure programs are creating specification advantages for suppliers with verified lifecycle emissions data.
Industry Challenges
- Fire-Resistance Engineering Talent Scarcity:Specialized thermal modeling and smoke propagation simulation capabilities are concentrated among legacy European and Japanese engineering consultancies.
- Legacy System Integration Complexity:Retrofitting variable-speed drives and smart sensors into 1980s-era tunnel ventilation infrastructure requires bespoke control architecture redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel and Metro Ventilation Fans Market |
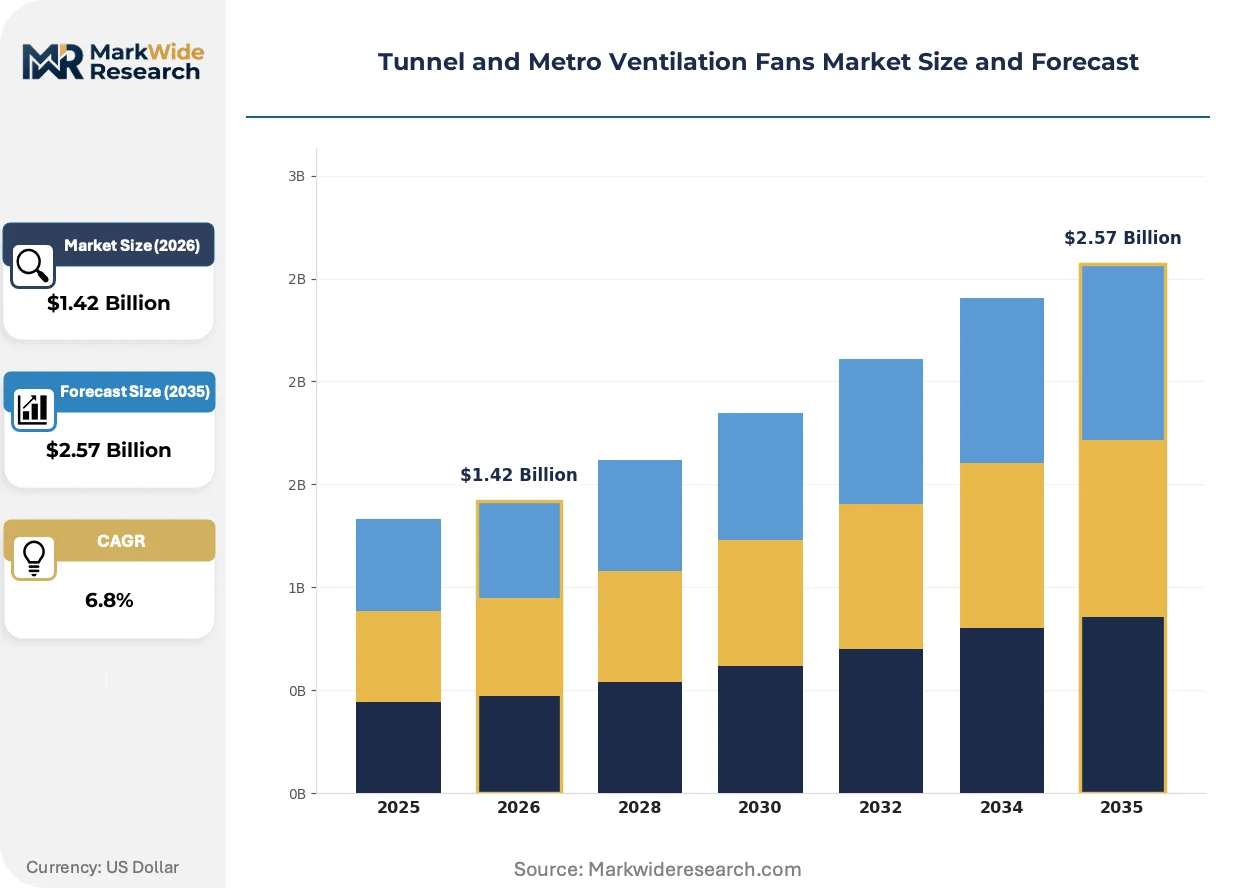
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fan Type: Axial, Centrifugal, Mixed-Flow, Jet Power Rating: Low Power, Medium Power, High Power, Variable Speed Application: Tunnel Ventilation, Station Ventilation, Emergency Ventilation, Exhaust Systems Control System: Manual Control, Automatic Control, Remote Control, Smart Systems |
| Companies Covered | Systemair, TLT-Turbo GmbH, Kruger Ventilation, WITT & SOHN, FläktGroup, Howden, Jindun, ShangFeng, Zhonglian Wind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel and Metro Ventilation Fans Market Trends and Innovations
Active reshaping in tunnel and metro ventilation centers on electromechanical system intelligence, regulatory compression of allowable failure modes, and procurement model evolution toward lifecycle performance contracting.
Jet fan technology is bifurcating the tunnel ventilation market between ducted and ductless architectures. European road tunnel authorities are specifying reversible jet configurations for new-bore projects exceeding two kilometers. This technology is bifurcating supplier margins—civil cost savings accrue to project developers while equipment manufacturers capture premium pricing on integrated control systems.
REACH chemical restrictions and the EU F-Gas Regulation are prohibiting certain refrigerant-based cooling integrations in underground environments. Machinery Directive fail-safe mandates now require redundant power supply architectures for all life-safety ventilation equipment. Rail infrastructure operators in Germany and France are responding by consolidating procurement specifications around pre-certified integrated fan-and-control packages.
Lifecycle performance contracting is displacing capital-equipment-only purchasing in publicly funded metro programs. European and Chinese transit authorities now unbundle energy consumption guarantees from hardware supply, forcing manufacturers to retain operational risk through 15-20 year service agreements. This shift is most visible in UK Crossrail-style programs and Singapore's ongoing underground network expansion.
Tunnel and Metro Ventilation Fans Market Segmentation
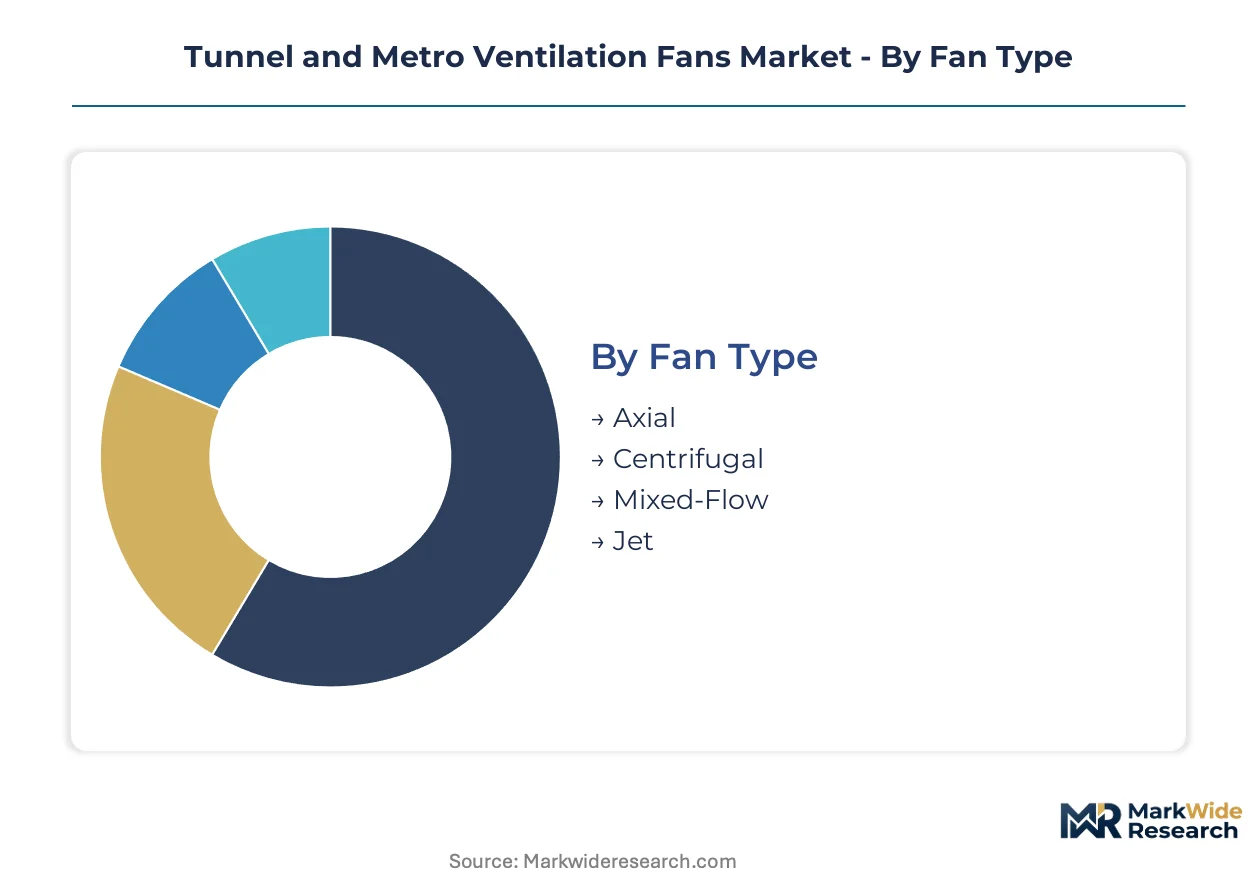
Tunnel and metro ventilation fans fragment across four technical dimensions that shape procurement patterns and supplier economics. Fan type and application determine civil engineering integration requirements, while power rating and control architecture dictate lifecycle operating costs and maintenance liability.
Fan Type:
Axial and jet configurations dominate domestic procurement in China and India, while centrifugal and mixed-flow units concentrate in European export markets where precision-machined impellers command specification premiums.
- Axial:High-volume, low-pressure electromechanical systems engineered for bidirectional reversible airflow in rail tunnels. China's GB standards for metro ventilation mandate these configurations across central and western provincial networks where construction volume concentrates.
- Jet:Ductless thrust-producing units eliminating civil infrastructure in long-bore road tunnels. European road authorities specify reversible jet configurations for projects exceeding two kilometers, capturing margin premiums through integrated control system bundling.
- Centrifugal:Radial-flow designs achieving higher static pressures for complex underground geometries. German and French rail operators specify these for station ventilation where space constraints limit axial fan deployment.
- Mixed-Flow:Hybrid aerodynamic profiles combining axial capacity with centrifugal pressure characteristics. Japanese engineering consultancies specify these for retrofit applications demanding footprint reduction in legacy tunnel infrastructure.
Axial holds the largest share; momentum sits with jet configurations as ductless architectures eliminate civil works.
Power Rating:
Power tier selection correlates directly with tunnel length and emergency smoke extraction mandates, with variable-speed drives concentrating in lifecycle performance contracts.
- High Power:Systems exceeding 200kW motor ratings for primary ventilation in high-traffic road tunnels. China's western province metro programs absorb dominant procurement volumes under stricter fire safety mandates.
- Variable Speed:Electronically commutated drives with energy-recovery algorithms enabling predictive maintenance integration. UK Crossrail-style programs and Singapore underground expansions specify these through 15-20 year service agreements.
- Medium Power:75-200kW rated equipment for secondary ventilation and thermal load management. Indian metro construction in Delhi and Mumbai corridors drives specification under CEA electrical standards.
- Low Power:Sub-75kW auxiliary systems for station platform ventilation and personnel access tunnels. Distributed across refurbishment programs in aging European networks facing EU F-Gas Regulation compliance deadlines.
High power retains volume leadership; variable speed climbs fastest as procurement shifts toward outcome-based contracting.
Application:
Application segmentation reflects divergent engineering standards between new construction and retrofit markets, with emergency systems commanding certification premiums.
- Tunnel Ventilation:Primary airflow management for vehicle exhaust dilution and fire smoke control in enclosed road and rail passages. China's accelerating metro construction absorbs dominant equipment procurement under GB ventilation standards.
- Emergency Ventilation:Fail-safe redundant systems activated during fire events to maintain evacuation pathway tenability. NFPA 130 and EN 12101 certification requirements extend validation cycles by 12-18 months, hardening barriers for new market entrants.
- Station Ventilation:Platform and concourse air quality management for passenger comfort and thermal regulation. Indian underground rail expansion in Bangalore and Mumbai corridors presents underpenetrated specification opportunities.
- Exhaust Systems:Localized extraction for maintenance bays, equipment rooms, and service corridors. Concentrated in European refurbishment programs where REACH chemical restrictions prohibit certain refrigerant-based cooling integrations.
Tunnel ventilation commands the largest equipment volume; emergency systems gain specification weight as fire-resistance testing protocols harden.
Control System:
Control architecture segmentation tracks the shift from electromechanical switching toward integrated building management systems, with smart configurations concentrating margin in service contracts.
- Smart Systems:Sensor-networked architectures with predictive maintenance algorithms and energy-recovery optimization. European transit authorities unbundle consumption guarantees from hardware supply, forcing manufacturers to retain operational risk.
- Automatic Control:Pre-programmed response sequences triggered by fire detection or traffic monitoring inputs. China's metro expansion programs specify these for central and western provincial networks under standardized procurement frameworks.
- Remote Control:Centralized operator interfaces enabling real-time adjustment from traffic management centers. German and French rail infrastructure operators consolidate specifications around pre-certified integrated fan-and-control packages.
- Manual Control:Direct operator intervention systems for maintenance modes and emergency override. Persists in legacy 1980s-era tunnel infrastructure where retrofitting variable-speed drives requires bespoke control architecture redesigns.
Smart systems represent the steepest expansion trajectory; automatic control retains installed base dominance across Asian metro construction programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese metro authorities exhibit the lowest price elasticity as fire safety mandates harden under GB standards, while Indian procurement remains acutely cost-sensitive under CEA electrical frameworks. European buyers occupy a middle tier, balancing lifecycle performance against upfront capital constraints imposed by EU F-Gas Regulation compliance deadlines.
China
Central and western provincial governments are accelerating underground rail construction through Chengdu, Xi'an, and Chongqing corridors. GB standards for metro ventilation mandate fail-safe redundancy and emergency smoke extraction protocols that eliminate low-cost equipment options. Sichuan-Chongqing economic zone absorbs dominant procurement volumes for high-pressure axial fan systems.
India
Delhi Metro Rail Corporation and Mumbai Metro expansion programs are driving specification volumes for reversible jet fan configurations. CEA electrical standards govern power rating certifications, compressing validation timelines relative to European protocols. Bangalore and Hyderabad corridors present underpenetrated demand as state governments unbundle station ventilation from tunnel ventilation contracts.
Germany
Federal Ministry of Transport infrastructure programs prioritize retrofit of 1980s-era road tunnels under Machinery Directive fail-safe mandates. KBA vehicle safety authority specifications influence ventilation performance requirements for high-traffic Alpine transit corridors. Bavaria and Baden-Württemberg concentrate equipment procurement for Stuttgart 21 and Munich S-Bahn tunnel extensions.
United Kingdom
Crossrail-style lifecycle performance contracting has displaced capital-equipment-only purchasing across Transport for London procurement frameworks. Health and Safety Executive fire-resistance testing protocols extend product validation cycles, hardening barriers for non-European suppliers. Greater London Authority carbon accounting disclosures create specification advantages for vendors with verified lifecycle emissions data.
United States
Federal Transit Administration capital investment grants are channeling funds toward legacy system ventilation upgrades in Boston and New York City subway networks. NFPA 130 standard for fixed guideway transit establishes mandatory airflow capacities that shape product certification requirements. Port Authority of New York and New Jersey specifications are consolidating around pre-certified integrated fan-and-control packages.
Tunnel and Metro Ventilation Fans Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive engineering capabilities determining access to high-pressure rail infrastructure contracts. The market structure compresses into three strategic archetypes: European precision-machined impeller specialists, Chinese cost-optimized volume producers, and diversified industrial conglomerates with captive ventilation divisions. Competitive moves concentrate on backward integration into motor laminates and precision casting, alongside 15-20 year service agreement bundling to capture lifecycle revenue streams.
Within the European specialist tier, TLT-Turbo GmbH and WITT & SOHN exemplify precision-engineering positioning anchored to German regulatory compliance requirements. Howden occupies a position representing diversified industrial conglomerate architecture with captive engineering capabilities spanning multiple infrastructure verticals. Jindun and ShangFeng sit within the Chinese volume-producer archetype, competing on production scale serving domestic metro expansion programs under standardized GB procurement frameworks.
| Leading Market Players |
|---|
| Systemair |
| TLT-Turbo GmbH |
| Kruger Ventilation |
| WITT & SOHN |
| FläktGroup |
| Howden |
| Jindun |
| ShangFeng |
| Zhonglian Wind |
| Others |
Pricing and Supply Chain Analysis
Lifecycle performance contracting with 15-20 year service obligations locks in supply access for precision-machined impellers and variable-speed drive assemblies while compressing price visibility for component assemblers excluded from integrated fan-and-control packages.
Pricing Analysis
After-sales service revenue from predictive maintenance contracts and energy-consumption guarantees now exceeds hardware margins for leading axial fan suppliers. Pricing stratifies across premium, standard, and economy tiers based on GB standard certification grade and captive motor laminate production. Cost compression in medium-power configurations is intensifying because Indian metro authorities unbundle station ventilation contracts under CEA electrical frameworks. State-owned Chinese rail operators exhibit the lowest price sensitivity; private European road tunnel developers retain acute capital constraints.
Supply Chain Analysis
Rare earth element processing in China and Vietnam underwrites permanent magnet supply for high-efficiency motor laminates across the industry. Precision-machined impeller production draws from German and Japanese specialty steel mills; aluminum alloy castings feed from Chinese foundries serving domestic metro programs. Single-source vulnerability concentrates in NdFeB magnet supply chains subject to export licensing protocols. Distribution runs through EPC contractors and rail infrastructure OEMs rather than direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and energy-performance guarantees expand faster than standalone equipment sales, particularly in UK Crossrail-style programs and Singapore underground expansions.
For Market Incumbents: Secure captive supply of rare earth magnet laminates through backward integration or long-term offtake agreements with Chinese processors. Deepen vertical integration into precision casting capabilities to defend margin position against emerging Chinese volume producers capturing share in Indian metro corridors under CEA electrical standards. For New Entrants and Emerging Players: Lead with smart control system integration targeting 1980s-era European tunnel retrofit programs where legacy infrastructure demands bespoke sensor-network architectures. Bangalore and Hyderabad metro corridors present the most penetrable geography given unbundled procurement frameworks and compressed validation timelines relative to NFPA 130 jurisdictions. For Investors and Strategic Acquirers: Capital is best deployed toward precision-machined impeller specialists with EN 12101 pre-certification and established relationships with German KBA and French rail safety authorities. The inflection signal to monitor is consolidation of European procurement specifications around integrated fan-and-control packages, which would accelerate margin capture by engineering-capable incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Laminates | Captive NdFeB magnet supply insulates margin from Chinese export licensing volatility. |
| Lifecycle Performance Contracting | 15-20 year service agreements with Transport for London shift operational risk to manufacturers. |
| Smart Control System Development | Predictive maintenance algorithms open recurring revenue streams in Singapore underground expansion. |
| EN 12101 Pre-Certification Investment | Fire-resistance testing compliance hardens barriers against non-European competitors in Alpine corridors. |
| India Metro Corridor Targeting | Delhi and Mumbai expansion programs under CEA standards reward faster validation cycles. |
Research Methodology
Desk research of EU F-Gas Regulation compliance filings, Chinese GB standard procurement databases, and NFPA 130 technical documentation preceded structured interviews with metro ventilation engineering directors, EPC contractor procurement leads, rail infrastructure OEM technical specialists, and aftermarket service heads. Primary fieldwork across tunnel construction sites in Germany, China, and India combined with customs trade data and industrial fan shipment records to enable bottom-up and top-down triangulation.
Variance decomposition across fan type, power rating, application, and control architecture segments shaped the analytical framework throughout the forecast period. CAGRs were derived from installed base growth rates, replacement cycle analysis, and new-build project pipelines. Jet fan adoption curves in European road tunnels and variable-speed drive penetration in lifecycle contracts served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement, Chinese GB standard implementation, and US NFPA 130 adherence; material policy shifts in refrigerant phase-down timelines or fire-resistance testing protocols would require re-modeling. Practitioners should keep alternative scenarios live as rare earth export licensing conditions and carbon-accounting disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Gas Wall Hung Boilers Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Marine HVAC Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Cooling Tower Fans Market