
 Hospital HVAC Systems Market | 2026-2036
Hospital HVAC Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital HVAC Systems Market Analytics
The hospital HVAC equipment landscape is pivoting sharply between premium systems with real-time air quality monitoring and commodity units lacking integrated filtration diagnostics. Trane Technologies plc leverages its chiller portfolio to anchor high-reliability contracts with major health systems. Daikin Industries Ltd. specializes in variable refrigerant flow configurations for surgical suites. Johnson Controls International plc competes through smart building integration that unifies HVAC with fire safety and access systems.
Hospital HVAC systems encompass climate control equipment engineered to maintain precise temperature, humidity, and airborne particulate thresholds critical for patient safety and surgical sterility. These installations typically achieve MERV 14-16 filtration with 15-25 air changes per hour in operating theaters, using chilled water or direct expansion architectures to manage thermal loads across isolation wards, pharmacies, and imaging suites. Air handling units dominate retrofit budgets as facilities prioritize single-pass HEPA configurations over recirculating designs. Energy recovery ventilation is displacing conventional economizer cycles in new construction, driven by utility rebate structures and operational cost scrutiny. Smart controls represent the fastest-expanding technology segment, though hydronic systems still command the largest installed base in legacy general hospitals.
ASHRAE Standard 170 governs ventilation rates in US healthcare facilities, while the EPA enforces refrigerant phase-down timelines that reshape equipment procurement decisions. The EU Green Deal and F-Gas Regulation compel European hospitals to abandon high-GWP refrigerants, accelerating replacement cycles across Germany, France, and Italy. Stakeholders must weigh total cost of ownership against compliance deadlines as regulatory thresholds tighten and energy benchmarking becomes mandatory for hospital accreditation.
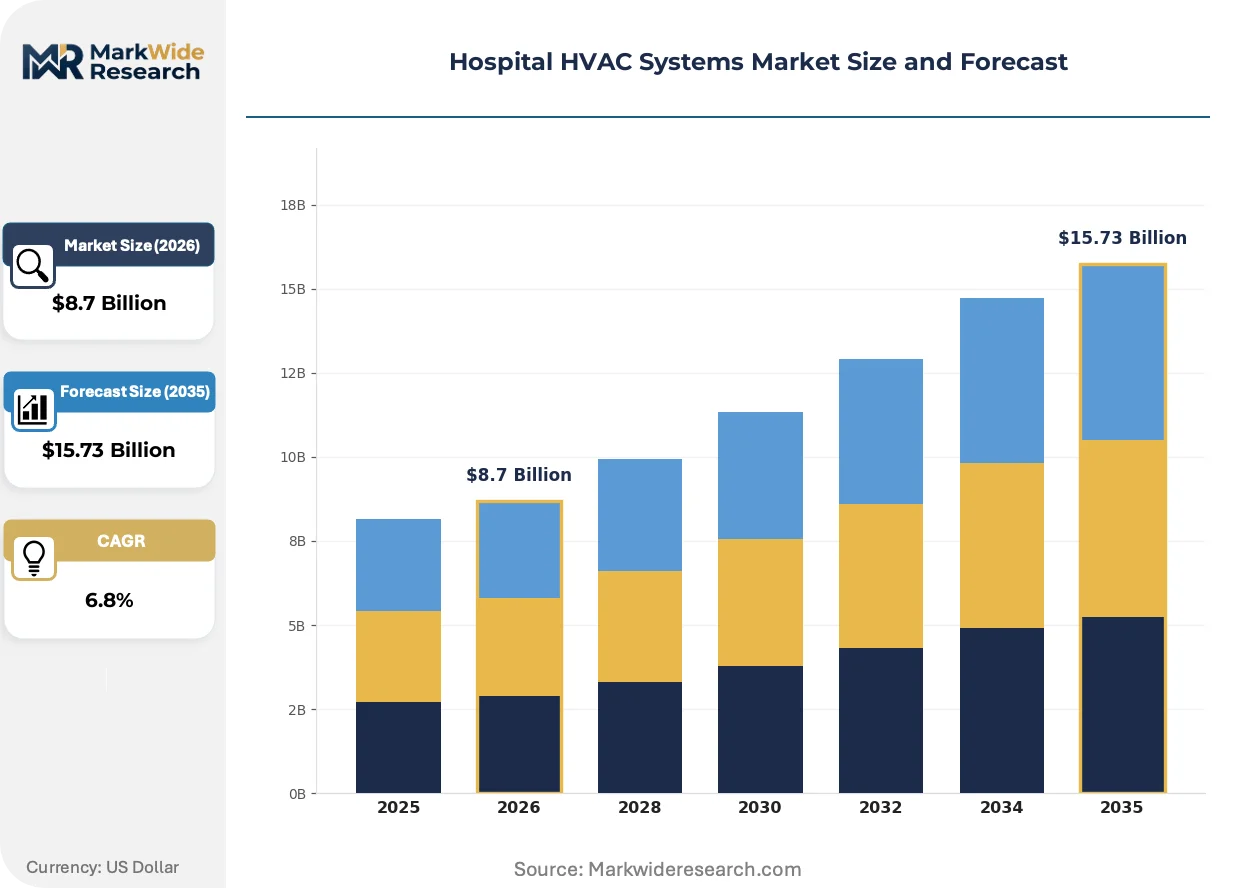
Market Dynamics
The hospital HVAC market pivots on the collision between ASHRAE Standard 170's ventilation mandates and the capital constraints facing mid-sized general hospitals. Facilities must achieve 15-25 air changes per hour in critical care zones while legacy chilled water infrastructure ages past design life. Energy recovery ventilation is compressing payback periods for upgrade decisions.
Growth Catalysts
- ASHRAE Standard 170:The ventilation benchmark mandates HEPA filtration and pressure differentials in US healthcare facilities, forcing replacement of recirculating air handling units with single-pass configurations.
- EU F-Gas Regulation:The refrigerant phase-down compels German, French, and Italian hospitals to abandon high-GWP equipment, accelerating full-system retrofits ahead of compliance deadlines.
- Energy Recovery Ventilation:Heat exchanger technology captures exhaust thermal energy, cutting operational costs for 24/7 clinical environments and qualifying installations for utility rebate programs.
Market Restraints
- Copper and aluminum price volatility:Raw material swings compress margins on coil and heat exchanger production, forcing manufacturers to index contracts or absorb cost spikes.
- Specialized contractor concentration:Certified healthcare HVAC installation capacity clusters in major metropolitan markets, creating bottlenecks for rural hospital projects.
- Refrigerant compatibility lock-in:Existing chiller architectures constrain transition paths to low-GWP alternatives, extending replacement cycles beyond optimal efficiency timelines.
Strategic Opportunities
- Japan's hospital modernization wave:Aging demographic pressure and METI efficiency standards drive replacement demand in Tokyo, Osaka, and Nagoya health systems.
- Smart building convergence:Integration of HVAC controls with fire safety and access management systems creates bundled procurement opportunities for integrated facility management contracts.
- Modular air handling units:Prefabricated, skid-mounted configurations slash on-site construction time for expansion projects and emergency surge capacity installations.
Industry Challenges
- Certified commissioning engineer shortage:ASHRAE 170 compliance requires specialized testing, adjusting, and balancing expertise that outpaces vocational training program output.
- Phased renovation coordination:Live hospital environments demand temporary HVAC bridging without interrupting critical care zones, multiplying project complexity and risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital HVAC Systems Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Handling Units, Ductless Systems, Exhaust Fans End User: General Hospitals, Specialty Clinics, Long-term Care Facilities, Surgical Centers Installation: New Construction, Retrofit, Expansion, Upgrades Technology: Energy Recovery Ventilation, Smart Controls, Variable Refrigerant Flow, Hydronic Systems |
| Companies Covered | Trane Technologies plc, Lennox International Inc., Carrier Corporation, Haier Group Corporation, Mitsubishi Electric Corporation, Daikin Industries Ltd., LG Electronics Inc., Rheem Manufacturing Company, Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital HVAC Systems Market Evolving Landscape
Digital twin modeling and predictive maintenance algorithms are compressing equipment lifecycle costs. Manufacturers now embed IoT sensors as standard rather than premium options. The competitive frontier has shifted from hardware specifications to software-enabled service contracts.
Ultraviolet-C germicidal irradiation is overtaking traditional filtration as the primary airborne pathogen control layer in US surgical suites. The technology neutralizes viable organisms in a single pass through air handling units. Major health systems in Texas and California are specifying UV-C retrofits on existing AHUs ahead of full replacement cycles.
The EPA's refrigerant phase-down timeline under the AIM Act is forcing procurement departments to specify equipment compatible with R-454B and R-1234ze alternatives. Chiller manufacturers must re-engineer compressor architectures and safety systems for mildly flammable refrigerants. General hospitals in Florida and Arizona face accelerated replacement windows due to cooling-dominated load profiles.
Integrated service contracts now bundle equipment, installation, and decade-long maintenance into single-line procurement. Health system CFOs favor predictable operational expenditures over capital outlays. This financing preference is most pronounced in Germany's Krankenhaus sector, where energy performance contracting has captured significant retrofit volume.
Hospital HVAC Systems Market Segmentation
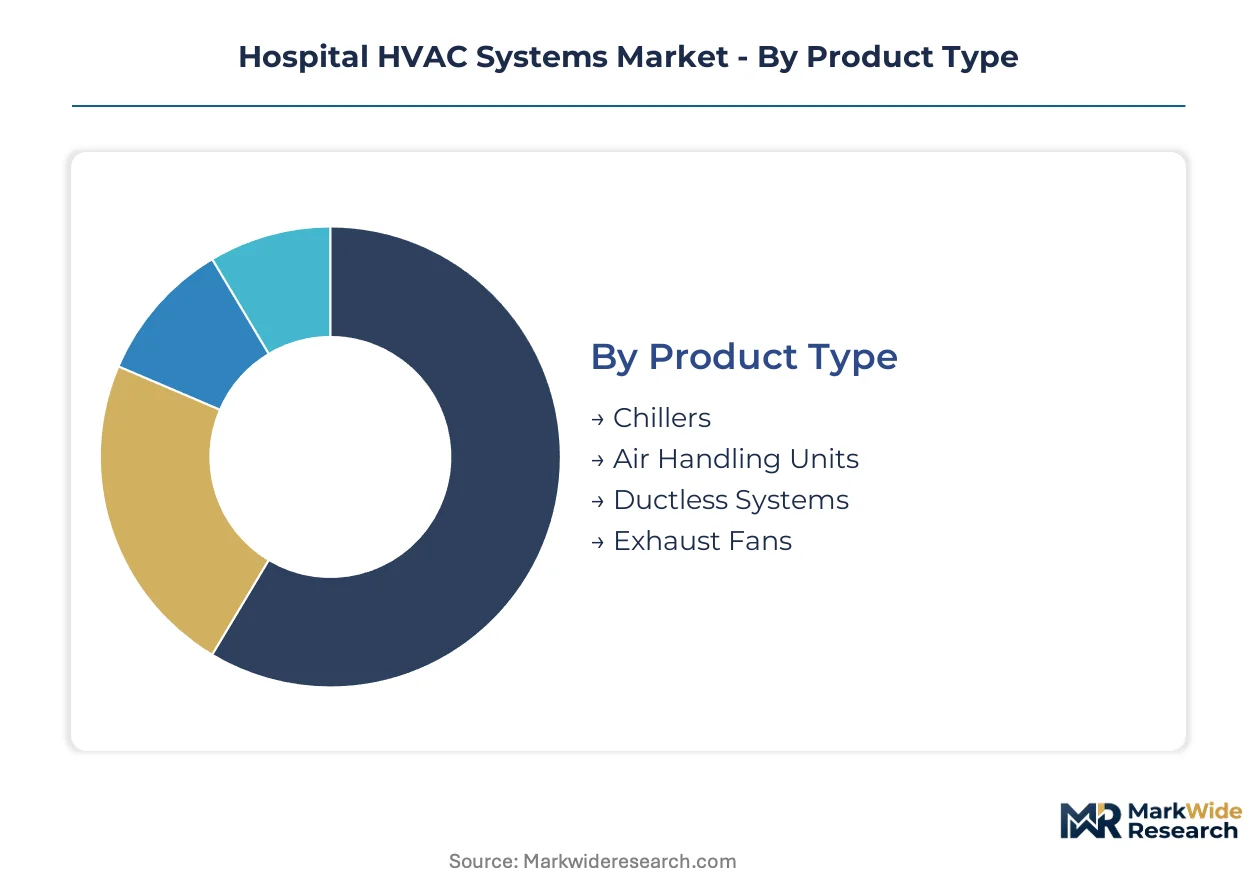
Hospital HVAC procurement splits sharply between standalone equipment purchases and integrated building systems. Understanding where each segment sits on this integration spectrum clarifies why some categories command premium pricing while others face commodity pressure.
Product Type:
Standalone units dominate initial procurement for budget-constrained facilities, while embedded configurations anchor integrated health system contracts.
- Chillers:Centralized chilled water plants serve as thermal anchors for multi-building hospital campuses, typically specified with N+1 redundancy. Demand concentrates in the United States and Germany where aging infrastructure replacement cycles accelerate under ASHRAE and EU F-Gas deadlines. These systems face the steepest refrigerant transition costs as R-1234ze and R-454B compatibility becomes mandatory.
- Air Handling Units:Single-pass HEPA configurations are displacing recirculating designs in US operating theaters under ASHRAE Standard 170 pressure. Texas and California health systems specify UV-C germicidal irradiation integration as standard. Volume placements concentrate in retrofit projects where existing ductwork constraints limit chiller alternatives.
- Ductless Systems:Variable refrigerant flow mini-splits serve isolation rooms and satellite clinics requiring zonal temperature control without central plant infrastructure.
- Exhaust Fans:Dedicated exhaust systems maintain negative pressure in infectious disease wards and laboratories, specified for 24/7 operation with redundant motor configurations.
Volume placements concentrate in Air Handling Units; the faster expansion belongs to Chillers as refrigerant phase-downs force full-system replacement.
End User:
Capital availability and regulatory scrutiny create divergent procurement patterns across facility types, with acute care settings absorbing premium system costs.
- General Hospitals:Comprehensive clinical environments require simultaneous compliance with ASHRAE Standard 170 ventilation mandates and Joint Commission accreditation standards. These facilities allocate the largest capital budgets to HVAC, prioritizing 15-25 air changes per hour in surgical suites and ICUs. German Krankenhaus operators increasingly favor energy performance contracting to convert capital outlays into operational expenditures.
- Surgical Centers:Ambulatory facilities concentrate investment in operating theater climate precision, often specifying variable refrigerant flow for rapid temperature recovery between procedures. Standalone surgical centers in Florida and Arizona face compressed replacement windows due to cooling-dominated load profiles and EPA refrigerant timelines.
- Specialty Clinics:Outpatient facilities prioritize zonal control for imaging suites and procedure rooms, typically specifying ductless configurations to avoid central plant construction.
- Long-term Care Facilities:Extended care settings emphasize resident comfort and energy efficiency over surgical-grade filtration, driving demand for smart controls and energy recovery ventilation.
Capital deployment concentrates in General Hospitals; the steepest expansion trajectory belongs to Surgical Centers as outpatient volume migrates from inpatient settings.
Installation:
Project type determines contractor specialization requirements and financing structure, with live-facility work commanding risk premiums.
- New Construction:Greenfield hospitals specify integrated digital twin modeling and predictive maintenance architectures from foundation phase. These projects capture energy recovery ventilation and smart controls as baseline rather than upgrade. METI efficiency standards in Japan drive specifications for heat pump chillers and advanced economizer cycles in Tokyo and Osaka health systems.
- Retrofit:Live-facility replacement demands temporary HVAC bridging without interrupting critical care zones, multiplying project complexity. ASHRAE 170 compliance requires specialized testing, adjusting, and balancing expertise that outpaces vocational training program output. Rural US hospitals face contractor availability bottlenecks for certified healthcare installation.
- Expansion:Modular air handling units reduce on-site construction time for emergency surge capacity additions and pandemic preparedness infrastructure.
- Upgrades:Component-level improvements target refrigerant transition and filtration enhancement without full system replacement, common in facilities with recent chiller investments.
Project volume concentrates in Retrofit; the fastest share gain belongs to New Construction as Japan's hospital modernization wave accelerates.
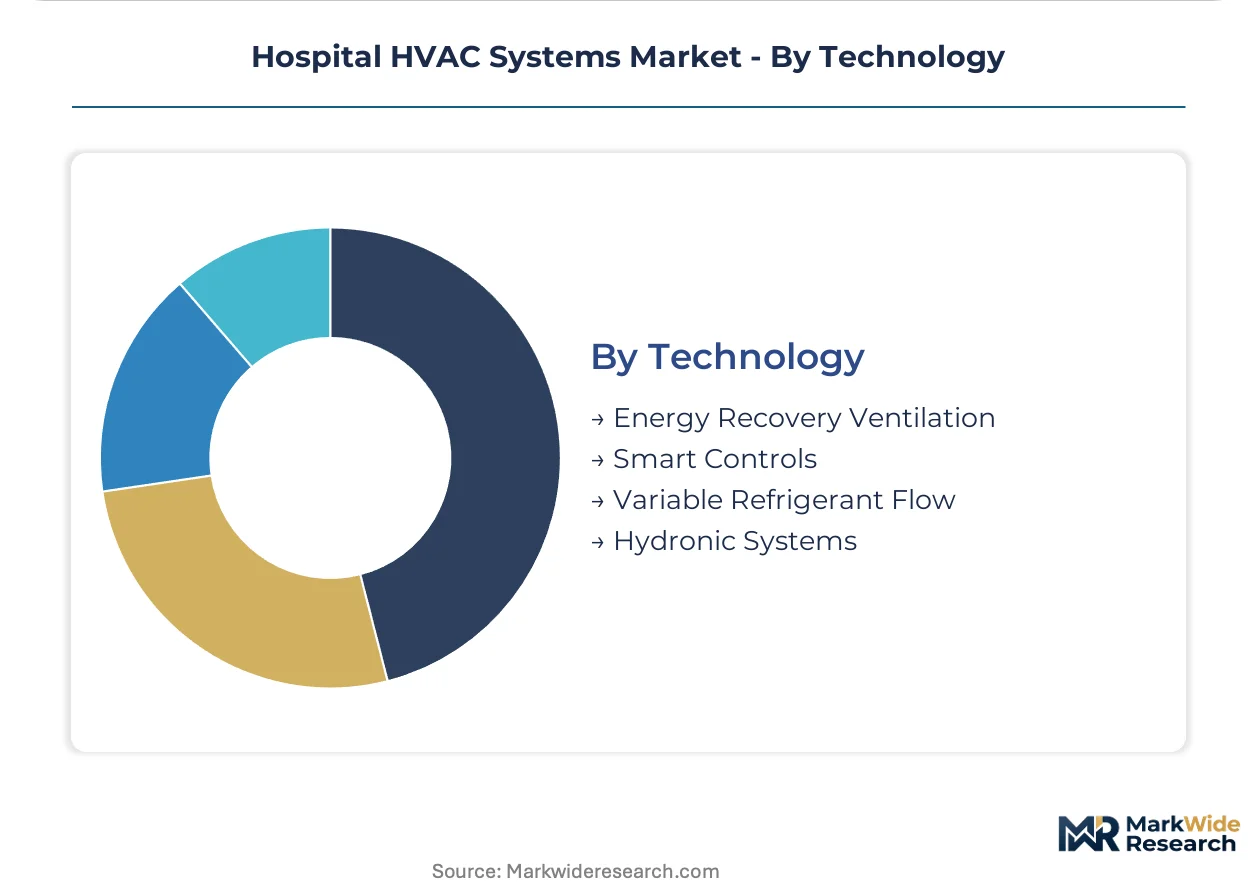
Technology:
Technology selection tracks facility digital maturity, with connected systems requiring cybersecurity infrastructure and staff training investment.
- Energy Recovery Ventilation:Heat exchanger technology captures exhaust thermal energy, cutting operational costs for 24/7 clinical environments. German and French hospitals qualify installations for utility rebate programs under EU Green Deal efficiency benchmarks. These systems compress payback periods for upgrade decisions in high-energy-cost markets.
- Smart Controls:IoT-enabled building automation unifies HVAC with fire safety and access management, creating bundled procurement opportunities. Manufacturers embed sensors as standard rather than premium options, shifting competitive frontier to software-enabled service contracts. Health system CFOs favor predictable operational expenditures through integrated service agreements.
- Variable Refrigerant Flow:Zonal refrigerant distribution serves surgical suites requiring precise temperature recovery and individual room control without dedicated air handlers.
- Hydronic Systems:Legacy chilled water and hot water distribution maintains the largest installed base in general hospitals, constraining transition paths to low-GWP alternatives.
Installed base concentrates in Hydronic Systems; the steepest technology climb belongs to Smart Controls as digital twin modeling becomes standard specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the most concentrated hospital HVAC modernization activity, with Osaka and Nagoya health systems driving replacement demand under METI efficiency mandates. German Krankenhaus operators and US metropolitan health systems follow as regulatory deadlines compress procurement timelines.
United States
Texas and California health systems specify UV-C germicidal irradiation as standard for surgical suite retrofits. EPA refrigerant phase-down timelines under the AIM Act force accelerated replacement windows in Florida and Arizona cooling-dominated markets. ASHRAE Standard 170 mandates HEPA filtration and pressure differentials, compelling single-pass air handling unit configurations across major metropolitan hospital networks.
Germany
Krankenhaus operators favor energy performance contracting to convert capital HVAC outlays into operational expenditures. EU F-Gas Regulation compels abandonment of high-GWP refrigerants, accelerating full-system retrofits ahead of compliance deadlines. Berlin and Munich health systems concentrate procurement of heat pump chillers and advanced economizer cycles under EU Green Deal efficiency benchmarks.
Japan
Aging demographic pressure and METI efficiency standards drive replacement demand across Tokyo, Osaka, and Nagoya health systems. Hospital modernization waves prioritize heat pump chillers and smart building integration. Kanto and Kansai regions concentrate the steepest technology upgrades as facilities replace infrastructure installed during the 1980s construction boom.
France
Paris and Lyon hospital networks qualify energy recovery ventilation installations for utility rebate programs under EU Green Deal frameworks. ANSM oversight of healthcare facility accreditation tightens ventilation benchmarks for surgical sterility. French procurement departments specify equipment compatible with R-454B and R-1234ze alternatives ahead of F-Gas Regulation deadlines.
Italy
Milan and Rome health systems face compressed replacement cycles as aging chilled water infrastructure exceeds design life. EU F-Gas Regulation reshapes equipment procurement decisions across Lombardy and Lazio regions. Italian facilities prioritize modular air handling units to reduce on-site construction time for emergency surge capacity additions.
Hospital HVAC Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across refrigerant transition readiness and smart building integration depth. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with full-system portfolios, specialized climate control pure-plays with surgical-grade expertise, and electronics manufacturers leveraging sensor and control technologies. Dominant competitive moves include vertical integration into predictive maintenance software and geographic expansion through energy performance contracting vehicles.
Among diversified industrial conglomerates, Trane Technologies plc and Carrier Corporation exemplify full-system portfolio breadth, while Daikin Industries Ltd. occupies a position within the specialized climate control tier. Johnson Controls International plc anchors the smart building convergence segment where HVAC integration with fire safety and access management creates bundled procurement opportunities. These named entities represent distinct competitive positioning vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Trane Technologies plc |
| Lennox International Inc. |
| Carrier Corporation |
| Haier Group Corporation |
| Mitsubishi Electric Corporation |
| Daikin Industries Ltd. |
| LG Electronics Inc. |
| Rheem Manufacturing Company |
| Johnson Controls International plc |
| Others |
Value Network & Pricing Analysis
Family-owned HVAC component specialists in Germany and Japan anchor coil and compressor manufacturing, translating concentrated ownership into pricing discipline through long-term service contracts and captive maintenance revenue streams. Their financing preference for operational expenditure models reinforces supply-side bargaining power against capital-constrained hospital procurement departments.
Pricing Analysis
Uptime-guarantee contracts serve as the value-based pricing anchor, with manufacturers charging premiums for systems promising 99.9% availability in surgical suites. Three-tier pricing structure across premium, standard, and economy levels separates ASHRAE 170-certified configurations from commodity units lacking HEPA integration. Pricing pressure stems from copper and aluminum volatility forcing manufacturers to absorb margin compression or index contracts. General hospitals exhibit highest price sensitivity due to capital budget constraints, while surgical centers prioritize performance over cost.
Supply Chain Analysis
Ocean freight cost spikes from Asia-Pacific manufacturing hubs to US East Coast ports compress margins on bulky air handling units and chiller assemblies. Production concentrates in China, South Korea, and Germany for compressors, heat exchangers, and control systems. Supply chains draw from copper coil stock, aluminum fin stock, and rare-earth magnet dependencies. Single-source vulnerability sits with semiconductor components for smart control systems. Distribution runs through certified healthcare HVAC contractors rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
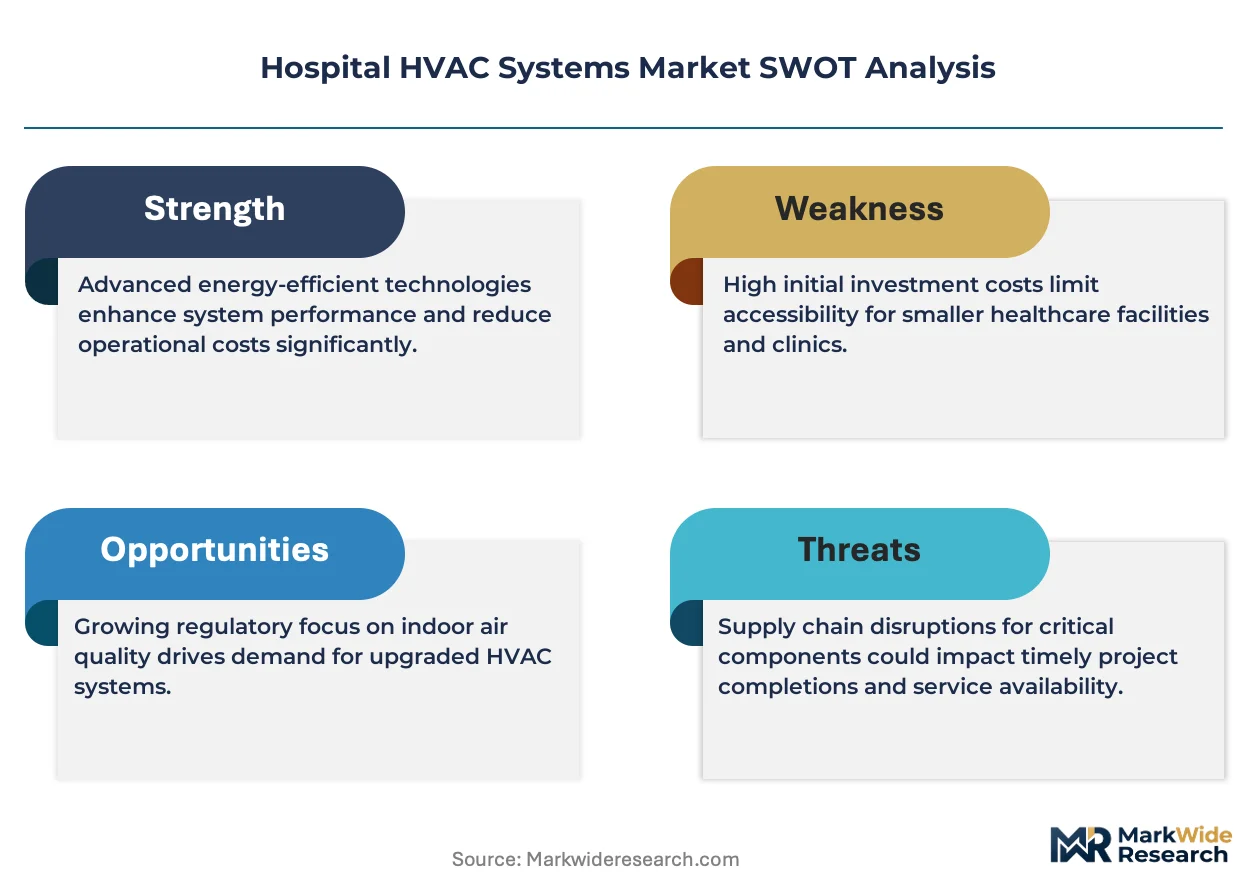
This market reads as a cost-of-compliance story where ASHRAE Standard 170 ventilation mandates create a barrier-to-entry moat for certified players capable of delivering 15-25 air changes per hour with documented pressure differential performance.
For Market Incumbents: Cement market position through backward integration into predictive maintenance software and IoT sensor manufacturing, capturing recurring revenue streams that offset hardware margin compression. Acquire certified commissioning engineering firms in Texas and California to address the vocational training bottleneck constraining installation capacity. Threat substitution from UV-C germicidal irradiation retrofits demands rapid AHU portfolio refresh. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer the lowest-friction entry vector, bypassing concentrated contractor networks that block traditional channel access. Target rural US hospital retrofits where certified installation capacity shortages create service gaps. Energy performance contracting vehicles in Germany's Krankenhaus sector present the most penetrable financing structure for unbundled equipment-plus-service offerings. For Investors and Strategic Acquirers: METI efficiency standard acceleration in Japan is the leading indicator that heat pump chiller replacement cycles are compressing from fifteen-year to ten-year intervals. Long-term viability favors vertically integrated manufacturers with captive refrigerant transition capabilities and smart building convergence expertise. Watch for EPA refrigerant phase-down enforcement intensity as the signal for US replacement window timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Engineering | R-454B and R-1234ze compatibility investments lock in EPA compliance ahead of AIM Act deadlines. |
| Smart Building Integration | Unified HVAC-fire safety-access control platforms capture bundled procurement from health system CFOs. |
| Energy Performance Contracting | Operational expenditure conversion unlocks German Krankenhaus retrofit volume through guaranteed savings structures. |
| Modular AHU Prefabrication | Skid-mounted configurations slash on-site construction time for emergency surge capacity installations. |
| Predictive Maintenance Software | Digital twin modeling compresses lifecycle costs and anchors decade-long service agreements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital facilities directors, HVAC contractor principals, biomedical engineers, and GPO contracts managers. ASHRAE Standard 170 compliance documentation, EPA AIM Act implementation guidance, and EU F-Gas Regulation enforcement schedules formed the regulatory backbone. Customs records tracking copper and aluminum coil imports, alongside hospital procurement database analysis, enabled bottom-up equipment placement triangulation against top-down market sizing.
Data-stream reconciliation across manufacturer shipment reports, health system capital expenditure disclosures, and contractor backlog surveys calibrated volume estimates across the projection horizon. Segmentation modeling captured product type splits, end-user facility categories, installation project types, and technology adoption patterns. CAGRs derived from historical replacement cycle analysis, regulatory deadline compression effects, and energy cost trajectory assumptions. Refrigerant phase-down timelines and METI efficiency standard enforcement intensity served as industry-specific forecast sensitivity inputs.
The model holds under stable copper and aluminum pricing and consistent ASHRAE 170 enforcement; deviation in raw material volatility or regulatory delay would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
North America Residential Ductwork Design Software Market
HVAC Systems
Europe Residential Heat Pump Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Commercial Kitchen Ventilation System Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
HVAC Control System Market