
 Global BOPET Packaging Films Market | 2026-2036
Global BOPET Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global BOPET Packaging Films Market Intelligence
Demand from large-scale consumer goods manufacturers seeking standardized, high-volume films is bifurcating from demand by niche pharmaceutical firms requiring specialized, high-barrier coated films. Jindal Poly Films Limited leverages its massive production scale to serve the high-volume segment. In contrast, DuPont Teijin Films specializes in advanced, high-performance films for technical applications like electrical insulation. Toray Industries competes across both segments with a broad portfolio and significant R&D investment.
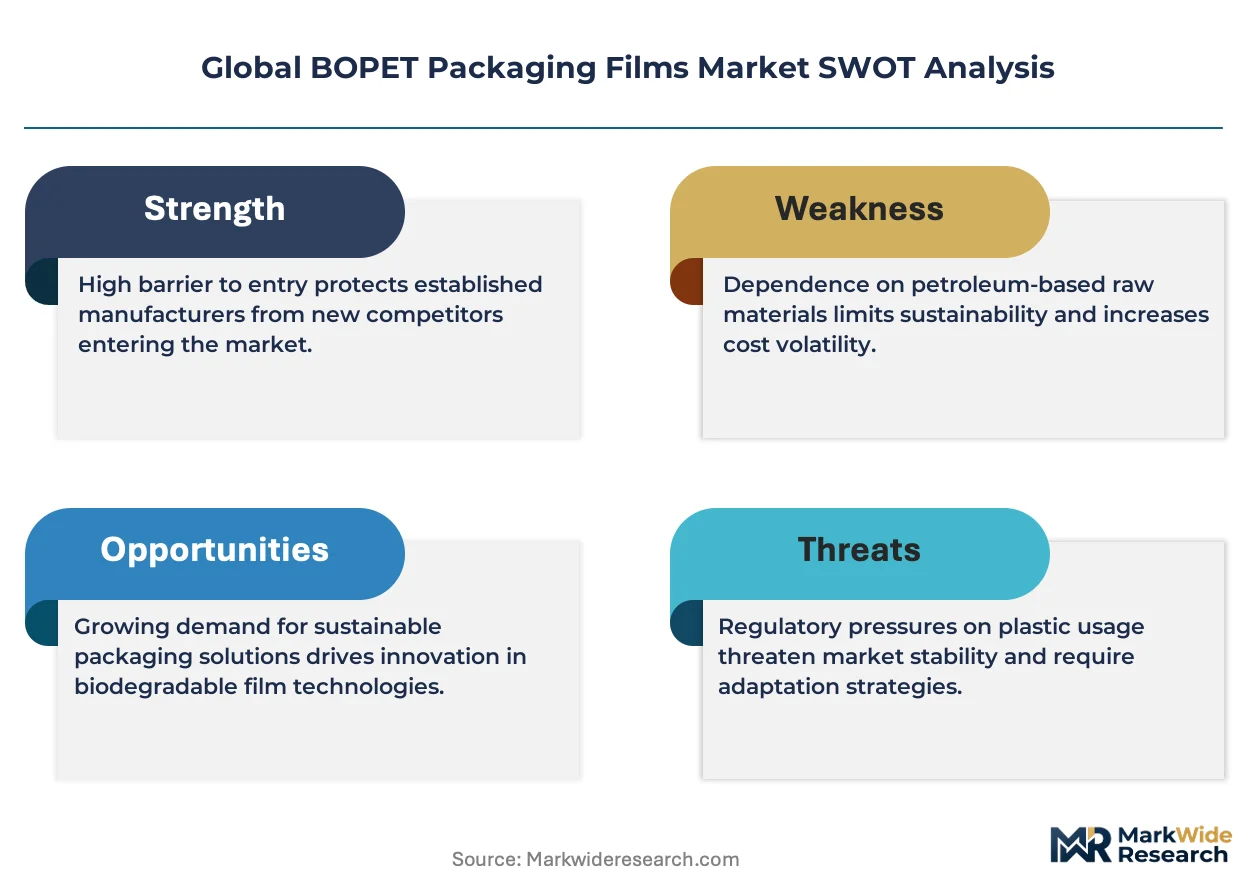
Biaxially-oriented polyethylene terephthalate (BOPET) packaging film is a polyester material stretched in two perpendicular directions to enhance its properties. This process imparts exceptional tensile strength, chemical stability, and gas barrier characteristics, making it ideal for protecting sensitive products. Transparent BOPET films for food packaging applications constitute the largest volume segment. However, metallized and coated BOPET films used in high-barrier pharmaceutical packaging and electronics are showing the fastest value growth.
Food contact material regulations, such as those from the US FDA and the European Food Safety Authority (EFSA), govern material composition and migration limits. Additionally, sustainability directives like the EU Green Deal and China's dual carbon goals are pushing for films with higher recycled content and better end-of-life recyclability. Navigating the trade-offs between performance, cost, and compliance with evolving circular economy mandates remains the central challenge for film producers and converters.
Market Dynamics
The central dynamic is the conflict between the need for high-performance barrier properties in packaging and the escalating regulatory pressure for circularity. This tension is forcing innovation in mono-material design and recycled content integration across the BOPET film industry.
Growth Catalysts
- Pharmaceutical Demand:Growth in high-barrier blister packs for moisture-sensitive drugs is driven by stricter stability requirements for advanced APIs.
- Sustainability Mandates:The EU Green Deal and similar policies promote mono-material structures, creating pull for innovative, recyclable BOPET film designs.
- Asian Export Growth:Concentrated demand in India and Vietnam for flexible food packaging to serve export markets in Europe and North America.
Market Restraints
- Feedstock Volatility:Price fluctuations in purified terephthalic acid (PTA) and monoethylene glycol (MEG) create cost instability for film producers.
- Recycled Content Trade-offs:Incorporating high levels of post-consumer recycled (PCR) content can compromise optical clarity and mechanical strength, a barrier for premium applications.
- BOPA Substitution:Biaxially-oriented polyamide (BOPA) films offer superior puncture resistance, presenting a substitution threat in applications like meat packaging.
Strategic Opportunities
- Photovoltaic Backsheets:Specialized, weather-resistant BOPET films are a critical component in solar panel backsheets, a key non-packaging growth vector.
- Chemical Recycling:Scaling chemical recycling converts mixed plastic waste into virgin-quality rPET feedstock for food-grade films, enabling circularity.
- Bio-based PET:Developing bio-based PET resins from plant sources offers a path to reduce the carbon footprint and reliance on fossil feedstocks.
Industry Challenges
- Capital Intensity:The high cost and long lead times for installing new biaxial orientation lines act as a significant barrier to entry and rapid capacity expansion for most players.
- PCR Supply Chain:Establishing a reliable supply chain for high-quality, food-contact-approved post-consumer recycled (PCR) feedstock is a major operational challenge, hindering recycled content goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global BOPET Packaging Films Market |
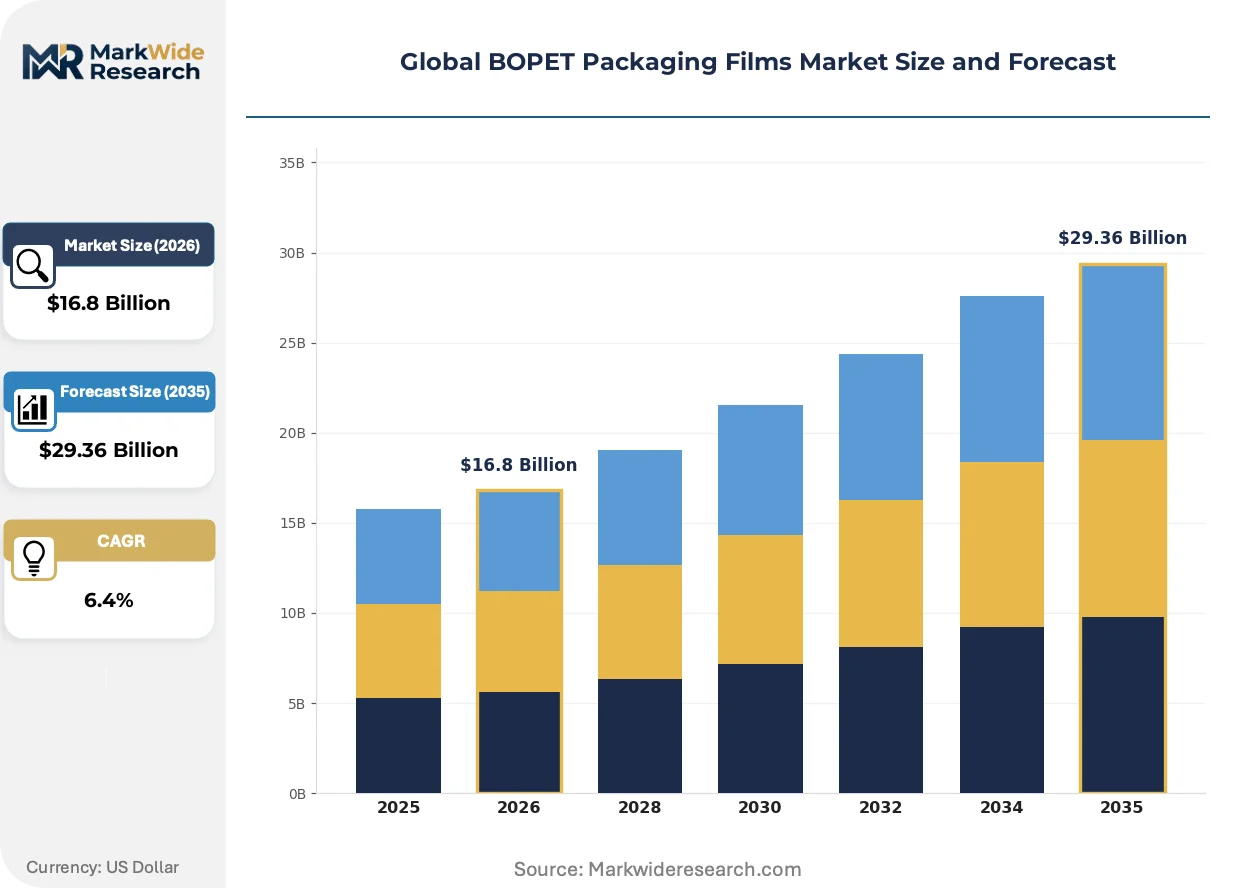
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent BOPET Films, Metallized BOPET Films, Coated BOPET Films, Embossed BOPET Films, Printed BOPET Films Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Industrial Wrapping, Electrical Insulation End User Industry: Consumer Goods Manufacturers, Pharmaceutical Firms, Textile Producers, Electronics Assemblers, Agriculture Suppliers Packaging Type: Rolls, Sheets, Pouches, Bags, Blister Packs |
| Companies Covered | Jindal Poly Films Limited, Mitsubishi Polyester Film, Toray Industries, DuPont Teijin Films, SKC, UFlex Limited, SRF Limited, Terphane, Polyplex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global BOPET Packaging Films Market Strategic Shifts & Innovations
Material science advancements are converging with circular economy principles, forcing a fundamental re-evaluation of BOPET film design. This shift prioritizes end-of-life recyclability and reduced carbon intensity without compromising essential barrier performance.
Chemically recycled PET (rPET) provides a high-purity feedstock for new film production. Food and beverage brand owners are adopting films with rPET content to meet sustainability pledges and prepare for regulatory mandates. The availability of food-contact approved rPET is displacing the industry's sole reliance on virgin petrochemical feedstocks for premium packaging applications.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes mandatory recycled content targets and stringent design-for-recycling criteria. This directive compels producers to accelerate investment in mono-material solutions compatible with established recycling streams. Flexible packaging converters serving the European food market are most affected, redesigning their product portfolios to ensure compliance.
A significant shift in buying behavior sees large consumer goods companies consolidating their supplier base. They are prioritizing film producers that offer globally standardized specifications with verifiable sustainability credentials, such as ISCC PLUS certification. This trend is most visible within the North American and European packaged food and beverage sectors.
Global BOPET Packaging Films Market Segmentation
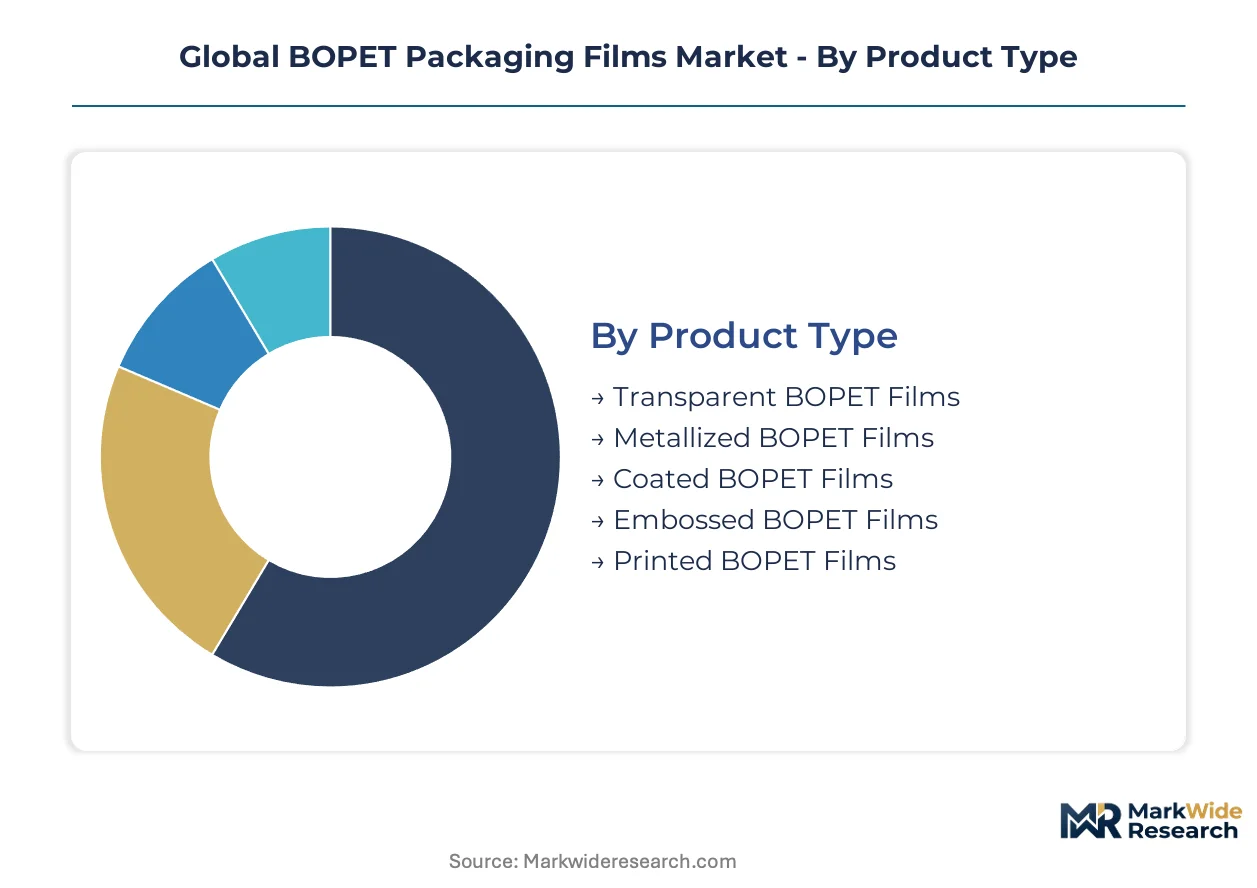
Understanding the varied applications and performance requirements of BOPET films necessitates a detailed segmentation analysis. This breakdown helps differentiate demand patterns across diverse end-use industries, from high-volume food packaging to specialized technical applications. Each segment possesses distinct drivers and regulatory compliance needs, influencing material specifications and market opportunities.
Product Type:
Material composition and end-use dictate varied regulatory scrutiny across BOPET product types, influencing their market adoption.
- Transparent BOPET Films:Biaxially-oriented polyethylene terephthalate film offers exceptional clarity and tensile strength, crucial for visual product appeal and structural integrity. US FDA and European Food Safety Authority (EFSA) regulations strictly govern its use in direct food contact applications.
- Metallized BOPET Films:These films feature a vacuum-deposited metal layer, typically aluminum, providing superior barrier properties to oxygen and moisture. This enhanced protection is critical for sensitive products under China's stringent food preservation standards and for extended shelf life.
- Coated BOPET Films:Applied layers enhance barrier properties or provide heat-sealability, crucial for complex flexible packaging structures and specific product protection.
- Embossed BOPET Films:Surface patterns improve aesthetics or reduce film blocking, often for specialty labels or decorative wraps in consumer goods.
- Printed BOPET Films:Films receive custom graphics and branding, essential for consumer product appeal and market differentiation, especially in competitive retail environments.
Transparent BOPET Films handles the majority of throughput; Metallized BOPET Films is the fastest mover on share.
Application:
Application segments exhibit distinct cost sensitivities driven by performance requirements and volume scales for film procurement.
- Food Packaging:BOPET films provide critical barrier protection against moisture and oxygen for perishable food items, significantly extending product shelf life. This segment demands high volume and cost-efficiency for global consumer markets in Europe and North America.
- Pharmaceutical Packaging:High-barrier BOPET films are essential for protecting moisture-sensitive drugs in blister packs and sachets, ensuring product stability. Strict regulatory compliance, including US FDA and EMA guidelines, governs material selection for advanced APIs.
- Cosmetic Packaging:These films offer aesthetic appeal and product protection for personal care items, ensuring product integrity and brand presentation for consumers.
- Industrial Wrapping:Durable BOPET films provide protective layers for various industrial goods, safeguarding them during transport and storage in manufacturing and logistics.
- Electrical Insulation:Specialized BOPET films offer high dielectric strength and thermal stability, critical for components in electronic devices and photovoltaic backsheets.
Food packaging drives the largest volume, while electrical insulation shows strong value expansion.
End User Industry:
End-user industries are differentiated by the scale of their film procurement and specific technical requirements for BOPET films.
- Consumer Goods Manufacturers:These firms require vast quantities of standardized BOPET films for food, beverage, and household product packaging. They prioritize consistent quality and cost-effectiveness for mass production across global supply chains.
- Pharmaceutical Firms:Specialized BOPET films are procured by pharmaceutical companies for protecting sensitive medications, demanding stringent quality control and high-barrier properties. Compliance with national drug regulators, such as India's CDSCO, is paramount.
- Textile Producers:BOPET films are used for protective wrapping and specialized packaging of textiles, ensuring product integrity during distribution.
- Electronics Assemblers:These users require high-performance BOPET films for electrical insulation and component protection within electronic devices.
- Agriculture Suppliers:Films protect agricultural products and serve in specialized applications like seed packaging or greenhouse films, extending product viability.
Consumer goods manufacturers represent the largest volume segment, with pharmaceutical firms demanding highly specialized film solutions.
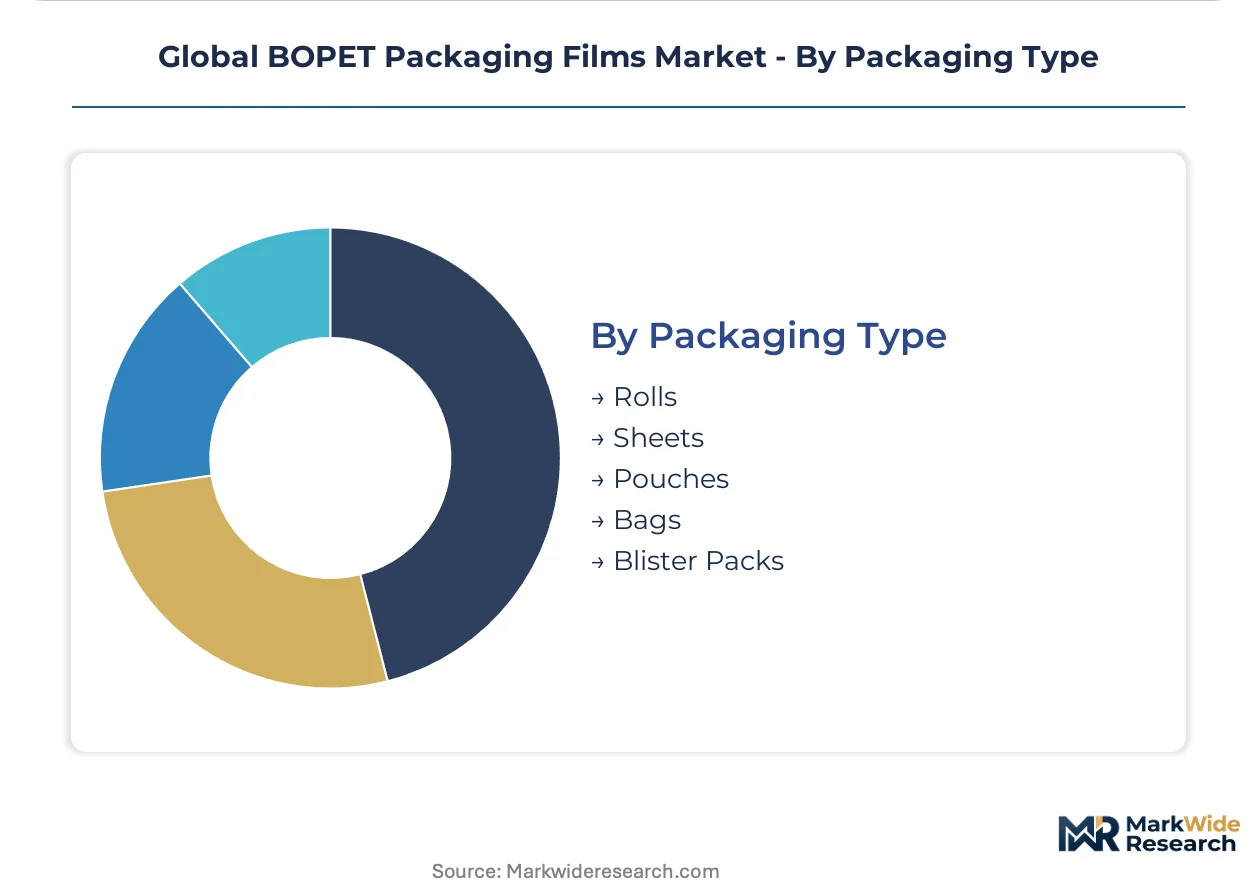
Packaging Type:
Packaging types are defined by their functional form and how they deliver product protection and user convenience in various applications.
- Rolls:Large-format BOPET film rolls serve as primary feedstock for converters, enabling high-speed processing into various flexible packaging formats. This format is crucial for manufacturing hubs in Vietnam and India serving export markets.
- Sheets:BOPET film sheets are used for specific lamination processes or as protective overlays in various industrial applications, offering structural rigidity.
- Pouches:Flexible BOPET pouches offer versatile packaging for food and personal care products, providing convenience and barrier protection for consumers.
- Bags:BOPET films contribute to the strength and barrier properties of bags used for bulk packaging or specialized product containment, enhancing durability.
- Blister Packs:These thermoformed packages use high-barrier BOPET films to protect individual doses of pharmaceuticals, ensuring product stability and tamper evidence. Strict regulatory approval, such as from the US FDA, is required for drug packaging.
Rolls constitute the primary form for film distribution, and blister packs exhibit the most demanding performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Vietnam are key exporters of flexible food packaging to Europe and North America, driving BOPET film demand. This trade corridor shapes film specifications and sustainability requirements for film producers. Local manufacturing hubs concentrate production for these export markets, ensuring consistent supply.
India
Demand for flexible food packaging is high, serving both domestic consumption and export markets. The country's FSSAI regulations govern food contact materials, influencing film composition. Production facilities in Gujarat and Maharashtra expand capacity for high-volume film production, supporting regional and international supply chains.
Vietnam
Export-oriented manufacturing drives significant demand for BOPET films in food packaging. The government's trade policies support foreign investment in packaging production, boosting local capabilities. Ho Chi Minh City and Hanoi host major packaging converters, producing for global brands and regional distribution.
Germany
High-barrier BOPET films are crucial for pharmaceutical packaging and specialized food applications. The EU Green Deal mandates circularity, pushing for mono-material and recycled content solutions. The Rhine-Ruhr region features advanced material science companies developing sustainable film innovations and specialized coatings.
United States
Consumer goods manufacturers require high-volume, standardized BOPET films for food and beverage packaging. US FDA regulations dictate strict safety and migration limits for food contact films, ensuring product integrity. Production clusters in the Midwest and Southeast serve large-scale packaging operations across diverse industries.
China
The country's vast domestic market and export capabilities fuel demand for both transparent and metallized BOPET films. China's dual carbon goals and GB standards promote sustainable packaging solutions and material innovation. Major manufacturing centers in the Yangtze River Delta focus on high-performance film production and distribution.
Global BOPET Packaging Films Market Key Industry Players
Listed leaders compete with private specialists across production scale and technological sophistication. The market exhibits a tiered structure, with a few integrated global players alongside numerous regional and niche manufacturers. Competitive moves include capacity expansion to meet volume demand and strategic R&D investments for specialized film properties. Portfolio diversification into sustainable solutions also shapes competitive positioning.
At the global scale-driven end, companies like Jindal Poly Films Limited and Toray Industries exemplify firms with extensive production capacities. These entities serve diverse end-use industries, from high-volume food packaging to specialized technical applications, leveraging their broad portfolios. DuPont Teijin Films represents a specialist archetype, focusing on advanced, high-performance films for demanding technical sectors such as electrical insulation and pharmaceutical packaging. These specialists often differentiate through proprietary coating technologies and application-specific formulations.
| Leading Market Players |
|---|
| Jindal Poly Films Limited |
| Mitsubishi Polyester Film |
| Toray Industries |
| DuPont Teijin Films |
| SKC |
| UFlex Limited |
| SRF Limited |
| Terphane |
| Polyplex Corporation |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and similar sustainability mandates gate supply qualification, simultaneously influencing price differentiation for compliant BOPET films. This regulatory pressure pushes manufacturers towards advanced, recyclable solutions, impacting both production costs and market pricing. The global nature of the BOPET market means regulatory compliance significantly shapes supply chain configurations and product offerings.
Pricing Analysis
The technology-generation pricing gap differentiates chemically recycled rPET films from virgin or mechanically recycled alternatives. Contract-based long-term offtake agreements dominate for high-volume orders, securing supply for large consumer goods manufacturers. Price differentiation stems from quality grade, specific barrier properties, and food-contact certification, such as US FDA or EFSA approval. Cost compression in transparent BOPET films for commodity applications intensifies due to feedstock volatility. Consumer goods manufacturers seeking standardized films exhibit high price sensitivity, while pharmaceutical firms prioritize performance over marginal cost savings for specialized films.
Supply Chain Analysis
Extended lead times for new biaxial orientation lines influence supply availability, creating capital-intensity barriers for market entry. Geographic supply concentration centers in India, Vietnam, and China, which serve as major production hubs for flexible packaging exports. The supply chain depends on purified terephthalic acid (PTA) and monoethylene glycol (MEG) as primary raw material inputs, making it vulnerable to price fluctuations. Commodity price volatility for these feedstocks presents a structural risk. Distribution primarily runs through large-format BOPET film rolls supplied to packaging converters for further processing into finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces a capability scarcity, particularly in establishing reliable, food-contact-approved post-consumer recycled (PCR) feedstock supply chains. Developing robust chemical recycling infrastructure remains a critical gap for achieving circularity goals. Expertise in advanced coating technologies for high-barrier films also represents a specialized asset gap.
For Market Incumbents: Fortify existing market positions by investing in chemical recycling technologies to secure high-purity rPET feedstock. Expand capacity in key Asian manufacturing hubs like India and Vietnam to leverage cost efficiencies and meet export demand. Diversify product portfolios into specialized, high-performance films for photovoltaic backsheets to mitigate BOPA substitution threats in packaging. Pursue ISCC PLUS certification to meet global sustainability mandates from large brand owners.
For New Entrants and Emerging Players: Differentiate on sustainability credentials, targeting niche applications like bio-based PET films or advanced mono-material structures. The specialized high-barrier pharmaceutical packaging segment presents a penetrable opportunity for firms with proprietary coating technologies. Focus go-to-market strategies on offering verifiable sustainability data and design-for-recycling expertise to European flexible packaging converters. Leverage partnerships with chemical recyclers to ensure a circular supply of raw materials.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across specialized film production due to R&D and equipment costs, signaling a long-term value creation opportunity. Target acquisition archetypes include firms with proprietary coating technologies, advanced chemical recycling capabilities, or established food-contact rPET production. A signal to watch is the increasing availability and quality of food-grade rPET feedstock, indicating scaling circular economy solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Investment | Secures high-purity rPET feedstock, enabling circularity for food-grade films under regulatory pressure. |
| Capacity Expansion in Asia | Meets growing demand for flexible food packaging exports from regions like India and Vietnam. |
| Mono-material Film Development | Aligns product portfolios with EU Green Deal mandates for enhanced end-of-life recyclability. |
| Specialized Coating R&D | Enhances barrier properties for pharmaceutical packaging and expands into non-packaging applications. |
| Bio-based PET Resin Partnership | Reduces reliance on fossil feedstocks, improving the carbon footprint of BOPET film production. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase. This involved interviews with packaging converters, brand owners, film producers, and regulatory experts across key geographies. Secondary validation leveraged US FDA filings, EFSA reports, industry association data, and company financial reports. The approach employed both bottom-up market sizing and top-down validation to ensure comprehensive coverage.
The analytical framework spans the entire projection horizon, modeling market dynamics across key segments. Segmentation dimensions included product type, application, end-user industry, packaging type, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and future projections, integrating factors like raw material prices and evolving regulatory changes. Key forecast inputs included PTA and MEG price trends, alongside global pharmaceutical packaging demand.
The analysis sits within stated boundaries; outcomes outside significant macroeconomic shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding feedstock availability and regulatory enforcement. Key risk factors include sudden shifts in raw material costs or accelerated adoption of substitute packaging materials. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Tube Laminating Films Market
Poly film
China Plastic Packaging Film Market
Poly film
Nylon Films Market
Poly film
PP Laminating Films Market
Poly film
LDPE Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Global BOPP Films Market
Poly film
PVC Cling Film Market
Poly film
Polyolefin Films Market