
 Tube Laminating Films Market | 2026-2036
Tube Laminating Films Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Laminating Films Market Analytics
Asset-light leasing models for extrusion and lamination equipment is fragmenting competitive dynamics in tube laminating films, enabling mid-tier converters to enter without heavy capital deployment. Essel Propack Limited leverages its integrated tube-making and film-lamination capabilities to sustain cost leadership across Asia and Europe. Mondi Group anchors its position through controlled fiber-to-film supply chains that reduce resin price volatility exposure. Huhtamäki Oyj differentiates via specialized high-barrier structures for pharmaceutical tubes that meet stringent migration limits.
Tube laminating films are multi-layer polymer webs, typically combining polyethylene, polyester, or polypropylene substrates with adhesive tie layers, engineered to provide barrier protection, print receptivity, and seal integrity for collapsible packaging tubes. The lamination process bonds these layers through heat and pressure to achieve precise thickness tolerances measured in microns, delivering the mechanical flexibility and chemical resistance required for squeezable formats in cosmetics, pharmaceuticals, and food. Polyethylene formulations currently dominate volume shipments due to established recycling streams and cost efficiency, though polypropylene grades are gaining traction where higher temperature resistance and stiffness prove critical for pharmaceutical applications. BOPP variants occupy premium positioning in personal care segments where optical clarity and dimensional stability command margin premiums over standard polyethylene constructions.
EMA migration limits and FDA 21 CFR compliance frameworks govern extractable and leachable profiles for pharmaceutical tube laminates, directly shaping resin selection and adhesive chemistry across the supply base. REACH substance restrictions and the EU Green Deal packaging waste directives are accelerating converter investment in mono-material and chemically recyclable barrier structures. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling certifications that will determine market access and cost structures ahead of regulatory deadlines.
Market Dynamics
Pharmaceutical tube formats are displacing rigid glass and metal containers for semi-solid drug delivery, forcing converters to reconfigure lamination lines for EMA-compliant barrier structures and squeezable mechanical performance.
Growth Catalysts
- EU Green Deal packaging mandates:REACH substance restrictions and extended producer responsibility schemes in Germany and France accelerate investment in mono-material polyethylene laminates with chemically recyclable barrier coatings.
- Collapsible tube adoption in topical pharmaceuticals:Cream and ointment manufacturers across India and Brazil are abandoning jars for laminated tubes to improve dosing precision and patient compliance.
- Cosmetic brand sustainability pledges:Personal care multinationals headquartered in Hamburg and Frankfurt specify post-consumer recycled content thresholds that drive converter procurement of certified circular polyethylene streams.
Market Restraints
- Ethylene-vinyl alcohol resin price volatility:High-barrier laminates depend on EVOH interlayers whose pricing tracks naphtha and natural gas spreads, compressing converter margins during feedstock spikes.
- Specialized adhesive supply concentration:Solvent-free polyurethane laminating adhesives meeting pharmaceutical migration limits source from a narrow German and Swiss supplier base, creating single-source vulnerability.
- Multi-layer recycling incompatibility:Conventional aluminum-plastic tube laminates face sorting and reprocessing dead-ends under current mechanical recycling infrastructure, exposing producers to EU landfill diversion penalties.
Strategic Opportunities
- Underpenetrated Indian pharmaceutical packaging:CDSCO regulatory harmonization with ICH guidelines enables multinational drug makers to specify European-standard tube laminates for domestic topical production.
- Digital printing integration:UV inkjet systems converge with inline lamination to enable short-run cosmetic tube campaigns with variable graphics, collapsing minimum order quantities for niche personal care brands.
- Japan's pharmaceutical serialization mandates:PMDA track-and-trace regulations create demand for laminates with embedded micro-tagging layers and machine-readable surface structures.
Industry Challenges
- Migration testing capacity bottlenecks:ISO 10993 and USP Class VI certification queues at accredited laboratories extend pharmaceutical laminate qualification timelines by six to twelve months.
- Legacy extrusion asset retrofit costs:Converters face seven-figure capital outlays to convert solvent-based lamination lines to water-based or solventless systems compliant with ECHA workplace exposure limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Laminating Films Market |
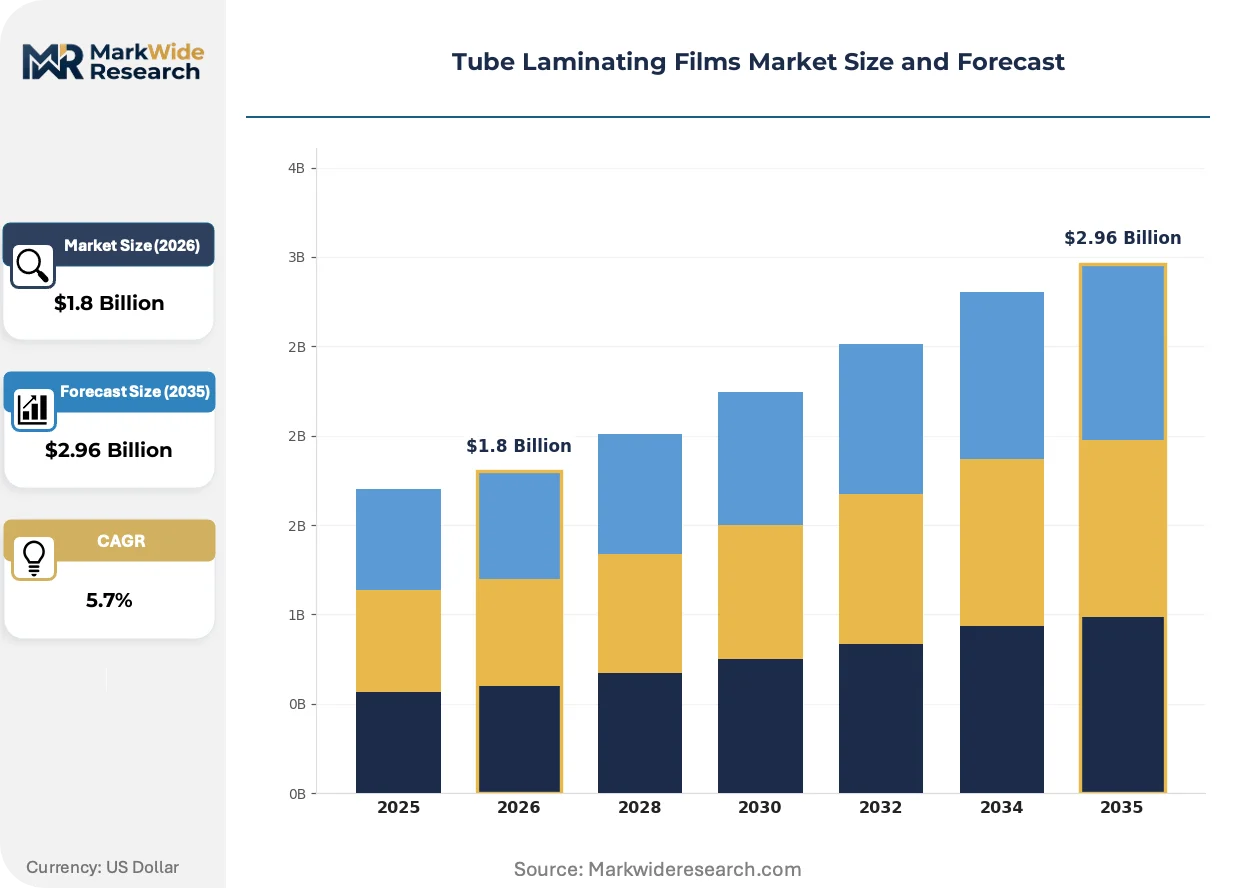
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyester, Polypropylene, BOPP End Use Industry: Food Packaging, Pharmaceuticals, Personal Care, Electronics Thickness: Thin, Medium, Thick, Extra Thick Technology: Extrusion, Coating, Lamination, Printing |
| Companies Covered | Albea S.A., Perfektup Ambalaj Sanayi Ve Ticaret AS, Berry Global Group Inc., Essel Propack Limited, Mondi Group, CCL Industries Inc., Tubopress Italia S.R.L, Cosmo Films Ltd, Huhtamäki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Laminating Films Market Evolving Landscape
Water-based barrier coatings and digital print integration are compressing conventional multi-step lamination workflows, while regulatory pressure on extractables forces adhesive chemistry reinvention across pharmaceutical supply chains.
Polyethylene furanoate barrier layers are rendering obsolete conventional polyester substrates in cosmetic tube laminates. Premium personal care brands in France and Germany specify PEF for its renewable feedstock credentials and superior oxygen barrier performance. The material's adoption is rendering obsolete established PET supply contracts and forcing resin distributors to build biopolymer sourcing capabilities.
EMA's revised guideline on plastic immediate packaging materials tightens extractable and leachable thresholds for pharmaceutical laminates. The regulation forces adhesive suppliers to eliminate specific isocyanate curing agents and accelerant packages from tube laminate constructions. German converters are responding by qualifying alternative two-component polyurethane systems with extended curing windows and reduced volatile profiles.
Brand procurement teams now mandate recycled content certificates traceable to specific mechanical recycling facilities rather than mass-balance claims. Cosmetic tube buyers in Hamburg and Frankfurt audit converter pellet inventories and lamination scrap segregation practices. The verification burden falls heaviest on mid-tier converters lacking integrated recycling partnerships or captive film extrusion capacity.
Tube Laminating Films Market Segmentation
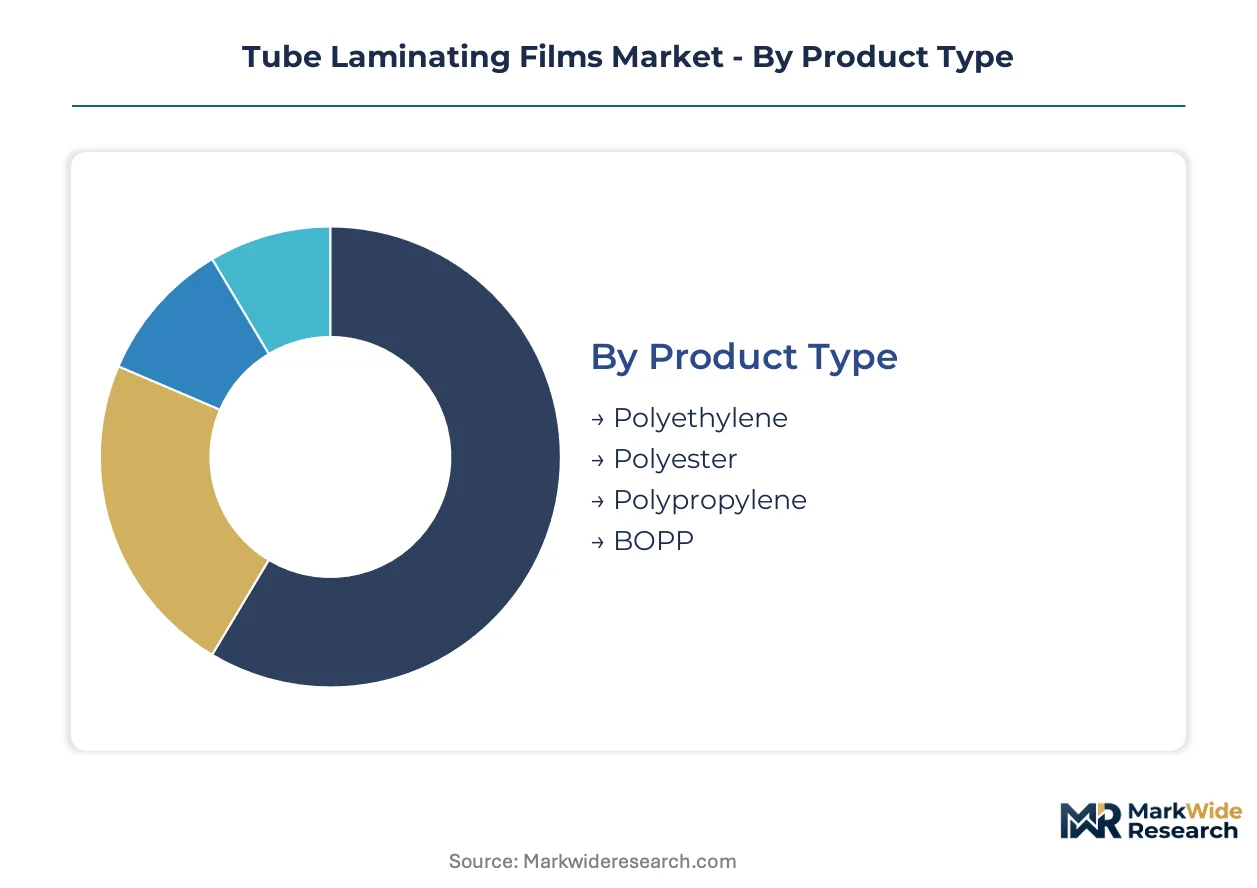
Tube laminating films serve distinct performance requirements across squeezable packaging formats. Material selection, thickness engineering, and conversion technology each create divergent margin profiles and qualification barriers that reshape procurement patterns.
Product Type:
Converters select substrates based on barrier demands, recycling credentials, and end-use temperature exposure.
- Polyethylene:Low-density and linear low-density formulations dominate pharmaceutical and food tube applications due to established mechanical recycling streams and FDA 21 CFR compliance pathways. German cosmetic brands in Hamburg specify certified circular polyethylene streams to meet EU Green Deal procurement mandates.
- Polyester:PET substrates deliver dimensional stability and optical clarity for premium personal care tubes where shelf presence commands margin premiums. Demand concentrates in French and German markets where brand sustainability pledges now favor chemically recyclable alternatives over conventional polyester.
- Polypropylene:Homopolymer and copolymer grades provide higher temperature resistance for pharmaceutical ointments requiring sterilization compatibility.
- BOPP:Biaxially oriented variants occupy premium positioning with superior stiffness and print receptivity for high-end cosmetic applications.
The dominant share belongs to polyethylene, while polypropylene is closing the gap fastest as pharmaceutical temperature requirements tighten.
End Use Industry:
Each vertical imposes distinct regulatory and performance specifications that filter eligible suppliers.
- Pharmaceuticals:EMA migration limits and USP Class VI extractables testing govern resin and adhesive selection. Indian CDSCO harmonization with ICH guidelines enables multinational drug makers to specify European-standard laminates for domestic topical production.
- Personal Care:Post-consumer recycled content thresholds and optical clarity demands drive specification divergence between mass-market and prestige segments.
- Food Packaging:FSSAI and FDA compliance for direct food contact restricts adhesive chemistry options in collapsible food tube formats.
- Electronics:Anti-static and moisture-barrier specifications apply to specialized tube formats for solder pastes and thermal compounds.
Pharmaceuticals command the highest qualification barriers, with personal care expanding most quickly as sustainability procurement mandates proliferate.
Thickness:
Calender control and layer engineering determine mechanical performance and material economics.
- Thin:Sub-100 micron constructions minimize material cost for high-volume cosmetic tubes where barrier demands are modest.
- Medium:100-200 micron specifications balance squeezability with structural integrity for standard pharmaceutical and personal care applications.
- Thick:200-300 micron laminates accommodate aggressive product chemistries and extended shelf-life requirements in topical drug delivery.
- Extra Thick:Above-300 micron specialty constructions serve industrial and electronics applications requiring puncture resistance.
Medium thickness holds the volume center, though thin specifications are gaining share fastest as lightweighting targets intensify.
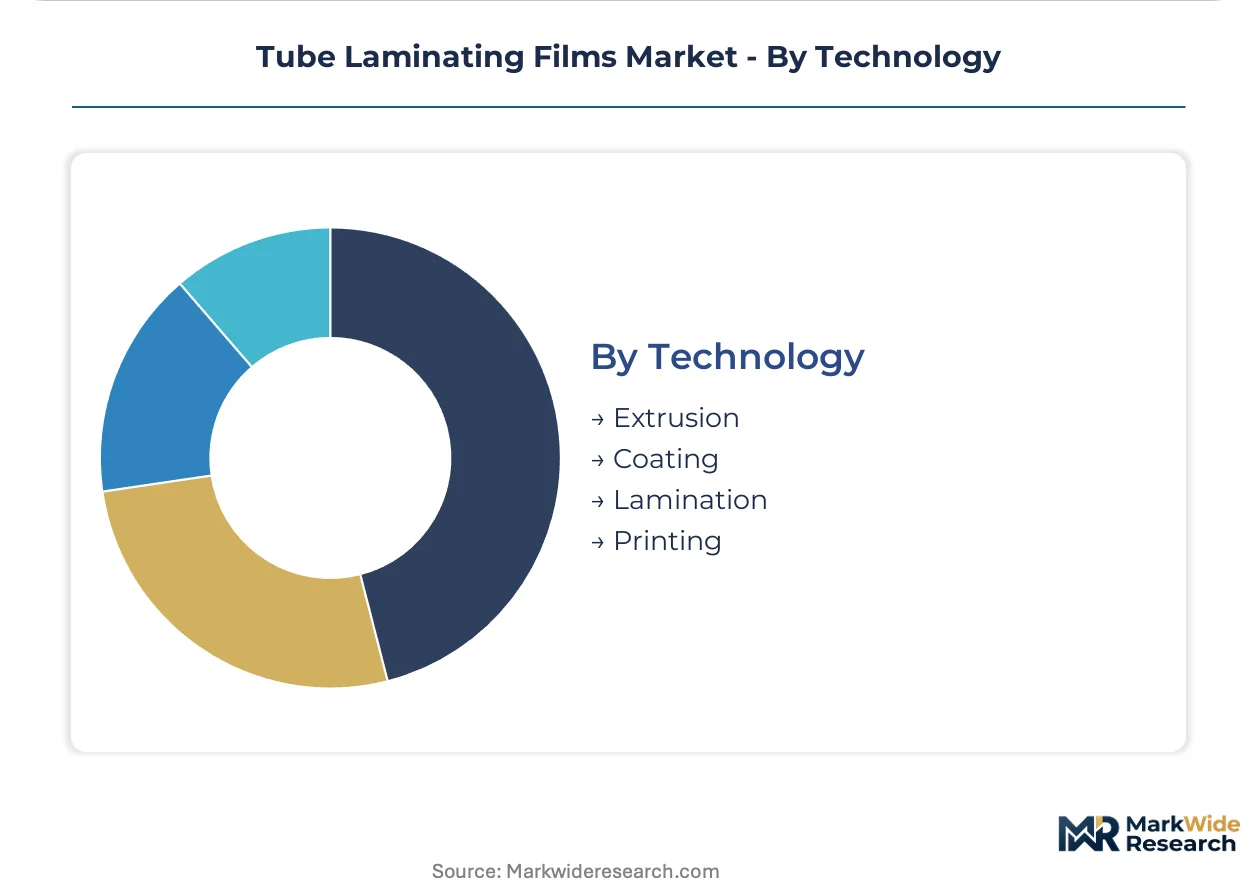
Technology:
Conversion method shapes capital intensity, regulatory compliance, and production flexibility.
- Extrusion:Cast and blown film extrusion of base substrates remains the volume foundation, with asset-light leasing models fragmenting competitive dynamics.
- Coating:Water-based and solventless barrier coating systems are displacing conventional multi-layer structures as REACH workplace exposure limits tighten.
- Lamination:Solvent-free polyurethane adhesive bonding achieves precise layer registration for pharmaceutical migration compliance.
- Printing:UV inkjet integration with inline lamination enables short-run cosmetic campaigns with variable graphics.
Extrusion retains the installed base majority, while coating is climbing the fastest as mono-material recyclable structures displace conventional laminates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and cosmetic brand procurement teams concentrate purchasing power in Germany, India, and the United States, with secondary clusters emerging in Brazil and Japan as regulatory harmonization accelerates tube format adoption.
Germany
Tube laminate converters around Hamburg and Frankfurt supply cosmetic and pharmaceutical brands with REACH-compliant multi-layer structures. ECHA workplace exposure limits and EU Green Deal packaging mandates push producers toward solventless lamination systems. The Rhine-Main cluster houses specialized adhesive suppliers serving EMA-compliant pharmaceutical tube specifications.
India
CDSCO regulatory harmonization with ICH guidelines enables multinational drug makers to specify European-standard tube laminates for domestic topical production. Mumbai and Ahmedabad host contract manufacturers converting jar-based ointment lines to collapsible tube formats. FSSAI compliance requirements for food-contact adhesives filter eligible converter suppliers.
United States
FDA 21 CFR extractables testing governs resin selection for pharmaceutical tube laminates serving topical drug delivery. New Jersey and Pennsylvania pharmaceutical packaging corridors source barrier films meeting USP Class VI certification. EPA emissions regulations accelerate water-based coating adoption over solvent-based lamination systems.
Brazil
ANVISA pharmaceutical packaging regulations align with ICH stability guidelines, enabling laminated tube adoption for semi-solid drug delivery. São Paulo state cosmetic manufacturers specify post-consumer recycled content for personal care tube procurement. Local converters face import dependency for high-barrier EVOH interlayers.
Japan
PMDA track-and-trace mandates create demand for tube laminates with embedded authentication layers and machine-readable surface structures. Osaka and Tokyo pharmaceutical packaging clusters source specialized barrier films for serialized topical products. METI circular economy directives push converters toward mono-material recyclable constructions.
Tube Laminating Films Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated tube manufacturers with captive film lamination capacity anchor the top tier, capturing pharmaceutical and premium cosmetic volumes through qualification barriers. Mid-tier converters lease extrusion assets to serve regional cosmetic brands without capital deployment. Fragmented local suppliers occupy the base tier with commodity polyethylene laminates for mass-market personal care. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with pharmaceutical contract manufacturers.
Among Asia-based integrated specialists, Essel Propack Limited exemplifies the tube-to-film model that compresses converter margins through captive supply chains. European fiber-to-film players like Mondi Group anchor positions through controlled raw material sourcing that dampens resin price volatility. Finnish barrier specialists including Huhtamäki Oyj occupy premium positioning via pharmaceutical-grade qualification portfolios. These three archetypes represent the structural fault lines shaping procurement leverage and margin compression dynamics across the forecast window.
| Leading Market Players |
|---|
| Albea S.A. |
| Perfektup Ambalaj Sanayi Ve Ticaret AS |
| Berry Global Group Inc. |
| Essel Propack Limited |
| Mondi Group |
| CCL Industries Inc. |
| Tubopress Italia S.R.L |
| Cosmo Films Ltd |
| Huhtamäki Oyj |
| Others |
Value Network & Pricing Analysis
German adhesive suppliers serving EMA-compliant pharmaceutical specifications anchor upstream margin capture, forcing downstream converters to absorb qualification premiums or surrender pricing power to integrated tube manufacturers with captive lamination capacity.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and cosmetic-grade tube laminates. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance, with USP Class VI certified constructions commanding substantial premiums over uncertified alternatives. Price differentiation hinges on migration testing documentation and adhesive chemistry transparency. Cost compression in standard cosmetic grades is intensifying as leasing models for extrusion equipment fragment converter margins. Mass-market personal care brands exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize qualification reliability over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and Switzerland dominates supply chain risk planning for solvent-free polyurethane adhesive sourcing. Raw material concentration centers on Saudi Arabia and South Korea for polyethylene resin feedstocks, with EVOH interlayers drawing from Japanese and Belgian specialty polymer producers. Single-source vulnerability pervades the laminating adhesive tier, where German and Swiss suppliers control pharmaceutical-grade formulations. Distribution runs through converter-direct relationships with cosmetic brand procurement teams in Hamburg and Frankfurt, supplemented by pharmaceutical contract manufacturer networks in New Jersey and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across mid-tier converter capacity creates entry niches as sustainability procurement mandates splinter demand into certified circular polyethylene streams and conventional virgin grades.
For Market Incumbents: Insulate pharmaceutical qualification portfolios by deepening captive adhesive compounding capabilities or exclusive partnerships with Swiss laminating chemistry specialists. Essel Propack's integrated tube-to-film model demonstrates how backward integration into resin compounding compresses rival converter margins. Capacity addition in India addresses CDSCO harmonization demand before regional competitors consolidate contract manufacturer relationships.
For New Entrants and Emerging Players: Brazil's laminated pharmaceutical tube segment remains underpenetrated relative to European and North American adoption curves, presenting white-space opportunity as ANVISA alignment with ICH stability guidelines accelerates format conversion from rigid containers. Digital printing integration for short-run cosmetic campaigns offers second entry vector with collapsed minimum order quantities. Asset-light extrusion leasing enables regional presence without seven-figure capital deployment.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier converters with established pharmaceutical qualification pipelines and underutilized lamination line capacity. Long-term viability across the analysis window favors assets positioned for mono-material recyclable structure transitions mandated by EU Green Deal packaging directives. The signal to watch is extended producer responsibility scheme implementation timelines, which will determine cost pass-through mechanics and stranded asset risk for multi-layer aluminum-plastic laminate producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Compounding | Captive supply of EMA-compliant laminating chemistry reduces single-source vulnerability for German converters. |
| Mono-Material Recyclable Structure Transition | REACH workplace exposure limits and EU landfill diversion penalties accelerate water-based barrier coating adoption. |
| Digital Printing Line Integration | UV inkjet convergence with inline lamination collapses minimum order quantities for niche cosmetic brands. |
| Pharmaceutical Qualification Portfolio Expansion | USP Class VI certification queues at accredited laboratories create six-to-twelve-month competitive moats. |
| Regional Capacity Expansion in India | CDSCO harmonization with ICH guidelines enables European-standard laminate specification for domestic topical production. |
Research Methodology
A spread of perspectives from converter operations directors, cosmetic brand procurement managers, pharmaceutical packaging engineers, and laminating adhesive R&D leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EMA regulatory filings, FDA 21 CFR guidance documents, customs trade data for polyethylene resin imports, and SEC disclosures from integrated packaging manufacturers. Bottom-up segment sizing triangulated against top-down macro demand indicators for collapsible tube format adoption across pharmaceutical and personal care verticals.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included substrate chemistry, end-use regulatory tier, thickness specification, and conversion technology. CAGRs derived from regression analysis of historical pharmaceutical tube format penetration rates correlated with regulatory harmonization milestones. Industry-specific forecast inputs incorporated EVOH resin price volatility indices and accredited laboratory migration testing capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in naphtha-natural gas spreads or EU extended producer responsibility implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding CDSCO regulatory harmonization pace and REACH substance restriction enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
China BOPP Film Market
Poly film
Soft Touch Lamination Film Market
Poly film
High Density Polyethylene Film Market
Poly film
Silicone Release Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
PE Foam Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Forming Films Market
Poly film
Stretch Films Packs Market
Poly film
Recyclable Lidding Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Global Specialty Films Polymer Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Nylon Films Market