
 Global Polyethylene Packaging Market | 2026-2036
Global Polyethylene Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyethylene Packaging Market Foresight
Flexible-format consolidation is consolidating buyer preference around multi-layer polyethylene films that replace rigid alternatives in food and personal care distribution. Berry Global leverages vertical integration across resin compounding and film extrusion to capture margin pools in barrier laminates. Amcor PLC anchors its position through R&D intensity in recyclable mono-material polyethylene structures that align with retailer sustainability mandates. Sealed Air Corporation differentiates via automated packaging systems paired with engineered polyethylene films for e-commerce damage reduction.
Polyethylene packaging denotes thermoplastic enclosures fabricated from polymerized ethylene monomers, typically processed through blown film extrusion, cast film methods, or injection and blow molding at densities spanning 0.910 to 0.965 g/cm³ to achieve tensile strength, moisture barrier, and seal integrity specifications required for perishable and industrial goods protection. Low-Density Polyethylene films dominate fresh produce and bakery wrapping where clarity and puncture resistance command premium positioning, while Linear Low-Density Polyethylene grades are displacing conventional LDPE in stretch wrap and heavy-duty sack applications due to superior toughness-to-thickness ratios that reduce material intensity per load unit.
The FDA governs polyethylene contact substances under 21 CFR 177.1520 with specific migration limits for olefin polymers in food applications, while the EU REACH regulation and F-Gas framework constrain fluorinated barrier additives and certain processing aids in polyethylene film production. China's SAMR enforces GB standards for food-contact plastics that restrict additive chemistries and mandate migration testing protocols for imported polyethylene packaging materials. Stakeholders must monitor evolving extended producer responsibility schemes and chemical disclosure requirements that will reshape resin sourcing and converter qualification criteria across multiple jurisdictions.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing resin converters to requalify supply chains around mechanically recycled and bio-based polyethylene grades, compressing legacy virgin resin offtake while opening certified circular material premiums.
Growth Catalysts
- E-commerce fulfillment networks:Automated sortation hubs in Germany, the United States, and India are standardizing flexible polyethylene mailers for dimensional weight reduction. Protective films now replace corrugated void fill in electronics and apparel last-mile delivery.
- REACH F-Gas constraints:Fluorinated barrier additives face phase-down timelines, accelerating mono-material polyethylene laminates that simplify mechanical recycling streams. Retailers in France and the Netherlands now specify these structures in private-label packaging tenders.
- Food processing investments:India's organized retail expansion and cold chain infrastructure buildout are lifting consumption of LLDPE and HDPE formats for dairy, edible oils, and pulses. Domestic converters are scaling blown film capacity to serve this demand.
Market Restraints
- Naphtha-cracker feedstock volatility:Ethylene production costs swing with crude oil and natural gas liquid pricing, compressing margin predictability for integrated polyethylene resin suppliers and downstream film extruders.
- Mechanical recycling yield limits:Post-consumer polyethylene film collection suffers from multi-layer contamination and print adhesion, constraining food-grade recycled content availability below brand owner targets.
- Substitute material competition:Paper-based flexible packaging gains shelf space in European fresh produce and bakery segments where fiber barrier coatings achieve moisture resistance parity at comparable unit economics.
Strategic Opportunities
- Bio-based ethylene feedstocks:Sugar cane and agricultural waste-derived polyethylene production in Brazil offers brand owners Scope 3 emissions reduction pathways that qualify for EU Green Deal-aligned procurement criteria.
- Pharmaceutical compliance films:FDA 21 CFR 177.1520 migration-tested polyethylene structures for unit-dose blister backing and medical device pouches command price premiums in North American and European healthcare supply chains.
- Digital watermarking integration:Invisible marker technologies from Digimarc and AIM are integrating with polyethylene film printing to enable automated sortation at materials recovery facilities, unlocking closed-loop supply contracts with major retailers.
Industry Challenges
- Recycling certification timelines:RecyClass and How2Recycle label approvals require 12-18 month validation cycles for novel polyethylene structures, delaying product launches and locking converters into legacy formulations.
- Multi-layer delamination complexity:Adhesive tie-layers and metallized films in existing barrier laminates complicate mechanical recycling, forcing capital-intensive reprocessing line investments or write-downs of stranded film inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyethylene Packaging Market |
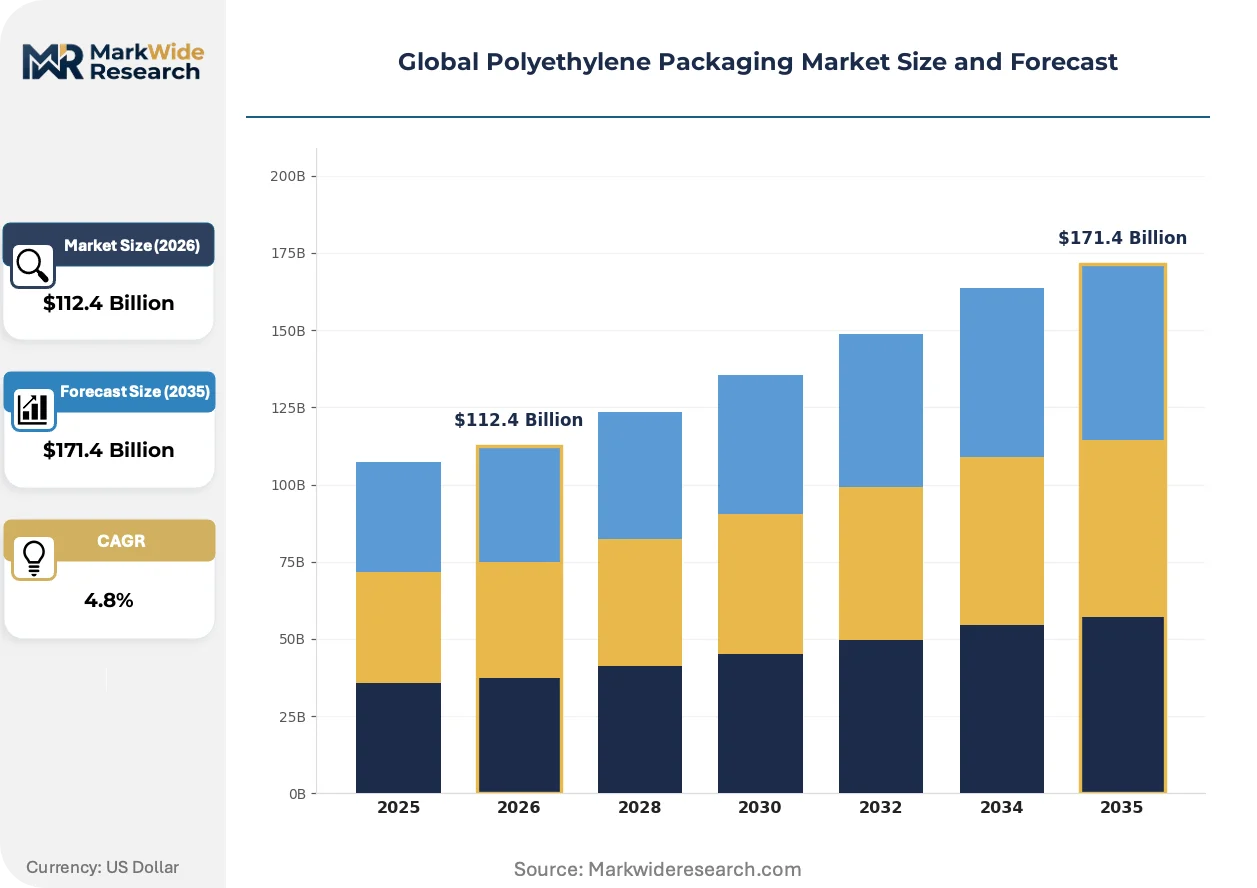
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $171.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Polyethylene, High-Density Polyethylene, Linear Low-Density Polyethylene, Medium-Density Polyethylene Application: Food Packaging, Pharmaceutical Packaging, Consumer Goods Packaging, Industrial Packaging, Agricultural Packaging Packaging Format: Films, Bags, Shrink Wrap, Containers, Bottles End User: Food & Beverage Manufacturers, Drug Producers, Personal Care Brands, Chemical Firms |
| Companies Covered | Berry Global, Amcor PLC, Sealed Air Corporation, Uflex Limited, Packaging Corporation of America, Mondi, Sonoco, Novolex, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyethylene Packaging Market Shifts & Advancements
Active pharmaceutical ingredient packaging, shelf-ready produce formats, and automated fulfillment damage reduction are converging to reshape polyethylene film specifications across food, healthcare, and e-commerce verticals.
Advanced mono-material barrier films are integrating ethylene-vinyl alcohol copolymer and metallocene polyethylene layers to achieve oxygen and moisture transmission rates previously requiring aluminum foil or fluoropolymer coatings. European dairy and meat processors in the Netherlands and Denmark are qualifying these structures for extended shelf-life applications. The technology is integrating closed-loop collection commitments from retailers seeking simplified recycling streams.
China's GB 4806.7-2016 food-contact plastics standards are tightening additive migration limits and mandating substance disclosure for imported polyethylene packaging materials. SAMR enforcement actions against non-compliant shipments from Southeast Asian converters are redirecting sourcing decisions toward certified domestic suppliers. Japanese food exporters are reformulating polyethylene seal layers to meet both Chinese GB thresholds and domestic Positive List System requirements.
Direct-to-consumer brands are compressing packaging specification cycles from annual to quarterly reviews, driven by social media unboxing performance and sustainability scorecard visibility. Third-party logistics providers in the United States and United Kingdom are consolidating film purchasing across multiple brand clients to achieve volume pricing on custom-printed polyethylene mailers. This consolidation is most visible in apparel and cosmetics verticals where influencer marketing amplifies packaging aesthetic scrutiny.
Global Polyethylene Packaging Market Segmentation
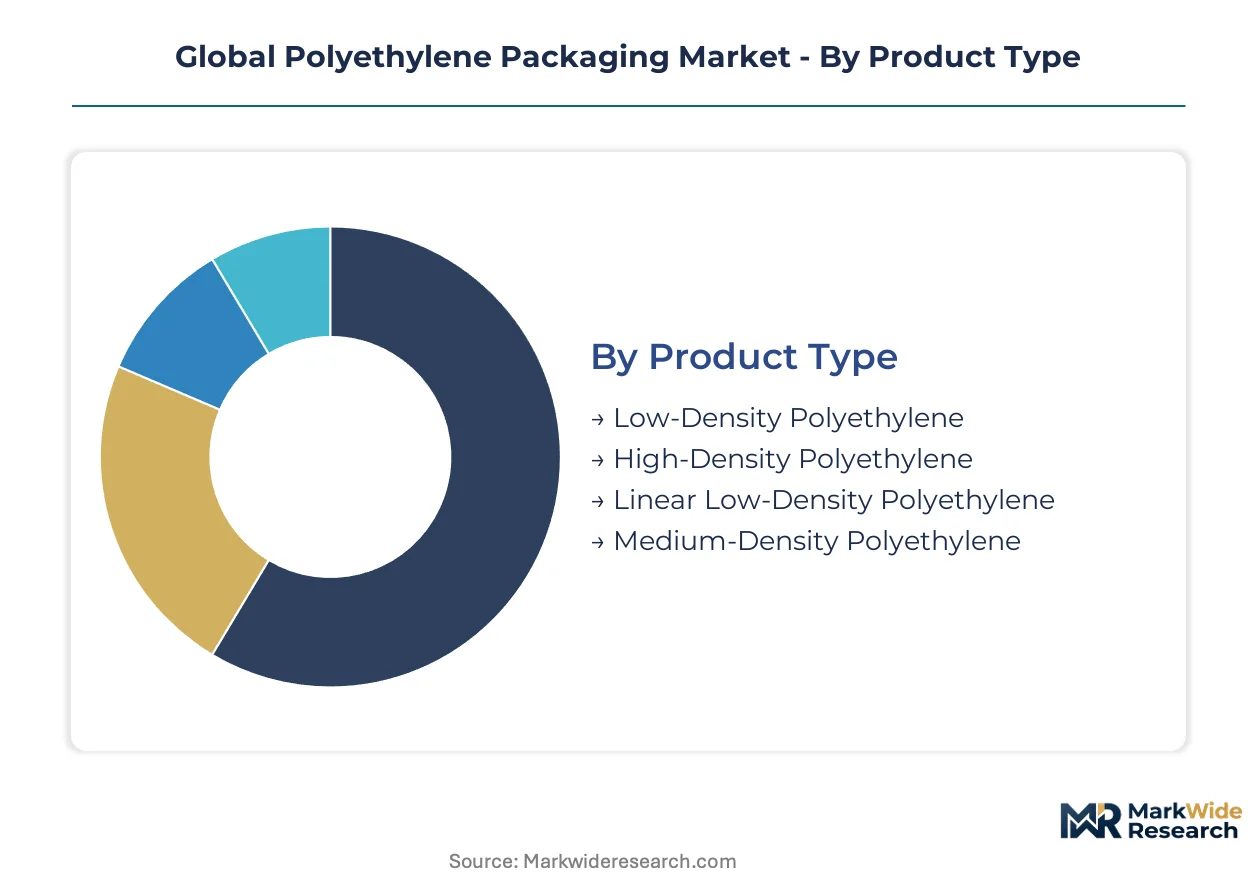
Polyethylene packaging segments diverge sharply in how they integrate into customer operations—some function as standalone purchased items, others embed deeply into automated production lines. Understanding this integration depth reveals where pricing power concentrates and where switching costs lock in volume.
Product Type:
Integration depth varies dramatically across polyethylene chemistries, with some grades serving as drop-in commodities while others require co-engineering with converter equipment.
- Linear Low-Density Polyethylene:Metallocene-catalyzed LLDPE delivers superior puncture resistance and draw-down ratios in stretch film applications. Demand concentrates in automated pallet-wrapping systems at German and US logistics hubs where downgauging reduces resin consumption per load. The material's compatibility with existing blown-film lines accelerates substitution for conventional LDPE in heavy-duty sack markets.
- High-Density Polyethylene:Stiffness and moisture-barrier properties position HDPE in rigid containers and industrial drums. Indian edible-oil processors favor HDPE jerrycans for their stackability in ambient distribution networks. The grade's higher crystallinity enables thinner-wall injection molding that reduces part weight in personal-care bottles.
- Low-Density Polyethylene:Clarity and heat-sealability sustain LDPE demand in fresh-produce overwrap and bakery films where optical properties command specification.
- Medium-Density Polyethylene:Intermediate density offers balanced toughness and rigidity for specialty caps and closures where precise dimensional stability matters.
LLDPE leads volumes today; HDPE is gaining share fastest in organized retail expansion across South Asia.
Application:
Cost-tier stratification separates applications where polyethylene competes on unit economics versus those where compliance premiums justify specialized grades.
- Food Packaging:Multi-layer barrier films integrate ethylene-vinyl alcohol and metallocene polyethylene to achieve oxygen transmission rates below 1 cc/m²/day for modified-atmosphere meat packaging. Dutch and Danish processors specify these structures for extended shelf-life retail formats. FDA 21 CFR 177.1520 migration testing and EU 10/2011 compliance requirements fragment supplier qualification across Atlantic trade lanes.
- Pharmaceutical Packaging:Unit-dose blister backing and medical-device pouches demand low-extractable polyethylene with documented DMF stability data. North American healthcare supply chains pay premiums for resin lots with certified USP Class VI biocompatibility and gamma-sterilization compatibility.
- Consumer Goods Packaging:Brand-owner sustainability scorecards drive specification of mechanically recycled content in personal-care and household product films.
- Industrial Packaging:Heavy-duty shrink wrap and drum liners prioritize tear resistance and load containment over optical clarity in chemical and construction material distribution.
- Agricultural Packaging:UV-stabilized greenhouse films and silage wrap require additive packages that resist photodegradation across seasonal exposure cycles.
Food packaging dominates revenue contribution; pharmaceutical applications expand most quickly on compliance-driven premium pricing.
Packaging Format:
Volume concentration and margin structure diverge across formats based on equipment capital intensity and print customization requirements.
- Films:Cast and blown film extrusion serves as the foundational format, spanning stretch wrap, food overwrap, and lamination substrates. Chinese converters scale multi-meter-wide lines to serve export markets for commodity-grade agricultural films.
- Bags:Flexible mailers and gusseted sacks integrate with e-commerce fulfillment automation where dimensional-weight shipping rules favor lightweight polyethylene over corrugated alternatives.
- Shrink Wrap:Biaxially oriented films provide unitization and tamper-evidence for beverage multipacks and industrial pallet loads.
- Containers:Injection and blow-molded rigid packaging competes with PET and PP in dairy and chemical containment applications.
- Bottles:Extrusion blow-molded HDPE bottles retain share in personal-care and household chemical segments where squeezability and chemical resistance matter.
Films command the largest volume position; bags are climbing fastest on e-commerce fulfillment network expansion.
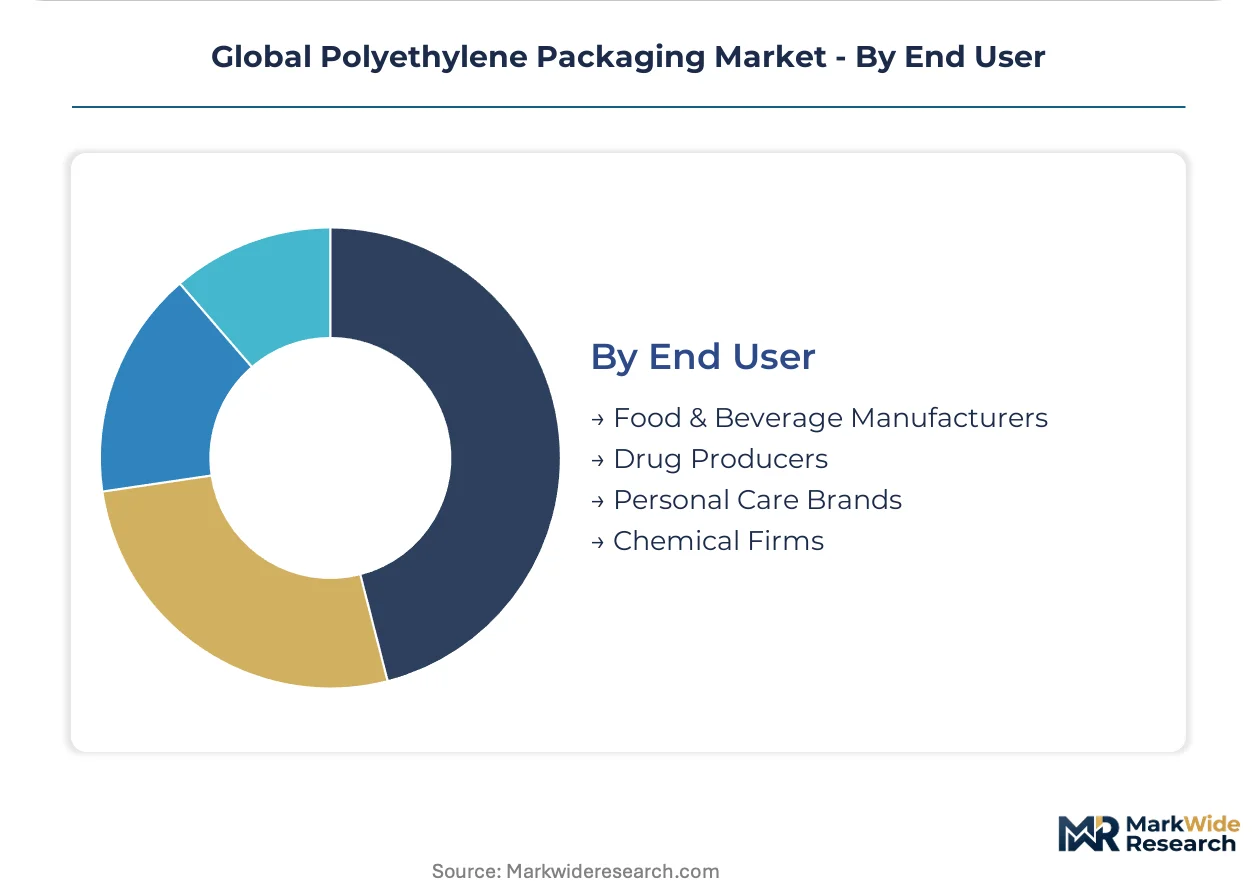
End User:
Customer-type segmentation reveals divergent procurement sophistication, with some buyers consolidating specifications across global manufacturing footprints while others operate localized spot purchasing.
- Food & Beverage Manufacturers:Multinational processors centralize resin qualification to secure volume pricing and simplify regulatory compliance across manufacturing sites in multiple jurisdictions. Extended producer responsibility schemes in France and Italy now mandate recycled content minimums that reshape tender specifications.
- Drug Producers:Pharmaceutical firms impose stringent change-control protocols that lock in approved resin grades for multi-year product lifecycles, creating high switching costs for qualified suppliers.
- Personal Care Brands:Direct-to-consumer brands compress specification cycles to quarterly reviews driven by unboxing aesthetics and influencer marketing visibility.
- Chemical Firms:Industrial buyers prioritize lot-to-lot consistency and UN-certified dangerous-goods compatibility over sustainability attributes in drum and pail applications.
Food and beverage manufacturers anchor current demand; personal care brands are shifting procurement fastest toward certified circular materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene packaging manufacturing originated in post-war Germany and the United States, where petrochemical complexes along the Rhine and Gulf Coast established the first integrated resin-to-film production corridors. These historical clusters continue to anchor capacity expansion and regulatory innovation today.
United States
E-commerce fulfillment networks in Dallas-Fort Worth and Atlanta drive specification of lightweight polyethylene mailers for dimensional-weight shipping optimization. FDA 21 CFR 177.1520 governs food-contact migration limits, while EPA enforcement targets per- and polyfluoroalkyl substance contamination in barrier films. The Houston Ship Channel corridor hosts integrated resin producers supplying blown-film converters serving North American retail private-label programs.
Germany
Automated logistics hubs in Leipzig and Duisburg standardize stretch-wrap films for pallet consolidation in European distribution networks. EU REACH F-Gas Regulation mandates phase-down of fluorinated barrier additives, accelerating converter qualification of mono-material polyethylene laminates. The Ruhr industrial cluster concentrates mechanical recycling infrastructure processing post-consumer films into food-grade certified resins.
China
Organized retail expansion in Shanghai and Shenzhen lifts demand for LLDPE fresh-produce films and HDPE rigid containers. SAMR enforces GB 4806.7-2016 food-contact standards with tightened additive migration thresholds and mandatory substance disclosure for imported materials. The Yangtze River Delta hosts multi-meter-wide cast film lines serving export markets for agricultural greenhouse films.
India
Food processing investments in Maharashtra and Gujarat accelerate consumption of LLDPE and HDPE formats for dairy, edible oils, and pulse packaging. FSSAI mandates food-contact compliance testing for polyethylene materials, while DGFT import restrictions on virgin resin stimulate domestic blown-film capacity expansion. The Mumbai-Pune industrial corridor concentrates converter operations supplying organized retail cold-chain infrastructure.
Brazil
Bio-based polyethylene production from sugar cane feedstocks in São Paulo state offers brand owners Scope 3 emissions reduction pathways qualifying for EU Green Deal procurement criteria. ANVISA regulates pharmaceutical-contact polyethylene with stability data requirements for medical-device packaging applications. The Camacari petrochemical complex anchors integrated resin production serving flexible film converters across Latin America.
Global Polyethylene Packaging Market Competitive Landscape
The competitive structure tilts toward integrated resin-to-film conglomerates with captive raw material supply and regional specialists commanding premium positioning in compliance-driven healthcare segments. Tier-one players leverage backward integration into resin compounding to capture margin pools in barrier laminates, while mid-scale converters compete on custom-printing agility and rapid specification turnaround. Two dominant competitive moves define current positioning: M&A activity consolidating regional film extrusion assets, and strategic partnerships between converters and automated packaging equipment vendors locking in volume commitments.
Within the integrated conglomerate tier, Berry Global and Amcor PLC exemplify archetypes combining resin qualification depth with multi-jurisdictional regulatory compliance infrastructure. Sealed Air Corporation occupies a position bridging engineered film production with automated packaging system integration. Among Asia-Pacific specialists, Uflex Limited represents the regional converter archetype scaling blown-film capacity to serve domestic organized retail expansion. These named entities anchor the competitive map without exhausting the participant base.
| Leading Market Players |
|---|
| Berry Global |
| Amcor PLC |
| Sealed Air Corporation |
| Uflex Limited |
| Packaging Corporation of America |
| Mondi |
| Sonoco |
| Novolex |
| Winpak |
| Others |
Supply & Pricing Matrix
Naphtha-cracker feedstock costs cascade through polyethylene resin pricing tiers, with ethylene spot volatility in the US Gulf and Rotterdam hubs compressing margin buffers for downstream film extruders serving e-commerce and food packaging buyers. Contract-based long-term offtake agreements between integrated resin producers and major converters in Germany and India insulate volume commitments from spot swings, while spot purchasers in Southeast Asia absorb sharper price dislocations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the polyethylene packaging market by certification grade and volume scale. Premium tiers command spreads for FDA 21 CFR 177.1520 migration-tested resins and EU food-contact compliance, while standard grades serve private-label retail programs with less stringent barrier specifications. Price differentiation hinges on recycled content certification and geographic delivery cost, with EU Green Deal-aligned bio-based polyethylene from Brazil carrying sustainability premiums. Cost compression in standard-grade blown film is intensifying because of Chinese export capacity expansion and domestic converter scale-up in India. Small-format personal care brands exhibit highest price sensitivity, while pharmaceutical contract manufacturers accept substantial premiums for documented DMF stability data.
Supply Chain Analysis
RecyClass and How2Recycle label approvals function as qualification gates that delay product launches and lock converters into legacy formulations for 12-18 month validation cycles. Resin supply concentrates in the United States, Germany, and China, with the Houston Ship Channel, Ruhr industrial cluster, and Yangtze River Delta anchoring integrated production corridors. Raw material flows draw from naphtha crackers, natural gas liquids, and emerging sugar cane ethanol feedstocks in Brazil. Single-source vulnerability runs through specialized metallocene catalyst supply for LLDPE grade differentiation. Distribution runs through converter-direct relationships with multinational food and beverage manufacturers, supplemented by regional distributor networks serving mid-scale personal care and chemical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyethylene packaging market reads as a late-cycle quality story, with specification cycles compressing toward certified circular materials and mono-material barrier structures that command compliance premiums. EU Packaging and Packaging Waste Regulation mandates and retailer sustainability scorecards are shifting procurement toward mechanically recycled and bio-based grades.
For Market Incumbents: Anchor market position through backward integration into resin compounding and mechanical recycling infrastructure, particularly in the Ruhr and Houston corridors where food-grade recycled content capacity remains constrained. Defend against paper-based flexible packaging substitution in European fresh produce by accelerating mono-material polyethylene qualification with ethylene-vinyl alcohol barrier layers. Prioritize certification investment in RecyClass and How2Recycle labeling to lock in retailer private-label volumes before validation timelines extend further. For New Entrants and Emerging Players: Launch via regional converter partnerships targeting India's organized retail cold-chain buildout in Maharashtra and Gujarat, where FSSAI compliance testing requirements and DGFT resin import restrictions create qualification barriers for unestablished foreign suppliers. Penetrate the pharmaceutical compliance film segment in North America and Europe, where USP Class VI biocompatibility and gamma-sterilization compatibility documentation commands substantial premiums and incumbent change-control protocols slow competitive response. Pursue white-label manufacturing arrangements with direct-to-consumer personal care brands seeking quarterly specification turnaround for influencer-driven unboxing aesthetics. For Investors and Strategic Acquirers: Consolidation pressure builds where mechanical recycling yield limits constrain food-grade recycled content availability below brand owner targets, stranding mid-scale converters without certified circular supply contracts. Target acquisition profiles center on regional film extrusion assets with established retailer closed-loop collection commitments and validated mono-material laminate qualifications. The signal to watch as inflection indicator is EU member state implementation timelines for extended producer responsibility recycled content minimums, which will reshape tender specifications and accelerate converter consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin pools in barrier laminates and insulates against naphtha-cracker feedstock volatility. |
| Mechanical Recycling Capacity Expansion | Addresses EU Packaging and Packaging Waste Regulation mandates and secures food-grade recycled content certification. |
| Mono-Material Barrier Film Qualification | Aligns with retailer sustainability scorecards and simplifies mechanical recycling streams for closed-loop contracts. |
| Pharmaceutical Compliance Film Development | Commands price premiums in North American and European healthcare supply chains with documented DMF stability data. |
| Digital Watermarking Integration | Enables automated sortation at materials recovery facilities and unlocks retailer closed-loop supply contracts. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation across trade and regulatory databases. Interviews with resin procurement directors at multinational food and beverage manufacturers, technical R&D leads at film extrusion converters, regulatory affairs specialists navigating FDA and EU REACH compliance, and sustainability officers at retail private-label programs informed demand-side assumptions. Secondary sources include customs and trade flow data, SEC 10-K filings from integrated resin producers, RecyClass certification registries, and EU extended producer responsibility implementation documents. Bottom-up volume estimates by product grade, application, and packaging format triangulate against top-down ethylene consumption and polyethylene resin production capacity data.
Rate-of-change decomposition separates volume growth from price and mix effects across the projection horizon. Segmentation dimensions modeled include polyethylene chemistry grade, end-use application, packaging format, and regional production hub regulatory cluster. CAGRs derive from trend extrapolation of historical resin consumption patterns adjusted for identified catalysts and restraints, with cross-validation against ethylene derivative demand forecasts and converter capacity expansion announcements. Industry-specific inputs incorporate e-commerce fulfillment network automation adoption curves, EU Packaging and Packaging Waste Regulation implementation phasing, and bio-based polyethylene production scale-up timelines in Brazil.
Several conditions sit outside the modeled scope, including abrupt crude oil and natural gas liquid price dislocations, unilateral trade restriction impositions on polyethylene resin or film imports, and breakthrough substitution technologies achieving cost parity with polyethylene barrier structures. Forecasts reflect assumptions about regulatory enforcement consistency, certification body validation timeline stability, and brand owner recycled content target adherence. A model refresh is warranted upon material change in EU member state extended producer responsibility implementation schedules or FDA migration limit revisions for olefin polymers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
China BOPP Film Market
Poly film
Polystyrene Films Market
Poly film
Polysaccharide Films Market
Poly film
MDO-PE Films Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
Global Specialty Films Polymer Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Poly Coated Paper Market
Poly film
Automotive Wrap Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Brazil Plastic Packaging Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Timber Wrap Films Market
Poly film
PVC Films Market