
 High Barrier Packaging Films for Pharmaceuticals Market | 2026-2036
High Barrier Packaging Films for Pharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
High Barrier Packaging Films for Pharmaceuticals Market Outlook
The EU Green Deal is consolidating demand for recyclable mono-material barrier structures across European pharmaceutical supply chains. Amcor plc leverages its integrated film-to-package development network to sustain leadership in sustainable barrier platforms. Klöckner Pentaplast Group anchors its position through specialized pharmaceutical-grade PVC and PVDC alternatives. Tekni-Plex Inc. competes on multi-layer coextrusion capabilities tailored to moisture-sensitive dosage forms.
High barrier packaging films for pharmaceuticals are multi-layer polymer or metallized structures engineered to achieve oxygen transmission rates below 0.1 cc/m²/day and water vapor transmission rates under 0.01 g/m²/day, typically manufactured through cast coextrusion, blown film, or vacuum metallization processes to protect drug stability throughout shelf life. Blister films dominate value generation due to their ubiquity in oral solid dose protection, while pouches represent the fastest-expanding format as biologics and injectable solutions migrate from glass to flexible containment. Aluminium foil occupies the premium margin tier for high-sensitivity applications, whereas polyethylene and polypropylene gain share in recyclable mono-material designs.
The FDA enforces strict Container Closure System integrity requirements under 21 CFR Part 211, while EMA's Annex 1 revisions on sterile manufacturing elevate barrier performance standards for aseptic fill-finish operations. REACH compliance in Europe and EPA oversight of perfluorinated substances in the US are reshaping material selection across supplier bases. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and qualification costs.
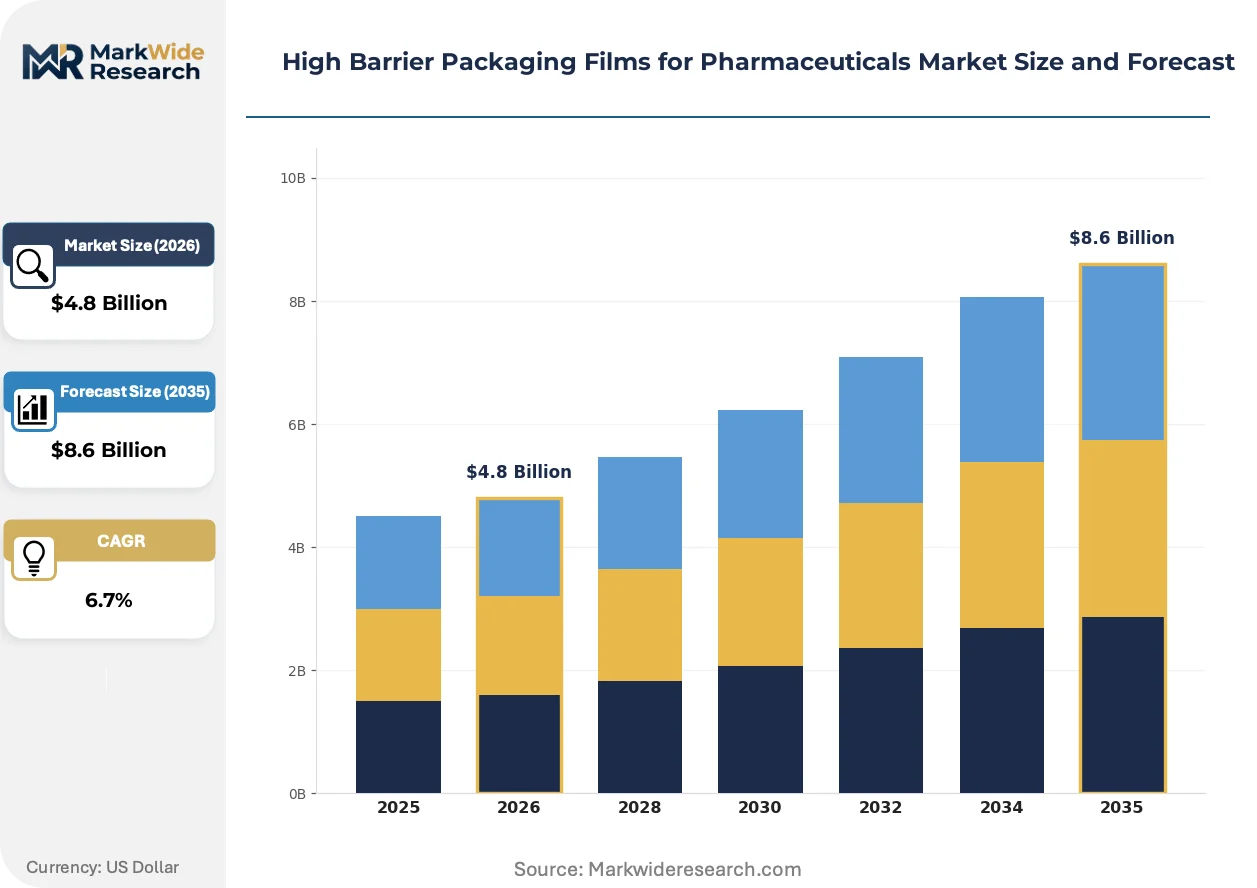
Market Dynamics
The EU F-Gas Regulation is compressing the supply base for fluoropolymer-dependent barrier films, forcing reformulation cycles that favor multi-layer coextrusion and metallized alternatives. Cold-chain biologics expansion is simultaneously pulling investment toward ultra-low temperature performance specifications.
Growth Catalysts
- Cold-chain biologics proliferation:Cell and gene therapies requiring -70°C stability are pulling demand for specialized barrier structures that maintain integrity across cryogenic distribution. German packaging clusters are scaling metallized coextrusion capacity to serve this segment.
- REACH chemical restrictions:ECHA's expanding SVHC candidate list is disqualifying legacy PVC-PVDC laminates from European pharmaceutical packaging, redirecting procurement toward EVOH and cyclic olefin copolymer alternatives.
- Blister-to-pouch format migration:Injectable biologics are abandoning glass vials for flexible containment, with multi-chamber pouches capturing volume in parenteral nutrition and vaccine delivery systems.
Market Restraints
- Aluminium foil supply concentration:European smelter capacity constraints and energy cost volatility in Germany and France are transmitting price instability into metallized film supply chains.
- Fluoropolymer technical lock-in:PVDC remains unmatched for ultra-high moisture barrier in tropical markets, creating compliance-performance trade-offs that slow material transitions.
- Qualification timeline friction:FDA Container Closure System changes under 21 CFR Part 211 require 18-24 month stability studies, freezing supplier switches even when superior alternatives exist.
Strategic Opportunities
- Mono-material recyclable structures:EU Green Deal packaging mandates are creating first-mover advantage for suppliers achieving PP or PE-only barrier films with sub-0.1 cc/m²/day oxygen transmission.
- Home-based injectable delivery:Self-administered biologics are expanding demand for patient-friendly pouch formats with integrated needle safety and tamper-evidence features.
- Digital printing convergence:Serialized unit-dose packaging combining high barrier films with inkjet-printed traceability is capturing share in clinical trial supply chains.
Industry Challenges
- Coextrusion engineering talent scarcity:Nine-layer blown film expertise is concentrated among aging specialist workforces in southern Germany and northern Italy, constraining capacity expansion timelines.
- Legacy equipment reconfiguration:Converting cast film lines to handle cyclic olefin copolymer requires capital outlays exceeding €15 million per facility, freezing mid-tier supplier participation.
- Annex 1 sterile barrier validation:EMA's revised aseptic processing guidelines are extending qualification protocols for films used in fill-finish isolators, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Barrier Packaging Films for Pharmaceuticals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Films, Pouches, Wraps, Bags Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Aluminium Foil Application: Oral Medication, Injectable Solutions, Topical Products, Controlled Release End User: Pharmaceutical Companies, Contract Packaging, Healthcare Providers, Research Institutions |
| Companies Covered | Amcor plc, Klöckner Pentaplast Group, Tekni-Plex Inc., Constantia Flexibles, Wipak Group, Mondi Group, Berry Global Inc., Uflex Ltd., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Barrier Packaging Films for Pharmaceuticals Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are converging to redefine barrier performance benchmarks. Suppliers are racing to decouple high protection from multi-polymer complexity.
Metallized polyethylene terephthalate is overtaking aluminium foil laminates in mid-tier oral solid dose applications. Generic manufacturers in India and Eastern Europe are adopting metallized PET to cut unit costs while meeting USP <671> moisture limits. This displacement is compressing foil demand growth to high-sensitivity biologics segments where zero oxygen ingress remains non-negotiable.
EMA's F-Gas Regulation is eliminating hydrofluorocarbon-based plasma treatment processes used for fluoropolymer adhesion. European converters are retrofitting corona and atmospheric plasma systems that eliminate perfluorinated process chemicals. German pharmaceutical packaging clusters are absorbing the capital burden fastest, while Italian and Spanish suppliers lag 18-24 months on compliance timelines.
Long-term supply agreements are displacing spot purchasing for critical barrier films. Large biopharma manufacturers in Switzerland and the Netherlands are locking three-to-five year contracts with volume guarantees and co-development clauses. This concentration of procurement power is squeezing mid-tier generic drug makers into secondary supplier tiers with inferior technical service access.
High Barrier Packaging Films for Pharmaceuticals Market Segmentation
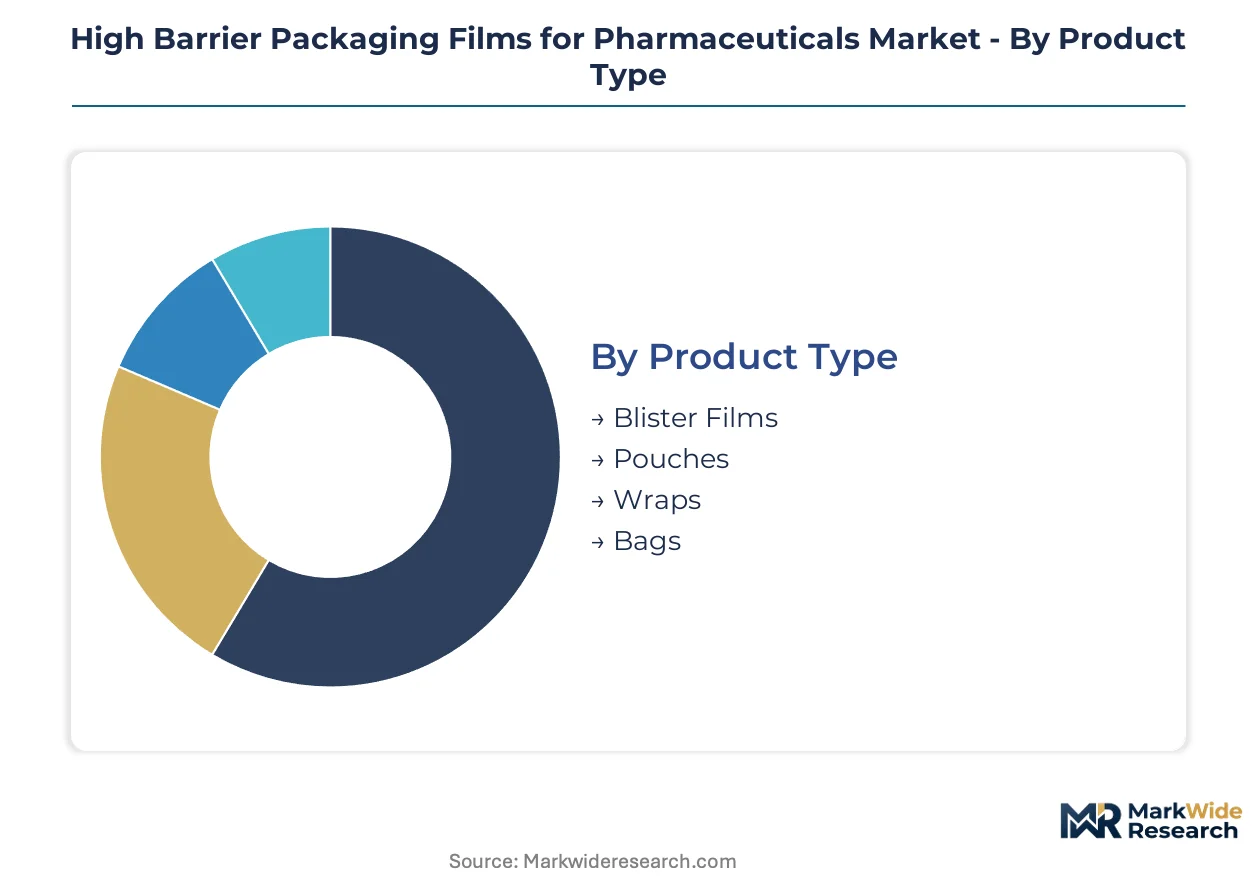
Segmentation in pharmaceutical barrier films tracks how drug delivery formats, material chemistry, and end-user procurement power reshape supplier priorities. Each dimension captures distinct technical specifications and qualification burdens that determine competitive positioning.
Product Type:
Upgrade cycles in pharmaceutical packaging favor formats that reduce unit costs while preserving barrier integrity through distribution.
- Blister Films:Multi-layer coextruded or cold-form laminates engineered for cavity-forming precision and push-through lidding compatibility. German packaging clusters concentrate demand for high-volume oral solid dose production serving European distribution networks, with EMA's Annex 1 revisions elevating validation requirements for aseptic fill-finish integration.
- Pouches:Flexible containment structures transitioning from glass vial alternatives for biologics and parenteral nutrition. Swiss and Dutch biopharma manufacturers are locking long-term supply agreements for multi-chamber designs with integrated needle safety, pulling investment toward patient-friendly formats.
- Wraps:Secondary barrier layers for palletized pharmaceutical shipments requiring moisture and oxygen protection across extended storage. Contract packaging operations in Eastern Europe favor metallized polyethylene wraps for cost-sensitive generic distribution.
- Bags:Bulk containment for active pharmaceutical ingredients and excipients prior to final dosage form manufacturing. Indian generic producers drive procurement of polyethylene-based bags with desiccant integration for tropical climate stability.
Blister films sit at the top of the volume ranking, with pouches climbing the fastest.
Material:
Material selection tracks regulatory chemistry restrictions and recyclability mandates that force substitution away from legacy polymer systems.
- Polyethylene:Linear low-density and high-density grades gaining share in mono-material recyclable designs. EU Green Deal packaging mandates are accelerating reformulation toward PE-only structures with metallized or EVOH coextrusion layers.
- Polypropylene:Cast and oriented films preferred for thermoforming clarity and moisture resistance in tropical markets. REACH SVHC disqualifications of PVC-PVDC laminates are redirecting procurement toward cyclic olefin copolymer-enhanced PP alternatives.
- Polyvinyl Chloride:Rigid and plasticized grades facing phased reduction across European pharmaceutical supply chains. ECHA's expanding candidate list is compressing remaining demand to legacy oral solid dose lines with frozen qualification timelines.
- Aluminium Foil:Cold-rolled and soft-temper foils occupying the premium tier for zero-oxygen-ingress biologics applications. European smelter capacity constraints in Germany and France are transmitting price volatility into metallized laminate supply chains.
Aluminium foil commands the highest margin tier, with polypropylene gaining share fastest.
Application:
Application segmentation follows drug stability requirements that dictate barrier performance specifications and distribution infrastructure.
- Oral Medication:Tablets and capsules requiring moisture protection within USP <671> limits. Metallized PET is displacing foil laminates in mid-tier generics from Indian and Eastern European manufacturers.
- Injectable Solutions:Parenteral biologics and vaccines demanding ultra-low oxygen transmission and cold-chain compatibility. Cell and gene therapies requiring -70°C stability are pulling specialized metallized coextrusion capacity expansion in German clusters.
- Topical Products:Transdermal patches and semisolid formulations needing oxygen and light barrier with flexible conformability. Contract packaging specialists in Italy concentrate volume for European dermatology distribution.
- Controlled Release:Osmotic pump tablets and reservoir systems with precise moisture ingress control. Research institutions and specialized CDMOs in Switzerland drive development-stage procurement for novel delivery platforms.
Oral medication holds the largest volume position, with injectable solutions expanding most quickly.
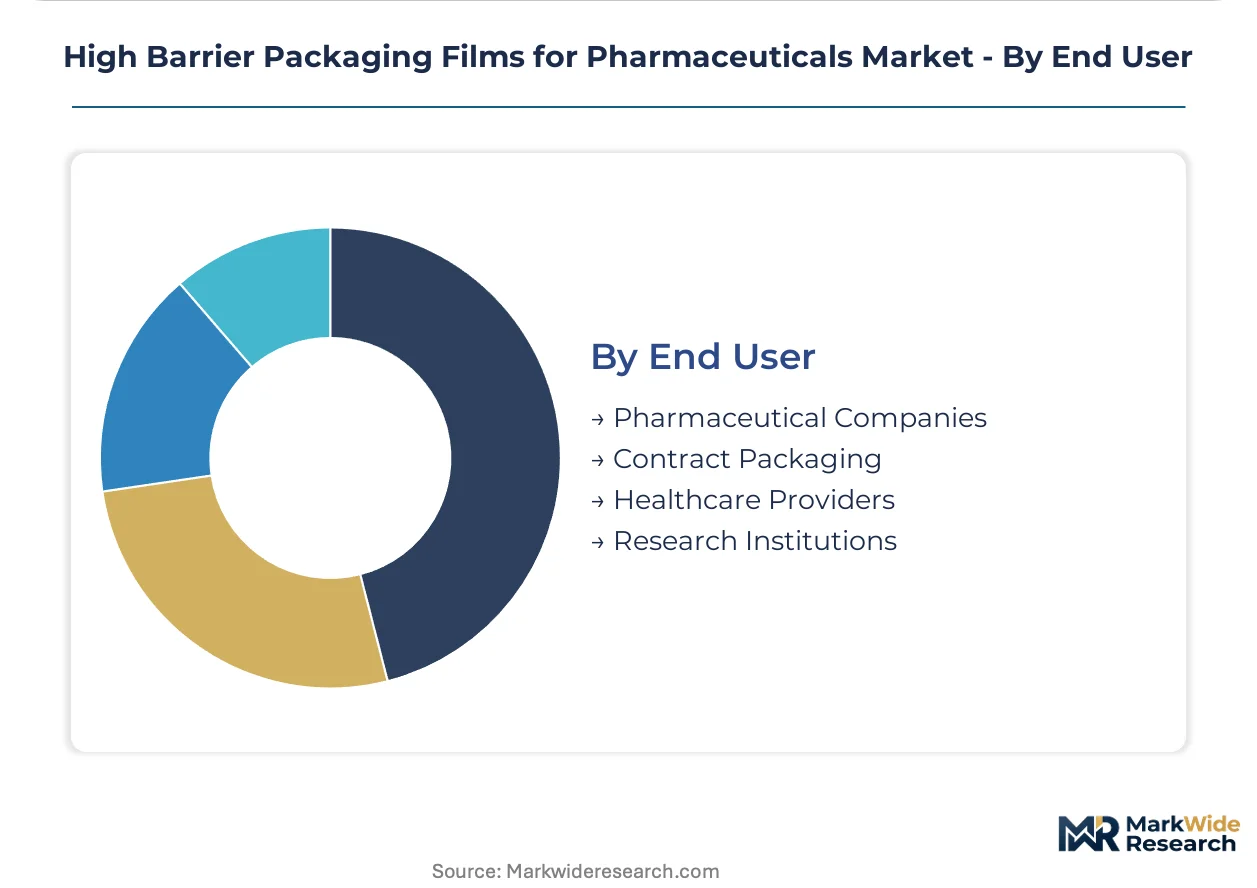
End User:
End-user concentration determines pricing power and technical service intensity across supplier relationships.
- Pharmaceutical Companies:Integrated drug manufacturers with captive packaging operations or direct film procurement. Large biopharma in Switzerland and the Netherlands are consolidating three-to-five year supply agreements with co-development clauses.
- Contract Packaging:Third-party fill-finish and packaging service providers serving multiple drug sponsors. Mid-tier generic makers are being squeezed into secondary supplier tiers with inferior technical access.
- Healthcare Providers:Hospital systems and pharmacy chains with direct sourcing for unit-dose and compliance packaging. Home-based injectable delivery expansion is pulling demand for patient-friendly pouch formats with tamper-evidence.
- Research Institutions:Clinical trial supply chains requiring serialized unit-dose packaging with digital printing convergence. Academic medical centers in Germany and the Netherlands are piloting inkjet-printed traceability on high barrier films.
Pharmaceutical companies dominate procurement volume, with contract packaging climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized coextrusion engineers in southern Germany and northern Italy anchor European barrier film production, with their expertise constraining capacity expansion timelines across the continent.
Germany
Cell and gene therapy manufacturers in Munich and Heidelberg drive demand for cryogenic-stable barrier structures. The F-Gas Regulation is eliminating hydrofluorocarbon plasma treatment processes, forcing converter retrofits. The Stuttgart packaging cluster absorbs capital burdens fastest, scaling metallized coextrusion capacity for -70°C distribution.
Switzerland
Large biopharma manufacturers in Basel consolidate long-term supply agreements with co-development clauses. Swissmedic maintains stringent Container Closure System requirements that exceed EMA baselines. The Basel-Land industrial zone concentrates procurement power, squeezing mid-tier generic makers into secondary supplier tiers.
United States
FDA enforcement of 21 CFR Part 211 freezes supplier switches behind 18-24 month stability studies. The EPA oversees perfluorinated substance restrictions that reshape material selection. New Jersey and Massachusetts pharmaceutical corridors drive serialized unit-dose packaging combining high barrier films with inkjet-printed traceability.
India
Generic manufacturers in Mumbai and Hyderabad adopt metallized PET to cut unit costs while meeting USP <671> moisture limits. The CDSCO aligns with international barrier performance standards for export-oriented production. The Baddi-Barotiwala-Nalagarh belt concentrates polyethylene-based bag procurement with desiccant integration for tropical climate stability.
Netherlands
Contract packaging operations in Amsterdam and Rotterdam favor multi-chamber pouch designs with integrated needle safety. The EU Green Deal packaging mandates accelerate reformulation toward mono-material recyclable structures. The Randstad logistics hub pulls investment toward patient-friendly formats for home-based injectable delivery.
High Barrier Packaging Films for Pharmaceuticals Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered supply positions. Integrated film-to-package developers hold pricing power through captive qualification relationships. The market structures around three archetypes: multinational converters with full-stack capabilities, regional specialists in pharmaceutical-grade substrates, and mid-tier generic suppliers competing on unit cost. Dominant competitive moves include backward integration into resin compounding and strategic partnerships for cold-chain validation.
Among European-based converters, Amcor plc, Klöckner Pentaplast Group, and Tekni-Plex Inc. occupy positions across the capability spectrum. Amcor exemplifies the integrated multinational archetype with film-to-package development networks. Klöckner Pentaplast represents specialized substrate expertise in pharmaceutical-grade alternatives. Tekni-Plex sits within the multi-layer coextrusion tier serving moisture-sensitive dosage forms. These anchors illustrate how supplier positioning tracks regulatory chemistry restrictions and recyclability mandates rather than pure scale economics.
| Leading Market Players |
|---|
| Amcor plc |
| Klöckner Pentaplast Group |
| Tekni-Plex Inc. |
| Constantia Flexibles |
| Wipak Group |
| Mondi Group |
| Berry Global Inc. |
| Uflex Ltd. |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Aluminium ingot price volatility on the London Metal Exchange cascades through European metallized film supply chains, compressing margins for converters serving mid-tier generic drug manufacturers while amplifying pricing power for integrated multinational suppliers with captive resin compounding operations.
Pricing Analysis
Bundled technical service contracts separate premium-tier suppliers from unbundled commodity film vendors. Three-tier pricing structure across premium, standard, and economy levels tracks qualification depth: FDA-validated structures command sustained premiums, while REACH-compliant mono-material alternatives capture Green Deal procurement. Price differentiation hinges on cold-chain validation documentation and volume scale. Cost compression in standard-tier metallized PET is intensifying because Indian generic manufacturers are adopting the format for USP <671> compliance. Contract packaging operations exhibit highest price sensitivity; Swiss biopharma with captive fill-finish show least.
Supply Chain Analysis
EU Green Deal local-content mandates for recyclable packaging are reshaping sourcing patterns toward domestic European resin compounding. Supply concentrates in Germany, Italy, and Switzerland for pharmaceutical-grade coextrusion. The chain draws from aluminium smelters in Germany and France, EVOH resin from Belgium and the Netherlands, and cyclic olefin copolymer from Japan. Single-source vulnerability concentrates in nine-layer blown film expertise anchored in southern Germany and northern Italy. Distribution runs through Stuttgart and Basel-Land packaging clusters serving European fill-finish networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Cell and gene therapy cold-chain requirements are pulling procurement toward premium barrier specifications with cryogenic validation.
For Market Incumbents: Extend qualification relationships into co-development clauses for mono-material recyclable structures. Lock three-to-five year supply agreements with volume guarantees before REACH SVHC expansions disqualify additional legacy chemistries. Backward integration into EVOH resin compounding in Belgium or the Netherlands defends margin position against raw material volatility. Prioritize metallized coextrusion capacity expansion in German clusters serving -70°C distribution. For New Entrants and Emerging Players: Mid-tier generic drug makers in Eastern Europe represent an underserved buyer archetype squeezed into secondary supplier tiers with inferior technical service access. Target contract packaging operations in the Netherlands and Belgium with rapid-turnaround pouch formats for home-based injectable delivery. Penetrate through digital printing convergence offering serialized unit-dose packaging with integrated traceability for clinical trial supply chains. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized multi-layer coextrusion engineers in pharmaceutical-grade substrates. Long-term viability over a five-to-ten year window favors converters with proven EMA Annex 1 validation protocols and established Swissmedic relationships. Acquisition targets should demonstrate captive cold-chain qualification capabilities. Watch for inflection when EU F-Gas Regulation enforcement accelerates fluoropolymer-free barrier adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive EVOH supply from Belgian facilities insulates against REACH-driven material substitution cycles. |
| Metallized Coextrusion Capacity Expansion | Stuttgart cluster scaling for -70°C cell therapy distribution captures Swiss biopharma procurement consolidation. |
| Mono-Material Recyclable Structure Development | PP-only barriers with sub-0.1 cc/m²/day oxygen transmission secure EU Green Deal compliance advantage. |
| Long-Term Supply Agreement Lock-In | Three-to-five year contracts with co-development clauses freeze out mid-tier generic competitors. |
| Digital Printing Convergence Investment | Inkjet-printed traceability integration captures clinical trial serialization demand from German academic centers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged pharmaceutical packaging engineers, regulatory affairs specialists at EMA-notified bodies, procurement directors at Swiss and Dutch biopharma manufacturers, and technical directors at German coextrusion converters. Secondary validation drew from FDA 21 CFR Part 211 guidance documents, EMA Annex 1 revision drafts, ECHA SVHC candidate list updates, and SEC filings from listed packaging converters. Bottom-up demand modeling across dosage formats triangulated against top-down macro pharmaceutical production indices.
Comparable-period anchoring linked projection assumptions to historical qualification timeline data and regulatory implementation trajectories. The analytical framework segmented by product type, material chemistry, application stability requirements, and end-user procurement power. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Forecast inputs incorporated cold-chain biologics proliferation rates and EU F-Gas Regulation compliance cost curves.
Underlying measurement precision varies by segment; blister films and established oral solid dose applications carry tighter precision than emerging pouch formats for cell therapies. Forecasts reflect documented assumptions regarding regulatory timeline adherence and raw material price stability. Unmodelled risks include accelerated REACH restrictions, aluminium smelter capacity disruptions, and qualification timeline extensions under FDA enforcement shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
Release Coatings Market
Packaging Barrier Films
North America Protective Films Market
Packaging Barrier Films
Special Effects Laminate Films Market
Packaging Barrier Films
Japan Food Cling Film Market
Packaging Barrier Films
Cap Liner Films Market
Packaging Barrier Films
Self-Adhesive Films Market
Packaging Barrier Films
Middle East and Africa Airless Packaging Market
Packaging Barrier Films
Aluminum Barrier Laminate (ABL) Tubes Market
Packaging Barrier Films
Barrier Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
Pipe Insulation Film Market
Packaging Barrier Films
Micro-Perforated Food Packaging Market
Packaging Barrier Films
Electron High Barrier Packaging Film Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
Waterproof Packaging Market